
 Global Optical Character Recognition Market | 2026-2036
Global Optical Character Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Character Recognition Market Foresight
Enterprise procurement teams are redrawing vendor evaluation criteria around data sovereignty and model explainability. ABBYY dominates document-centric automation through its captive supply of training data pipelines across European financial institutions. Google leverages its tensor processing infrastructure to sustain price-performance leadership in cloud-based document parsing. Amazon Web Services competes by anchoring OCR modules within broader enterprise workflow suites.
Optical character recognition encompasses algorithms and systems that convert images of typed, handwritten, or printed text into machine-encoded text through feature extraction, neural network classification, and post-processing correction at accuracy thresholds typically exceeding 99 percent for clean documents. Its primary commercial purpose centers on eliminating manual data entry across high-volume document workflows in regulated industries. Cloud-based OCR now captures the bulk of new deployments as organizations prioritize elastic scaling over fixed on-premises infrastructure commitments. Mobile OCR represents the fastest-expanding technology segment, driven by field-service applications in retail inventory and logistics tracking where smartphone cameras replace dedicated scanning hardware.
FDA 21 CFR Part 11 requirements shape healthcare OCR deployments by mandating audit trails and electronic signature validation for digitized patient records. The EU AI Act imposes conformity assessments on automated document processing systems handling sensitive personal data, directly affecting OCR vendors serving European banking and insurance clients. GDPR data minimization principles restrict how long extracted text residues may persist in cloud training corpora. Stakeholders must monitor evolving algorithmic accountability frameworks as regulators tighten scrutiny on automated decision systems processing financial and health records.
Market Dynamics
Enterprise procurement of OCR systems is decomposing around data sovereignty mandates and explainability requirements, forcing vendors to rearchitect recognition engines for auditability rather than raw accuracy alone.
Growth Catalysts
- EU AI Act conformity assessments:Automated document processing systems handling sensitive personal data in European banking and insurance must now embed explainability modules, creating replacement demand for legacy black-box OCR.
- Mobile field-service deployment:Smartphone camera-based text recognition is displacing dedicated scanning hardware in retail inventory and logistics tracking applications across tier-two Indian cities.
- FDA 21 CFR Part 11:Healthcare digitization in Germany and the United States requires audit trails and electronic signature validation for patient records, accelerating procurement of compliant recognition engines.
Market Restraints
- Cloud training data persistence limits:GDPR data minimization principles restrict how long extracted text residues may remain in cloud corpora, constraining vendor ability to improve models through continuous retraining.
- Handwriting recognition accuracy ceilings:Neural network classifiers still struggle with degraded document quality and cursive scripts, limiting addressable volume in historical archive digitization.
- On-premises infrastructure lock-in:Regulated financial institutions in Switzerland and Singapore maintain fixed capital commitments to local processing hardware, slowing elastic cloud migration.
Strategic Opportunities
- Regional lender KYC automation:India's banking sector shows concentrated demand for mobile OCR verification in tier-two cities where branch infrastructure remains thin.
- Convergence with robotic process automation:Document parsing engines are integrating with workflow orchestration platforms to capture full process automation budgets rather than point-solution spending.
- PLI scheme alignment:India's production-linked incentive framework for electronics manufacturing creates localized assembly opportunities for OCR hardware vendors serving government digitization tenders.
Industry Challenges
- Legacy system integration complexity:Mainframe-based patient record systems in German hospitals require custom middleware development for OCR output ingestion, extending deployment timelines.
- Multilingual model training scarcity:Low-resource Indic and Dravidian language corpora limit accuracy for Indian government identity document verification at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Character Recognition Market |
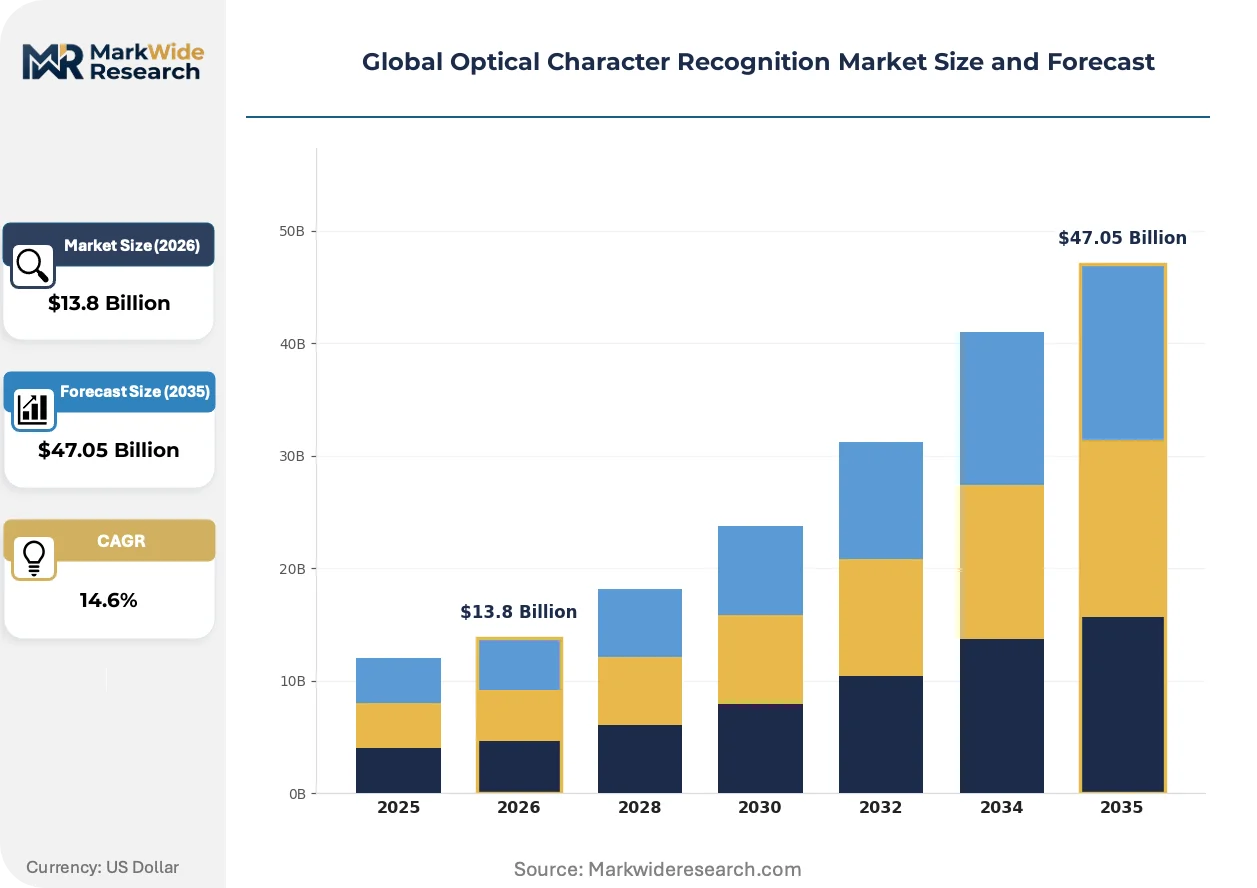
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $47.05 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: OCR Software, Cloud-based OCR, Mobile OCR, Embedded OCR End User: Banking, Education, Healthcare, Retail Deployment: On-premises, Hybrid, Cloud, SaaS Application: Invoice Processing, Document Scanning, Data Entry, License Plate Recognition |
| Companies Covered | Google, Ocrolus, ABBYY, Anyline, Docsumo, Adobe, Rossum, Scandit, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Character Recognition Market Shifts & Advancements
Recognition accuracy thresholds exceeding 99 percent for clean documents have commoditized basic OCR, forcing competitive differentiation toward explainability, edge deployment, and vertical-specific compliance.
Transformer-based architectures are decomposing the traditional pipeline of feature extraction, classification, and post-processing correction into end-to-end neural approaches. Banking and insurance buyers in the European Union are adopting these models fastest where the EU AI Act mandates interpretability. This compression is enabling smaller vendors to challenge incumbents by licensing pre-trained foundation models rather than building proprietary training pipelines.
REACH and RoHS substance restrictions are reshaping hardware component sourcing for document scanners and mobile capture devices. Industrial consequence includes accelerated redesign of optical sensor modules to eliminate restricted materials. Asian contract manufacturers serving European OEMs are responding by shifting supply chains to compliant component suppliers in Taiwan and South Korea.
Buyer evaluation criteria now weight data residency guarantees above per-page pricing in healthcare and financial services procurement. Traditional perpetual-license vendors are being displaced by subscription models with explicit geographic processing boundaries. This shift is most visible in German hospital systems and US health networks where HIPAA business associate agreements require explicit infrastructure location commitments.
Global Optical Character Recognition Market Segmentation
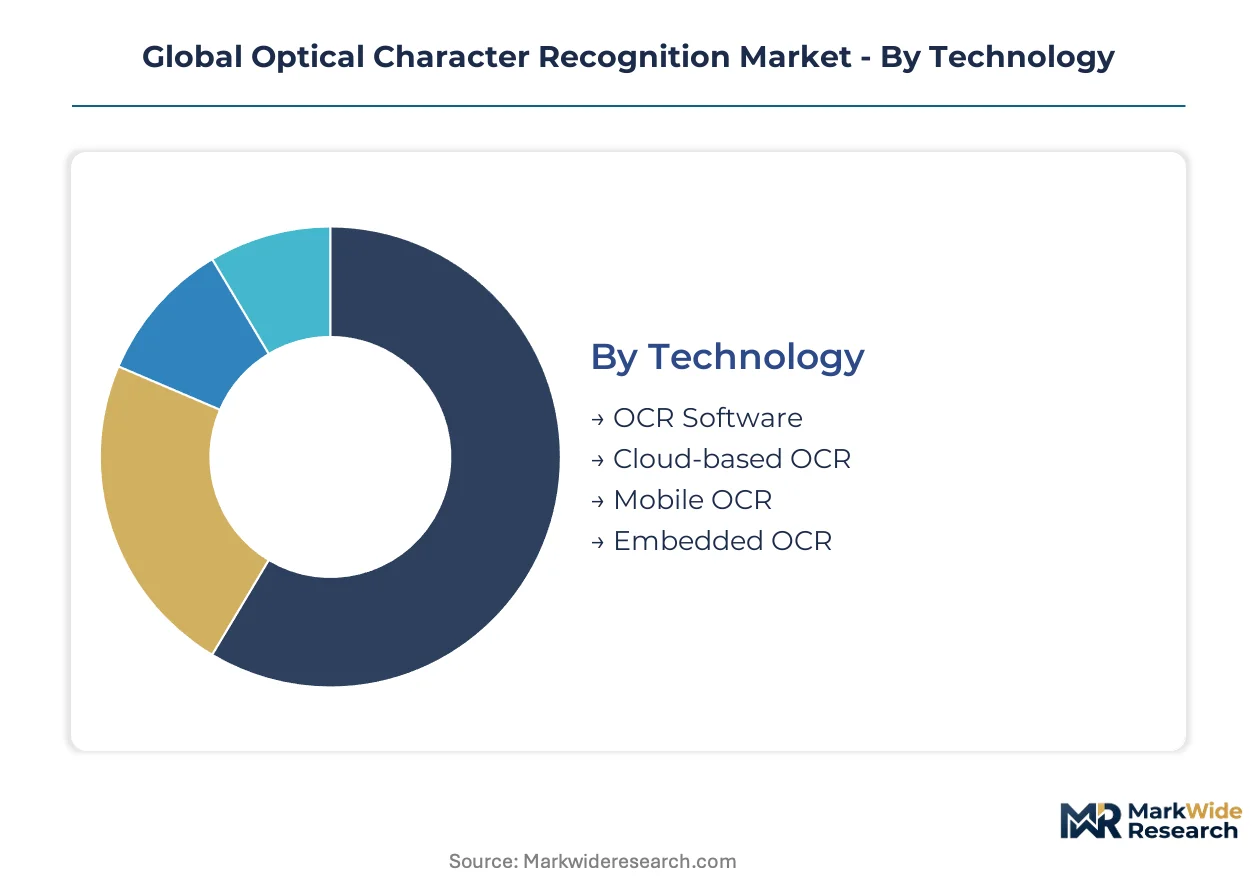
OCR procurement patterns diverge sharply across technology platforms and deployment architectures. Banking and healthcare buyers prioritize compliance-certified solutions, while retail and logistics operators optimize for field mobility and edge processing economics.
Technology:
Cloud-based OCR and mobile deployments flow through hyperscaler marketplaces and API-first channels, while embedded and on-premises software routes through systems integrators and vertical specialists.
- Cloud-based OCR:Elastic compute architectures process document streams without fixed infrastructure commitments. German banks and US health networks dominate procurement, driven by HIPAA and EU AI Act audit trail mandates that favor centralized logging.
- Mobile OCR:Smartphone camera pipelines leverage on-device neural inference for field-capture scenarios. India's tier-two banking sector concentrates demand, where regional lenders deploy KYC verification without branch hardware investments.
- OCR Software:Perpetual-license desktop suites persist in regulated Swiss and Singaporean financial institutions with data sovereignty requirements.
- Embedded OCR:Firmware modules integrate into industrial scanners and logistics handhelds for deterministic latency environments.
By volume, OCR Software leads legacy installed bases. By growth pace, Mobile OCR is climbing the fastest.
End User:
Customer type determines pricing tolerance and compliance burden, with healthcare and banking accepting premium tiers for certification depth while retail optimizes per-transaction economics.
- Banking:KYC automation and trade document processing drive procurement across Indian regional lenders and European correspondent banking networks. RBI guidelines and EU AI Act conformity assessments shape vendor selection criteria.
- Healthcare:Patient record digitization in German hospital systems and US health networks requires FDA 21 CFR Part 11 validation. Audit trail granularity commands price premiums over raw accuracy metrics.
- Education:Administrative transcript processing and examination digitization concentrate demand in national government tenders.
- Retail:Inventory tracking and receipt processing prioritize low-latency mobile capture over archival-grade precision.
Healthcare commands highest per-seat pricing. Banking shows steepest expansion trajectory as regulatory deadlines force replacement cycles.
Deployment:
Infrastructure location choices map directly to data residency mandates, with hybrid architectures emerging as the compromise for multi-jurisdiction operators.
- Hybrid:Split processing routes sensitive extraction to on-premises engines while pushing non-critical workloads to cloud tiers. German automotive suppliers and US pharmaceutical distributors adopt this model to satisfy GDPR and HIPAA geographic constraints simultaneously.
- Cloud:Fully managed APIs dominate mid-market procurement where compliance requirements permit third-party processing.
- On-premises:Fixed hardware deployments persist in Swiss private banking and Singaporean sovereign wealth fund document processing.
- SaaS:Subscription consumption models with explicit geographic processing boundaries displace perpetual licenses in procurement cycles.
Cloud captures greatest transaction volume. Hybrid deployment is gaining share fastest as jurisdictional complexity increases.
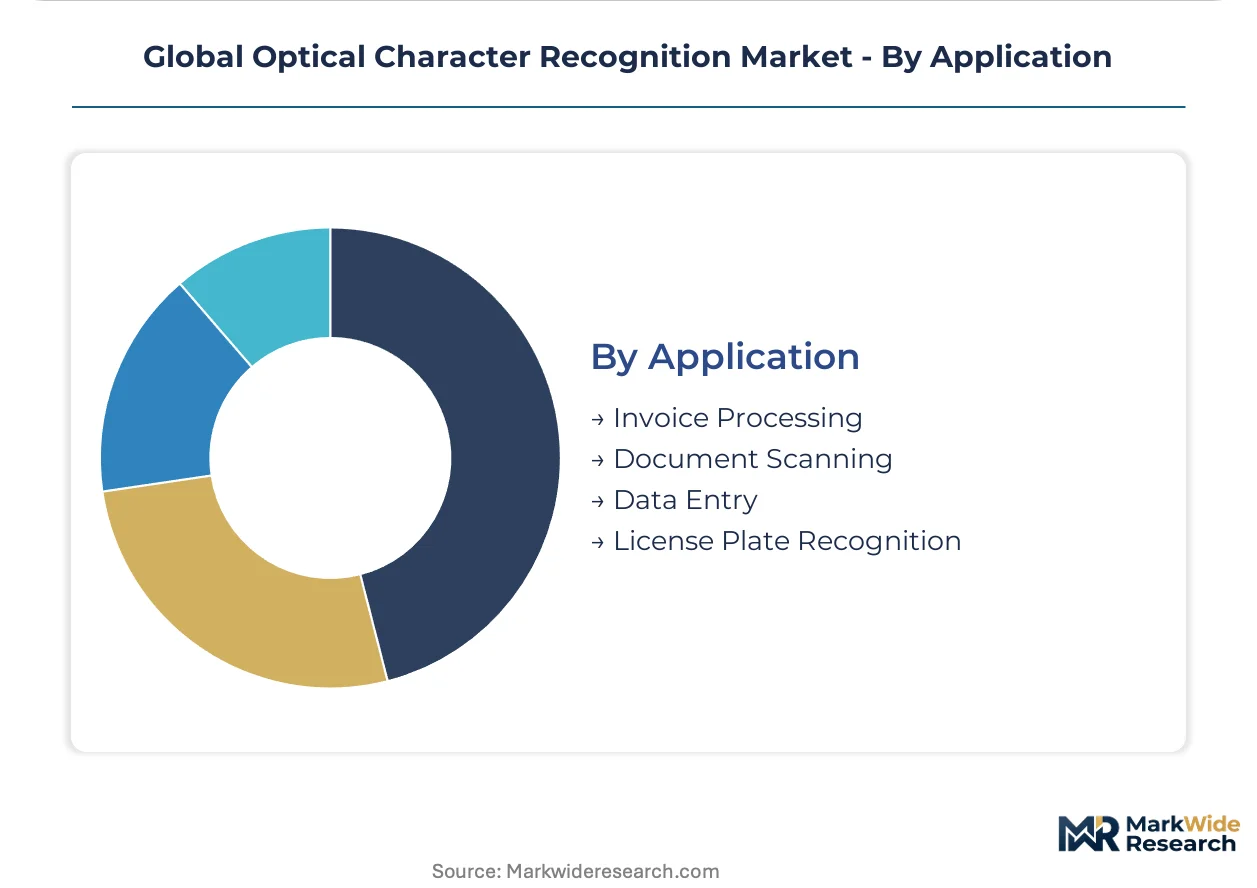
Application:
Use case specificity determines accuracy thresholds and integration depth, with financial document processing demanding structured data output while recognition tasks tolerate lower precision.
- Invoice Processing:Accounts payable automation extracts line-item detail and tax identifiers from supplier documents. European manufacturing mid-market and Indian GST compliance workflows concentrate demand, where extraction accuracy directly impacts reconciliation labor.
- Document Scanning:Archival digitization for legal discovery and government record retention requires 99-plus percent accuracy on degraded source material.
- Data Entry:Form population and database ingestion applications prioritize speed over perfect fidelity, accepting human verification loops.
- License Plate Recognition:Edge-optimized character recognition for traffic enforcement and parking management operates under strict latency budgets.
Document Scanning leads by installed transaction base. Invoice Processing shows most rapid adoption acceleration as AP automation budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables and Frankfurt's DE-CIX internet exchange underpin Europe's data processing infrastructure for document automation. India's Unified Payments Interface rail network enables real-time KYC verification across tier-two banking corridors. Submarine cable landing stations in Singapore and Mumbai anchor Asia-Pacific cloud processing hubs for financial document workflows.
United States
FDA 21 CFR Part 11 mandates electronic signature validation and audit trails for digitized patient records in hospital systems. HIPAA business associate agreements require explicit infrastructure location commitments from OCR vendors serving health networks. The Mayo Clinic corridor in Rochester, Minnesota, concentrates procurement of compliant recognition engines for clinical trial documentation.
Germany
The EU AI Act imposes conformity assessments on automated document processing systems handling sensitive personal data in banking and insurance. GDPR data minimization principles restrict how long extracted text residues persist in cloud training corpora. Bavaria's automotive supplier cluster around Munich adopts hybrid deployment models to satisfy geographic processing constraints.
India
RBI guidelines shape vendor selection criteria for KYC automation across regional lenders deploying mobile OCR. The PLI scheme for electronics manufacturing creates localized assembly opportunities for hardware vendors serving government digitization tenders. Hyderabad's fintech corridor concentrates demand for smartphone-based identity verification in tier-two cities.
Switzerland
Swiss private banking maintains fixed capital commitments to on-premises processing hardware for data sovereignty compliance. FINMA regulatory frameworks require audit granularity that commands price premiums over raw accuracy metrics. Zurich's wealth management cluster sustains demand for perpetual-license desktop suites with explicit geographic boundaries.
Singapore
The Monetary Authority of Singapore's technology risk management guidelines constrain cloud migration for sovereign wealth fund document processing. Submarine cable infrastructure connecting Southeast Asia to global financial centers enables low-latency hybrid architectures. The Marina Bay financial district anchors procurement of edge-optimized recognition engines for trade documentation.
Global Optical Character Recognition Market Competitive Landscape
Listed leaders compete with private specialists across cloud infrastructure and compliance certification dimensions. The vendor base segments into hyperscale platform operators, vertical compliance specialists, and mobile-first API providers. Three archetypes dominate: tensor-processing cloud giants, document-centric automation incumbents with captive training data pipelines, and smartphone-native capture specialists. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through regulatory certification stacking.
Within the hyperscale tier, Google and Amazon Web Services occupy positions anchored by elastic compute infrastructure and marketplace distribution. ABBYY represents the document-centric specialist archetype with European financial institution relationships. Among mobile-native providers, Scandit exemplifies the smartphone camera pipeline approach for field-service deployments. These three anchors illustrate how competitive positioning fragments across infrastructure scale, vertical compliance depth, and edge deployment economics.
| Leading Market Players |
|---|
| Ocrolus |
| ABBYY |
| Anyline |
| Docsumo |
| Adobe |
| Rossum |
| Scandit |
| Amazon Web Services |
| Others |
Supply & Pricing Matrix
Hyperscale tensor-processing infrastructure in Google Cloud and AWS data centers creates margin compression that cascades through vendor tiers, forcing mid-market SaaS providers toward specialized compliance premiums while anchoring economy-tier pricing floors. This scale asymmetry concentrates supply-side bargaining power among Asian optical sensor contract manufacturers serving hardware-integrated deployments.
Pricing Analysis
Volume-discount tiering structures separate enterprise API consumption blocks from per-transaction mobile verification pricing in Indian KYC workflows. Three-tier pricing stratification across premium compliance-certified, standard cloud-managed, and economy on-device inference levels reflects FDA 21 CFR Part 11 and EU AI Act certification depth as the primary differentiation driver. Pricing pressure stems from transformer-based foundation model commoditization eroding proprietary training pipeline premiums. Banking procurement teams in Germany and Switzerland demonstrate lowest price sensitivity where audit granularity commands contractual premiums, while Indian regional lenders optimize strictly for per-KYC transaction economics.
Supply Chain Analysis
Inventory lead times for CMOS optical sensors stretch 16-22 weeks through Taiwanese and South Korean foundries, constraining hardware-integrated OCR module availability for European industrial scanner OEMs. Component sourcing concentrates in Taiwan, South Korea, and China, with REACH and RoHS substance restrictions forcing accelerated redesign cycles for compliant sensor modules. Supply chain risk centers on single-source dependency for high-resolution imaging arrays in smartphone camera pipelines. Distribution runs through hyperscaler marketplaces for cloud APIs, systems integrators for embedded firmware, and vertical specialists for compliance-heavy healthcare deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OCR markets exhibit defensive-moat characteristics rooted in regulatory entrenchment: compliance certification stacking creates switching costs that lock banking and healthcare buyers into validated vendor relationships across multi-year procurement cycles.
For Market Incumbents: Compound regulatory certification depth by embedding EU AI Act conformity assessments and FDA 21 CFR Part 11 validation into core product architecture rather than bolt-on modules. Extend captive training data pipelines through exclusive partnerships with German automotive suppliers and US health networks to raise rival replication costs. Counter transformer-based foundation model disruption by anchoring differentiation in audit-trail granularity that black-box neural architectures cannot replicate. For New Entrants and Emerging Players: Lead with mobile-first API specialization targeting India's tier-two banking corridor where RBI-mandated KYC automation outpaces incumbent cloud-to-edge deployment capabilities. Capture white-space in Dravidian and low-resource Indic language accuracy gaps that constrain government identity verification scale. Pursue PLI scheme alignment for localized hardware assembly serving government digitization tenders as the primary go-to-market wedge. For Investors and Strategic Acquirers: Mobile-native capture specialists with smartphone camera pipeline IP and field-service logistics relationships represent the most defensible acquisition archetype against hyperscaler commoditization pressure. Long-term viability hinges on vertical compliance depth rather than raw accuracy benchmarks as regulatory frameworks tighten. Watch for EU AI Act enforcement actions against non-compliant legacy vendors as the inflection signal for replacement-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Stacking | EU AI Act and FDA 21 CFR Part 11 validation creates multi-year procurement lock-in across German banking and US health networks. |
| Foundation Model Licensing | Pre-trained transformer architectures enable smaller vendors to challenge incumbents without proprietary training pipeline investments. |
| Edge Deployment Optimization | On-device neural inference for smartphone KYC verification addresses data residency constraints in Indian tier-two cities. |
| Vertical Workflow Integration | Robotic process automation convergence captures full automation budgets rather than point-solution document parsing spend. |
| Supply Chain Compliance Redesign | REACH and RoHS alignment forces sensor module redesign toward Taiwan and South Korean component suppliers. |
Research Methodology
The analysis maps cloud-based API deployments, mobile camera pipelines, embedded firmware modules, and on-premises software suites, each validated through CTOs at European financial institutions, healthcare IT procurement committees, Indian fintech platform engineers, and logistics operations directors. Primary interview insights triangulate against secondary sources including SEC hyperscaler capex disclosures, FDA 510(k) filings for medical device OCR, RBI circulars on KYC automation, and EU AI Act implementation guidance. Bottom-up segment sizing cross-checks against top-down market aggregation across deployment architecture and end-user verticals.
Consistency checks validate volume and value outputs against hyperscaler revenue disclosures, vertical software vendor filings, and regional banking automation procurement databases. The analytical framework segments by technology platform, deployment infrastructure, end-user industry, and geographic regulatory cluster across the projection horizon. CAGRs derive from adoption curve modeling calibrated to EU AI Act compliance deadlines and RBI KYC digitization mandates. Key inputs include cloud compute pricing trajectories, smartphone camera sensor cost curves, and compliance certification timeline assumptions.
Forecasts assume regulatory continuity in EU AI Act enforcement, FDA 21 CFR Part 11 validation requirements, and RBI KYC guidelines; material policy shifts would require re-modeling. Model outputs reflect assumptions about transformer architecture commoditization speed and mobile inference hardware advancement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Technology
Digital Smell Technology Market
Analytical Technology
Computational Fluid Dynamics (CFD) Market
Analytical Technology
Emission Monitoring Software Market
Analytical Technology
Incubator Analyzer Market
Analytical Technology
Europe Computational Fluid Dynamics Market
Analytical Technology
Global Weather Forecasting Systems Market
Analytical Technology
Process Analyzer Market
Analytical Technology
Asia-Pacific Digital Scent Technology Market
Analytical Technology
AI-Powered Video Analytics Market
Analytical Technology
United States Computational Fluid Dynamics Market
Analytical Technology
Motion Simulation Market
Analytical Technology
Global Advanced Visualization Market
Analytical Technology
Brain Fingerprinting Technology Market
Analytical Technology
North America Trace Detection Screening Market