
 North America Management Consulting Services Market | 2026-2036
North America Management Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Management Consulting Services Market Insights
Artificial intelligence is hardening into a core delivery substrate across North American consulting engagements, displacing traditional labor-hour economics with outcome-based pricing models. McKinsey & Company leverages its QuantumBlack analytics division to embed machine learning directly into client operations. Boston Consulting Group (BCG) anchors its competitive position through Gamma, its dedicated data science and AI implementation arm. Deloitte Consulting sustains market breadth by integrating strategy, technology, and risk advisory under a unified delivery framework.
Management consulting services encompass structured advisory engagements where external experts diagnose organizational challenges, design operational or strategic interventions, and oversee implementation across functional boundaries; engagements typically span eight to twenty-four weeks and deploy multidisciplinary teams blending industry specialists with methodology-trained generalists. Strategy Consulting commands premium fee structures due to C-suite access and high-stakes decision support, while Operations Consulting captures volume through recurring process improvement mandates. Financial Advisory and Human Resources Consulting occupy mature growth trajectories, with margin pools shifting toward technology-enabled transformation and talent analytics respectively.
The US Securities and Exchange Commission (SEC) shapes demand through climate disclosure rules that require extensive advisory support for emissions accounting and scenario analysis. The Federal Trade Commission (FTC) and Department of Justice Antitrust Division influence merger-related consulting volume through intensified deal scrutiny. Stakeholders must monitor how generative AI tooling reshapes talent deployment models and whether regulatory fragmentation between US federal and state jurisdictions creates specialized compliance advisory opportunities.
Market Dynamics
Generative AI is compressing project timelines and collapsing the traditional pyramid staffing model across North American consulting engagements. Firms now deploy smaller, machine-augmented teams that deliver equivalent analytical depth at substantially lower labor-hour multiples.
Growth Catalysts
- The US Inflation Reduction Act:Pharmaceutical and energy clients require intensive cost modeling and compliance strategy support, creating sustained advisory demand from implementation through 2035.
- Healthcare operational restructuring:Hospital systems and payers facing margin pressure engage external advisors for clinical workflow redesign and supply chain rationalization.
- Climate disclosure mandates:SEC rules on emissions accounting and scenario analysis force Fortune 500 companies to retain specialized sustainability advisory capacity.
Market Restraints
- Talent cost inflation:Competing demand from technology firms and private equity for quantitative and AI-skilled professionals compresses consulting margin structures.
- Client insourcing:Sophisticated buyers in financial services and technology verticals build internal strategy functions that displace traditional advisory relationships.
- Project scope compression:Procurement departments mandate shorter engagement durations and fixed-fee structures that limit value capture from complex transformation work.
Strategic Opportunities
- Mid-market penetration:Private equity-owned portfolio companies in the US Southeast and Midwest represent underserved demand for operational improvement and digital transformation.
- Regulatory fragmentation advisory:Divergent state-level AI governance and privacy rules in California, New York, and Texas create compliance specialization opportunities.
- AI implementation services:Convergence of machine learning operations and change management expertise enables premium positioning for technology-enabled transformation.
Industry Challenges
- Knowledge codification:Firms must capture and systematize partner expertise into scalable digital assets without commoditizing core advisory value.
- Generative AI integration:Consultants face client pressure to demonstrate proprietary AI tooling while managing accuracy risks and hallucination liabilities in client-facing outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Management Consulting Services Market |
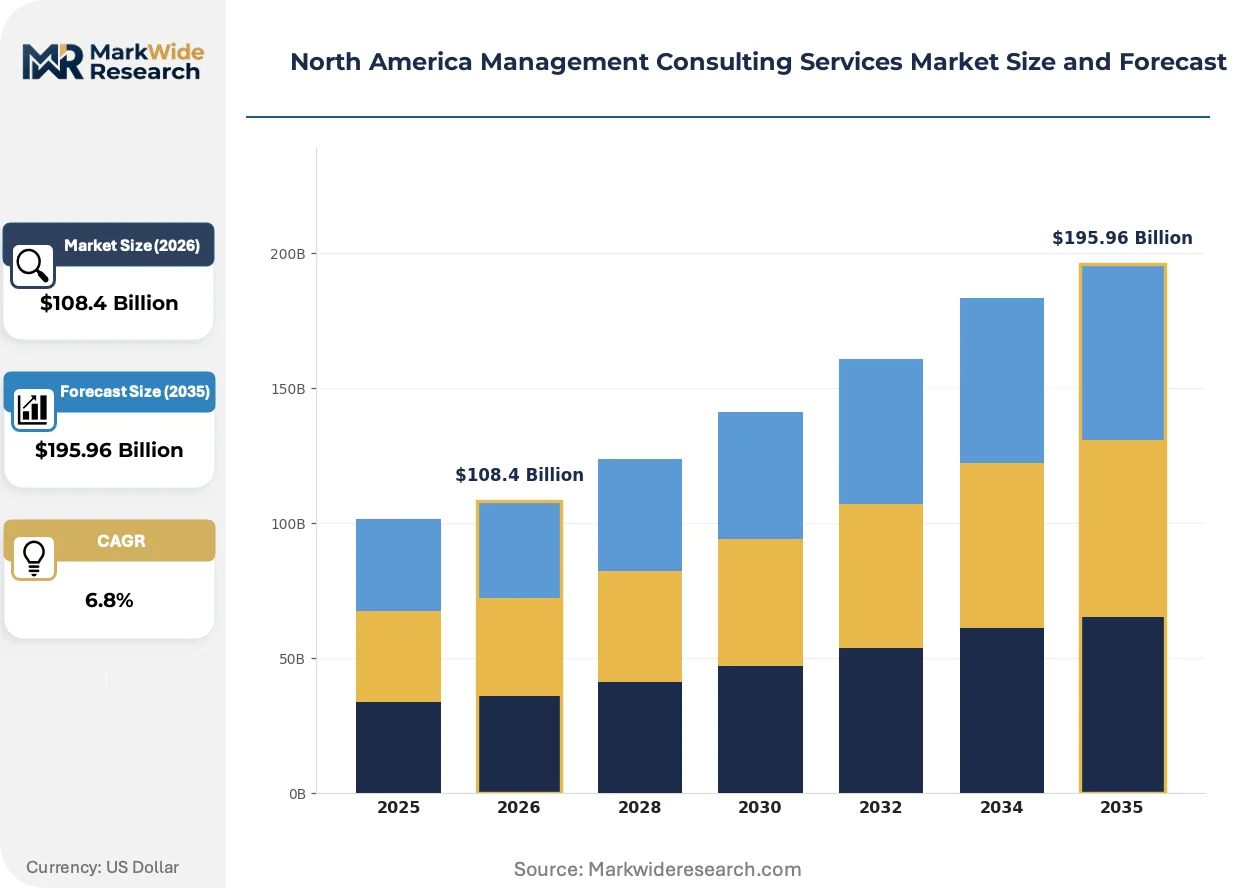
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operations Consulting, Financial Advisory, Human Resources Consulting Client Type: Large Enterprises, SMEs, Government Agencies, Non-Profits Industry Vertical: Healthcare, Technology, Manufacturing, Retail Engagement Model: Project-Based, Retainer-Based, On-Demand, Transactional |
| Companies Covered | Deloitte Consulting, EY-Parthenon, McKinsey & Company, Oliver Wyman, KPMG Advisory, Bain & Company, PwC Strategy&, Analysis Group, Boston Consulting Group (BCG), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Management Consulting Services Market Trends and Innovations
Advisory delivery models are fragmenting as technology enables unbundling of traditional strategy, implementation, and managed services. Firms compete through specialized AI capabilities, vertical depth, and outcome-aligned commercial structures rather than generalized relationship coverage.
Enterprise-grade generative AI platforms are unifying research synthesis, scenario modeling, and executive communication into single workflow environments. Healthcare and financial services clients in the Boston and New York corridors adopt these tools fastest, compressing the traditional eight-week diagnostic phase into days. This acceleration is unifying strategy formulation and implementation timelines, eroding the historical boundary between advisory phases.
SEC climate disclosure rules mandate granular emissions accounting and forward-looking scenario analysis for registrants. Industrial and energy sector clients face the steepest compliance burden, requiring specialized advisory capacity that most generalist firms cannot supply. The US market responds through rapid capability acquisition and partnership with climate data providers.
Buyers increasingly disaggregate strategy advisory from implementation execution, awarding contracts to separate vendors with demonstrated functional excellence. Large pharmaceutical and technology companies in California and Washington state lead this procurement evolution, replacing sole-source relationships with modular vendor panels. The shift pressures traditional full-service firms to defend positioning through demonstrable outcome metrics rather than relationship tenure.
North America Management Consulting Services Market Segmentation
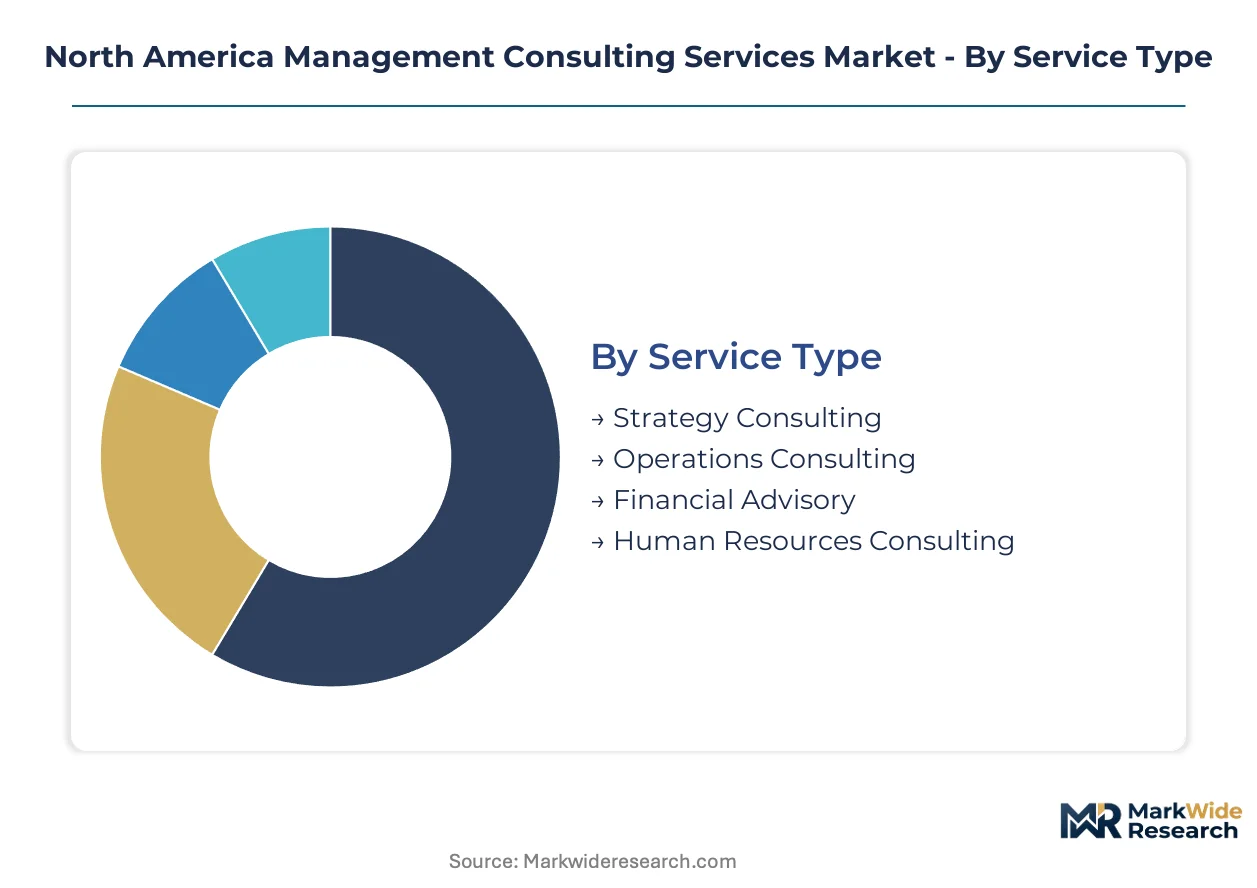
Management consulting engagements fragment across four structural dimensions that determine pricing architecture, talent deployment, and competitive positioning. Service type and client type together dictate margin capture, while vertical specialization and engagement model shape delivery economics and renewal rates.
Service Type:
Customization intensity varies sharply across this spectrum, from bespoke C-suite strategy to standardized process diagnostics.
- Strategy Consulting:High-touch advisory engagements targeting board-level decisions on market entry, M&A, and portfolio restructuring. Demand concentrates among Fortune 500 headquarters in New York and Boston, where financial services and life sciences clients pay premium fees for confidential decision support.
- Operations Consulting:Process redesign and cost optimization mandates spanning supply chain, manufacturing, and service delivery. US Midwest manufacturing clients and Southeast distribution hubs drive recurring volume, though procurement departments increasingly compress engagement scopes.
- Financial Advisory:Transaction support, valuation, and restructuring services. Private equity sponsors in Texas and California generate deal flow, with SEC disclosure rules expanding climate-related advisory needs.
- Human Resources Consulting:Talent strategy, compensation benchmarking, and organizational design. Technology firms in Seattle and Austin seek workforce analytics as AI deployment reshapes headcount planning.
Most installed capacity flows through Operations Consulting. Expansion is steepest in Strategy Consulting.
Client Type:
Contract value and relationship tenure separate institutional buyers from episodic purchasers.
- Large Enterprises:Multi-year advisory relationships with dedicated partner coverage and integrated service bundles. Pharmaceutical and energy clients facing IRA compliance requirements sustain the highest per-client spend.
- SMEs:Project-specific engagements with shorter sales cycles and standardized deliverables. Private equity-owned portfolio companies in the US Southeast represent underserved demand for operational improvement.
- Government Agencies:Federally mandated procurement processes with cost-plus fee structures and extensive compliance documentation. Federal Trade Commission and Department of Justice advisory needs concentrate in Washington DC.
- Non-Profits:Board-governed engagements with constrained budgets and mission-aligned outcome metrics. Hospital systems facing margin pressure engage for clinical workflow redesign.
Large Enterprises command the deepest partner relationships. SMEs are climbing the fastest as private equity penetration expands.
Industry Vertical:
Regulatory density and technology adoption velocity create divergent advisory needs across sectors.
- Healthcare:Clinical workflow optimization, payer-provider integration, and regulatory compliance. Hospital systems and payers engage external advisors for supply chain rationalization and operational restructuring.
- Technology:AI implementation, platform strategy, and talent analytics. California and Washington state clients lead procurement evolution toward modular vendor panels.
- Manufacturing:Lean operations, digital transformation, and reshoring strategy. US Midwest industrial clients require emissions accounting support under SEC climate disclosure rules.
- Retail:Omnichannel fulfillment, customer analytics, and cost-to-serve optimization. Margin pressure drives demand for supply chain rationalization.
Healthcare absorbs the most advisory hours. Technology is gaining share fastest as AI deployment accelerates.
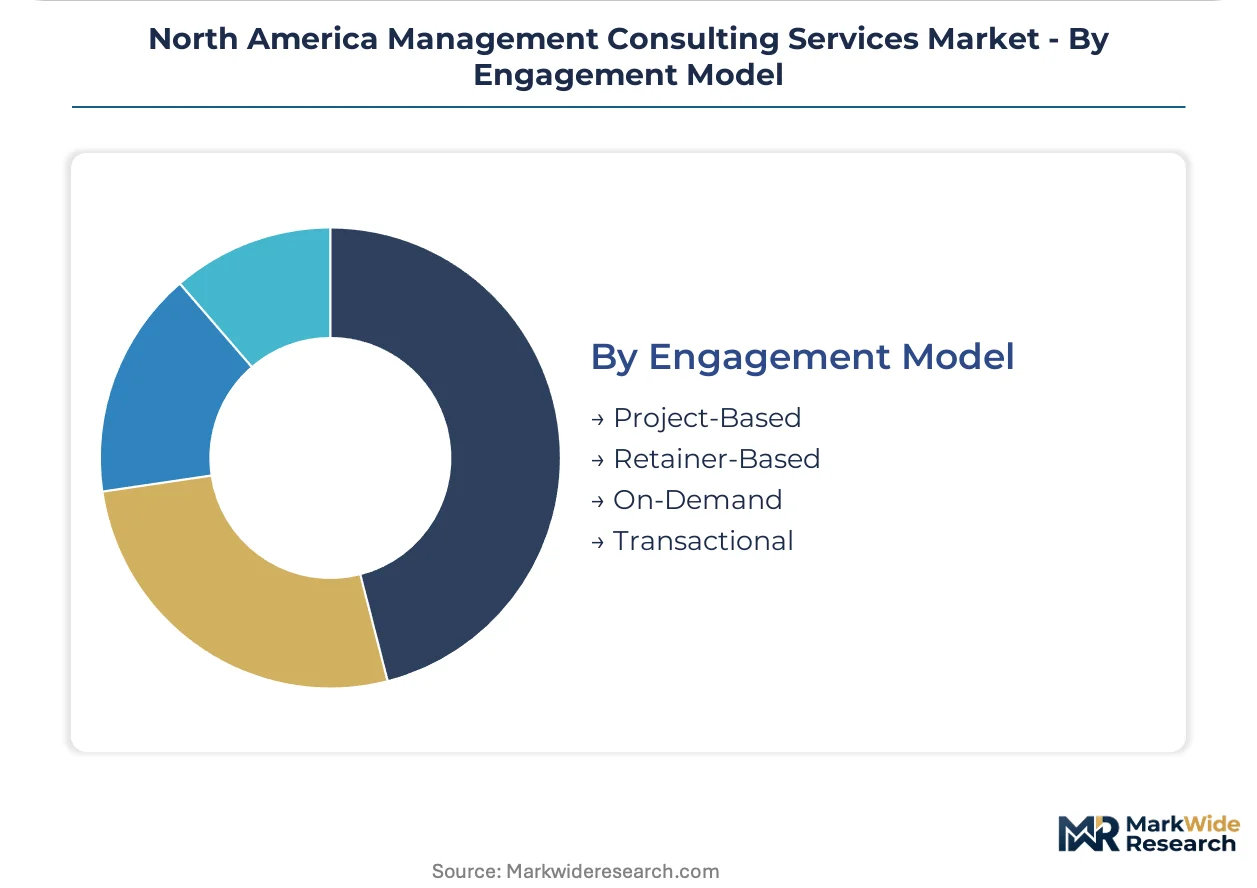
Engagement Model:
Commercial structure determines risk allocation and value capture between client and firm.
- Project-Based:Defined scope, fixed timeline, and milestone-based billing. Sophisticated buyers mandate shorter durations and fixed-fee structures that limit value capture.
- Retainer-Based:Continuous advisory access with predictable recurring revenue. Financial services clients in New York maintain long-term relationships for regulatory and strategic support.
- On-Demand:Rapid deployment for urgent diagnostic or crisis response needs. Technology clients use this for AI implementation sprints.
- Transactional:Event-driven support for M&A, litigation, or restructuring. Deal volume fluctuates with FTC and DOJ antitrust scrutiny intensity.
Project-Based structures dominate current bookings. Retainer-Based contracts are expanding most quickly as clients seek embedded advisory capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York-Boston corridor anchors North American management consulting demand, with financial services and life sciences clients sustaining premium advisory relationships. This concentration reflects deep capital markets infrastructure and dense pharmaceutical R&D ecosystems. Geographic expansion into underserved markets is reshaping competitive deployment across the continent.
United States
Pharmaceutical manufacturers facing IRA compliance mandates drive sustained advisory demand for cost modeling and pricing strategy. The SEC climate disclosure rules force Fortune 500 industrials to retain specialized sustainability advisory capacity. Hospital systems across the Midwest and Southeast engage external advisors for clinical workflow redesign and supply chain rationalization.
Canada
Energy sector clients in Alberta require emissions accounting support under evolving federal climate regulations. Toronto's financial services cluster sustains retainer-based relationships for regulatory and M&A advisory. Federal procurement processes in Ottawa create dedicated advisory demand for compliance documentation and cost-plus structuring.
Mexico
Nearshoring manufacturing investments in Nuevo León and the Bajío Region generate operational improvement advisory needs. Energy sector privatization and regulatory reform create compliance strategy demand from international investors. Mexico City's corporate headquarters sustain project-based engagements for market entry and organizational design.
Pacific Northwest
Technology firms in Seattle and Portland seek workforce analytics as AI deployment reshapes headcount planning. Amazon and Microsoft alumni networks accelerate procurement evolution toward modular vendor panels. Cloud infrastructure providers drive demand for platform strategy and data architecture advisory.
North America Management Consulting Services Market Competitive Landscape
Global majors compete with regional champions across service breadth and vertical specialization. The North American consulting market exhibits tiered concentration, with a handful of full-service networks capturing disproportionate share in strategy and financial advisory. Three archetypes dominate: integrated professional services networks, pure-play strategy boutiques, and specialized analytics divisions. Competitive moves center on AI capability acquisition and outcome-based commercial restructuring.
Within the integrated network tier, Deloitte Consulting and PwC Strategy& anchor positions through unified delivery frameworks spanning strategy, technology, and risk advisory. McKinsey & Company exemplifies the analytics-forward archetype through dedicated machine learning implementation capabilities. These firms represent contrasting responses to generative AI compression of traditional project timelines.
| Leading Market Players |
|---|
| Deloitte Consulting |
| EY-Parthenon |
| McKinsey & Company |
| Oliver Wyman |
| KPMG Advisory |
| Bain & Company |
| PwC Strategy& |
| Analysis Group |
| Boston Consulting Group (BCG) |
| Others |
Pricing and Supply Chain Analysis
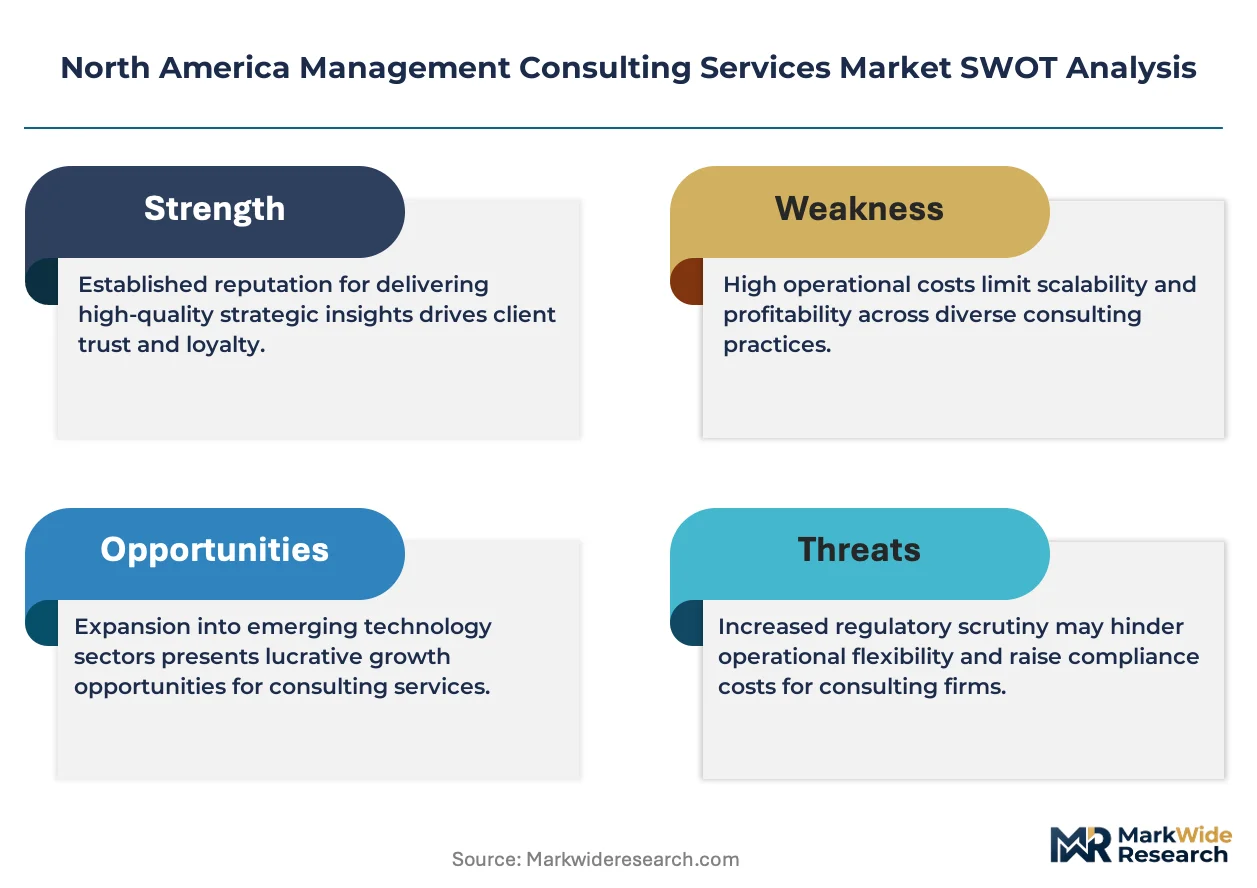
SEC climate disclosure mandates gate qualified advisory supply and premium-tier pricing access for North American management consulting engagements, as only firms with certified sustainability accounting capabilities can serve Fortune 500 industrials facing emissions compliance deadlines. This regulatory filter concentrates pricing power among established networks while compressing margins for generalist competitors lacking specialized credentialing.
Pricing Analysis
Input-cost pass-through from AI-skilled talent inflation reshapes fee structures across the consulting pyramid. Project-based billing dominates engagements, though outcome-based models gain traction as clients demand risk-sharing on transformation mandates. Price differentiation hinges on partner seniority and vertical certification depth, with C-suite access commanding substantial premiums over staff-augmentation tiers. Pricing pressure stems from procurement departments mandating fixed-fee compression and shorter diagnostic phases. Private equity-owned portfolio companies in the US Southeast exhibit highest price sensitivity, while pharmaceutical clients facing IRA compliance deadlines show lowest elasticity for specialized advisory.
Supply Chain Analysis
Dual-sourcing requirements from sophisticated buyers fragment advisory delivery across multiple firm relationships, ending sole-source dependencies. Supply concentrates in the United States, United Kingdom, and India, with New York and London anchoring partner-level strategy capacity while Bengaluru and Hyderabad deliver analytics and research support. Talent pipelines draw from elite business schools, technology firm alumni networks, and specialized data science programs. Single-source vulnerability emerges from concentrated partner expertise in niche regulatory domains. Distribution runs through direct enterprise sales, alumni referral networks, and private equity sponsor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America management consulting market represents a late-cycle quality story as buyers shift procurement toward outcome-guaranteed engagements requiring demonstrated AI implementation credentials rather than relationship tenure alone.
For Market Incumbents: Cement defensive positioning through exclusive data partnerships with climate accounting platforms and embedded AI tooling that raises switching costs for pharmaceutical and energy clients. Acquire boutique regulatory specialists in California and Texas to preempt state-level fragmentation advisory demand. Vertical integration into proprietary machine learning operations platforms protects margin structures against talent cost inflation from technology firm competition.
For New Entrants and Emerging Players: Generative AI implementation services offer a technology-first wedge into mid-market private equity portfolio companies underserved by full-service networks. Target operational improvement mandates in US Midwest manufacturing and Southeast distribution hubs where procurement evolution lags coastal markets. Lead with fixed-outcome commercial structures and rapid diagnostic tooling to differentiate against incumbent relationship-based selling.
For Investors and Strategic Acquirers: Roll-up economics work for specialized analytics boutiques because regulatory complexity and AI tooling requirements prevent mid-market clients from building equivalent internal capabilities. Focus acquisition screening on firms with embedded healthcare or energy vertical expertise and demonstrated outcome-based contract structures. Watch FTC antitrust scrutiny intensity as the inflection signal for transaction advisory volume cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Capability Acquisition | McKinsey's QuantumBlack and BCG Gamma demonstrate machine learning implementation premiums. |
| Vertical Specialization Buildout | SEC climate rules force industrial sector expertise concentration beyond generalist reach. |
| Outcome-Based Commercial Restructuring | Risk-sharing contracts align fees with measurable transformation results for PE sponsors. |
| Mid-Market Penetration | US Southeast and Midwest portfolio companies represent underserved operational improvement demand. |
| Regulatory Fragmentation Advisory | Divergent state AI governance rules in California, New York, and Texas create compliance specialization. |
Research Methodology
Direct dialogue with consulting firm partners, healthcare system CFOs, pharmaceutical procurement leads, and private equity operating partners grounded qualitative findings in practitioner experience. Secondary validation drew from SEC filings, FTC enforcement actions, IRA implementation guidance, and clinical workflow redesign case studies. Bottom-up and top-down triangulation cross-checked engagement volume estimates against firm headcount disclosures and client spend patterns.
Bottom-up modeling aggregated service-type, client-type, and vertical-specific growth trajectories across the projection horizon. Segmentation dimensions included engagement model, AI implementation maturity, and regulatory exposure intensity. CAGRs derived from weighted scenario analysis of talent supply constraints and technology adoption curves. Forecast inputs incorporated IRA compliance timelines and SEC disclosure phase-in schedules.
The model holds under stable regulatory implementation timelines; deviation in antitrust enforcement intensity or AI governance fragmentation would shift advisory demand composition materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Multivendor ATM Software Market
Financial Services
Commodity Trade Finance Market
Financial Services
United States Credit Agency Market
Financial Services
Smart Finance Services Market
Financial Services
Global Product Cost Management Market
Financial Services
Pawn Shop Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Financial Advisory Services Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Check Cashing Services Market
Financial Services
Factoring Services Market
Financial Services
China Supply Chain Financing Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Saas Escrow Services Market