
 Advanced Baby Monitors Market | 2026-2036
Advanced Baby Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Baby Monitors Market Analysis
Aftermarket service revenue from subscription-based monitoring and cloud storage is fragmenting across hardware manufacturers and third-party platform providers. Owlet Baby Care leverages its wearable monitoring ecosystem to sustain recurring revenue through health-data analytics services. Arlo Technologies Inc. competes on camera-centric architectures, while VTech Communications Inc. anchors volume through retail channel control in North American big-box distribution.
Advanced baby monitors integrate audio capture, video transmission, biometric sensing, and wireless connectivity into nursery safety and infant health surveillance systems, typically operating on 2.4 GHz Wi-Fi or proprietary DECT protocols with AES-128 encryption. Smart monitors incorporating real-time breathing and oxygen-level tracking command the highest margin pools, whereas audio-only devices face commoditization pressure. Wi-Fi-enabled units are expanding fastest among dual-income urban households, while infrared night-vision functionality remains standard across all premium tiers.
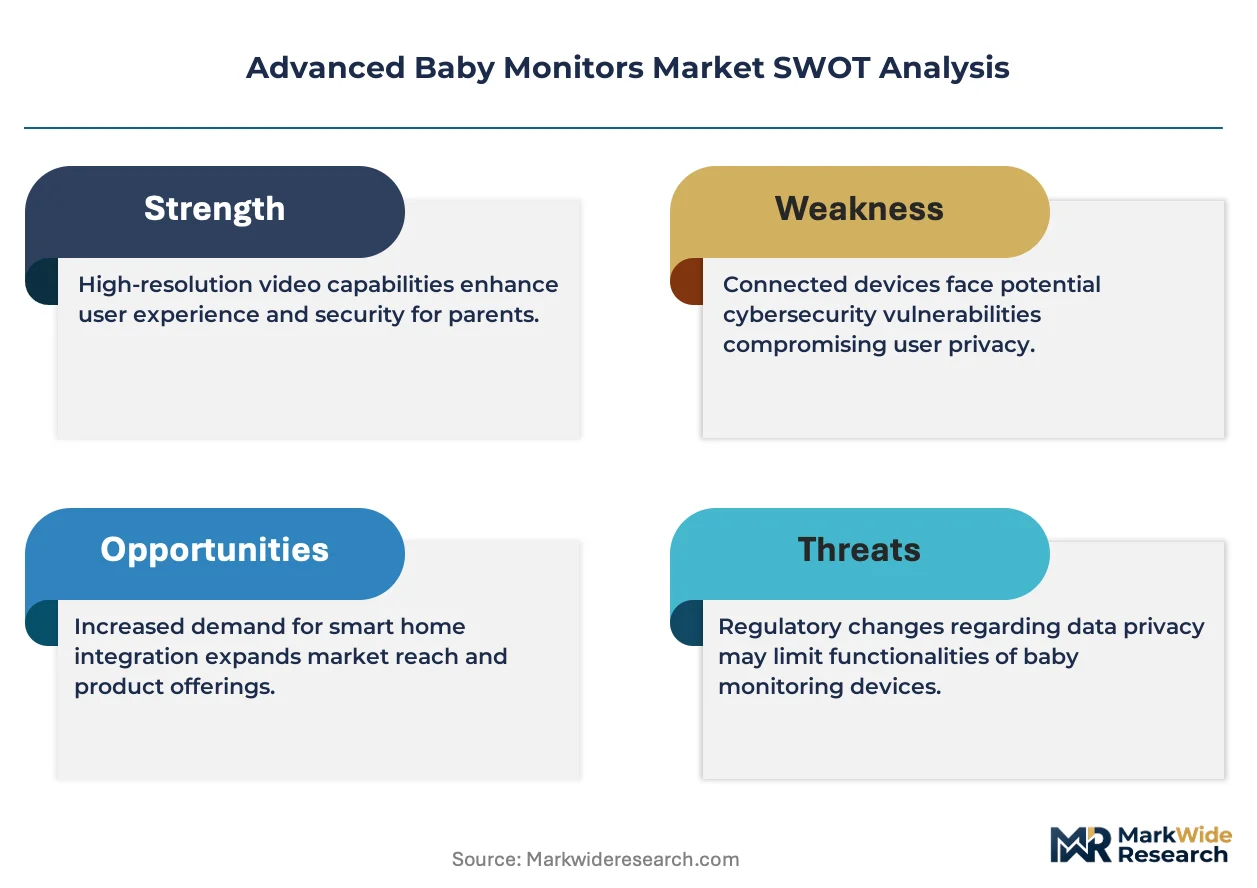
The FCC governs radio-frequency emissions and spectrum allocation for wireless nursery devices in the United States, while the EU Radio Equipment Directive mandates cybersecurity resilience and interoperability testing for connected monitors sold in Europe. China's MIIT enforces GB standards for wireless transmission power and data localization in IoT devices. Stakeholders must monitor evolving data-privacy obligations and pediatric-health-claim substantiation rules as regulatory scrutiny intensifies on biometric-sensing features marketed to anxious parents.
Market Dynamics
Subscription monetization of biometric data streams is restructuring competitive economics in connected nursery devices, forcing hardware-centric vendors toward recurring-revenue architectures or margin erosion.
Growth Catalysts
- EU Radio Equipment Directive:Cybersecurity certification mandates for IoT devices are creating compliance-driven demand for premium encrypted monitors in European retail channels.
- Biometric sensing convergence:Real-time breathing and oxygen-level tracking technologies are commanding margin premiums from anxiety-prone millennial parent segments.
- Dual-income household concentration:Urban China and Germany are exhibiting concentrated adoption of Wi-Fi-enabled units with remote workplace monitoring capabilities.
Market Restraints
- Semiconductor supply concentration:Taiwan-domiciled foundry capacity constraints are creating lead-time volatility for DECT protocol chipsets.
- GB standards localization:China's MIIT data-localization requirements for wireless transmission are fragmenting cloud architecture economics.
- Audio-only commoditization:Low-cost 2.4 GHz analog alternatives from unbranded Asian manufacturers are compressing entry-tier pricing floors.
Strategic Opportunities
- Pediatric telehealth integration:Remote patient monitoring reimbursement codes are opening clinical channel partnerships for FDA-cleared biometric wearables.
- Third-party platform unbundling:Independent cloud storage providers are disintermediating manufacturer-controlled subscription stacks.
- India urban penetration:Nuclear family concentration in Mumbai and Delhi is creating first-mover advantage for premium smart monitor distribution.
Industry Challenges
- Pediatric health-claim substantiation:FDA and EMA scrutiny of anxiety-marketed biometric features is extending regulatory clearance timelines.
- Legacy DECT-Wi-Fi interoperability:Multi-protocol firmware engineering talent scarcity is constraining product roadmap velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Baby Monitors Market |
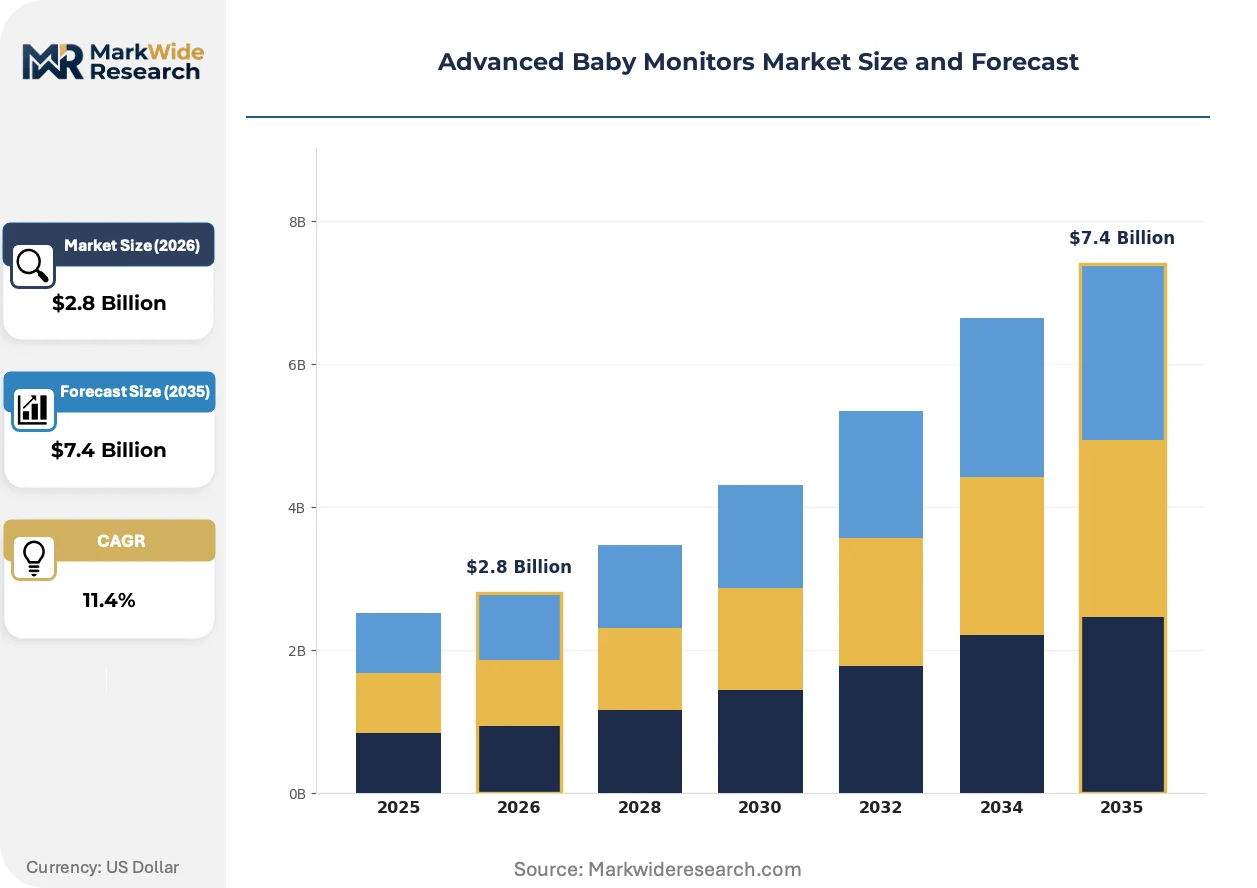
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Monitors, Video Monitors, Smart Monitors, Wearable Monitors Technology: Wi-Fi, Bluetooth, Cellular, Infrared End User: Parents, Caregivers, Hospitals, Daycare Centers Feature: Night Vision, Temperature Sensors, Two-way Talk, Motion Detection |
| Companies Covered | VTech Communications Inc., Motorola Mobility LLC, Panasonic Holdings Corporation, Samsung Electronics, Lenovo Group Limited, Owlet Baby Care, Arlo Technologies Inc., Philips Avent, Summer Infant Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Baby Monitors Market Emerging Trajectories
Edge-computing architectures and on-device AI inference are redistributing data processing away from cloud dependencies, altering cost structures and privacy risk profiles simultaneously.
Computer-vision-based contactless breathing monitoring is rendering obsolete wearable sock and band form factors that require direct skin contact and frequent recharging. Dual-income households in the United States are adopting camera-centric nursery systems at three times the rate of traditional wearable setups. This displacement is compressing addressable market share for Owlet-style hardware ecosystems and forcing biometric vendors toward multi-modal sensing strategies.
The EU AI Act's risk-classification framework for biometric identification systems is imposing conformity assessment obligations on breathing-pattern recognition algorithms. Manufacturers must now document algorithmic transparency and pediatric dataset representativeness before CE marking. Premium-tier smart monitors with AI-driven anomaly detection face the steepest compliance cost escalation, with German and French regulators conducting parallel market surveillance.
Millennial parents are consolidating purchase decisions around pediatrician recommendation channels rather than retail discovery. Big-box electronics distribution in North America is losing share to medical device showrooms and direct-to-consumer telehealth platforms. This channel rotation is most pronounced in California and New York, where employer-sponsored parental benefit programs include subsidized smart monitor procurement.
Advanced Baby Monitors Market Segmentation
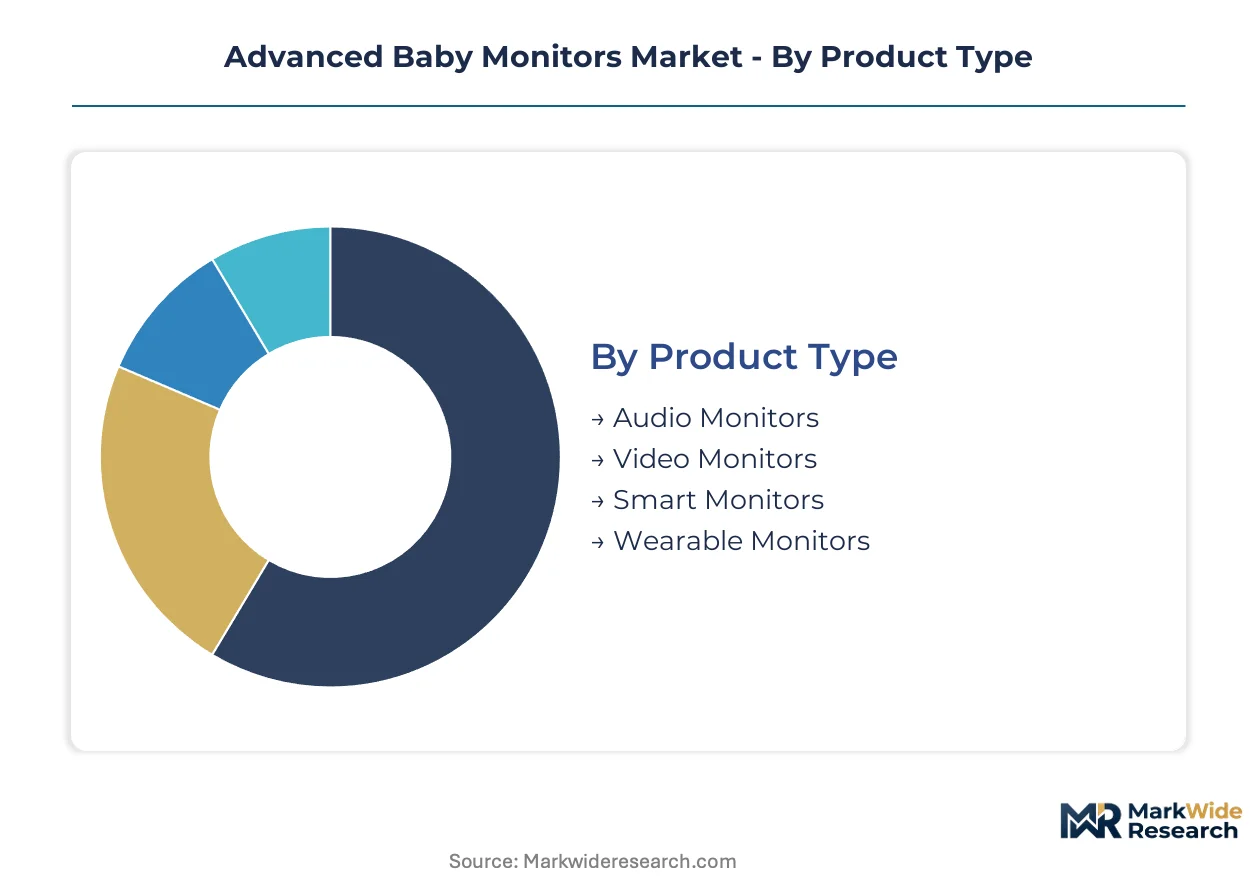
Segmentation reveals distinct margin profiles across the Advanced Baby Monitors Market. Hardware-only segments face commoditization pressure, while biometric-integrated categories sustain recurring revenue through subscription attach rates and cloud storage dependencies.
Product Type:
After-sales-service intensity varies dramatically across hardware tiers, with wearable and smart monitors demanding ongoing firmware updates, health-data analytics subscriptions, and clinical integration support that audio-only devices never require.
- Smart Monitors:These systems integrate real-time breathing tracking, oxygen-level sensing, and AI-driven anomaly detection through edge-computing architectures. Demand concentrates in dual-income urban households across the United States, Germany, and China, where millennial parents prioritize pediatric telehealth compatibility and FDA-cleared biometric claims over upfront hardware cost.
- Video Monitors:Camera-centric nursery systems with infrared night-vision and computer-vision-based contactless monitoring are displacing wearable alternatives. Adoption clusters in California and New York employer-sponsored parental benefit programs, where pediatrician recommendation channels now outweigh retail discovery for purchase decisions.
- Wearable Monitors:Sock and band form factors requiring direct skin contact face form-factor fatigue and recharging friction.
- Audio Monitors:Low-cost 2.4 GHz analog alternatives from unbranded manufacturers dominate price-sensitive entry tiers with minimal service attachment.
By volume, audio monitors lead. By growth pace, smart monitors are climbing the fastest.
Technology:
Protocol selection determines cloud architecture economics, regulatory compliance burden, and interoperability complexity across connected nursery deployments.
- Wi-Fi:2.4 GHz connectivity enables remote workplace monitoring and third-party platform integration but exposes devices to cybersecurity certification mandates under the EU Radio Equipment Directive. Urban China and Germany exhibit concentrated adoption where dual-income household density supports premium positioning.
- Infrared:Night-vision functionality operates as a standard feature across premium tiers regardless of primary connectivity protocol, with sensor modules sourced from concentrated Asian optical component suppliers.
- Bluetooth:Short-range protocols suit localized nursery coverage with reduced cybersecurity surface area.
- Cellular:LTE and 5G modules bypass Wi-Fi dependency for rural or multi-location monitoring scenarios.
By installed base, Wi-Fi dominates. By regulatory complexity, cellular faces the steepest compliance escalation.
End User:
Customer type dictates channel configuration, with clinical procurement requiring FDA clearance and telehealth platform integration that consumer retail never demands.
- Parents:Millennial dual-income households drive premium smart monitor adoption through pediatrician recommendation channels and employer-sponsored benefit programs. Purchase consolidation around medical device showrooms and direct-to-consumer telehealth platforms is eroding big-box electronics distribution in California and New York.
- Hospitals:Neonatal intensive care units and pediatric wards require FDA-cleared biometric wearables with remote patient monitoring reimbursement codes, opening clinical channel partnerships distinct from consumer markets.
- Caregivers:Grandparents and extended family members represent a secondary purchase influencer segment with lower technology sophistication.
- Daycare Centers:Multi-infant monitoring environments prioritize cost scalability over individual biometric precision.
By unit volume, parents account for the majority. By margin per unit, hospitals command the highest pricing.
Feature:
Capability bundling determines tiered pricing architecture, with computer-vision and biometric sensing commanding premiums over environmental monitoring alone.
- Motion Detection:AI-driven activity recognition algorithms face EU AI Act conformity assessment obligations for biometric identification systems. German and French regulators conduct parallel market surveillance, imposing documentation requirements for algorithmic transparency and pediatric dataset representativeness.
- Two-way Talk:Real-time audio communication supports remote parental reassurance but adds latency and privacy risk profiles that edge-computing architectures partially mitigate.
- Night Vision:Infrared illumination modules are standard across premium tiers regardless of other feature bundling.
- Temperature Sensors:Environmental monitoring capabilities face commoditization as baseline inclusions.
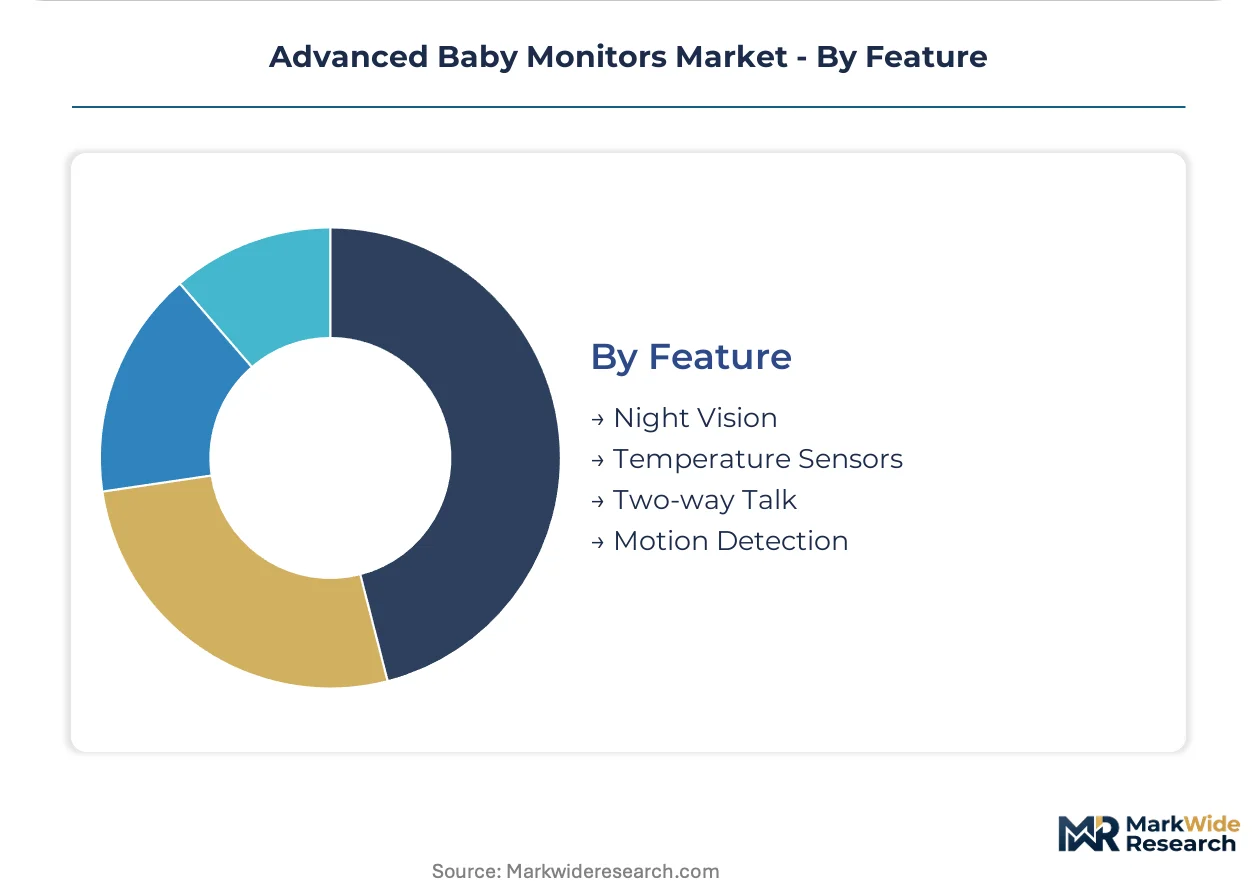
By penetration rate, night vision is universal. By differentiation power, motion detection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Millennial parents in the United States and Germany prioritize biometric sensing and pediatric telehealth integration, while Chinese buyers favor workplace remote-monitoring capabilities and Indian markets remain nascent with concentrated urban adoption.
United States
Dual-income households in California and New York drive premium smart monitor adoption through employer-sponsored parental benefit programs. The FCC governs radio-frequency emissions and spectrum allocation for wireless nursery devices, creating compliance thresholds for Wi-Fi-enabled units. Pediatrician recommendation channels now outweigh big-box retail discovery in these coastal clusters.
Germany
Urban centers exhibit concentrated demand for encrypted monitors with EU Radio Equipment Directive certification. The EU AI Act's risk-classification framework imposes conformity assessment obligations on breathing-pattern recognition algorithms. Berlin and Munich regulators conduct parallel market surveillance, documenting algorithmic transparency requirements before CE marking.
China
MIIT enforces GB standards for wireless transmission power and data localization in IoT devices, fragmenting cloud architecture economics. Shanghai and Beijing dual-income households adopt Wi-Fi-enabled units with remote workplace monitoring capabilities at accelerated rates. Localized server requirements reshape subscription monetization models for foreign entrants.
India
Nuclear family concentration in Mumbai and Delhi creates first-mover advantage for premium smart monitor distribution. The country's national telecommunications regulator oversees wireless device certification with evolving data-privacy obligations. Metro-specific retail partnerships concentrate initial penetration before secondary city expansion.
United Kingdom
Pediatric telehealth integration opens clinical channel partnerships for biometric wearables with remote patient monitoring reimbursement codes. The Medicines and Healthcare products Regulatory Agency scrutinizes health-claim substantiation for anxiety-marketed features. London-based medical device showrooms gain share from traditional electronics distribution.
Advanced Baby Monitors Market Vendor Landscape
Capability concentration sits with biometric-integrated specialists; scale advantage sits with consumer electronics conglomerates. The vendor base stratifies across three tiers: wearable ecosystem builders, camera-centric platform providers, and volume-driven retail channel controllers. Strategic moves center on subscription revenue architecture migration and third-party platform unbundling.
Within the wearable monitoring tier, Owlet Baby Care exemplifies recurring-revenue architecture through health-data analytics services. Arlo Technologies Inc. and VTech Communications Inc. occupy positions on the camera-centric and retail-channel vectors respectively. These three anchors represent divergent competitive responses to subscription monetization pressure.
| Leading Market Players |
|---|
| VTech Communications Inc. |
| Motorola Mobility LLC |
| Panasonic Holdings Corporation |
| Samsung Electronics |
| Lenovo Group Limited |
| Owlet Baby Care |
| Arlo Technologies Inc. |
| Philips Avent |
| Summer Infant Inc. |
| Others |
Supply Flow & Price Mechanics
Foundry undercapacity in Taiwan is compressing DECT chipset availability and forcing smart monitor manufacturers toward spot-market procurement premiums. This utilization squeeze simultaneously elevates input costs for encrypted premium tiers and accelerates Wi-Fi protocol migration among cost-sensitive vendors seeking supply diversification.
Pricing Analysis
Long-term offtake contracts dominate procurement for DECT protocol chipsets, while spot-market purchasing prevails for Wi-Fi modules and infrared sensor arrays. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biometric systems from encrypted EU-compliant units and unbranded analog alternatives. Pricing pressure stems from low-cost 2.4 GHz audio imports flooding entry tiers. Daycare centers exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to reimbursement code coverage.
Supply Chain Analysis
Extended payment terms from Taiwan-domiciled foundries are tightening working capital cycles for mid-tier manufacturers without supply-chain finance facilities. Component sourcing draws from Taiwan for DECT chipsets, China for infrared optical modules, and South Korea for edge-computing AI processors. Single-source vulnerability concentrates in DECT protocol semiconductor fabrication. Distribution runs through big-box retail in North America, medical device showrooms in Germany, and direct-to-consumer telehealth platforms in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as biometric data streams disaggregate from hardware-bound subscription stacks, with third-party cloud providers unbundling manufacturer-controlled revenue architectures.
For Market Incumbents: Build switching-cost moats through pediatric telehealth integration and employer benefit program exclusivity. Secure FDA clearance for breathing-pattern algorithms before EMA scrutiny intensifies. Acquire edge-computing firmware talent scarce in multi-protocol engineering. Channel control through medical device showrooms defends against retail erosion in coastal United States clusters.
For New Entrants and Emerging Players: Build out white-space presence in Indian nuclear family segments across Mumbai and Delhi before secondary city saturation. Target caregiver-influencer purchase decisions with simplified UX architectures bypassing millennial complexity fatigue. Pursue direct-to-consumer telehealth platform partnerships as primary go-to-market angle rather than retail distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward biometric-integrated specialists with recurring-revenue attach rates above hardware-centric volume players. Long-term viability favors FDA-cleared wearable ecosystems over camera-centric architectures facing computer-vision displacement. Monitor EU AI Act conformity assessment timelines as inflection signal for premium-tier compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Telehealth Integration | FDA-cleared biometric wearables unlock remote patient monitoring reimbursement codes in hospital channels. |
| EU Cybersecurity Certification | Radio Equipment Directive compliance creates premium positioning in German and French retail segments. |
| Edge-Computing Architecture Migration | On-device AI inference reduces cloud dependency and mitigates MIIT data-localization cost fragmentation. |
| Third-Platform Cloud Partnership | Independent storage providers disintermediate manufacturer subscription stacks, altering margin capture economics. |
| Computer-Vision Form Factor Shift | Contactless breathing monitoring renders wearable sock ecosystems obsolete in dual-income United States households. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with connected device product managers, pediatric telehealth platform engineers, hospital biomedical procurement leads, and FCC regulatory affairs specialists; and secondary validation through FDA 510(k) filings, EU Radio Equipment Directive certification databases, MIIT GB standard publications, and hyperscaler IoT platform capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across the projection horizon.
Forecast inputs incorporated product type segmentation by biometric integration level, technology protocol selection, end-user channel configuration, and regional regulatory cluster intensity. CAGRs derived from installed base growth rates, replacement cycle compression, and subscription attach rate evolution. Pediatric health-claim substantiation timelines and semiconductor foundry utilization curves served as industry-specific sensitivity parameters.
Stress conditions across DECT chipset lead-time volatility, EU AI Act enforcement intensity, and China data-localization compliance cost were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding millennial parent technology adoption curves and employer benefit program expansion. Macroeconomic recession, regulatory clearance delays, or edge-computing cost breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Office and Contact Center Headset Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Adult Sex Dolls Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Mini Bluetooth Shower Speaker Market