
 Missouri Legal Cannabis Market | 2026-2036
Missouri Legal Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Missouri Legal Cannabis Market Analytics
Medical patients are reorganizing their purchasing patterns toward full-spectrum and higher-potency products as adult-use access broadens the customer base. Good Day Farm Missouri leverages vertical cultivation and processing infrastructure to control quality from biomass to packaged goods. Illicit Gardens differentiates through craft flower genetics and small-batch curing protocols that command shelf space in premium dispensaries. Proper Cannabis anchors its position with a dense retail network across Missouri's urban corridors.
Missouri legal cannabis comprises regulated tetrahydrocannabinol and cannabidiol products cultivated, processed, and sold under state-issued licenses, with mandatory third-party testing for contaminants and potency verification before retail release. The industry serves therapeutic relief, wellness supplementation, and adult recreational consumption within state-defined purchase limits and possession thresholds. Flower retains the largest revenue share among product types, though concentrates are expanding fastest as extraction technology improves and experienced consumers seek higher bioavailability. Recreational users now represent the fastest-growing customer type segment, while medical patients sustain the highest purchase frequency and brand loyalty metrics. Dispensaries dominate distribution channel volume, yet delivery services are gaining traction in suburban markets where zoning restrictions limit storefront density.
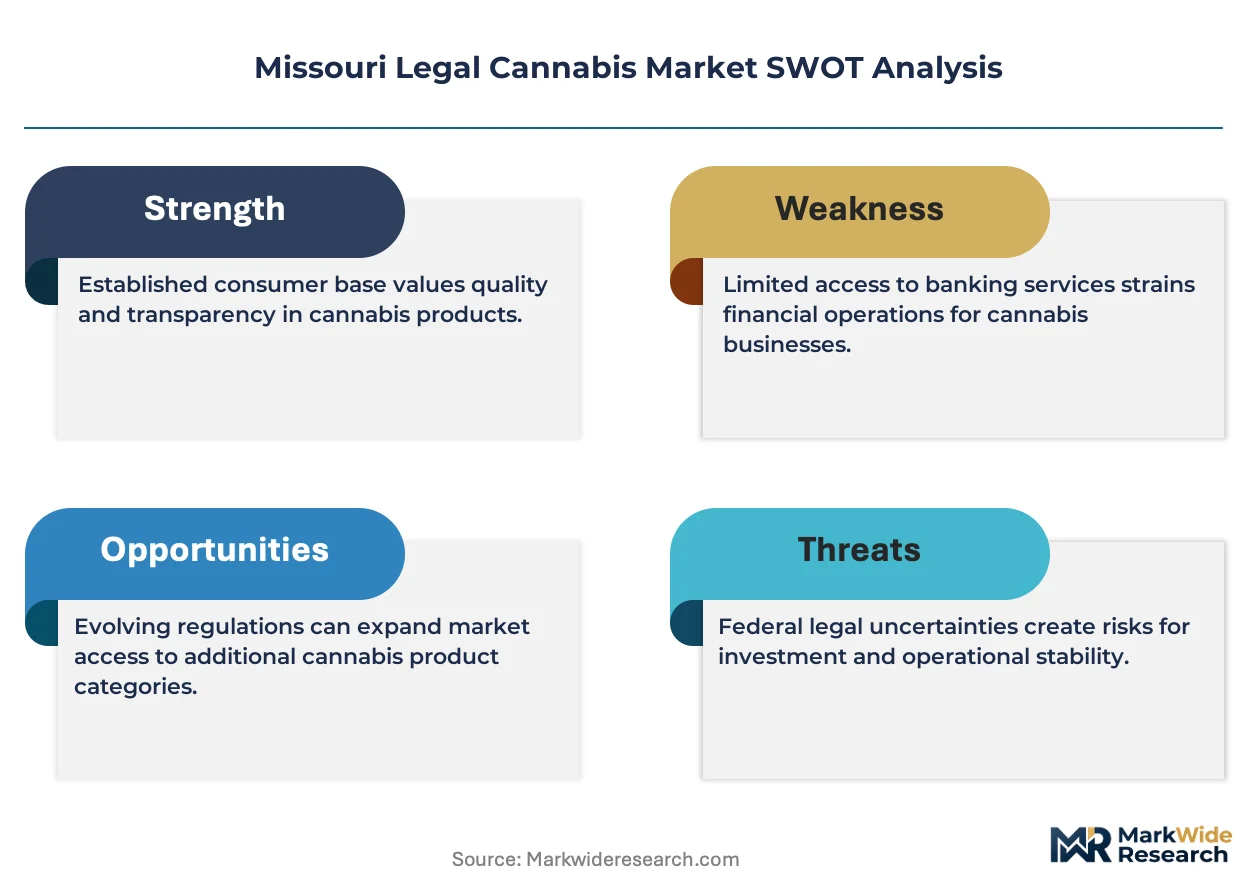
Missouri DHSS governs licensing, product testing, and seed-to-sale tracking through its Division of Medical Cannabis, while the Missouri Department of Agriculture oversees hemp-derived product standards and pesticide screening protocols. Local municipal zoning boards impose additional operational constraints on cultivation sites and retail locations, creating patchwork market access conditions across counties. Stakeholders must monitor pending legislative revisions to possession limits, social equity licensing provisions, and potential federal rescheduling impacts that would alter banking access and interstate commerce prohibitions.
Market Dynamics
Missouri DHSS seed-to-sale tracking mandates and potency testing requirements are compressing product development cycles and forcing reformulation of legacy SKUs to meet new packaging and labeling standards.
Growth Catalysts
- Adult-use legalization framework:Missouri's voter-approved constitutional amendment expanded the addressable consumer base beyond registered medical patients, creating dual-track demand for both therapeutic and recreational product lines.
- Extraction technology advancement:Closed-loop hydrocarbon and CO2 systems are enabling concentrate production at scale, satisfying experienced consumers seeking higher bioavailability formats.
- St. Louis-Kansas City corridor concentration:Metropolitan dispensary density and consumer education levels in these urban clusters are generating disproportionate revenue per capita versus rural markets.
Market Restraints
- Input cost volatility:Energy-intensive indoor cultivation faces electricity rate pressure from regional utility providers, compressing margins for operators without solar or efficiency retrofits.
- Municipal zoning fragmentation:Local boards impose patchwork operational constraints on cultivation sites and retail locations, creating supply access gaps in conservative counties.
- Federal banking prohibition:Cannabis remains Schedule I under the Controlled Substances Act, forcing cash-heavy operations and excluding operators from SBA lending and commercial credit facilities.
Strategic Opportunities
- Delivery channel expansion:Suburban markets with restrictive storefront zoning are creating white space for licensed delivery services to capture underserved households.
- Social equity licensing provisions:Pending legislative revisions to Missouri's licensing structure may reserve cultivation and retail permits for communities disproportionately impacted by prior enforcement.
- Full-spectrum product convergence:Medical patients migrating to recreational access are seeking minor cannabinoid formulations, opening formulation differentiation beyond THC-centric SKUs.
Industry Challenges
- Compliance talent scarcity:Missouri operators face acute shortages of professionals versed in DHSS seed-to-sale software, METRC reconciliation, and batch-level recall protocols.
- Testing bottleneck compression:Third-party laboratory capacity constraints are extending product release timelines, forcing inventory carry costs and retail stockout risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missouri Legal Cannabis Market |
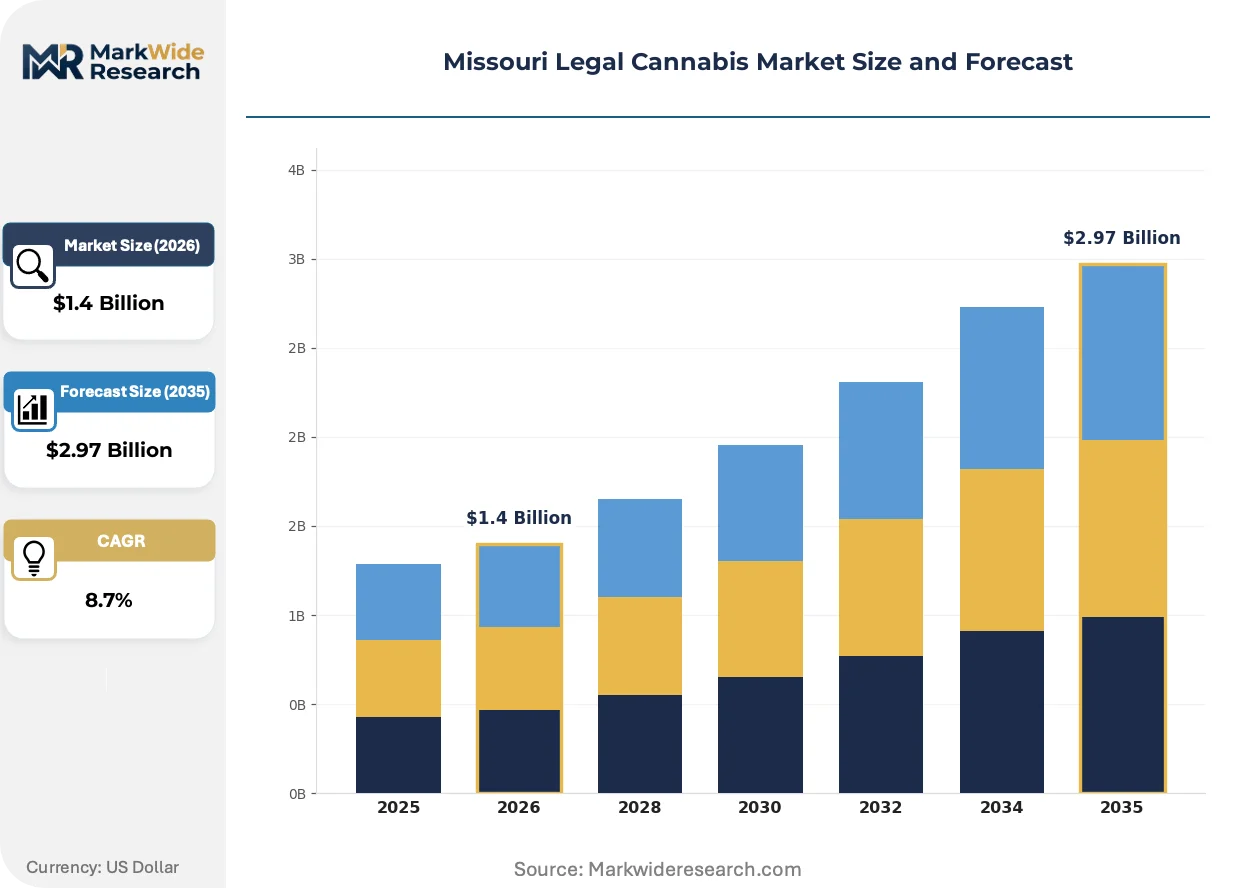
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flower, Edibles, Concentrates, Topicals Customer Type: Recreational Users, Medical Patients, Cannabis Enthusiasts, First-Time Buyers Distribution Channel: Dispensaries, Delivery Services, Online Retail, Markets Form: CBD Oil, Vapes, Tinctures, Pre-rolls |
| Companies Covered | Good Day Farm Missouri, Illicit Gardens, Proper Cannabis, Heya Wellness, Greenlight Dispensary, Flora Farms, CLOVR, Elevate, Organic Remedies Missouri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missouri Legal Cannabis Market Evolving Landscape
Processing technology and regulatory instrumentation are reshaping how Missouri operators convert biomass into shelf-stable products while maintaining compliance with evolving state mandates.
Live resin extraction equipment is miniaturizing. Small-batch processors in Springfield and Columbia are deploying portable closed-loop systems that reduce solvent volume requirements and enable on-site terpene preservation. This technology compression is allowing craft operators to compete with industrial-scale facilities on aromatic fidelity without capital-intensive infrastructure.
Missouri DHSS Division of Medical Cannabis is tightening potency variance thresholds. New rules mandate that labeled cannabinoid content fall within 15% of laboratory-tested values, forcing manufacturers to reformulate edibles and tinctures with narrower dosing bands. Concentrate producers face the steepest compliance burden as high-potency products amplify percentage deviation risks.
Medical patients are reorganizing purchase patterns toward higher-frequency, lower-basket-size transactions. Dispensary loyalty programs and subscription models are displacing bulk purchasing as the dominant retention mechanism. This behavioral shift is most pronounced in Kansas City metro operations, where competitive storefront density enables convenient repeat visitation.
Missouri Legal Cannabis Market Segmentation
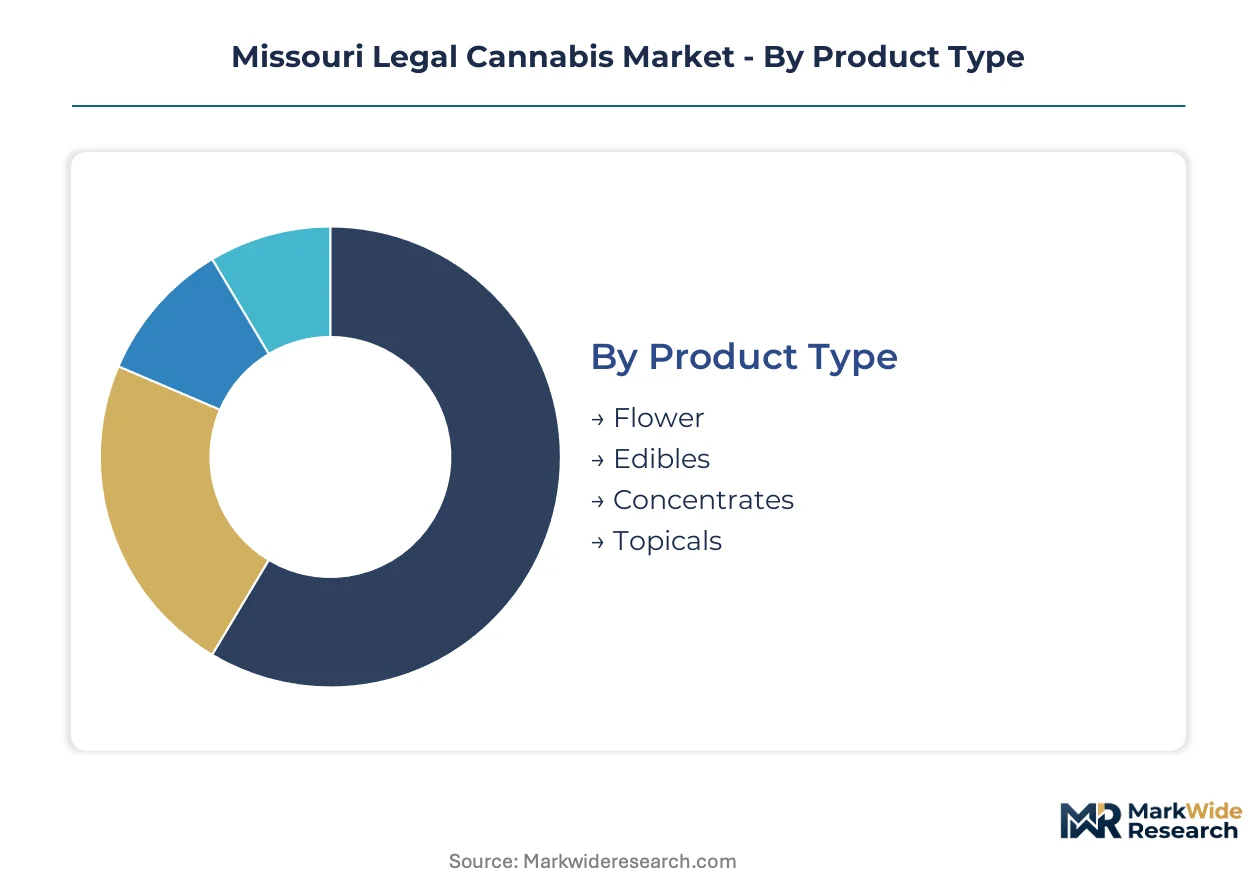
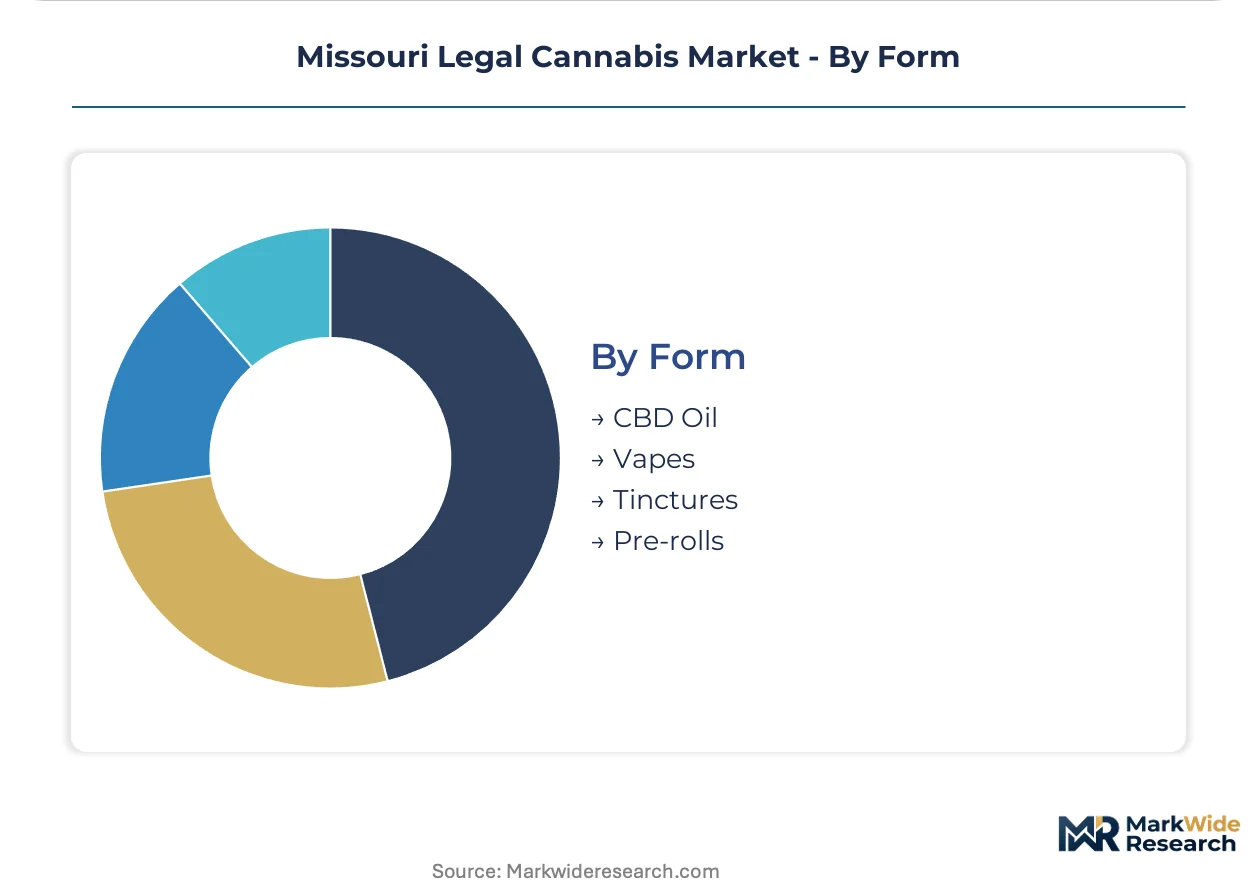
Missouri's legal cannabis market segments along four distinct dimensions that determine channel strategy and margin capture. Product type and distribution channel alignment dictates inventory investment, while customer type and form factor preferences shape formulation priorities for licensed operators navigating DHSS compliance frameworks.
Product Type:
Flower and concentrates flow through dispensary channels with the highest velocity, while edibles and topicals require extended retail education and slower turnover cycles.
- Flower:Dried cured cannabis retains dominant shelf presence across Missouri dispensaries. St. Louis and Kansas City metro stores allocate premium display space to craft cultivators with verified genetics and small-batch curing protocols.
- Concentrates:Hydrocarbon and CO2-extracted oils, waxes, and shatter formats satisfy experienced consumers seeking rapid onset and precise dosing. Live resin variants command price premiums in urban corridors where extraction technology literacy runs highest.
- Edibles:Infused chocolates, gummies, and beverages carry extended onset windows that appeal to discretion-conscious consumers. DHSS potency variance rules force manufacturers toward narrower dosing bands and reformulated legacy SKUs.
- Topicals:Transdermal creams and balms serve localized therapeutic applications without psychoactive effects. Medical patients in suburban Kansas City markets drive repeat purchase frequency for cannabinoid-infused wellness products.
By volume, flower leads. By growth pace, concentrates are expanding most quickly as extraction infrastructure matures across the state.
Customer Type:
Recreational access has rebalanced the customer mix toward first-time and casual users, compressing average basket sizes while expanding total transaction counts.
- Recreational Users:Adult consumers purchasing under constitutional amendment provisions now represent the broadest addressable base. Kansas City metro dispensaries report highest penetration among 25-34 age cohorts seeking social consumption formats.
- Medical Patients:Registered therapeutic users sustain elevated purchase frequency and brand loyalty metrics. These consumers prioritize full-spectrum formulations and minor cannabinoid ratios over THC-centric recreational SKUs.
- Cannabis Enthusiasts:Experienced consumers with sophisticated product knowledge drive concentrate and craft flower demand. Their purchasing patterns concentrate in St. Louis corridor stores with dense competitive storefront environments.
- First-Time Buyers:New entrants post-legalization require educational support and low-dose entry products. Dispensary staff training investments correlate directly with conversion rates in this segment.
Recreational users dominate transaction counts. Medical patients generate superior lifetime value through subscription and loyalty program engagement.
Distribution Channel:
Channel selection determines regulatory burden intensity, with dispensaries absorbing full DHSS seed-to-sale tracking compliance while delivery services navigate municipal zoning fragmentation.
- Dispensaries:Brick-and-mortar retail locations handle the majority of volume under state-issued licenses. St. Louis and Kansas City density clusters enable competitive pricing and convenient repeat visitation patterns.
- Delivery Services:Licensed transport operators capture suburban households where local zoning boards restrict storefront permits. These services face elevated insurance and vehicle compliance costs under DHSS regulations.
- Online Retail:Digital ordering with in-store pickup functions as a convenience layer atop dispensary infrastructure. Pre-order capabilities reduce wait times and enable inventory reservation ahead of high-demand periods.
- Markets:Temporary retail events and pop-up formats operate under restricted licensing windows. These channels serve brand awareness objectives rather than sustained revenue contribution.
Dispensaries capture volume leadership. Delivery services are gaining share fastest in counties with restrictive municipal zoning.
Form:
Form factor selection reflects consumer experience level and consumption context constraints, with inhalable formats dominating recreational preference and sublingual options preferred for medical precision.
- CBD Oil:Hemp-derived and cannabis-derived cannabidiol formulations serve wellness and therapeutic applications. Missouri Department of Agriculture oversight applies to hemp-sourced products, creating dual regulatory pathways.
- Vapes:Cartridge and disposable pen formats offer discretion and rapid onset for mobile consumers. DHSS potency testing mandates and packaging standards have compressed hardware supplier options.
- Tinctures:Sublingual drops enable precise milligram dosing for medical patients and micro-dosing recreational users. Alcohol and oil-based carriers carry distinct shelf stability profiles under state storage regulations.
- Pre-rolls:Machine-rolled and hand-finished joints eliminate preparation friction for immediate consumption. Multi-packs and infused variants command premium positioning in urban dispensary environments.
Vapes lead by current volume contribution. Tinctures are climbing fastest as medical patients reorganize toward precision dosing formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 70 corridor anchors Missouri's cannabis distribution network, connecting cultivation clusters in mid-Missouri to retail density in the state's two major metropolitan zones. This east-west freight spine enables just-in-time inventory replenishment across a market where municipal zoning creates fragmented local access.
St. Louis Metropolitan Corridor
St. Louis city and county dispensaries generate the state's highest per-capita transaction volumes, driven by cross-border Illinois consumers and dense urban population. Missouri DHSS licensing caps in this zone have created intense competition for limited retail permits. Collinsville and East St. Louis satellite markets concentrate delivery logistics operations serving suburban St. Charles and Jefferson counties.
Kansas City Metro Area
Jackson County and surrounding Kansas suburbs sustain elevated medical patient registration rates alongside recreational demand expansion. Local zoning boards in Johnson County, Kansas, maintain restrictive storefront policies, pushing Missouri-side Clay and Platte counties to absorb overflow demand. Independence and Lee's Summit cultivation facilities leverage proximity to Kansas state line consumers.
Springfield-Greene County Hub
Springfield's central geographic position supports wholesale distribution to rural southwest Missouri markets where dispensary density remains sparse. Missouri State University research partnerships anchor minor cannabinoid formulation development for regional processors. Christian and Taney counties maintain prohibitionist zoning, forcing consumers toward Springfield retail or unlicensed alternatives.
Columbia-Jefferson City Axis
Boone County's college-town demographics drive experimentation with novel product formats and micro-dose edibles. Jefferson City hosts concentrated regulatory compliance services and DHSS administrative functions. Callaway County cultivation operations benefit from lower land costs and permissive agricultural zoning relative to metropolitan constraints.
Mid-Missouri Rural Belt
Pettis, Saline, and Cooper counties concentrate greenhouse and outdoor cultivation at scale, supplying biomass to state processors. These jurisdictions compete on production cost rather than retail proximity. Moberly and Marshall processing facilities convert raw material into distillate for statewide distribution.
Missouri Legal Cannabis Market Competitive Landscape
Concentration sits with vertically integrated operators controlling cultivation-through-retail pipelines. The Missouri market exhibits moderate consolidation among license holders, with multi-facility operators capturing disproportionate shelf space in high-traffic corridors. Three strategic archetypes dominate: craft cultivators emphasizing genetics and curing protocols, scale-driven greenhouse operators optimizing unit economics, and retail-focused chains maximizing storefront density. Competitive moves center on license accumulation through municipal zoning navigation and backward integration into proprietary genetics.
Among Missouri-based operators, Good Day Farm Missouri exemplifies the vertically integrated archetype with controlled supply chain infrastructure. Illicit Gardens occupies a position emphasizing craft cultivation differentiation. Proper Cannabis anchors the retail-density strategy through corridor-focused storefront expansion. These three represent distinct competitive vectors rather than direct substitutes, each capturing value at different vertical stages.
| Leading Market Players |
|---|
| Good Day Farm Missouri |
| Illicit Gardens |
| Proper Cannabis |
| Heya Wellness |
| Greenlight Dispensary |
| Flora Farms |
| CLOVR |
| Elevate |
| Organic Remedies Missouri |
| Others |
Value Network & Pricing Analysis
LED lighting retrofits displacing legacy HPS fixtures in Missouri cultivation facilities are simultaneously compressing energy input costs and redistributing production advantage toward operators with grid-scale solar installations in Callaway and Pettis counties. This substitution dynamic is collapsing the historical cost premium of indoor flower and forcing wholesale biomass pricing toward parity between greenhouse and controlled-environment agriculture.
Pricing Analysis
Volume-discount tiering structures separate craft small-batch flower from greenhouse standard grades and outdoor economy biomass. Price differentiation rests on DHSS potency certification variance and verified genetics documentation. Pricing pressure intensifies in standard tiers as greenhouse operators expand square footage. Medical patients demonstrate lowest price sensitivity, while recreational first-time buyers drive aggressive promotional discounting.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time replenishment along Interstate 70 corridors rather than strategic stockpiling given DHSS batch-level tracking mandates. Geographic supply concentration centers on Missouri's mid-state cultivation belt, with supplemental biomass draws from Oklahoma and Illinois processors. Raw material dependencies include fertilizer inputs, climate control equipment, and hydrocarbon extraction solvents. Single-source vulnerability concentrates in laboratory testing capacity. Distribution runs through licensed dispensary networks with emerging delivery service augmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Missouri's legal cannabis market sits at a platform-economics inflection where DHSS seed-to-sale tracking interoperability creates data network effects favoring operators with integrated METRC compliance infrastructure.
For Market Incumbents: Shield market position through backward integration into proprietary genetics libraries and captive extraction capacity. Defensive consolidation should prioritize laboratory testing assets given third-party capacity bottlenecks. The threat of federal rescheduling disrupting banking access makes cash-flow resilience the critical lever. For New Entrants and Emerging Players: Differentiate on minor cannabinoid formulation expertise targeting medical patient migration patterns. White-space concentration sits in suburban delivery corridors where Johnson County zoning restrictions push demand across state lines. A precision-dosing subscription model offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a licensing-maturation phase that favors vertically integrated operators with municipal zoning navigation capabilities. Long-term viability hinges on social equity license accumulation and regulatory compliance technology ownership. The signal to watch is DHSS rulemaking on interstate commerce provisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Genetics | Cultivators with verified strain libraries command shelf-space premiums in St. Louis corridor dispensaries. |
| Laboratory Testing Capacity Acquisition | Third-party bottlenecks extend product release timelines, making captive testing assets strategically valuable. |
| Delivery Infrastructure Expansion | Suburban zoning restrictions in Kansas metro areas create white-space for licensed transport operators. |
| Social Equity License Positioning | Pending legislative revisions may reserve permits for communities impacted by prior enforcement patterns. |
| Minor Cannabinoid Formulation Development | Medical patient migration toward full-spectrum products opens differentiation beyond THC-centric SKUs. |
Research Methodology
A standing panel of cultivation operations directors, DHSS compliance officers, dispensary procurement managers, and third-party laboratory technical leads provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from Missouri DHSS regulatory filings, METRC transaction databases, and municipal zoning board records. Bottom-up cultivation capacity modeling triangulated against top-down dispensary revenue tracking.
Consistency checks validated volume and value outputs against state-licensed facility counts and product category flow data. The analytical framework segmented across product type, customer archetype, distribution channel, and geographic corridor dimensions throughout the projection horizon. CAGRs derived from license issuance trajectories, patient registration trends, and per-capita consumption pattern shifts informed growth trajectory modeling.
Material uncertainties — federal rescheduling decisions, municipal zoning reversals, and laboratory capacity expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory continuity and patient-recreational consumer equilibrium. Revision becomes warranted when federal banking access legislation crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
Africa Medical Cannabis Market
Cannabis/Marijuana
Cannabigerol (CBG) Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market