
 Digital Reading Market | 2026-2036
Digital Reading Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Reading Market Insights
The EU Green Deal is recalibrating institutional procurement standards across European educational systems and public libraries, favoring low-power e-ink hardware and carbon-neutral cloud hosting for digital content distribution. Amazon leverages its vertically integrated Kindle ecosystem and publishing marketplace to sustain dominance in dedicated e-reader hardware. Rakuten Kobo anchors its position through strategic partnerships with independent booksellers and library lending platforms across Canada and multiple European countries. Apple competes by extending its Apple Books service across iPad and iPhone installed bases, emphasizing high-resolution display technology and seamless cross-device synchronization.
Digital reading encompasses the consumption of text-based and audio content through electronic devices, relying on display technologies such as e-ink Carta panels with 300 ppi resolution, LCD and OLED screens, or audio codecs streamed via Bluetooth connectivity. The primary commercial purpose centers on delivering portable, searchable, and network-connected access to books, periodicals, and documents for personal education, professional reference, and entertainment. E-readers and tablets command the largest installed base among device types, though smartphones capture the highest session frequency due to ubiquitous ownership. Audiobooks represent the fastest-expanding content category, driven by commuter consumption and multitasking behaviors, while monthly subscription models concentrate the most predictable revenue pools through recurring user commitments.
The Federal Communications Commission in the United States governs device connectivity standards and electromagnetic emissions for wireless reading hardware, while the European Accessibility Act mandates text-to-speech compatibility and navigability features across e-reading platforms sold in EU member states. China's National Radio and Television Administration oversees content licensing for digital publications, shaping market access for foreign publishers and domestic platforms alike. Stakeholders must monitor evolving interoperability mandates and content localization requirements as regulators treat digital reading infrastructure as critical to literacy policy and cultural sovereignty.
Market Dynamics
The transition from print to digital distribution is restructuring procurement patterns across educational institutions and public library systems, with sustainability mandates and mobile-first consumption habits compressing legacy publishing timelines.
Growth Catalysts
- EU Green Deal procurement criteria:European educational institutions now prioritize low-carbon e-ink hardware and cloud-hosted content delivery, redirecting institutional budgets from print supply chains toward digital infrastructure.
- Audiobook multitasking consumption:Commuter populations and remote workers integrate spoken-word content into daily routines, expanding addressable listening hours beyond traditional reading contexts.
- China's state-backed digital publishing infrastructure:Massive mobile-first reader populations sustain serialized online literature platforms and subscription streaming services at scale unmatched elsewhere.
Market Restraints
- E-ink display supply concentration:Production of high-resolution Carta panels clusters among East Asian component manufacturers, creating vulnerability to capacity constraints and input cost volatility.
- Digital rights management fragmentation:Incompatible encryption standards across platform ecosystems force consumers into single-vendor lock-in, suppressing cross-platform portability demand.
- Screen fatigue and wellness concerns:Extended LCD and OLED exposure triggers regulatory scrutiny over blue-light emissions and pediatric usage guidelines in multiple jurisdictions.
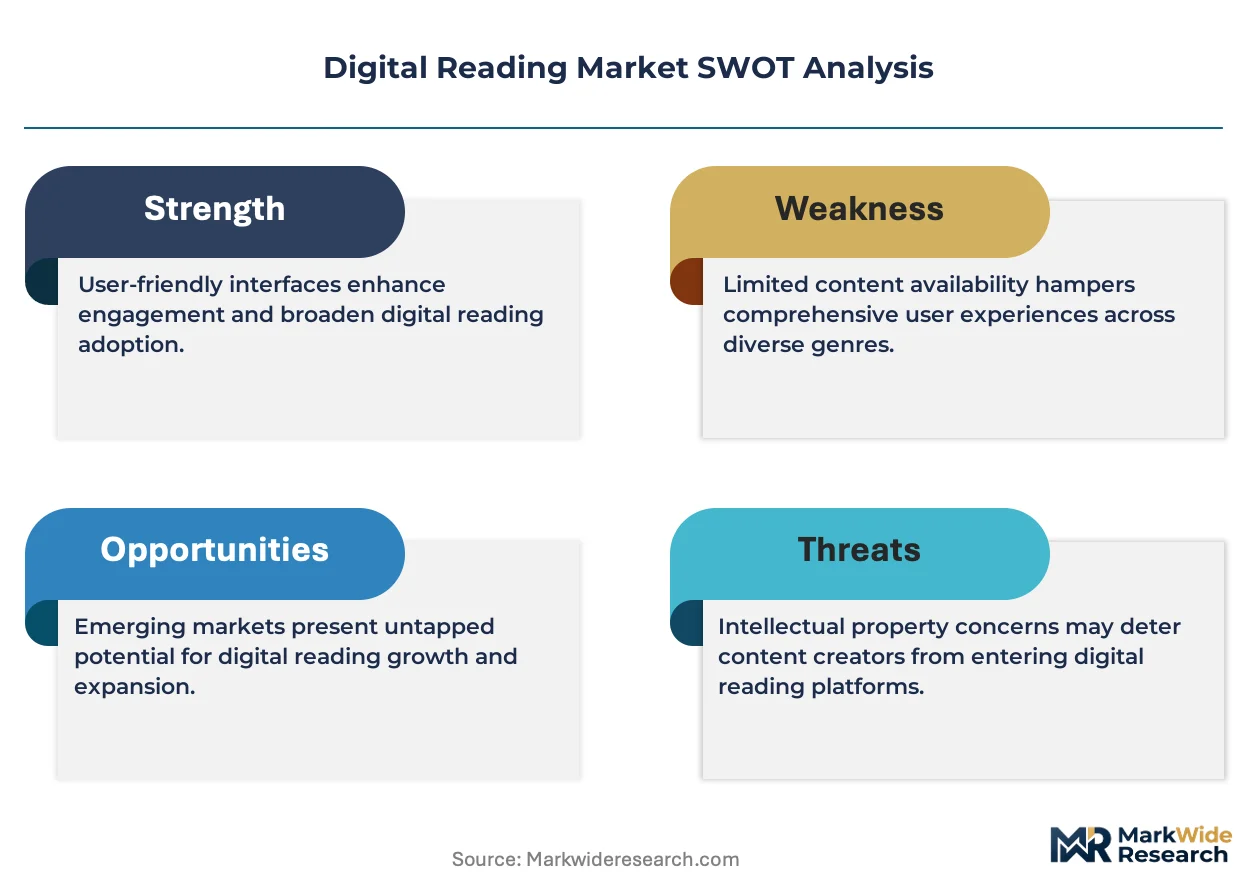
Strategic Opportunities
- India's underpenetrated higher education sector:Public universities and technical institutes show accelerating appetite for licensed e-textbook platforms as national digital literacy campaigns expand.
- Text-to-speech accessibility convergence:Integration of neural voice synthesis with e-ink devices opens compliance-driven procurement channels under the European Accessibility Act.
- Library lending platform integration:Cloud-based digital rights clearing enables frictionless borrowing models that recapture readers otherwise lost to subscription fatigue.
Industry Challenges
- Localization and translation pipeline bottlenecks:Platform operators struggle to scale culturally adapted content libraries fast enough to match geographic expansion timelines.
- Interoperability certification complexity:Divergent national content standards and accessibility mandates multiply compliance engineering costs for cross-border distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Reading Market |
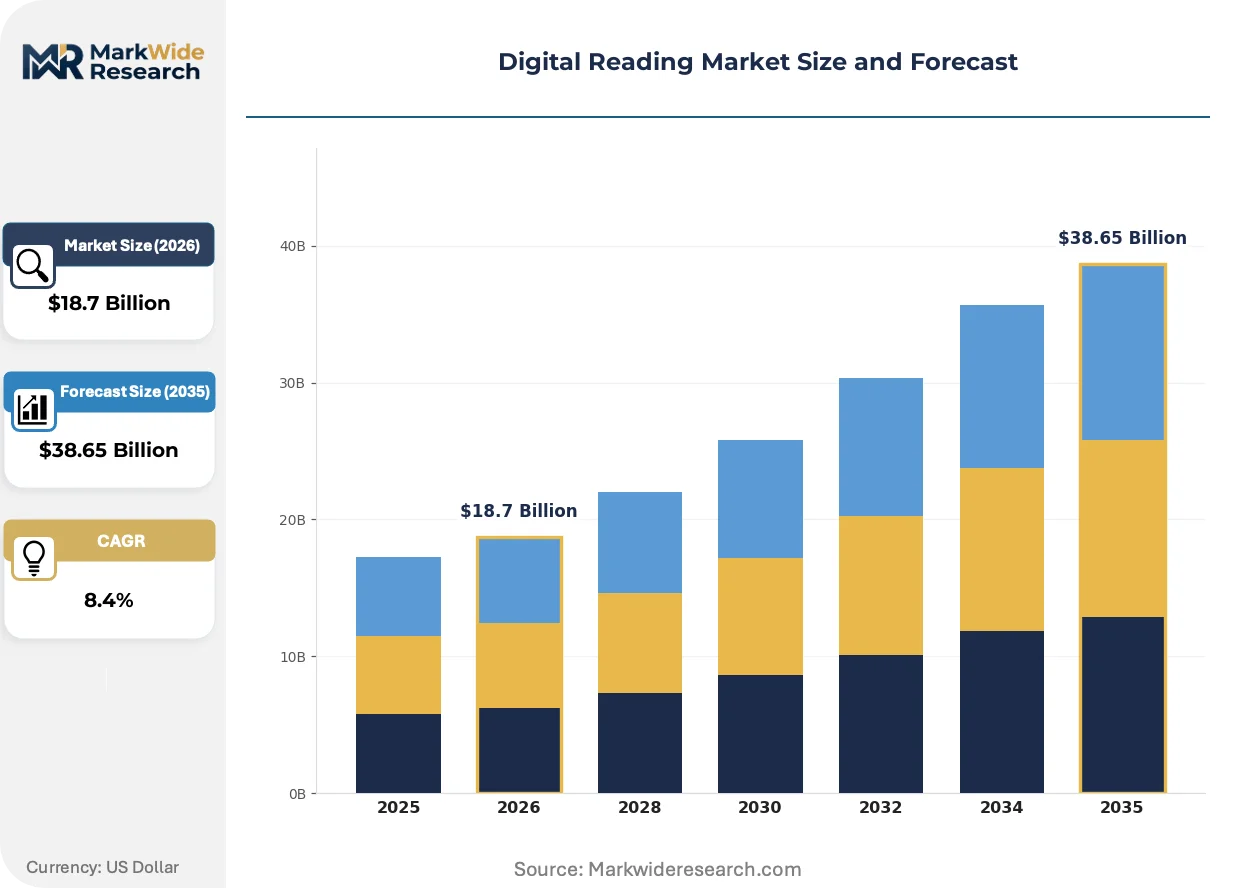
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: E-Readers, Tablets, Smartphones, Laptops Content Type: E-Books, Online Articles, Audiobooks, Magazines User Demographics: Students, Professionals, Casual Readers, Researchers Subscription Model: Monthly Subscription, Pay-Per-View, Free Access, Bundled Service |
| Companies Covered | Amazon, Apple, Google, Rakuten Kobo, Barnes & Noble, Scribd, Wattpad, China Literature, OverDrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Reading Market Trends and Innovations
Display technology evolution and regulatory accessibility mandates are compressing hardware refresh cycles while reshaping how content platforms monetize reader attention across device ecosystems.
Color e-ink Kaleido panels are overtaking monochrome displays in educational and graphic novel segments. K-12 procurement departments in the United States and Western Europe specify color-capable hardware for STEM textbook adoption. This shift is overtaking the historical cost advantage of grayscale e-readers, forcing component suppliers to scale manufacturing capacity for pigment-based electrophoretic films.
REACH substance restrictions and RoHS compliance deadlines in the European Union are tightening material specifications for device casings and battery assemblies. Manufacturers must reformulate flame-retardant plastics and lithium-ion cell chemistries to maintain market access. Premium e-reader product lines destined for EU distribution bear the highest compliance engineering burden, with certification timelines extending hardware release schedules.
Subscription bundling is consolidating individual title purchases into platform-all-you-can-read models. Mass-market readers in China and Southeast Asia now expect serialized content delivered through super-app ecosystems rather than standalone e-reader purchases. This behavioral pivot concentrates revenue predictability with platform operators while compressing per-unit margins for standalone hardware vendors competing on device specs alone.
Digital Reading Market Segmentation
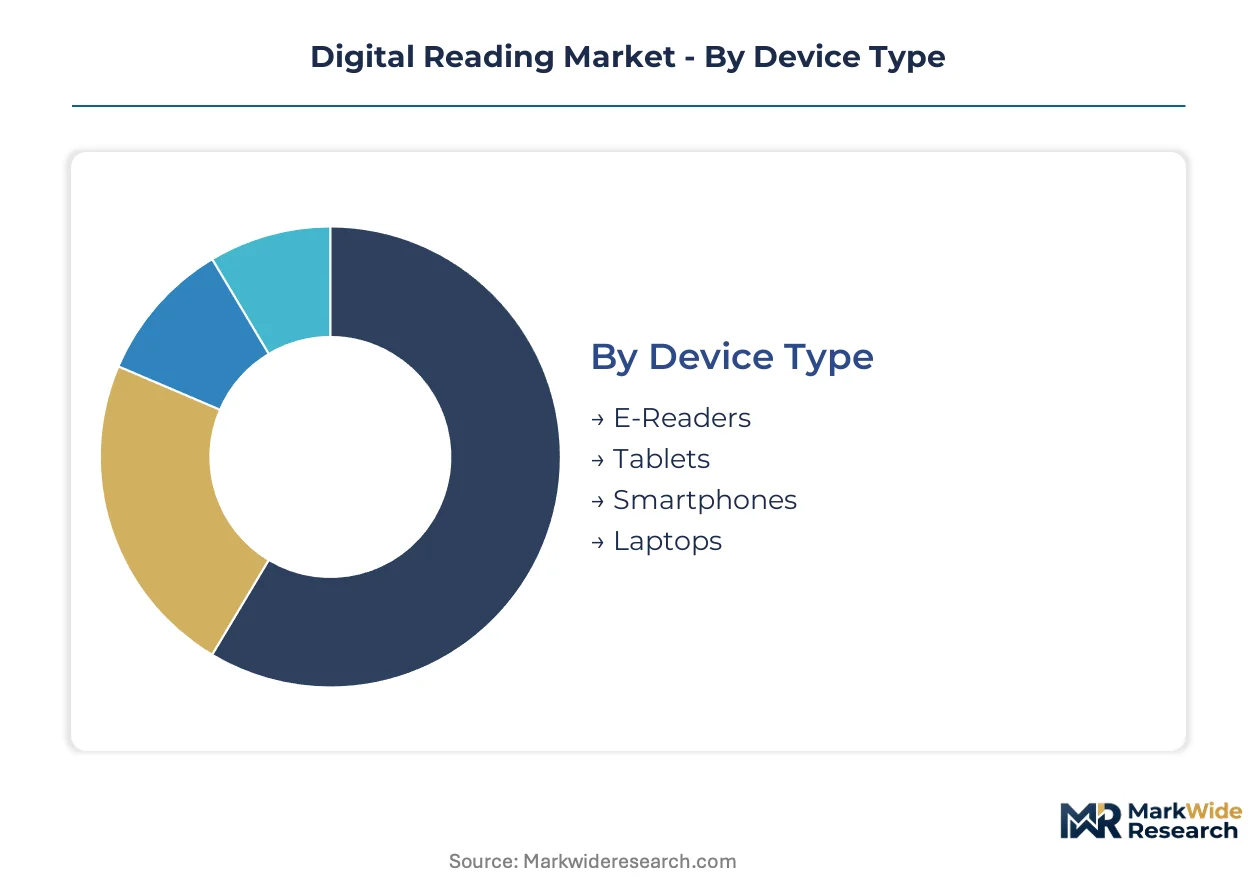
Device specifications and content delivery models determine regulatory exposure and procurement eligibility across institutional and consumer channels. Segmentation reveals where certification burdens cluster and which user groups drive platform monetization strategies.
Device Type:
E-ink hardware faces REACH substance screening and RoHS compliance deadlines in EU distribution, while LCD and OLED tablets trigger FCC electromagnetic certification in US retail channels.
- E-Readers:Carta e-ink panels with 300 ppi resolution dominate dedicated reading hardware. K-12 procurement in Germany and France specifies low-power displays for STEM textbook programs under EU Green Deal sustainability criteria.
- Tablets:LCD and OLED displays support color rendering for graphic novels and educational media. Higher education institutions in the United States prioritize these for interactive coursework despite elevated blue-light exposure concerns from pediatric regulators.
- Smartphones:Capture highest session frequency through ubiquitous ownership. China's mobile-first reader population sustains serialized literature consumption via super-app ecosystems without dedicated hardware investment.
- Laptops:Professional reference and research workflows demand full keyboard navigation. Corporate procurement in Japan favors these for compliance documentation requiring extensive annotation capabilities.
E-Readers sit at the top of the volume ranking, with Smartphones climbing the fastest.
Content Type:
Format selection dictates infrastructure requirements — streaming bandwidth for audio versus storage optimization for text archives.
- E-Books:Reflowable EPUB and fixed-layout PDF formats require DRM encryption compatibility. Library lending platforms in Canada and the United Kingdom prioritize these for frictionless borrowing integration.
- Audiobooks:Neural voice synthesis and Bluetooth codec streaming expand commuter consumption. This category is gaining share fastest as multitasking behaviors reshape addressable listening hours beyond traditional reading contexts.
- Online Articles:Serialized web literature dominates China's state-backed digital publishing infrastructure. Mobile-first delivery through subscription super-apps compresses per-unit margins while concentrating platform revenue predictability.
- Magazines:Color-dependent layout requirements accelerate Kaleido panel adoption. Periodical publishers in Italy and Spain specify pigment-based electrophoretic displays for graphic-heavy content preservation.
E-Books retain the largest installed base, though Audiobooks demonstrate the steepest expansion trajectory.
User Demographics:
Institutional procurement channels favor Students and Researchers for volume licensing, while Professionals command premium pricing tiers.
- Students:K-12 and higher education institutions drive e-textbook platform adoption. India's public universities show accelerating appetite for licensed content as national digital literacy campaigns expand infrastructure.
- Professionals:Corporate reference libraries and continuing education requirements sustain subscription commitments. Legal and medical sectors in Switzerland and Australia prioritize searchable document archives with annotation synchronization.
- Casual Readers:Mass-market consumption concentrates in serialized fiction and entertainment content. Southeast Asian markets exhibit expanding super-app integration for all-you-can-read subscription models.
- Researchers:Academic citation management and archival access requirements demand specialized platform features. Text-to-speech accessibility compliance under the European Accessibility Act opens procurement channels for neural voice synthesis integration.
Students generate the highest institutional volume, with Researchers expanding most quickly through accessibility-mandated procurement.
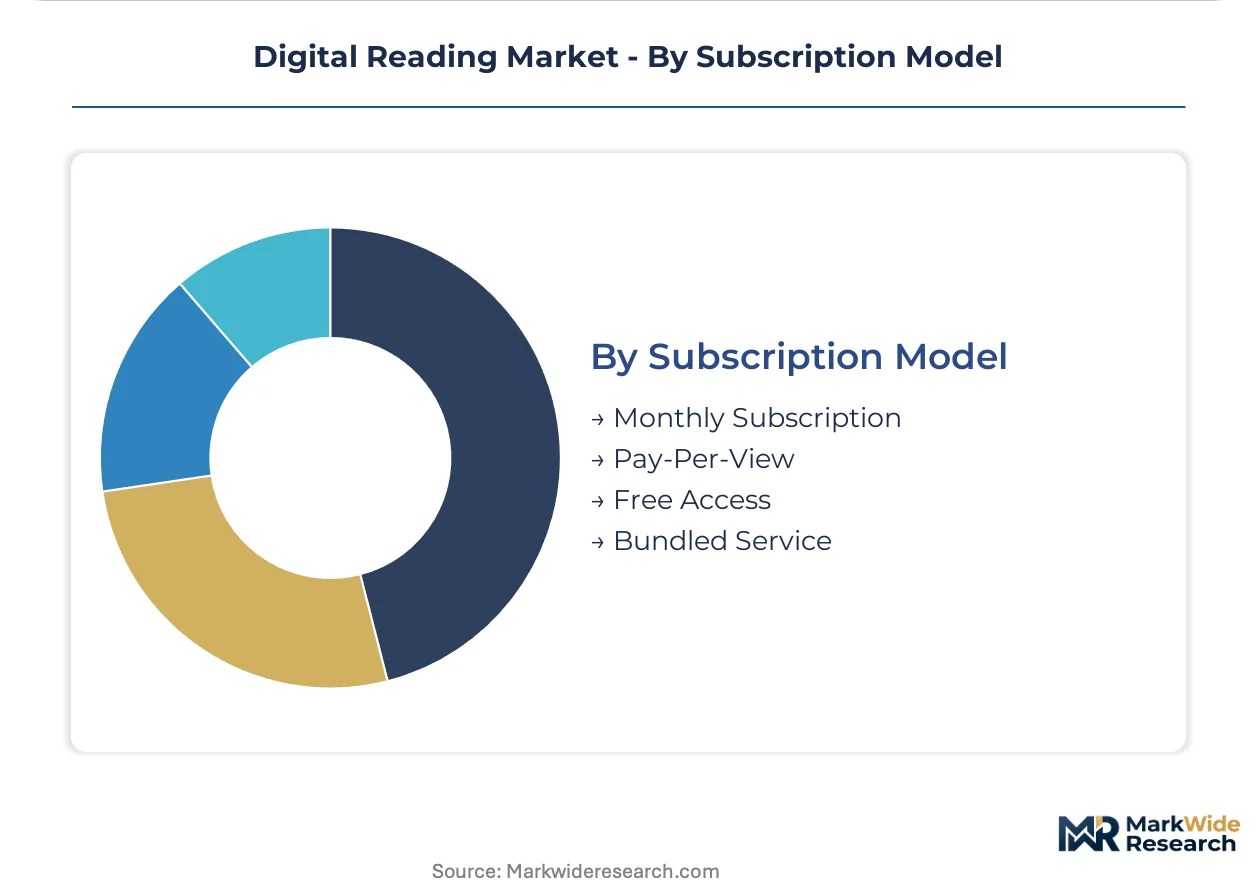
Subscription Model:
Revenue predictability varies directly with recurring commitment structures versus transactional consumption patterns.
- Monthly Subscription:Platform-all-you-can-read models concentrate recurring revenue pools. China's serialized literature ecosystems demonstrate this structure's scalability at unmatched addressable base.
- Pay-Per-View:Individual title purchases persist for premium academic and professional reference content. Per-unit economics favor standalone hardware vendors competing on device specifications.
- Free Access:Ad-supported and public library lending models recapture readers lost to subscription fatigue. Cloud-based digital rights clearing enables frictionless borrowing across Canada and multiple European countries.
- Bundled Service:Telecommunications and super-app ecosystems integrate reading access with broader service portfolios. Southeast Asian markets lead this convergence as mobile-first populations expect content within existing platform relationships.
Monthly Subscription commands the dominant revenue share, while Bundled Service is expanding most quickly through telecommunications integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers and content platform specialists concentrate in Shenzhen, Seattle, and Berlin, anchoring hardware innovation and cloud infrastructure deployment for digital reading ecosystems worldwide.
United States
K-12 districts and higher education institutions drive institutional procurement of e-textbook platforms and library lending systems. The Federal Communications Commission governs device connectivity standards and electromagnetic emissions for wireless reading hardware. Amazon anchors the Seattle-Tacoma corridor with vertically integrated Kindle ecosystem development and publishing marketplace operations.
China
Mobile-first reader populations sustain the world's largest addressable base for serialized online literature and audiobook streaming. The National Radio and Television Administration oversees content licensing for digital publications, shaping market access for domestic and foreign platforms. ByteDance and China Literature anchor Beijing's state-backed digital publishing infrastructure with super-app ecosystem integration.
Germany
Public universities and technical institutes prioritize low-carbon e-ink hardware under EU Green Deal sustainability mandates. REACH substance restrictions and RoHS compliance deadlines tighten material specifications for device casings and battery assemblies. Berlin-Brandenburg hosts Rakuten Kobo's European operations and strategic partnerships with independent booksellers.
India
Public universities and technical institutes show accelerating appetite for licensed e-textbook platforms as national digital literacy campaigns expand infrastructure. The Bureau of Indian Standards sets safety and interoperability benchmarks for imported electronic reading devices. Karnataka's Bangalore cluster concentrates software development talent for platform localization and regional language content pipelines.
United Kingdom
Library lending platforms and academic institutions drive frictionless borrowing integration for digital rights clearing. The European Accessibility Act mandates text-to-speech compatibility and navigability features across e-reading platforms. London anchors OverDrive's international operations and cloud-based distribution partnerships with Canadian and European library systems.
Digital Reading Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across hardware manufacturing and software platform development. The vendor base stratifies between vertically integrated ecosystem operators, hardware-agnostic content distributors, and specialized library service providers. Three archetypes dominate: captive hardware-content integrators, subscription-first platform operators, and institutional licensing specialists. Competitive positioning hardens through exclusive content partnerships and geographic licensing carve-outs rather than pure price competition.
Within the captive ecosystem tier, Amazon exemplifies vertical control from device manufacturing through publishing marketplace operations. Rakuten Kobo occupies a position bridging hardware production and strategic retail partnerships across European and Canadian markets. Among platform-native operators, Scribd represents the subscription-first archetype with all-you-can-read models that concentrate recurring revenue predictability.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Rakuten Kobo |
| Barnes & Noble |
| Scribd |
| Wattpad |
| China Literature |
| OverDrive |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement mandates for low-carbon e-ink hardware and cloud-hosted content delivery are forcing component suppliers to scale pigment-based electrophoretic film capacity and reformulate battery chemistries, compressing margins on entry-level devices while concentrating pricing power with RoHS-certified manufacturers.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive pricing architecture. Monthly subscription models dominate revenue pools through recurring commitments, while standalone hardware vendors compete on device specifications with thinning per-unit economics. Price differentiation hinges on certification grade under REACH and RoHS frameworks plus after-sales service bundling. Cost compression in economy-tier e-readers is intensifying because Kaleido panel adoption raises input costs. Students and casual readers exhibit highest price sensitivity, while legal and medical professionals in Switzerland and Australia accept premium tiers for searchable annotation archives.
Supply Chain Analysis
Freight cost volatility from East Asian component hubs to EU and North American assembly plants is reshaping inventory strategies across e-ink hardware vendors. Production of Carta and Kaleido panels concentrates in China, Taiwan, and South Korea, with lithium-ion cell assembly feeding from Japanese and South Korean suppliers. Raw material dependencies span rare earth elements for display substrates, cobalt for battery cathodes, and flame-retardant plastics for EU-compliant casings. Single-source vulnerability in electrophoretic film manufacturing creates exposure to capacity constraints. Distribution runs through telecommunications bundling partnerships in Southeast Asia and direct retail channels in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Reading Market functions as a stable compounder, with institutional procurement cycles and recurring subscription revenue providing predictable cash generation insulated from short-term consumer volatility.
For Market Incumbents: Anchor defensive positioning through exclusive content partnerships with serialized literature platforms and deepening backward integration into display panel supply. Threats from super-app ecosystem operators in China compress standalone hardware margins, demanding certification investment under the European Accessibility Act to lock in library and university procurement channels.
For New Entrants and Emerging Players: Capture white-space opportunity in India's underpenetrated higher education sector and text-to-speech accessibility compliance markets across EU member states. India's public universities show accelerating appetite for licensed e-textbook platforms. A go-to-market angle through telecommunications bundling partnerships mimics Southeast Asian super-app penetration models.
For Investors and Strategic Acquirers: Asymmetric upside sits with platform-native subscription operators possessing neural voice synthesis capabilities and cloud-based digital rights infrastructure. Long-term viability favors asset-light models with recurring revenue concentration over capital-intensive hardware manufacturers facing RoHS compliance engineering burdens. Watch for inflection signals in India's national digital literacy campaign procurement awards.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Super-app ecosystem embedding recaptures readers lost to subscription fatigue through frictionless access. |
| Accessibility Certification | European Accessibility Act compliance opens procurement channels for neural voice synthesis integration in e-ink devices. |
| Backward Integration | In-house production of pigment-based electrophoretic films reduces exposure to East Asian component supply volatility. |
| Geographic Expansion | India's higher education sector offers accelerating appetite for licensed e-textbook platforms as infrastructure expands. |
| Strategic Partnership | Library lending platform alliances enable frictionless borrowing models across Canada and European public systems. |
Research Methodology
Coverage spans the United States, China, Germany, India, and the United Kingdom, with primary inputs from each market cluster. The research combines structured interviews with e-textbook platform executives, university procurement officers, library systems administrators, and display component sourcing managers with secondary validation from FCC filings, EU Green Deal implementation documents, and China's National Radio and Television Administration licensing records. Bottom-up device shipment modeling and top-down content revenue aggregation provide triangulation across independent analytical paths.
Granularity-level framing segments the market by device type, content format, user demographic, and subscription model, with regional regulatory clusters treated as distinct forecast dimensions. CAGRs derive from installed base penetration curves and institutional procurement cycle analysis across the projection horizon. Specific inputs include K-12 adoption timelines under EU sustainability mandates and China's state-backed digital publishing infrastructure deployment schedules.
Regulatory enforcement variance, component supply disruptions, and currency translation effects are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about procurement budget trajectories and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Egypt Book Services Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Digital Comics Market
Digital Publishing
Global E-Book Market
Digital Publishing
Editor App Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Comic Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
US Newspaper Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Japan Catalog Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Book Publishers Market
Digital Publishing
France Catalog Market