
 Digital Newspapers and Magazines Market | 2026-2036
Digital Newspapers and Magazines Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Newspapers and Magazines Market Intelligence
The unbundling of content into article-level access is decoupling reader choice from traditional full-issue subscriptions. The New York Times Company leverages its strong brand to drive direct subscriptions for its premium journalism. In contrast, Alphabet Inc. dominates content discovery and aggregation through its extensive search and news platforms. Apple Inc. positions itself with a bundled service, Apple News+, which aggregates content from numerous publishers.
Digital newspapers and magazines encompass the electronic distribution of periodical content through web browsers, dedicated mobile applications, and email clients. These products utilize formats like HTML5 and interactive PDFs to deliver text, images, and multimedia. Freemium and ad-supported subscription models are expanding audience reach, while annual plans secure recurring revenue. Within content types, specialized Finance publications often command higher subscription premiums compared to general News.
Europe's GDPR dictates how publishers manage user data for personalization and advertising, impacting revenue from ad-supported models. Concurrently, copyright frameworks in countries like the United States and Canada define fair use and syndication rights. The central strategic decision for publishers involves balancing direct reader revenue against the scale offered by third-party aggregation platforms.
Market Dynamics
The central dynamic is the strategic conflict between pursuing direct reader revenue via premium subscriptions and leveraging the scale offered by third-party content aggregation platforms, which often control discovery.
Growth Catalysts
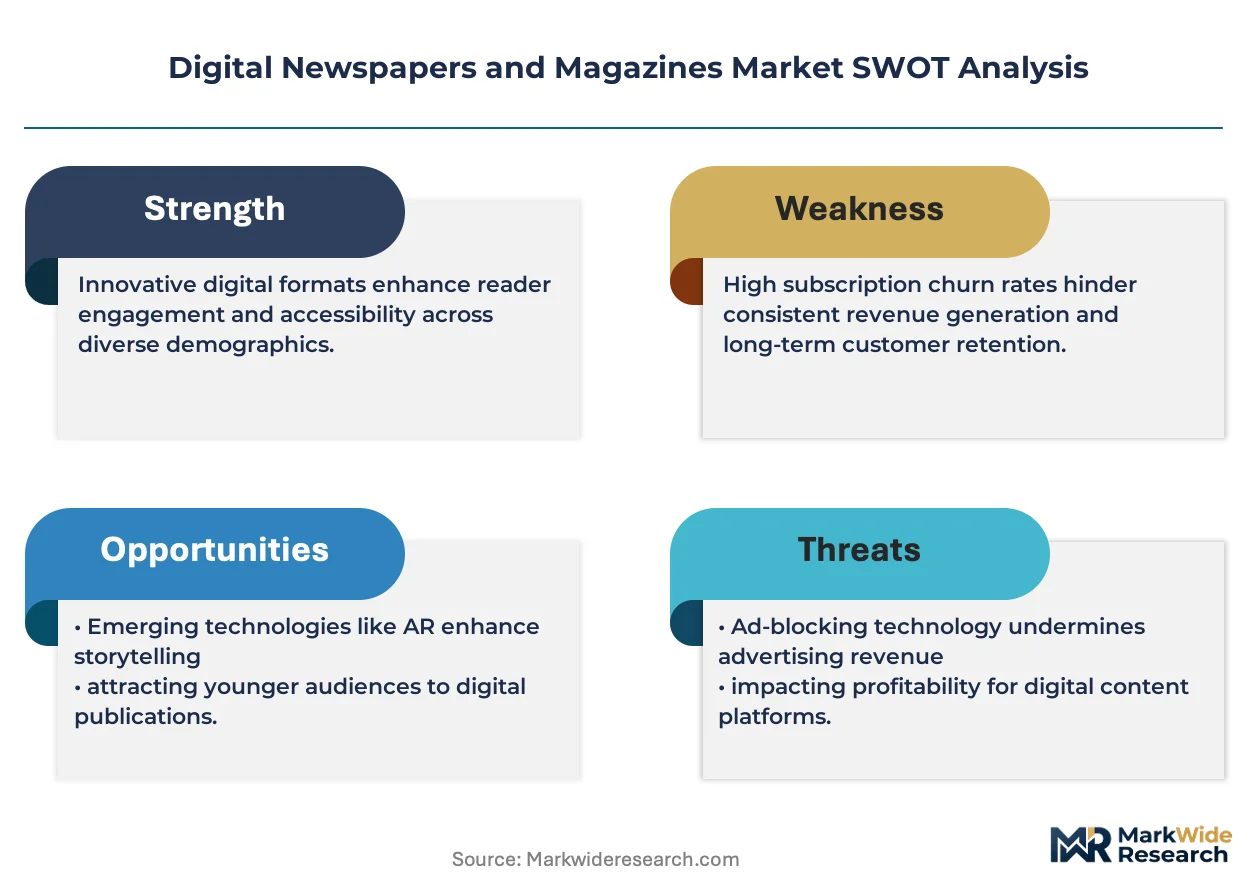
- AI Personalization:The integration of artificial intelligence for personalized content recommendations enhances user engagement, particularly for Professionals requiring curated, real-time information.
- Emerging Economies:Expanding internet access and smartphone use in digital economies like India create vast new audiences for mobile-first news consumption.
- Freemium Models:Adoption of freemium and metered paywalls allows publishers to attract a wide audience and convert engaged readers into paying subscribers.
Market Restraints
- Data Privacy Regulation:Europe's GDPR restricts user data collection for targeted advertising, impacting revenue for publishers who rely on ad-supported models.
- Substitution Threat:The prevalence of free, user-generated content and news feeds on social media platforms presents a direct substitute for paid journalism.
- Ad-Blocking Technology:Widespread use of ad-blocking software by consumers directly reduces a primary revenue stream for many digital news and magazine publishers.
Strategic Opportunities
- Niche Verticals:Developing hyper-specialized B2B or finance publications allows publishers to command higher subscription premiums from dedicated professional audiences.
- Multimedia Integration:Incorporating native audio and video formats, such as podcasts and short-form video, into articles increases reader engagement and time-on-page.
- Alternative Distribution:Utilizing closed messaging platforms and niche professional networks offers a new channel for curated content distribution to highly targeted audiences.
Industry Challenges
- Syndication Complexity:Publishers face difficulties navigating complex content syndication rights and fair use interpretations when dealing with large-scale aggregation platforms.
- Data Science Talent Gap:A shortage of data scientists and audience analysts hinders the ability to effectively use reader data to inform subscription strategies.
- Legacy System Integration:Integrating new subscription and analytics platforms with older, proprietary content management systems creates significant technical hurdles for established publishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Newspapers and Magazines Market |
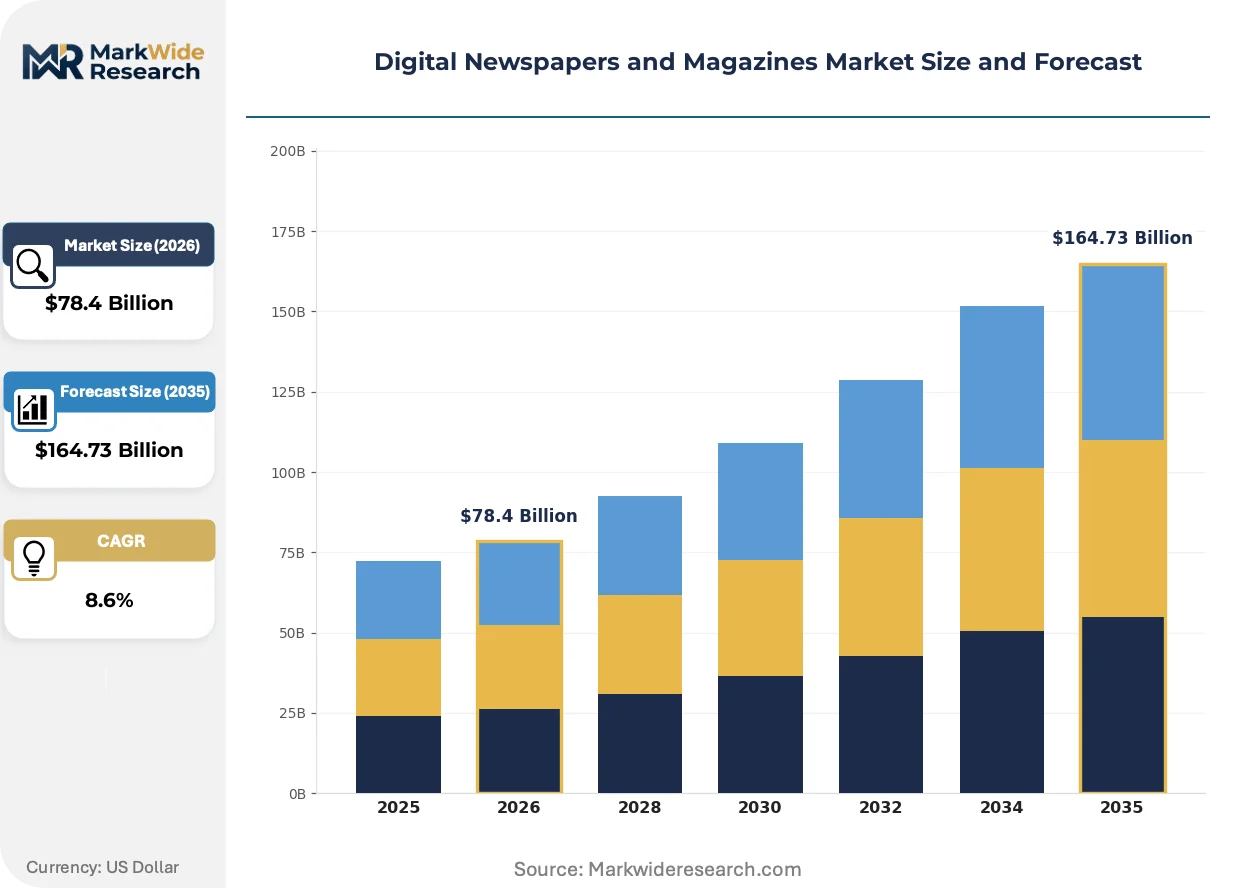
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Model: Monthly, Annual, Freemium, Ad-Supported Content Type: News, Lifestyle, Sports, Finance Delivery Method: Web, Mobile App, Email Newsletter, Social Media Target Audience: Professionals, Students, General Public, Niche Interests |
| Companies Covered | The New York Times Company, Condé Nast, Alphabet Inc., Axel Springer SE, Comcast Corporation, Amazon.com, Inc., News Corporation, Bloomberg L.P., Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Newspapers and Magazines Market Strategic Shifts & Innovations
Publisher strategies are undergoing a re-evaluation of content monetization and user engagement. Focus is shifting from sheer audience volume towards cultivating direct relationships and maximizing reader revenue through enhanced digital products and experiences.
Generative AI is being adopted for content summarization, headline testing, and creating article drafts. Newsrooms are implementing these tools to increase content velocity and personalize article recommendations for individual readers. This technology is unifying disparate reader data points, such as reading history and topic preferences, into cohesive profiles that drive dynamic paywalls.
The European Union's Directive on Copyright in the Digital Single Market establishes new rights for press publishers. This framework requires online platforms like news aggregators to obtain licenses for reusing content, altering revenue-sharing models. Publishers in EU member states are most affected, prompting new negotiations with large tech platforms over content licensing fees.
A significant behavioral shift is the consumer move away from full-issue subscriptions toward article-level access. This trend disrupts the traditional bundled model, with readers using aggregators or publisher-specific 'day passes' for specific stories. This pattern is most visible in general news consumption among younger demographics in the United States and Canada.
Digital Newspapers and Magazines Market Segmentation
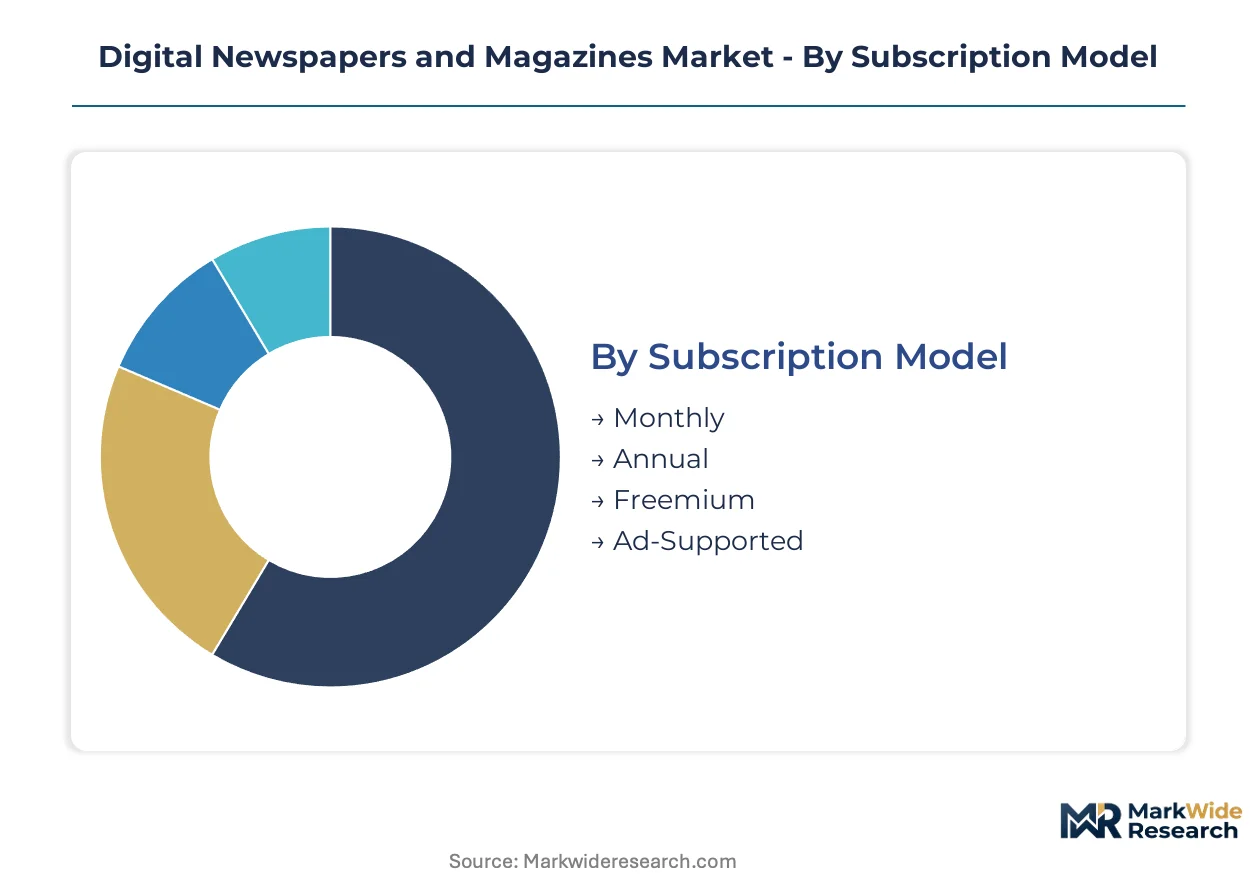
Segmentation provides a critical framework for understanding the diverse revenue streams and audience engagement strategies within the digital newspapers and magazines market. Analyzing these distinct segments helps publishers optimize content delivery, personalize user experiences, and refine monetization models to capture specific reader value.
Subscription Model:
The digital publishing landscape differentiates significantly based on how content is monetized, creating a clear split between models prioritizing broad audience reach and those focusing on premium content revenue.
- Freemium:This model offers basic content free of charge, while premium features, exclusive articles, or an ad-free experience require a paid subscription. It effectively converts casual readers into paying subscribers by demonstrating value upfront. Demand concentrates in emerging digital economies like India, driven by mobile-first access and a large user base.
- Annual:Subscribers commit to a full year of access, often at a discounted rate compared to monthly plans. This model secures predictable recurring revenue and cultivates long-term subscriber loyalty. Demand concentrates in mature media markets such as the United States, supporting the financial stability of premium journalism.
- Monthly:This model provides flexible access to content on a recurring basis, appealing to readers seeking shorter commitments without long-term contracts.
- Ad-Supported:Content is provided to users without direct payment, with revenue generated primarily through display advertising and programmatic ad sales.
Today's leader: Freemium. Tomorrow's challenger: Annual.
Content Type:
Content type directly influences reader value perception and the potential for specialized monetization, ranging from broad appeal to highly specific information needs.
- Finance:Specialized publications deliver real-time market data, investment analysis, and expert commentary for financial professionals. This content commands higher subscription premiums from users requiring critical, timely information for business decisions. Demand concentrates among financial professionals in global economic centers like New York and London.
- News:This segment encompasses general current events, investigative journalism, and breaking stories across various topics. It attracts a broad readership, often leveraging established brand strength for direct subscriptions. Demand is widespread across all demographics in countries like the United States and Canada.
- Lifestyle:This category covers topics such as fashion, travel, health, and home decor, engaging readers with aspirational and practical content.
- Sports:This segment delivers scores, in-depth analysis, and commentary for various athletic events, appealing to dedicated fan bases.
Finance content represents the fastest-growing trajectory due to its high-value, niche audience, while News maintains foundational market presence.
Delivery Method:
The method of content delivery shapes user experience and accessibility, catering to diverse consumption habits across various digital platforms.
- Mobile App:Dedicated applications offer optimized interfaces, push notifications, and offline reading capabilities for smartphones and tablets. This method enhances user engagement and provides a frictionless reading experience. Demand is significant in emerging economies like India, driven by high smartphone penetration.
- Web:Content is accessed via web browsers on desktops, laptops, and mobile devices, offering broad compatibility and discoverability. This remains a primary channel for content consumption globally, particularly for general news. Demand remains strong globally for general news consumption.
- Email Newsletter:Curated content and updates are delivered directly to subscriber inboxes, fostering direct reader relationships and habit formation.
- Social Media:Articles and updates are disseminated through platforms like Facebook, X, and LinkedIn, driving traffic and expanding audience reach.
Mobile app delivery continues to evolve rapidly, driven by user preference for convenience, while web access remains a foundational channel.
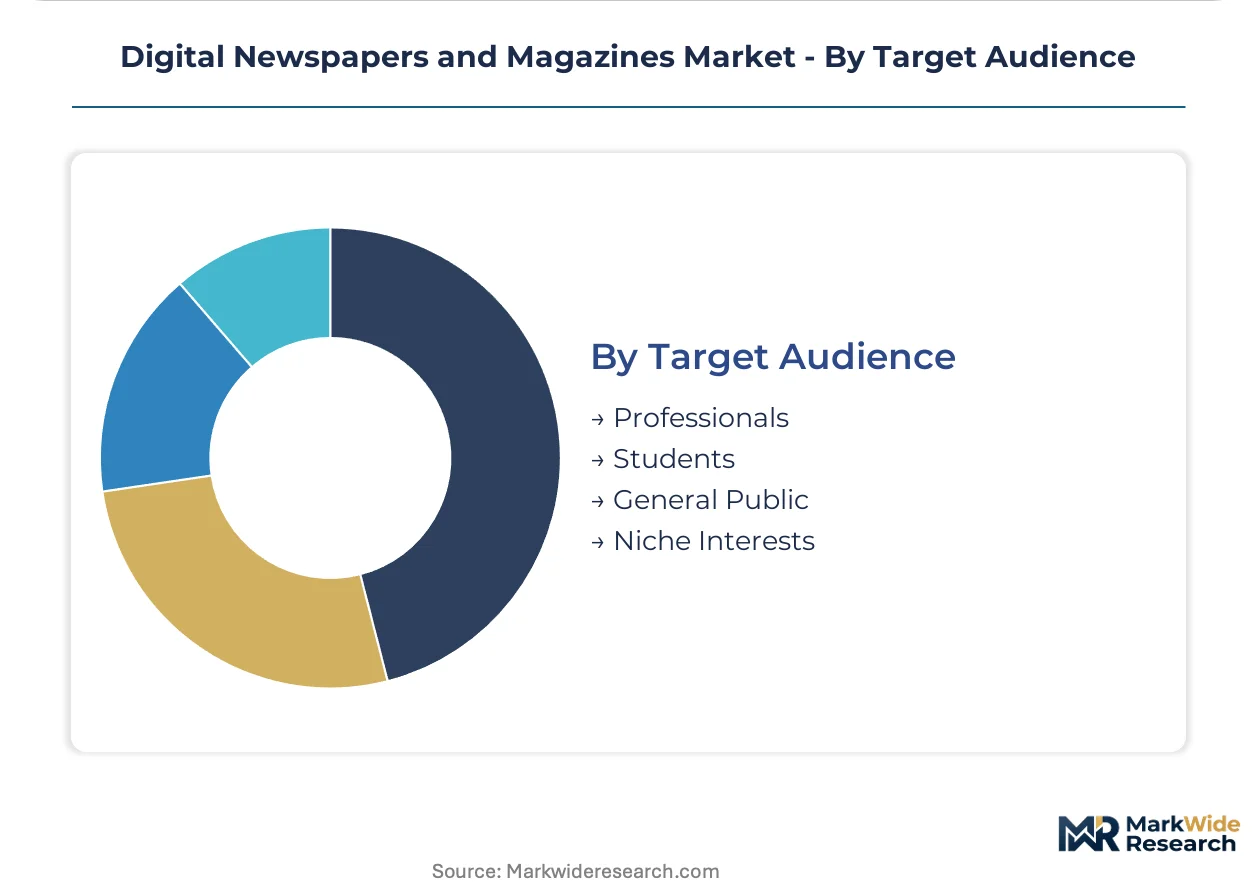
Target Audience:
Target audience segmentation allows publishers to tailor content and pricing strategies, ranging from broad appeal to highly specialized and premium user groups.
- Professionals:This segment comprises individuals who require specialized, real-time information and in-depth analysis for their work. Publishers command higher subscription premiums from this audience for critical industry insights. Demand concentrates in sectors like finance and technology across mature markets.
- General Public:This broad consumer base seeks everyday news, entertainment, and general information across a wide array of topics. It represents the largest volume of readers, often accessed through freemium or ad-supported models. Demand is ubiquitous across all geographies.
- Students:This group accesses educational content, academic journals, or news for research, learning, and current affairs awareness.
- Niche Interests:These are highly specific groups seeking content on particular hobbies, industries, or cultural topics, often willing to pay for specialized coverage.
Targeting professionals offers significant strategic value due to higher revenue potential, while the general public drives overall audience scale and reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital newspapers and magazines market first scaled in the United States, driven by early internet adoption and a robust media landscape. This initial growth established foundational models for digital content distribution and monetization. Today, diverse regional dynamics influence market expansion and content consumption patterns.
United States
Strong demand for premium journalism and specialized financial content drives revenue in the United States. Federal copyright frameworks like the Digital Millennium Copyright Act define content syndication rights for publishers. Major media hubs like New York City and Washington D.C. concentrate both content production and professional audiences seeking real-time information.
India
Expanding internet access and widespread smartphone use are accelerating mobile-first news consumption in India. The Telecom Regulatory Authority of India (TRAI) oversees digital content distribution policies. Rapid urbanization in cities such as Mumbai and Bangalore fuels a large, digitally native audience for freemium models.
Germany
A mature media market, Germany emphasizes data privacy and direct reader relationships for digital publications. The General Data Protection Regulation (GDPR) significantly influences publisher strategies for user data management. Berlin and Munich serve as key centers for media innovation and digital publishing ventures.
Canada
Demand for local news and diverse content drives digital newspaper and magazine subscriptions across Canada. Copyright frameworks in Canada, similar to those in the United States, shape fair use and content licensing agreements. Toronto and Montreal are significant cultural and media hubs, fostering a dynamic digital publishing ecosystem.
Japan
High digital literacy and a preference for mobile content consumption characterize the Japanese market. The Ministry of Internal Affairs and Communications (METI) guides digital media policies and internet infrastructure development. Tokyo, as a global economic center, sees strong demand for specialized business and financial digital publications.
Digital Newspapers and Magazines Market Key Industry Players
Premium-margin players sit above commodity-margin players across content quality and specialization within the digital newspapers and magazines market. The industry structure shows a clear delineation between traditional publishers adapting to digital and technology companies aggregating content. Strategic archetypes include established media brands, content aggregators, and bundled service providers. Dominant competitive moves involve portfolio diversification into multimedia and strategic partnerships for content distribution.
Within the established media brand archetype, The New York Times Company exemplifies a publisher leveraging its strong brand for direct subscriptions. Alphabet Inc. occupies a position as a dominant content aggregator, controlling extensive search and news platforms for discovery. Apple Inc. represents a bundled service provider, offering aggregated content through its Apple News+ platform to its device ecosystem.
| Leading Market Players |
|---|
| The New York Times Company |
| Condé Nast |
| Alphabet Inc. |
| Axel Springer SE |
| Comcast Corporation |
| Amazon.com, Inc. |
| News Corporation |
| Bloomberg L.P. |
| Apple Inc. |
Cost & Logistics Intelligence
Data science talent concentration in specific tech hubs such as Silicon Valley and Bangalore impacts development costs for AI personalization, influencing premium subscription pricing. This labor-cost differential creates varied pricing tiers across global markets.
Pricing Analysis
Freemium and subscription models represent the dominant pricing structures in the digital content market. Price differentiation drivers include content specialization, brand reputation, and the provision of an ad-free experience. Pricing softness stems from the prevalence of free user-generated content and widespread ad-blocking technology. The General Public segment is most price-sensitive, while Professionals demonstrate the least sensitivity for critical niche content.
Supply Chain Analysis
Dual-sourcing requirements for content creation talent ensure resilience against regional disruptions. Content creation talent concentrates in major media hubs like New York, London, and Berlin, alongside emerging digital economies such as India. High-quality journalism, specialized data, and AI development talent constitute key inputs for digital publications. Regulatory restrictions on user data management, exemplified by Europe's GDPR, pose a structural supply chain risk. Digital distribution runs primarily through web platforms, dedicated mobile applications, and third-party aggregation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital content market presents a geographic-arbitrage play, leveraging lower content creation costs in emerging economies like India against higher subscription revenues in mature markets such as the United States. This differential allows for varied monetization strategies.
For Market Incumbents: Deepen direct reader relationships through personalized content and exclusive access. Incumbents face a threat from content aggregators controlling discovery, necessitating investment in proprietary content management systems. Enhance brand premium by focusing on investigative journalism and data-driven insights. Cultivate long-term subscriber loyalty with annual plans.
For New Entrants and Emerging Players: Niche professional networks offer a direct channel for highly specialized content, targeting underserved B2B segments. The student demographic represents a penetrable segment for educational or career-focused digital publications. A freemium go-to-market angle can attract a broad audience before converting them to paid subscribers. Focus on mobile-first delivery in high-growth regions.
For Investors and Strategic Acquirers: Technology platforms are the most active acquirers in this space, seeking to expand content libraries and user bases over the long term. Acquisition targets include specialized content publishers with strong professional audiences or advanced AI personalization capabilities. A signal to watch is the shift in content licensing models driven by EU copyright directives. Monitor user engagement metrics for acquisition viability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Personalization | Enhances user engagement for professionals requiring curated information. |
| Niche Content Vertical Development | Commands higher subscription premiums from dedicated professional audiences. |
| Direct-to-Consumer Subscription Models | Cultivates reader loyalty and secures recurring revenue streams. |
| Multimedia Content Integration | Increases reader engagement and time-on-page through audio and video. |
| Content Licensing Negotiations | Establishes new revenue-sharing models with large tech platforms. |
Research Approach
Bottom-up reader segment modeling reconciled against top-down publisher revenue tracking forms the analytical core of this study. Primary interviews included content strategists, data scientists, digital editors, and platform executives. Secondary validation leveraged public company filings, media industry reports, and regulatory documents from TRAI and the METI. This approach triangulates market dynamics and growth trajectories.
Historical trendline analysis informed the projection of market expansion across the analysis window. Segmentation dimensions modeled included subscription model, content type, delivery method, and target audience. Compound annual growth rates were derived through a regression analysis of past performance and future demand indicators. Key forecast inputs included internet penetration rates and smartphone adoption.
The model assumes a particular technology adoption path; alternative pathways for generative AI integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer behavioral shifts. Deviation in content monetization strategies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
France Catalog Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Digital Reading Market
Digital Publishing
Comic Book Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Global E-Book Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
News and Magazines App Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
US Newspaper Market
Digital Publishing
Digital Comics Market