
 GCC Commercial Printing Market | 2026-2036
GCC Commercial Printing Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Commercial Printing Market Intelligence
Saudi ink formulation capacity is hardening as local producers respond to import substitution mandates. Toyo Ink leverages its regional blending facilities to supply packaging converters across the Eastern Province. Sun Chemical anchors the premium segment with high-performance UV-curable systems for luxury goods. Siegwerk competes aggressively in the food-compliant ink niche, where Gulf regulators enforce strict migration limits.
GCC commercial printing encompasses the mass reproduction of text and images on paper, board, film, and flexible substrates using mechanical or digital processes, typically at resolutions of 300–2400 dpi for commercial-grade output, serving brand communication, product identification, and information dissemination across retail, industrial, and publishing channels. Offset printing retains dominant share in long-run magazine and book work, though margin compression from overcapacity in Dubai and Jeddah has pushed converters toward digital workflows for shorter runs. Digital printing represents the fastest-expanding technology segment, with inkjet systems capturing promotional and variable-data applications as brands demand shorter lead times and personalization at scale.
Emirates Authority for Standardization and Metrology (ESMA) mandates G-Mark certification for printed materials entering UAE consumer channels, while Saudi Standards, Metrology and Quality Organization (SASO) enforces SABER registration for imported packaging substrates, effectively filtering non-compliant suppliers from Gulf procurement lists. The region's national quality infrastructure bodies are aligning with Gulf Standardization Organization (GSO) technical regulations for food-contact materials, raising barrier-to-entry for ink and coating formulations lacking toxicological clearance. Stakeholders must monitor how evolving Extended Producer Responsibility frameworks in the UAE and Saudi Arabia reshape substrate specifications and recycling compliance costs across the print value chain.
Market Dynamics
Digital inkjet adoption is compressing traditional offset run lengths across Gulf packaging converters, while SABER and ESMA compliance requirements are filtering substrate and ink suppliers from cross-border procurement channels.
Growth Catalysts
- SASO SABER Registration Mandate:Saudi Arabia's import conformity platform is accelerating local ink blending investments as foreign suppliers face documentation barriers for packaging substrates entering Riyadh and Jeddah industrial zones.
- Food-Contact Migration Limits:Gulf Standardization Organization technical regulations for printed materials touching consumables are pushing converters toward certified low-migration ink systems in dairy and confectionery packaging applications.
- Retail Hub Concentration:Dubai's logistics corridors and Riyadh's retail expansion are generating sustained large-format and label print volumes for FMCG brand owners.
Market Restraints
- Petrochemical Input Volatility:Solvent and resin costs for UV-curable and conventional offset inks fluctuate with regional feedstock pricing, compressing converter margins on fixed-price annual contracts.
- Equipment Capex Concentration:High-speed inkjet press installations require seven-figure dollar commitments, limiting digital adoption to well-capitalized groups with multi-year amortization capacity.
- Substrate Import Dependency:Coated paper and specialty films for premium packaging rely heavily on Asian and European mill supply, exposing Gulf converters to freight rate spikes and customs clearance delays.
Strategic Opportunities
- Kuwait and Bahrain Penetration:These smaller GCC markets show underdeveloped commercial print infrastructure relative to Saudi Arabia and UAE, offering first-mover positioning for digital workflow specialists.
- Extended Producer Responsibility Frameworks:Emerging EPR regulations in UAE and Saudi Arabia will mandate recyclable substrate specifications, creating service revenue streams for converters offering design-for-recycling consultation.
- Variable-Data Personalization:Inkjet technology is converging with CRM database integration to enable individualized packaging runs for loyalty programs and regional promotional campaigns.
Industry Challenges
- Color Management Specialist Scarcity:Gulf technical institutes produce insufficient ICC profiling and spectrophotometry technicians to support expanding digital press fleets.
- Legacy Prepress Integration:Hybrid workflows combining conventional plate-making with digital front-ends generate file-handling errors and proofing mismatches that delay job turnaround.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Commercial Printing Market |
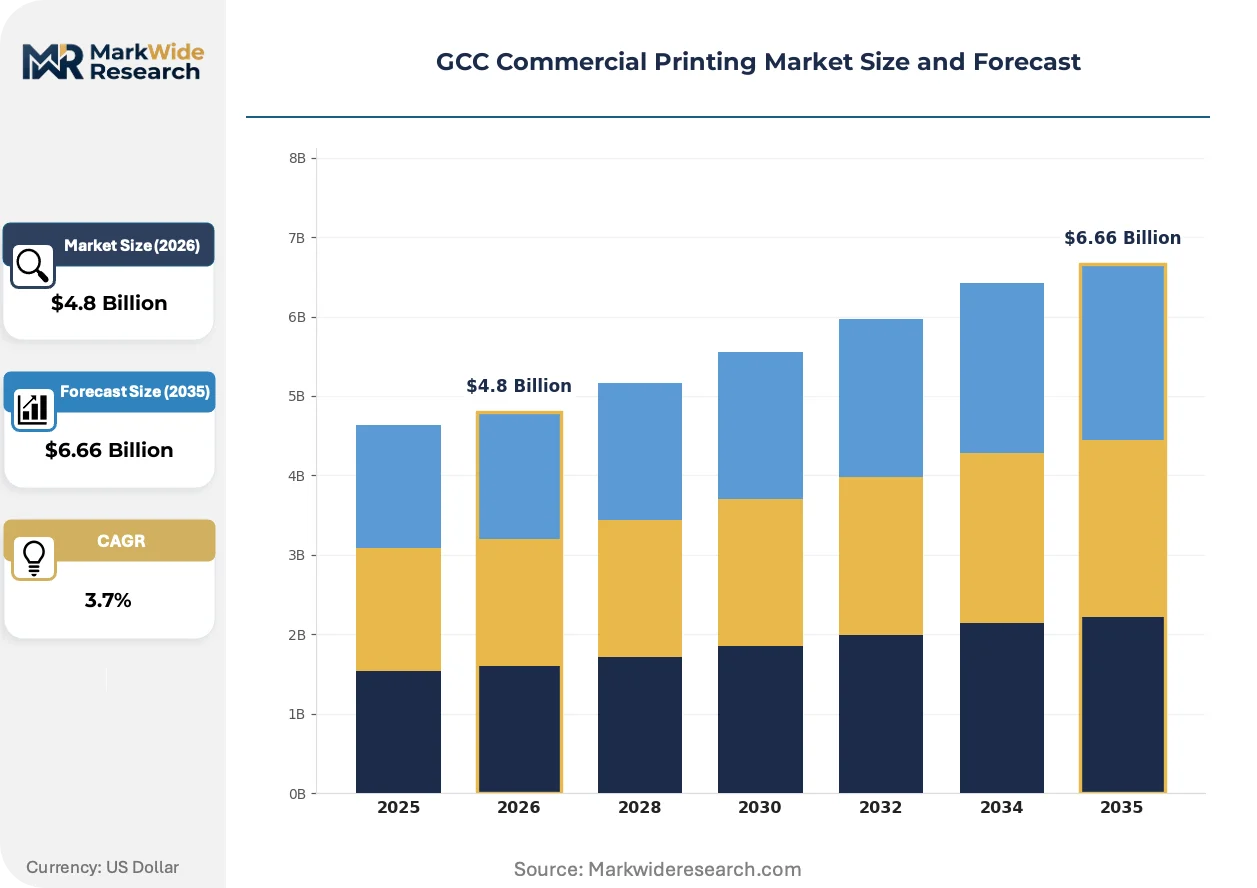
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printing, Offset Printing, Flexographic Printing, Gravure Printing End User: Publishing, Packaging, Advertising, Labels Technology: Inkjet, Laser, 3D Printing, Screen Printing Application: Commercial, Industrial, Retail, Promotional |
| Companies Covered | Toyo Ink, Alpha Inks, Sun Chemical, AHBAR Industries, Paintco, Flint Group, Siegwerk, Alsama Ink, DuPont, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Commercial Printing Market Strategic Shifts & Innovations
Water-based ink formulations and LED-UV curing systems are displacing conventional solvent technologies across Gulf packaging lines as brand owners respond to tightening volatile organic compound thresholds.
Single-pass inkjet printing for corrugated board is converging with automated pre-feed and post-print die-cutting lines, enabling converters to absorb shorter-run e-commerce packaging orders that previously flowed to flexographic competitors. Retail and logistics buyers in Dubai are adopting these integrated lines to serve same-week delivery requirements from fulfillment centers.
ESMA G-Mark certification requirements for printed consumer goods entering UAE distribution channels are forcing ink and substrate suppliers to maintain updated toxicological dossiers and third-party testing documentation. Luxury goods and food-contact packaging segments are absorbing the highest compliance costs, with several European ink houses withdrawing non-essential product lines rather than maintaining Gulf-specific registration files.
Brand procurement teams are consolidating print vendor relationships from fragmented local broker networks toward direct converter partnerships with certified quality management systems. Pharmaceutical and cosmetics verticals in Saudi Arabia are driving this consolidation most aggressively, seeking single-source accountability for batch traceability and regulatory documentation.
GCC Commercial Printing Market Segmentation
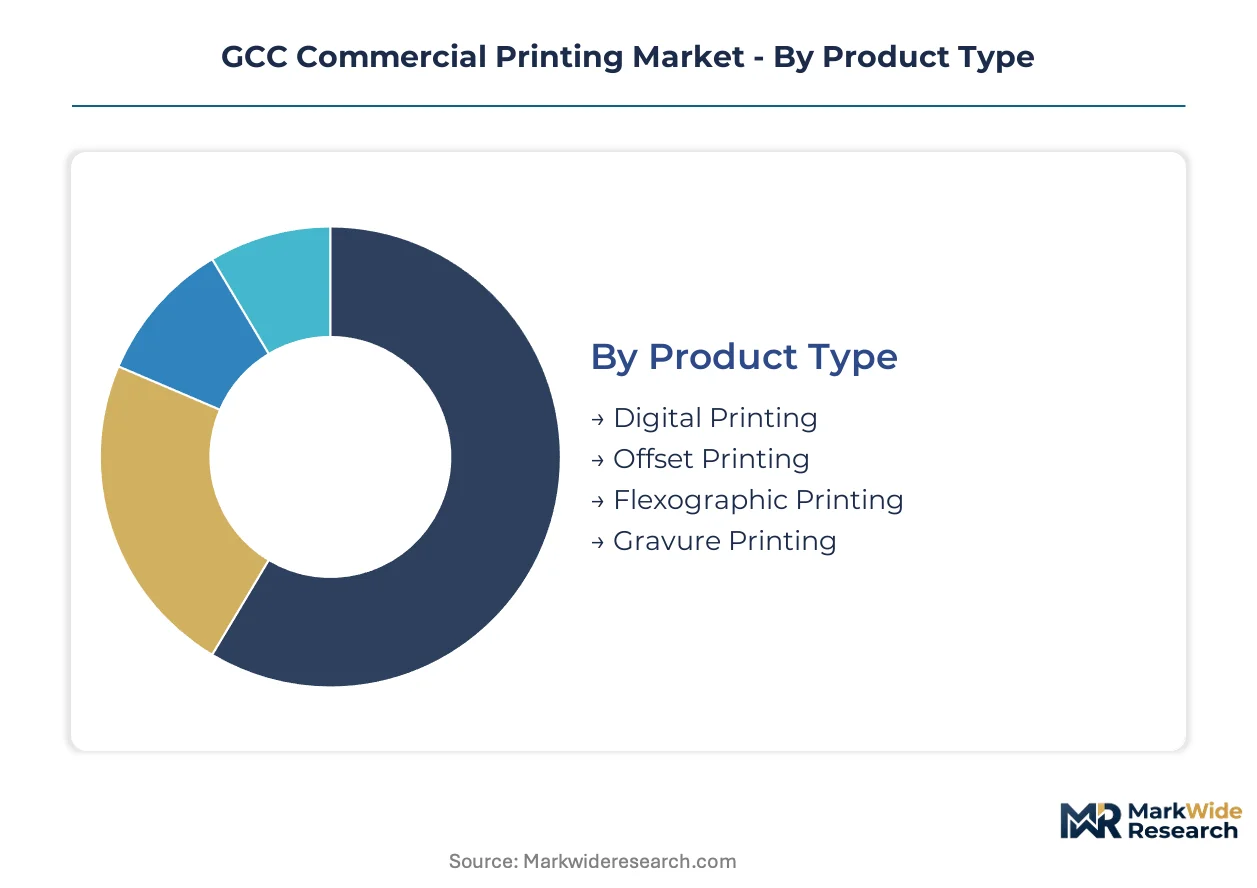
Technology and end-use boundaries in GCC commercial printing are hardening around regulatory compliance requirements. SABER and ESMA certifications now determine which segments can access Saudi and UAE procurement channels, reshaping investment priorities across converter operations.
Product Type:
SABER registration requirements for imported substrates and ESMA G-Mark certification for finished goods entering UAE distribution channels impose divergent compliance burdens across mechanical and digital processes.
- Digital Printing:Inkjet and electrophotographic systems enable variable-data output without plate-making, reducing setup waste for short-run jobs. Dubai packaging converters deploy these systems for e-commerce fulfillment clients demanding same-week turnaround on corrugated inserts. ESMA certification costs for digital substrates run lower than offset equivalents due to reduced chemical migration pathways.
- Offset Printing:Lithographic sheetfed and web-fed systems dominate long-run magazine and book production through economies of scale on unit costs. Saudi educational publishers in Riyadh maintain captive offset capacity for textbook runs exceeding fifty thousand impressions. SABER documentation for imported coated papers and fountain solutions adds procurement friction foreign suppliers struggle to navigate.
- Flexographic Printing:Rotary relief printing on flexible packaging and labels serves food-contact applications across Gulf dairy and confectionery sectors. Low-migration ink formulations from Siegwerk and Toyo Ink anchor compliance with GSO technical regulations.
- Gravure Printing:Intaglio cylinder engraving delivers premium decorative output for luxury cosmetics and tobacco packaging. High cylinder engraving costs restrict viable run lengths to major brand owners with annual volume commitments.
Leading the category by volume: Offset Printing. Growing fastest: Digital Printing.
End User:
Margin structures and certification intensity vary sharply across customer verticals, with food-contact and pharmaceutical applications commanding premium pricing for toxicological documentation.
- Packaging:Primary and secondary packaging for FMCG, pharmaceuticals, and cosmetics drives the largest revenue concentration across GCC print procurement. Riyadh retail expansion and Dubai logistics corridors generate sustained demand for folding cartons, flexible pouches, and corrugated shipping cases. SASO food-contact migration limits push converters toward certified ink systems with full toxicological dossiers.
- Labels:Pressure-sensitive and shrink-sleeve formats serve product identification, tamper evidence, and promotional coding requirements. Pharmaceutical serialization mandates in Saudi Arabia and UAE are accelerating digital press adoption for variable-data batch coding.
- Publishing:Educational textbooks, religious texts, and government documents sustain offset volume through long-run economics. Saudi curriculum reforms and UAE government communication programs anchor regional demand.
- Advertising:Point-of-sale displays, outdoor banners, and direct mail support retail and event marketing campaigns. Short-run promotional cycles favor digital production for versioning across Gulf city markets.
Highest margin capture: Packaging. Steepest expansion trajectory: Labels.
Technology:
Capital deployment thresholds and specialist labor requirements segment converter capabilities, with seven-figure press investments restricting digital adoption to well-capitalized groups.
- Inkjet:Piezoelectric drop-on-demand and continuous inkjet systems enable single-pass corrugated board printing and high-speed label production. Dubai converters integrate these lines with automated die-cutting for e-commerce packaging workflows. Water-based formulations are displacing solvent systems under tightening volatile organic compound thresholds.
- Laser:Electrophotographic toner fusion serves transactional printing, security documents, and short-run book production. Lower capital barriers support mid-market converter entry compared to production inkjet.
- Screen Printing:Stencil-based ink deposition handles thick-film decorative effects, industrial signage, and specialty substrates unsuited to contact printing. Manual and semi-automatic configurations persist for low-volume industrial applications.
- 3D Printing:Additive manufacturing for prototyping and short-run dimensional signage remains nascent in GCC commercial print, with limited substrate compatibility constraining production scale.
Dominant installed base: Inkjet. Fastest capability expansion: Laser.
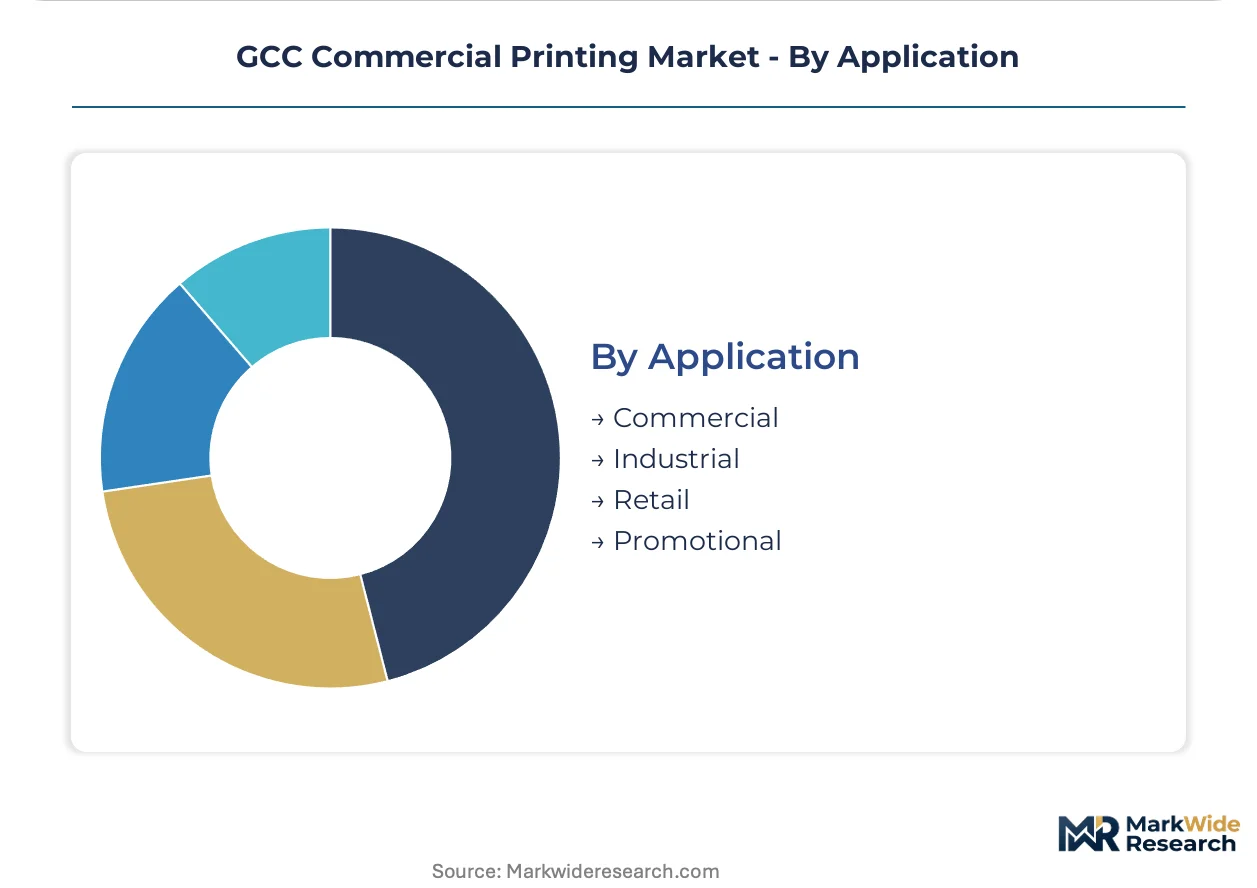
Application:
Customer procurement consolidation and direct converter relationships are concentrating volume in segments with certified quality management systems and batch traceability documentation.
- Commercial:General business printing encompassing stationery, marketing collateral, and corporate reports serves SME and enterprise clients across Gulf financial and professional services. Margin compression from overcapacity in Dubai and Jeddah has pushed converters toward value-added finishing services.
- Retail:In-store signage, shelf talkers, and seasonal promotional materials support hypermarket and mall-based merchandising programs. Riyadh retail expansion and Dubai tourism recovery sustain large-format print demand.
- Industrial:Technical documentation, safety labeling, and durable goods identification serve manufacturing and logistics operations. Oilfield services and petrochemical facilities in Saudi Eastern Province generate specialized durable label requirements.
- Promotional:Event-specific and campaign-based print products with compressed turnaround requirements favor digital production for versioning and personalization at scale.
Largest revenue pool: Commercial. Quickest share gain: Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the Arabian Gulf anchors ink formulation supply chains, with Saudi Arabia and the UAE converting crude derivatives into resin and solvent inputs that supply converters across the six-member economic bloc.
Saudi Arabia
Riyadh retail expansion and Jeddah logistics corridors drive large-format and label print volumes for FMCG distribution. SASO SABER registration mandates filter imported substrate suppliers, accelerating local ink blending investments in the Eastern Province industrial zones. Dammam-based converters leverage captive petrochemical feedstock to supply packaging for dairy and confectionery brands.
United Arab Emirates
Dubai's position as a regional trade hub concentrates demand for promotional and variable-data printing serving tourism and retail sectors. ESMA G-Mark certification requirements enforce toxicological documentation for food-contact materials entering UAE distribution channels. Sharjah industrial zones host mid-scale converters specializing in corrugated e-commerce packaging for Gulf fulfillment networks.
Kuwait
Government communication programs and educational publishing sustain offset volume through long-run textbook procurement. The country's national quality infrastructure body aligns with GSO technical regulations for printed materials, raising compliance barriers for non-certified ink suppliers. Hawalli Governorate print clusters serve local retail branding with limited digital infrastructure.
Bahrain
Financial services marketing and event-driven promotional printing generate demand for short-run digital production with compressed turnaround requirements. The national standards body enforces Gulf-wide conformity assessment protocols for imported packaging substrates. Manama commercial districts concentrate small-format print procurement for banking and professional services clients.
Qatar
Construction sector documentation and hydrocarbon industry safety labeling sustain industrial print applications despite retail market scale constraints. The national quality regulator mandates alignment with GSO food-contact migration limits for packaging entering consumer channels. Doha logistics zones serve as transshipment points for print materials destined for smaller Gulf markets.
GCC Commercial Printing Market Key Industry Players
Global majors compete with regional champions across formulation technology and regulatory compliance capabilities. Market structure shows moderate consolidation around ink suppliers with Gulf-specific registration dossiers and local blending infrastructure. Three archetypes dominate: multinational chemical houses with toxicological clearance portfolios, regional blenders leveraging import substitution mandates, and specialty converters integrating ink supply with print production. Competitive dynamics center on SABER and ESMA certification maintenance, plus backward integration into resin and pigment sourcing.
Within the multinational chemical tier, Toyo Ink and Sun Chemical exemplify divergent positioning strategies. Toyo Ink anchors regional supply through Eastern Province blending facilities serving packaging converters with proximity advantages. Sun Chemical occupies the premium formulation segment where UV-curable systems command pricing power for luxury goods applications. Siegwerk sits within the food-compliant specialization archetype, with low-migration ink portfolios aligned to GSO technical regulations.
| Leading Market Players |
|---|
| Toyo Ink |
| Alpha Inks |
| Sun Chemical |
| AHBAR Industries |
| Paintco |
| Flint Group |
| Siegwerk |
| Alsama Ink |
| DuPont |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock indices in the Arabian Gulf cascade through resin and solvent costs into three-tier pricing stratification across premium UV-curable, standard offset, and economy water-based ink formulations. SABER registration burdens and ESMA G-Mark certification costs concentrate pricing power with suppliers maintaining toxicological dossiers, while freight rate volatility on Asian substrate imports compresses converter margins on fixed annual contracts.
Pricing Analysis
Service-bundling separates certified ink suppliers offering SABER documentation support from unbundled commodity traders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and toxicological clearance depth. Cost compression in the economy tier intensifies as Asian substrate imports face customs clearance delays. Pharmaceutical and cosmetics verticals show least price sensitivity due to batch traceability requirements, while general commercial print buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
Saudi Arabia's SABER import substitution mandates and UAE's local-content preferences for government procurement are reshaping sourcing toward Eastern Province blending facilities and Sharjah industrial zones. Raw material flows draw from German pigment houses, Chinese coated paper mills, and regional petrochemical derivatives. Single-source vulnerability concentrates in specialty film substrates from European mills. Distribution runs through Dubai logistics corridors serving transshipment to smaller Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
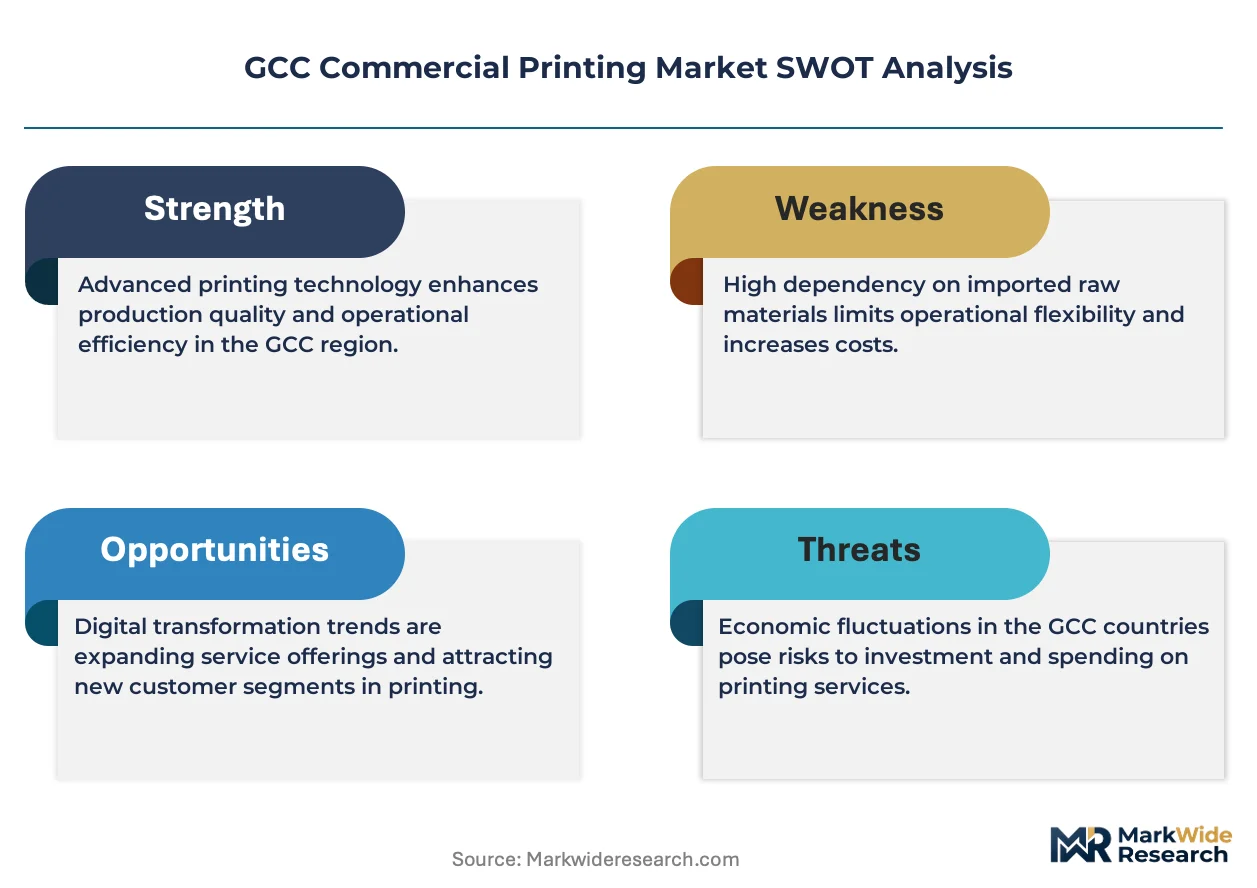
The GCC commercial printing market functions as a cost-of-compliance story where SASO SABER and ESMA G-Mark registration requirements erect barrier-to-entry moats favoring incumbent suppliers with established toxicological dossiers.
For Market Incumbents: Lock in converter relationships through multi-year ink supply contracts bundling SABER documentation services. Deepen backward integration into resin formulation at Eastern Province facilities to defend against Asian import substitution threats. Prioritize certification maintenance for food-contact migration limits as GSO technical regulations tighten. For New Entrants and Emerging Players: Launch via digital workflow partnerships serving Kuwait and Bahrain retail branding clusters where compliance infrastructure remains underdeveloped. Target corrugated e-commerce packaging segments in Sharjah industrial zones where same-week turnaround requirements favor agile production. Pursue white-label ink blending arrangements with Saudi distributors holding existing SABER registrations. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional blenders with captive petrochemical feedstock access in Saudi Arabia's Eastern Province over asset-light trading operations. Long-term viability hinges on regulatory compliance capabilities rather than volume scale. Watch for ESMA expansion of G-Mark requirements to additional substrate categories as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SABER Registration Investment | Toxicological dossier maintenance secures Saudi procurement channel access for ink suppliers. |
| Backward Integration into Resin | Captive petrochemical feedstock conversion at Dammam facilities reduces import dependency exposure. |
| Digital Press Fleet Expansion | Inkjet capacity addition captures e-commerce packaging versioning demand from Dubai fulfillment networks. |
| Food-Contact Certification Portfolio | Low-migration ink systems align with GSO dairy and confectionery packaging regulations. |
| Design-for-Recycling Consultation Service | EPR framework preparation creates recurring revenue streams from UAE and Saudi brand owners. |
Research Approach
Independent corroboration across packaging converter procurement directors, ink formulation technical managers, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from SASO SABER registration databases, ESMA G-Mark certification records, Gulf Standardization Organization technical regulations, and customs import documentation for substrates. Bottom-up converter capacity surveys triangulate against top-down petrochemical derivative consumption data.
Comparable historical periods anchored the forecast window to pre-pandemic baseline volumes and post-recovery normalization patterns. The analytical framework segments by technology type, end-use vertical, and regulatory compliance tier across the projection horizon. CAGRs derive from installed base depreciation schedules, digital press adoption curves, and substrate import volume trends. Migration limit enforcement intensity and EPR framework rollout pace serve as key demand-modulating inputs.
The model assumes a particular technology adoption path; alternative pathways for water-based ink displacement of solvent systems would alter the outlook. Forecasts reflect assumptions about SABER registration processing efficiency and GSO harmonization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
US Newspaper Market
Digital Publishing
Japan Catalog Market
Digital Publishing
News and Magazines App Market
Digital Publishing
France Catalog Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Books Market
Digital Publishing
Digital Reading Market
Digital Publishing
Book Publishers Market
Digital Publishing
Online Comic Market
Digital Publishing
Digital Comics Market
Digital Publishing
Editor App Market
Digital Publishing
Newspaper Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Digital Comics Distribution and Consumption Platforms Market
Digital Publishing
Europe E-Book Market