
 Cosmetics Foundation Market | 2026-2036
Cosmetics Foundation Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics Foundation Market Analysis
Cosmetic chemist talent scarcity is bifurcating the industry into brands that can formulate at speed and those stuck in compliance bottlenecks. L'Oréal leverages its integrated R&D campuses to sustain pipeline velocity across multiple coverage tiers. Estée Lauder Companies anchors prestige positioning through dermatological testing partnerships that differentiate its serum-infused offerings. Shiseido competes with Japan-centric shade-matching technology that dominates East Asian skin tone categories.
Cosmetics foundation comprises pigmented preparations—typically suspending titanium dioxide, iron oxides, and film-forming polymers in emollient bases—designed to even skin tone and create a uniform surface for additional color cosmetics. Manufacturing employs high-shear homogenization to achieve particle sizes below 15 microns, ensuring seamless skin adhesion and optical blurring. Liquid formulations lead volume due to blendability versatility, though stick formats are gaining fastest among travel-retail and on-the-go segments where portability commands premium placement. Dewy finish SKUs concentrate margin pools in premium channels, while matte coverage dominates mass-market turnover across drugstore and hypermarket distribution.
FDA color additive regulations and EU REACH restrictions on per- and polyfluoroalkyl substances constrain formulation flexibility, forcing reformulation cycles that reshape supplier relationships. China's NMPA filing requirements for imported cosmetics create market access timelines that favor domestic manufacturers with established testing partnerships. ISO 22716 Good Manufacturing Practices certification now functions as a baseline procurement filter for retailers across North America and Europe. Stakeholders must monitor how biotechnological alternatives to conventional silicones and evolving microplastic bans recalibrate ingredient sourcing strategies before competitors lock in compliant supply chains.
Market Dynamics
Clean beauty certification mandates and per-fluorinated substance bans are forcing simultaneous reformulation across prestige and mass tiers, compressing R&D timelines while elevating compliance costs as the dominant structural pressure.
Growth Catalysts
- Cross-border e-commerce expansion:China's Tmall Global and Douyin cross-border channels unlock direct consumer access for international brands without domestic entity establishment, accelerating market entry velocity.
- EU Green Deal chemical transparency requirements:Digital product passport mandates drive ingredient disclosure investments that premium brands leverage as competitive differentiation tools.
- Serum-infusion technology:Hybrid skincare-makeup formulations incorporating niacinamide and hyaluronic acid attract dermatological channel placement and professional makeup artist endorsement.
Market Restraints
- Titanium dioxide supply concentration:Chinese and Ukrainian feedstock processors control over 60% of cosmetic-grade TiO2 supply, exposing formulators to geopolitical disruption risk.
- REACH per- and polyfluoroalkyl substance restrictions:ECHA's PFAS ban timeline forces premature abandonment of long-wear film-forming polymers before viable alternatives achieve scale.
- Silicone substitution technical ceiling:Plant-derived emollients fail to replicate dimethicone's spreadability and water resistance, limiting clean-label claims in humidity-resistant formulations.
Strategic Opportunities
- India's organized retail penetration:Reliance Retail and Nykaa's physical expansion into Tier-2 cities creates first-mover advantage for shade-range localization in South Asian skin tones.
- Refillable packaging regulatory tailwinds:France's AGEC law and upcoming EU Packaging Regulation mandate extended producer responsibility, rewarding brands with circular infrastructure.
- AI-powered shade-matching convergence:Computer vision and spectral imaging integration enables virtual try-on accuracy that reduces return rates and enables direct-to-consumer precision.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in silicone-free emulsion stability commands 40% salary premiums, bottling pipeline velocity for mid-tier brands without captive R&D campuses.
- NMPA animal testing exemption navigation:China's acceptance of alternative toxicology data requires specialized regulatory affairs capabilities that delay market access by 12-18 months for unprepared entrants.
- ISO 22716 certification timeline compression:Retailer procurement mandates force simultaneous facility upgrades across multiple manufacturing sites, straining capex allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics Foundation Market |
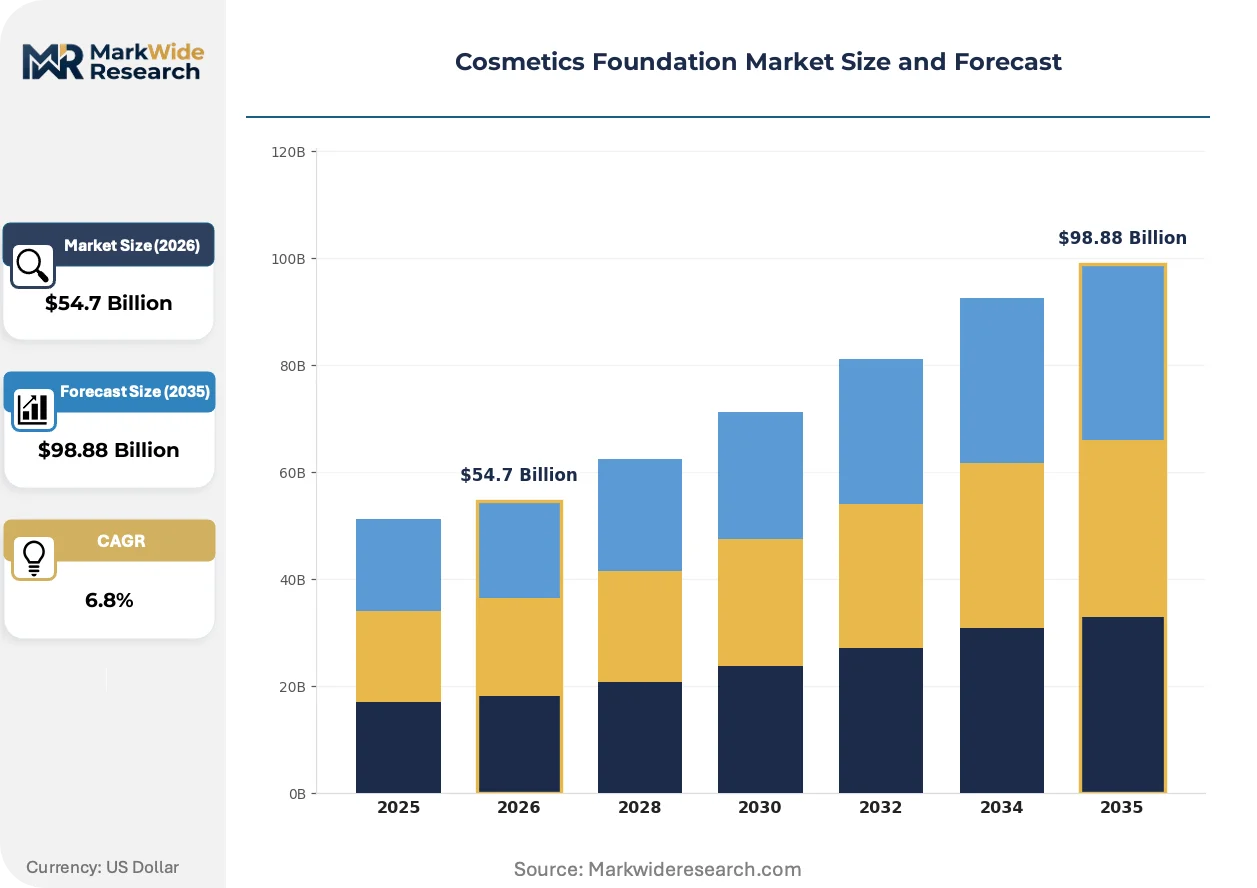
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Cream, Stick, Powder Coverage Level: Full, Medium, Sheer, Buildable Finish: Matte, Dewy, Satin, Natural Skin Type: Oily, Dry, Combination, Sensitive |
| Companies Covered | Coty, Charlotte Tilbury, L'Oréal, Revlon, Fenty Beauty, Estée Lauder Companies, Shiseido, Maybelline New York, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics Foundation Market Emerging Trajectories
Biotechnology-derived ingredients and algorithmic personalization are converging to redefine formulation architecture and consumer relationship models across coverage tiers.
Biotechnology-synthesized squalane and hemisqualane is fragmenting conventional olive and sugarcane-derived emollient supply chains. Indie brands and clean-beauty specialists adopt fermentation-based alternatives at 3x the pace of legacy houses. The technology is fragmenting traditional supplier relationships as biotech firms bypass conventional chemical distributors to contract directly with finished goods manufacturers.
REACH microplastic restrictions and impending powder-phase capture requirements reshape loose powder and glitter formulation portfolios. ECHA's 2023-2025 restriction roadmap forces immediate reformulation of conventional polyethylene and nylon texturizing agents. Pressed powder and anhydrous stick formats gain share as brands pre-empt compliance exposure in European distribution.
Algorithmic skin analysis and subscription-based shade-matching services compress traditional trial-and-purchase cycles. Professional makeup artists and bridal segment buyers increasingly bypass counter sampling for at-home diagnostic kits with AI-curated foundation matches. This behavioral pivot concentrates most visibly in South Korea and Japan, where beauty-tech integration penetrates earlier adopter cohorts fastest.
Cosmetics Foundation Market Segmentation
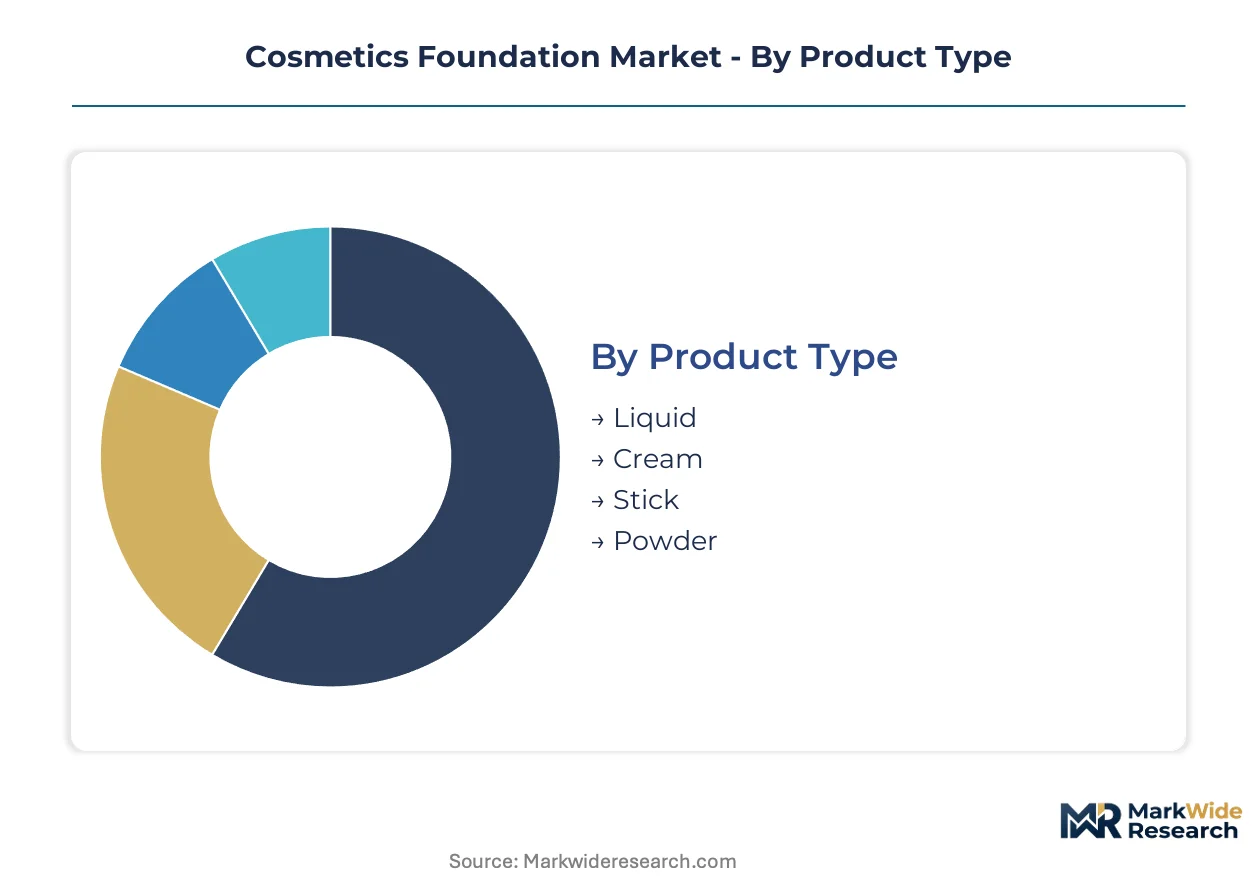
Foundation segmentation determines manufacturing complexity, distribution channel selection, and pricing architecture across prestige and mass tiers. Formulation chemistry, coverage performance, and skin-specific positioning create distinct margin pools that reward specialized capabilities.
Product Type:
Liquid and stick formats command the widest margin premiums due to formulation sophistication and portability-driven placement in travel retail.
- Liquid:Suspensions of titanium dioxide and iron oxides in emollient bases with particle sizes below 15 microns. Demand concentrates among professional makeup artists and salon channels where blendability versatility supports service-based revenue models. High-shear homogenization requirements elevate manufacturing barriers.
- Stick:Anhydous wax-polymer matrices delivering portable, precise application. Travel-retail and on-the-go segments in China and South Korea drive fastest expansion as portability commands premium shelf placement and impulse purchase behavior.
- Cream:Thicker emulsion bases targeting mature skin demographics with hydration-focused positioning.
- Powder:Pressed and loose formats facing REACH microplastic restriction headwinds; pressed variants gain share as brands pre-empt compliance exposure.
The dominant share belongs to liquid formulations, while stick formats are expanding most quickly in Asia-Pacific travel corridors.
Coverage Level:
Volume throughput and dermatological channel access split across coverage tiers, with buildable formulations capturing hybrid skincare-makeup positioning.
- Buildable:Layerable pigment concentration enabling sheer-to-full transition within single SKU. AI-powered shade-matching services and subscription models in Japan and South Korea concentrate demand as diagnostic kits reduce counter sampling dependency.
- Full:Maximum opacity formulations for professional photography, bridal, and stage applications. Salon and professional makeup artist channels in India and the United States anchor volume as high-definition media standards intensify coverage requirements.
- Medium:Mass-market workhorse positioning across drugstore and hypermarket distribution.
- Sheer:Tinted moisturizer hybrids facing silicone substitution technical ceilings in humidity-resistant claims.
Buildable coverage claims the steepest expansion trajectory, while full coverage defends its installed base in professional channels.
Finish:
Premium channel placement and mass-market turnover diverge sharply by finish type, with dewy formulations capturing serum-infusion technology premiums.
- Dewy:Light-reflecting emollient bases incorporating niacinamide and hyaluronic acid. Prestige positioning in the United States and France leverages dermatological testing partnerships and clean beauty certification standards.
- Matte:Oil-absorbing silica and clay matrices dominating drugstore turnover across mass-market distribution. Humidity-resistant claims face dimethicone substitution constraints from plant-derived emollient limitations.
- Satin:Balanced light diffusion for everyday professional wear.
- Natural:Skin-mimicking finish targeting male and gender-neutral positioning.
Matte finish retains volume leadership in mass channels, though dewy formulations are gaining share fastest in prestige e-commerce.
Skin Type:
Formulation specialization and clinical validation requirements elevate R&D investment for sensitive and oily skin targeting.
- Sensitive:Fragrance-free, hypoallergenic matrices with minimal preservative systems. EU and North American clean beauty certification mandates and ingredient transparency requirements reshape supplier relationships and testing protocols.
- Oily:Sebum-regulating actives and non-comedogenic claims. China's NMPA filing requirements for imported oil-control actives favor domestic manufacturers with established testing partnerships.
- Dry:Emollient-heavy bases with squalane and hemisqualane; biotechnology-derived alternatives fragment conventional olive supply chains.
- Combination:Zone-specific formulation balancing T-zone oil control with cheek hydration.
Sensitive skin positioning defends the highest margin tier, while oily skin targeting is climbing the fastest as humid climate demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR and NMPA filing requirements in China are compressing market access timelines while domestic manufacturers capture share through established testing partnerships. Professional makeup artist channels and cross-border e-commerce platforms are reshaping distribution across all major geographies.
China
Cross-border e-commerce through Tmall Global and Douyin accelerates international brand entry without domestic entity establishment. NMPA's evolving animal testing exemption pathways favor manufacturers with specialized regulatory affairs capabilities. Shanghai and Hangzhou anchor domestic brand headquarters where serum-infusion formulations and AI-powered shade-matching services concentrate development talent.
United States
Professional makeup artists and bridal segments anchor full-coverage demand as high-definition media standards intensify performance requirements. FDA color additive regulations constrain formulation flexibility while elevating compliance investments. Los Angeles and New York City clusters host dermatological testing partnerships that differentiate prestige positioning through clean beauty certification.
France
Dewy finish formulations capture premium channel margins through niacinamide and hyaluronic acid integration. AGEC law mandates on extended producer responsibility and refillable packaging infrastructure. Paris-based R&D campuses leverage EU Green Deal chemical transparency requirements as competitive differentiation tools against mass-market entrants.
Japan
Algorithmic skin analysis and subscription shade-matching services compress traditional trial-and-purchase cycles in Seoul-influenced beauty-tech adoption. METI standards on biotechnology-derived ingredients accelerate squalane and hemisqualane fermentation alternatives. Tokyo and Osaka clusters dominate East Asian skin tone shade-matching technology development.
India
Organized retail expansion into Tier-2 cities by Reliance Retail and Nykaa creates first-mover advantage for South Asian skin tone localization. BIS certification requirements and CDSCO regulations shape import timelines for international formulations. Mumbai and Bangalore manufacturing clusters build testing partnerships to bypass NMPA-equivalent delays for domestic production.
Cosmetics Foundation Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the prestige-mass divide. The market structures around three tiers: integrated multinational houses with captive R&D campuses, mid-tier brands dependent on contract manufacturers, and indie specialists leveraging biotechnology partnerships. Consolidation pressure concentrates among mid-tier players facing ISO 22716 certification capex strain. Dominant competitive moves include M&A to acquire formulation expertise and strategic partnerships with biotech suppliers for silicone alternatives.
Within the integrated multinational tier, L'Oréal and Estée Lauder Companies occupy positions defined by dermatological testing partnerships and serum-infusion technology pipelines. Shiseido anchors East Asian market representation through shade-matching specialization. Among mass-market fabricators, Coty and Revlon exemplify cost-leadership archetypes navigating silicone substitution technical ceilings. Fenty Beauty and Charlotte Tilbury represent indie-to-scale transitions leveraging clean beauty certification as tier-climbing mechanisms.
| Leading Market Players |
|---|
| Coty |
| Charlotte Tilbury |
| L'Oréal |
| Revlon |
| Fenty Beauty |
| Estée Lauder Companies |
| Shiseido |
| Maybelline New York |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for cosmetic-grade titanium dioxide lock in supply access and price visibility for integrated multinationals while exposing mid-tier brands to spot market volatility. These contract structures concentrate procurement power among houses with captive R&D campuses capable of absorbing minimum volume commitments.
Pricing Analysis
Geographic price spreads between prestige channels in France and mass-market distribution in India exceed 300% at equivalent coverage tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and dermatological testing investment. Cost compression in the matte finish mass tier is intensifying because Chinese domestic manufacturers exploit NMPA filing advantages to undercut import pricing. Professional makeup artist channels demonstrate lowest price sensitivity while drugstore turnover segments exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Chinese and Ukrainian titanium dioxide feedstock processors through Rotterdam and Shanghai ports have destabilized container availability on Asia-Europe trade lanes. Manufacturing concentrates in China, France, and Japan, with each hub serving distinct regulatory filing pathways. Raw material dependencies rest on titanium dioxide, iron oxide pigments, and dimethicone alternatives. Single-source vulnerability in Ukrainian TiO2 feedstock exposes formulators to geopolitical disruption. Distribution runs through professional salon channels, cross-border e-commerce platforms, and organized retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation demand sits in early-cycle expansion as serum-infusion technology and AI-powered shade-matching services penetrate professional and direct-to-consumer channels ahead of mass-market saturation.
For Market Incumbents: Consolidate formulation expertise through targeted acquisition of biotech-derived squalane suppliers to secure silicone-free emulsion capabilities. Expand captive R&D campus capacity in Shanghai and Tokyo to compress NMPA and METI filing timelines before domestic competitors lock in testing partnerships. For New Entrants and Emerging Players: Lead with refillable packaging infrastructure to capture France's AGEC law compliance premiums and upcoming EU Packaging Regulation mandates. Target India's Tier-2 organized retail expansion through Nykaa and Reliance Retail partnerships as the most penetrable white-space geography. Deploy AI-curated diagnostic kits to bypass traditional counter sampling dependency in South Korea and Japan. For Investors and Strategic Acquirers: Clean-beauty-certified contract manufacturers with ISO 22716 compliance and established China testing partnerships represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory affairs capabilities that compress market access timelines. Watch for NMPA animal testing exemption navigation success as the inflection signal separating scalable entrants from compliance-bottlenecked competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Ingredient Partnership | Fermentation-based squalane contracts bypass olive supply chain volatility and REACH silicone restrictions. |
| AI Shade-Matching Platform Launch | Computer vision integration reduces return rates and enables direct-to-consumer precision in Seoul-influenced markets. |
| Refillable Packaging Infrastructure | France's AGEC law mandates extended producer responsibility, rewarding circular supply chain investments. |
| NMPA Regulatory Affairs Buildout | Alternative toxicology data capabilities compress China market access timelines by 12-18 months. |
| South Asian Shade Range Localization | Tier-2 India retail expansion creates first-mover advantage in underserved skin tone categories. |
Methodological Framework
The analysis maps liquid, stick, cream, and powder foundation formats, each validated through cosmetic chemists, professional makeup artists, retail category buyers, and regulatory affairs specialists. Primary interviews with formulation directors at integrated multinationals and contract manufacturing executives combined with secondary validation from FDA color additive filings, ECHA REACH restriction databases, NMPA submission records, and customs trade data. Bottom-up SKU-level modeling and top-down category sizing triangulate volume estimates.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework segments by product type, coverage level, finish, and skin type positioning, with regional regulatory cluster as an additional modeling dimension. CAGRs derive from fitted growth curves calibrated to adoption rates of serum-infusion technology and AI-powered shade-matching penetration. Forecast inputs include cross-border e-commerce velocity through Tmall Global and Douyin, plus professional makeup artist channel expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained clean beauty certification adoption, stable titanium dioxide feedstock availability, and NMPA filing pathway evolution would require recalibration. Forecasts reflect assumptions about regulatory timeline adherence and biotechnology ingredient scale-up success. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Aluminium-Free Deodorants Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Europe Shampoo Market