
 IT Consumer Electronics E-Commerce Market | 2026-2036
IT Consumer Electronics E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
IT Consumer Electronics E-Commerce Market Analysis
Southeast Asia's fulfillment infrastructure build-out is tilting regional inventory positioning toward Vietnam and Indonesia. Amazon.com leverages its captive logistics network to sustain delivery speed advantages across North American urban corridors. JD.com anchors its competitiveness through in-house warehousing and last-mile control in mainland China. Alibaba Group differentiates via integrated payment ecosystems that lock in repeat transactions across its marketplace properties.
IT consumer electronics e-commerce encompasses the digital retail of computing devices, mobile terminals, and connected peripherals through internet-based transaction platforms, typically involving specifications such as processor architecture, display resolution, battery capacity, and wireless protocol compatibility. This commerce channel serves industrial and commercial purposes by collapsing distribution layers, enabling real-time price discovery, and extending geographic reach beyond physical retail boundaries. Smartphones and laptops within the product type dimension occupy the deepest margin pools due to high average selling prices and frequent refresh cycles, while wearables represent the fastest-expanding category as health-monitoring functionality broadens addressable demand. Online marketplaces dominate volume flows by aggregating third-party sellers alongside first-party inventory, though brand websites capture premium customer relationships through exclusive configuration options and direct warranty management.
The US Federal Trade Commission scrutinizes marketplace fee structures and search ranking transparency, directly influencing platform monetization models and seller access economics. China's State Administration for Market Regulation enforces anti-monopoly provisions against dominant e-commerce operators, reshaping exclusivity arrangements and promotional pricing mechanics. The European Union's Digital Services Act imposes algorithmic accountability and consumer protection standards that elevate compliance costs for cross-border electronics sellers. Stakeholders must monitor how divergent regulatory enforcement timelines fragment platform operating models across jurisdictions.
Market Dynamics
India's PLI scheme for electronics manufacturing is redirecting supply flows toward domestic production bases, forcing cross-border platforms to recalibrate inventory positioning and vendor relationships around new tariff-advantaged sourcing corridors.
Growth Catalysts
- Remote Work Infrastructure:Small business procurement of laptops and tablets through online channels is accelerating as distributed workforce models become standard operational practice across professional services and technology sectors.
- India's PLI Scheme:Production-linked incentive frameworks for electronics manufacturing are expanding domestic assembly capacity and reshaping supply availability for regional e-commerce fulfillment networks.
- Same-Day Delivery Density:China's tier-one cities have achieved unmatched last-mile network concentration for smartphones and wearables, compressing purchase-to-delivery windows and elevating platform switching costs.
Market Restraints
- Semiconductor Input Volatility:Foundry capacity constraints and advanced node allocation priorities create component scarcity that propagates through finished goods availability on digital retail platforms.
- Southeast Asian Fultration Concentration:Regional inventory positioning is tilting toward Vietnam and Indonesia, creating single-point vulnerability in fulfillment infrastructure build-outs.
- EU Digital Services Act Compliance:Algorithmic accountability and consumer protection standards elevate operational costs for cross-border electronics sellers accessing European Union markets.
Strategic Opportunities
- Tier-Two Chinese Penetration:Same-day delivery networks remain underdeveloped in China's tier-two and tier-three urban clusters, presenting expansion terrain for platform logistics investments.
- Wearables Health Integration:Health-monitoring functionality broadening across connected peripherals is opening addressable demand segments beyond traditional consumer electronics buyers.
- Captive Logistics Control:In-house warehousing and last-mile ownership models, as demonstrated by dominant mainland platforms, create defensible speed advantages that third-party dependent competitors cannot replicate.
Industry Challenges
- Cross-Border Customs Complexity:Divergent regulatory enforcement timelines across US FTC, China SAMR, and EU frameworks fragment platform operating models and elevate compliance staffing requirements.
- Platform Fee Structure Transparency:Scrutiny of marketplace commission rates and search ranking algorithms directly pressures monetization models and seller access economics.
- Brand Direct Channel Conflict:Exclusive configuration options and direct warranty management on manufacturer websites erode marketplace premium customer capture rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Consumer Electronics E-Commerce Market |
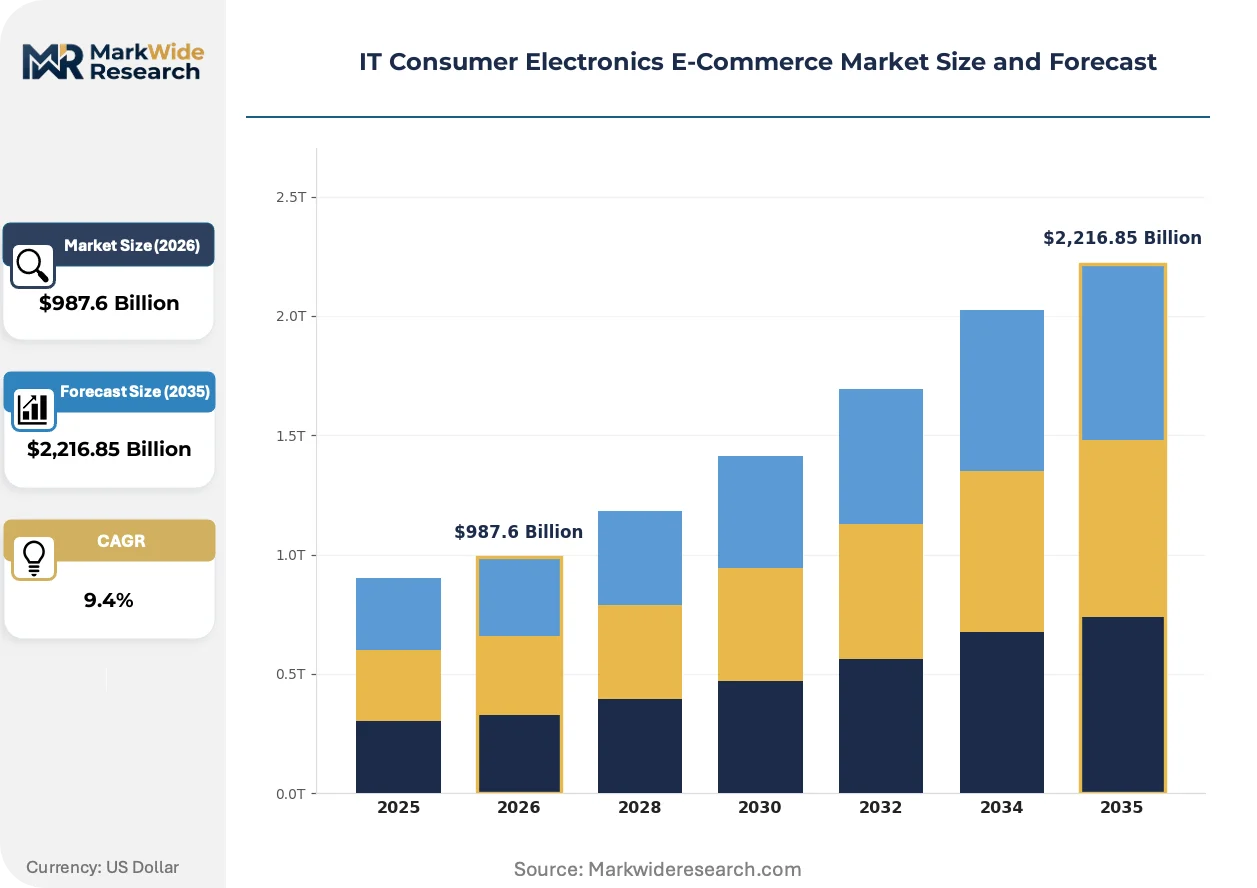
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $2,216.85 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Smartphones, Tablets, Wearables Sales Channel: Online Marketplaces, Brand Websites, Direct Sales, Retail Partnerships Customer Type: Individual Consumers, Small Businesses, Educational Institutions, Corporates Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Amazon.com, Apple, Best Buy, JD.com, Alibaba Group, Walmart, eBay, MediaMarktSaturn Retail Group, Flipkart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Consumer Electronics E-Commerce Market Emerging Trajectories
Platform business models are converging around integrated service ecosystems that lock in repeat transactions through payment, logistics, and device management bundling rather than pure product arbitrage.
Artificial intelligence-driven personalization engines are hybridizing product recommendation systems with predictive inventory placement. Enterprise procurement teams and individual consumers alike encounter algorithmically surfaced configurations matched to usage patterns. This compression of search-to-purchase cycles is reducing price comparison behavior and elevating platform stickiness metrics.
The European Union's Digital Services Act imposes algorithmic accountability requirements that force disclosure of content ranking parameters and advertising targeting logic. Cross-border electronics sellers face elevated documentation burdens and audit readiness protocols. Marketplace operators are responding by segregating EU-facing technical architectures from global systems to contain compliance scope.
Enterprise procurement of remote work equipment is migrating from centralized IT purchasing toward distributed employee self-selection with pre-approved catalog constraints. Channel conflict between direct brand websites and aggregator platforms intensifies as manufacturers deploy exclusive SKUs to defend margin pools. This behavioral shift is most visible in North American technology and professional services verticals where hybrid work policies have institutionalized device refresh subsidies.
IT Consumer Electronics E-Commerce Market Segmentation
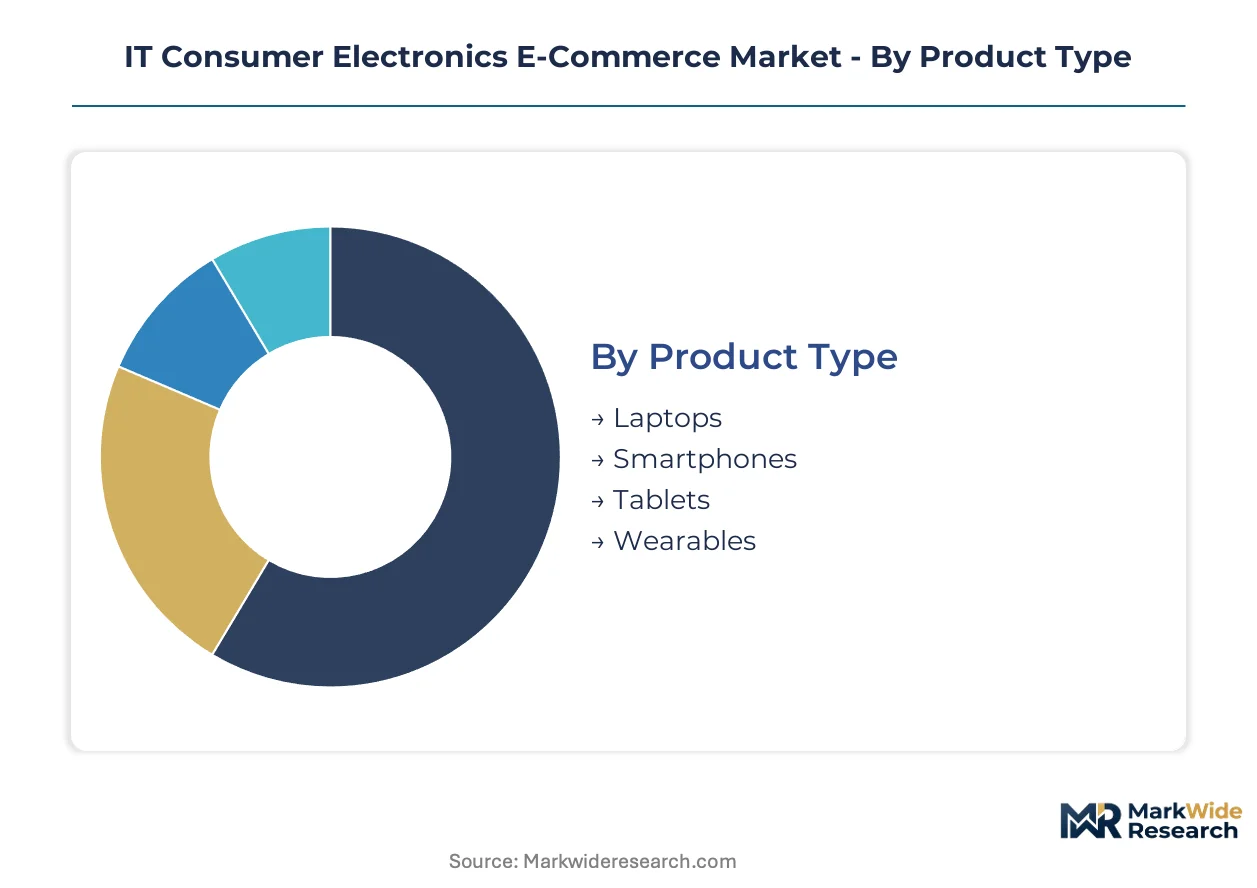
Segmentation in IT consumer electronics e-commerce reveals how purchasing behavior fragments across device categories, transaction platforms, and organizational scales. These divisions determine inventory allocation, pricing architecture, and fulfillment network design for digital retailers.
Product Type:
Device categories span professional productivity tools, personal communication terminals, portable computing surfaces, and biometric sensor platforms.
- Laptops:Mobile computing devices with x86 or ARM processor architectures, integrated keyboards, and display panels ranging from 13 to 17 inches. Procurement concentrates among North American technology sector employers refreshing remote work equipment fleets amid distributed workforce standardization.
- Smartphones:Cellular-enabled handheld terminals with touchscreen interfaces, multi-lens camera systems, and application ecosystem dependencies. China's tier-one cities drive volume through same-day delivery density that compresses replacement cycles and elevates platform switching costs.
- Tablets:Touchscreen slate devices bridging laptop productivity and smartphone portability through stylus and keyboard accessory ecosystems. Educational institutions in India and Indonesia represent concentrated demand corridors under national digital literacy initiatives.
- Wearables:Wrist-mounted or body-worn sensors capturing biometric data including heart rate, blood oxygen, and sleep architecture. Health-monitoring functionality expansion is broadening addressable demand beyond traditional consumer electronics buyers into preventive care segments.
The dominant share belongs to smartphones, while wearables are closing the gap fastest.
Sales Channel:
Transaction architecture separates aggregator platforms from captive brand environments through control over logistics, payment integration, and post-purchase service.
- Online Marketplaces:Third-party seller aggregation platforms combining first-party inventory with independent merchant listings. Amazon.com and JD.com anchor regional competitiveness through captive logistics networks that sustain delivery speed advantages.
- Brand Websites:Manufacturer-direct transaction environments offering exclusive configuration options and direct warranty management. Premium customer relationships concentrate here as channel conflict with aggregators intensifies over margin pool defense.
- Direct Sales:Employee-assisted or self-service transactions bypassing intermediary platform economics. Enterprise procurement teams leverage this channel for volume-negotiated terms on standardized device fleets.
- Retail Partnerships:Click-and-collect or ship-from-store arrangements with physical electronics chains. Inventory positioning tilts toward Vietnam and Indonesia as Southeast Asian fulfillment infrastructure build-out accelerates.
Aggregator platforms capture volume leadership, though brand-direct channels are climbing fastest as manufacturers deploy exclusive SKUs.
Customer Type:
Organizational scale determines purchasing authority concentration, from individual discretionary spend to centralized procurement functions.
- Individual Consumers:End-users acquiring single units through personal funds or device subsidy programs. Replacement cycles align with carrier contract terms and manufacturer refresh schedules.
- Small Businesses:Organizations with under 100 employees purchasing without dedicated IT procurement staff. Distributed employee self-selection with pre-approved catalog constraints is displacing centralized purchasing across North American professional services verticals.
- Educational Institutions:K-12 and higher education entities procuring through volume licensing and institutional discount frameworks. India's PLI scheme for electronics manufacturing is redirecting supply flows toward domestic production bases serving this segment.
- Corporates:Large enterprises with dedicated procurement functions negotiating master service agreements. The US Federal Trade Commission scrutinizes marketplace fee structures affecting total cost of ownership calculations in this tier.
Individual consumers hold the dominant position, while small businesses are gaining share fastest as remote work infrastructure becomes standard operational practice.
Price Tier:
Cost stratification separates entry-level accessibility from performance premium and status signaling positioning.
- Budget:Devices priced for cost-constrained buyers prioritizing core functionality over specification headroom. Component scarcity from foundry capacity constraints propagates availability volatility in this tier.
- Mid-Range:Specification-balanced offerings targeting three-to-four year ownership cycles without flagship price premiums. This tier captures the deepest volume pools as refresh cycles compress across emerging market middle classes.
- Premium:Near-flagship specifications with differentiated industrial design and material selection. The European Union's Digital Services Act elevates compliance costs that pressure margin structures in this segment.
- Luxury:Limited-production devices with precious material finishes, concierge service, and exclusivity guarantees. China's State Administration for Market Regulation anti-monopoly enforcement constrains promotional pricing mechanics affecting this tier's accessibility signaling.
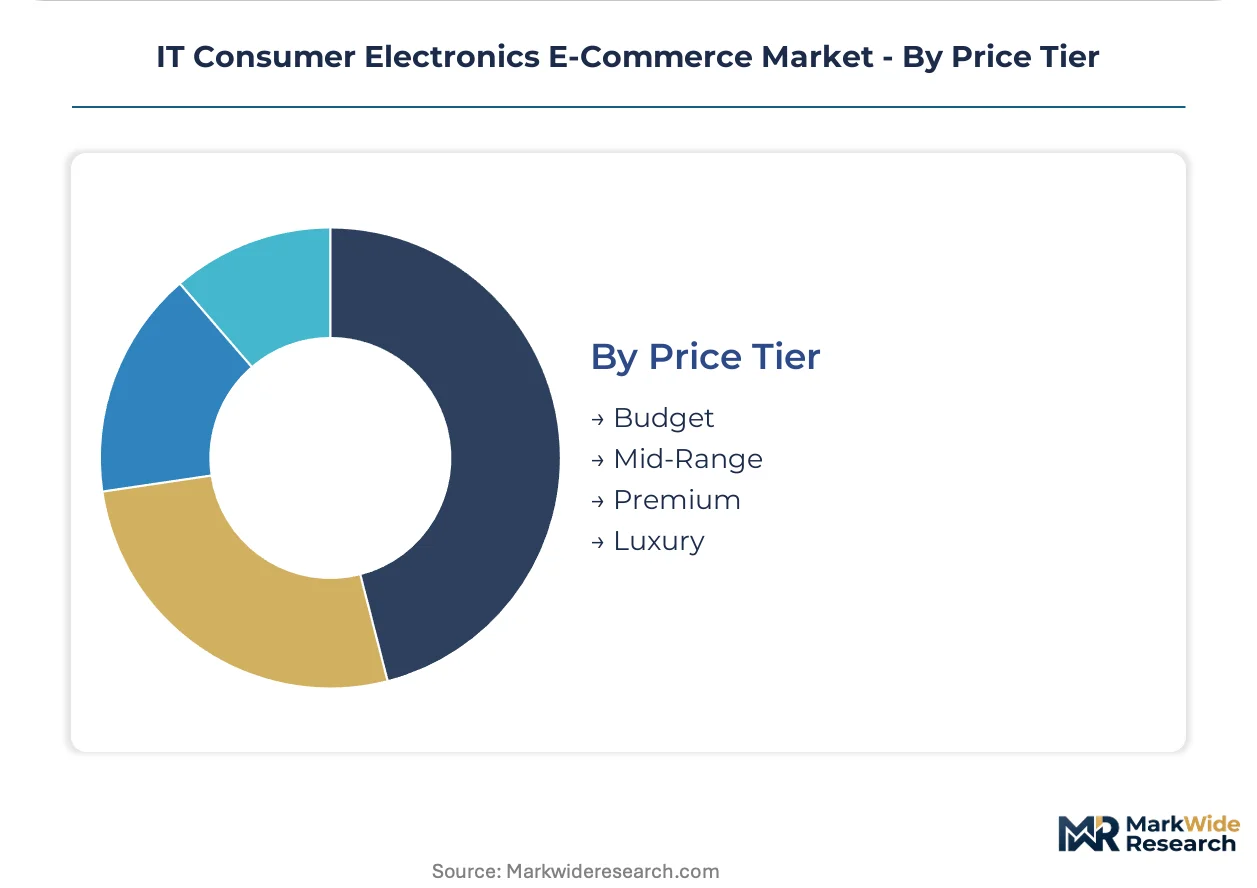
Mid-range pricing commands the dominant share, while premium tiers are climbing fastest as specification convergence blurs budget-premium boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's State Administration for Market Regulation anchors the regulatory framework governing the dominant geography, where anti-monopoly enforcement reshapes platform exclusivity arrangements and promotional mechanics for electronics retail.
China
Same-day delivery networks in Beijing, Shanghai, Shenzhen, and Guangzhou compress purchase-to-delivery windows for smartphones and wearables. SAMR's anti-monopoly provisions constrain dominant e-commerce operators from enforcing exclusivity arrangements with electronics vendors. JD.com anchors competitiveness through in-house warehousing and last-mile control concentrated in Yangtze River Delta logistics corridors.
United States
Enterprise procurement of remote work equipment through online channels accelerates as distributed workforce models standardize across technology and professional services sectors. The Federal Trade Commission scrutinizes marketplace fee structures and search ranking transparency affecting platform monetization. Amazon.com leverages captive logistics networks to sustain delivery speed advantages across dense urban corridors.
Germany
Cross-border electronics sellers face elevated compliance burdens from the European Union's Digital Services Act imposing algorithmic accountability standards. The country's central role in EU regulatory harmonization creates documentation and audit readiness protocols for platform operators. Berlin and Munich serve as compliance coordination hubs where marketplace technical architectures segregate EU-facing systems from global infrastructure.
India
Small business procurement of laptops and tablets through online channels accelerates as remote work infrastructure becomes standard operational practice. The PLI scheme for electronics manufacturing redirects supply flows toward domestic assembly bases serving cross-border platforms. Maharashtra and Karnataka host expanding production capacity that recalibrates inventory positioning around tariff-advantaged sourcing corridors.
Vietnam
Southeast Asia's fulfillment infrastructure build-out tilts regional inventory positioning toward Ho Chi Minh City and Hanoi logistics clusters. Educational institutions across ASEAN represent concentrated demand corridors for tablets under national digital literacy initiatives. Domestic platforms and cross-border aggregators compete to establish warehousing density ahead of anticipated electronics consumption growth.
IT Consumer Electronics E-Commerce Market Vendor Landscape
Capability concentration sits with vertically integrated logistics operators; scale advantage sits with aggregator platforms aggregating third-party seller networks. The market structure separates captive fulfillment networks from marketplace-dependent competitors through delivery speed differentiation. Three archetypes dominate: integrated logistics-platform hybrids, pure-play aggregators, and manufacturer-direct channels. Competitive moves center on warehouse capacity expansion and payment ecosystem integration to lock repeat transactions.
Among North American operators, Amazon.com and Best Buy exemplify divergent archetypes—the former through captive logistics scale, the latter through hybrid physical-digital fulfillment. JD.com represents the Asia-Pacific integrated model where warehousing and last-mile ownership create defensible speed advantages. Apple occupies a distinct premium-tier position through manufacturer-direct channel control and exclusive configuration ecosystems.
| Leading Market Players |
|---|
| Amazon.com |
| Apple |
| Best Buy |
| JD.com |
| Alibaba Group |
| Walmart |
| eBay |
| MediaMarktSaturn Retail Group |
| Flipkart |
| Others |
Supply Flow & Price Mechanics
China's foundry concentration for advanced semiconductors concentrates margin capture upstream, forcing downstream e-commerce platforms and device assemblers to compete on logistics speed and payment integration rather than component cost arbitrage. This upstream chokepoint elevates the strategic value of captive warehousing and last-mile ownership as alternative differentiation levers.
Pricing Analysis
Geographic price spreads between China's tier-one cities and India's emerging urban clusters exceed those within any single region, reflecting divergent delivery infrastructure maturity and tariff exposure. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by warranty bundling and same-day availability windows. Pricing pressure stems from semiconductor input volatility propagating through finished goods availability. Small businesses demonstrate highest price sensitivity due to unnegotiated volume terms, while corporate procurement functions leverage master service agreements to compress premiums.
Supply Chain Analysis
Extended payment terms from Vietnam and Indonesia logistics clusters are reshaping working capital requirements for cross-border platform operators. Component sourcing draws from China, Taiwan, and South Korea for advanced nodes, with assembly capacity expanding in India under PLI incentives. Foundry allocation priorities and customs processing complexity constitute the dominant structural risk. Distribution runs through captive warehousing networks in Yangtze River Delta and Pearl River Delta corridors, with third-party fulfillment serving peripheral penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among enterprise procurement functions and platform-dependent small businesses, fragmenting individual consumer price-taking behavior. This shift elevates the importance of pre-approved catalog constraints and volume-negotiated terms as competitive battlegrounds.
For Market Incumbents: Harden captive logistics networks against JD.com-style vertical integration by expanding same-day delivery density in China's tier-two clusters. Defend margin pools through exclusive SKU arrangements with smartphone and laptop manufacturers that limit aggregator platform commoditization. Priority lever: in-house warehousing ownership in Ho Chi Minh City and Jakarta logistics corridors.
For New Entrants and Emerging Players: Establish a beachhead in India's small business remote work equipment procurement segment, where PLI-scheme domestic assembly creates tariff-advantaged sourcing corridors absent from incumbent cross-border positioning. Target educational institution tablet demand under Indonesia's national digital literacy initiatives. Go-to-market angle: direct sales bypassing marketplace commission structures for volume-negotiated fleet terms.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated logistics-platform hybrids with demonstrated last-mile control in mainland China or Southeast Asia fulfillment clusters. Long-term viability hinges on warehouse capacity expansion outpacing demand growth across the projection horizon. Signal to watch: SAMR anti-monopoly enforcement intensity affecting exclusivity arrangement enforceability.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Capacity Expansion | JD.com's Yangtze River Delta density creates defensible speed advantages third-party competitors cannot replicate. |
| Payment Ecosystem Integration | Alibaba Group's Alipay bundling locks repeat transactions across marketplace properties through financial service anchoring. |
| Exclusive SKU Deployment | Apple's direct website configuration options erode aggregator premium customer capture rates through warranty control. |
| Same-Day Network Build-Out | Amazon's captive logistics sustains delivery speed advantages across North American urban corridors against hybrid competitors. |
| PLI-Aligned Sourcing Migration | India's domestic assembly incentives recalibrate inventory positioning toward Maharashtra and Karnataka production bases. |
Methodological Framework
The analysis maps online marketplaces, brand-direct channels, and retail partnerships, each validated through platform operations executives, logistics network planners, electronics procurement managers, and regulatory compliance officers. Primary interview intelligence triangulates against customs and trade data, SEC 10-K filings, SAMR enforcement disclosures, and hyperscaler capex disclosures. Bottom-up demand modeling and top-down supply validation converge through cross-referencing across the analysis window.
Assumptions held fixed include PLI scheme continuation intensity, SAMR anti-monopoly enforcement trajectory, and EU Digital Services Act implementation pace; variables tested include semiconductor foundry capacity allocation shifts and remote work policy institutionalization depth. Segmentation dimensions span product type, sales channel, customer scale, and price tier, with CAGRs derived from demand elasticity modeling against replacement cycle compression. Forecast inputs incorporate same-day delivery network density metrics and payment ecosystem penetration rates.
Sensitivities concentrate around foundry capacity reallocation, customs processing regulatory shifts, and platform fee structure transparency mandates. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
United States Same-Day Delivery Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
Iceland E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Direct-To-Consumer Test Market
E-Commerce Solutions
E-Commerce Market