
 Silicone Baby Product Market | 2026-2036
Silicone Baby Product Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Baby Product Market Insights
A capital-intensity divergence between large-scale molders and artisanal producers is rotating competitive dynamics in silicone baby goods. JEWELIVES leverages automated liquid injection molding to sustain cost advantages at volume. Pigeon Corporation anchors premium positioning through decades of pediatric nursing credibility. MAM Baby Articles AG differentiates via orthodontic design heritage and hospital-channel penetration.
Silicone baby products encompass food-grade elastomer items—typically platinum-cured polydimethylsiloxane with Shore A hardness between 30 and 70—engineered for infant feeding, soothing, and oral development. These goods resist thermal degradation from sterilization cycles while eliminating plasticizer migration risks associated with conventional polymers. Teething toys and bottles command the largest revenue pools within product type segmentation, with BPA-Free and Heat Resistant features now baseline expectations rather than premium differentiators. Online Retail and Specialty Stores capture the fastest-growing distribution channel share as direct-to-parent subscription models displace traditional supermarket aisle browsing.
FDA food-contact notification requirements and EU REACH compliance for silicone monomer residuals govern market access for exporters serving North American and European parents. China's GB standards and NMPA-equivalent food-grade certifications create parallel compliance obligations for manufacturers targeting domestic Chinese demand. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as regulatory scope expansion beyond BPA could force material reformulation across entire product lines.
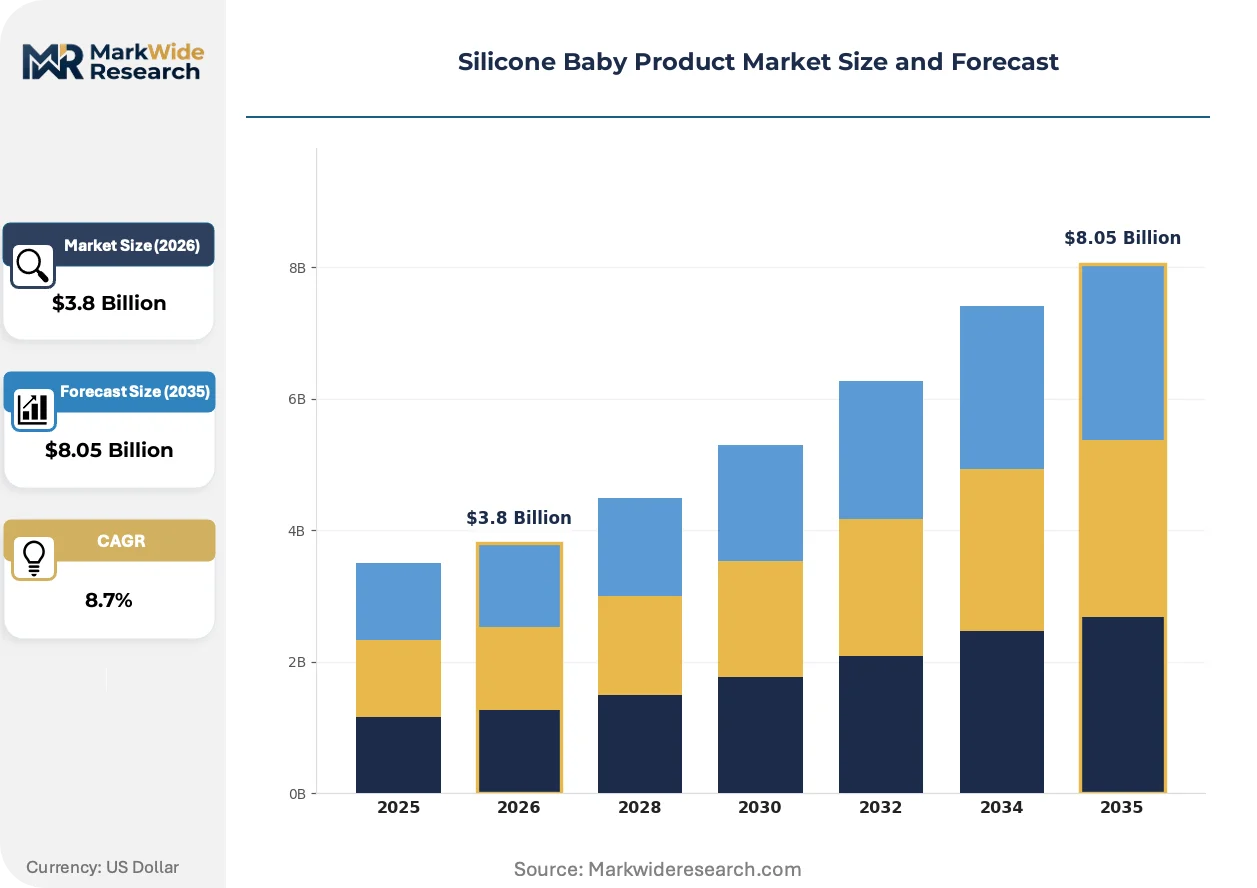
Market Dynamics
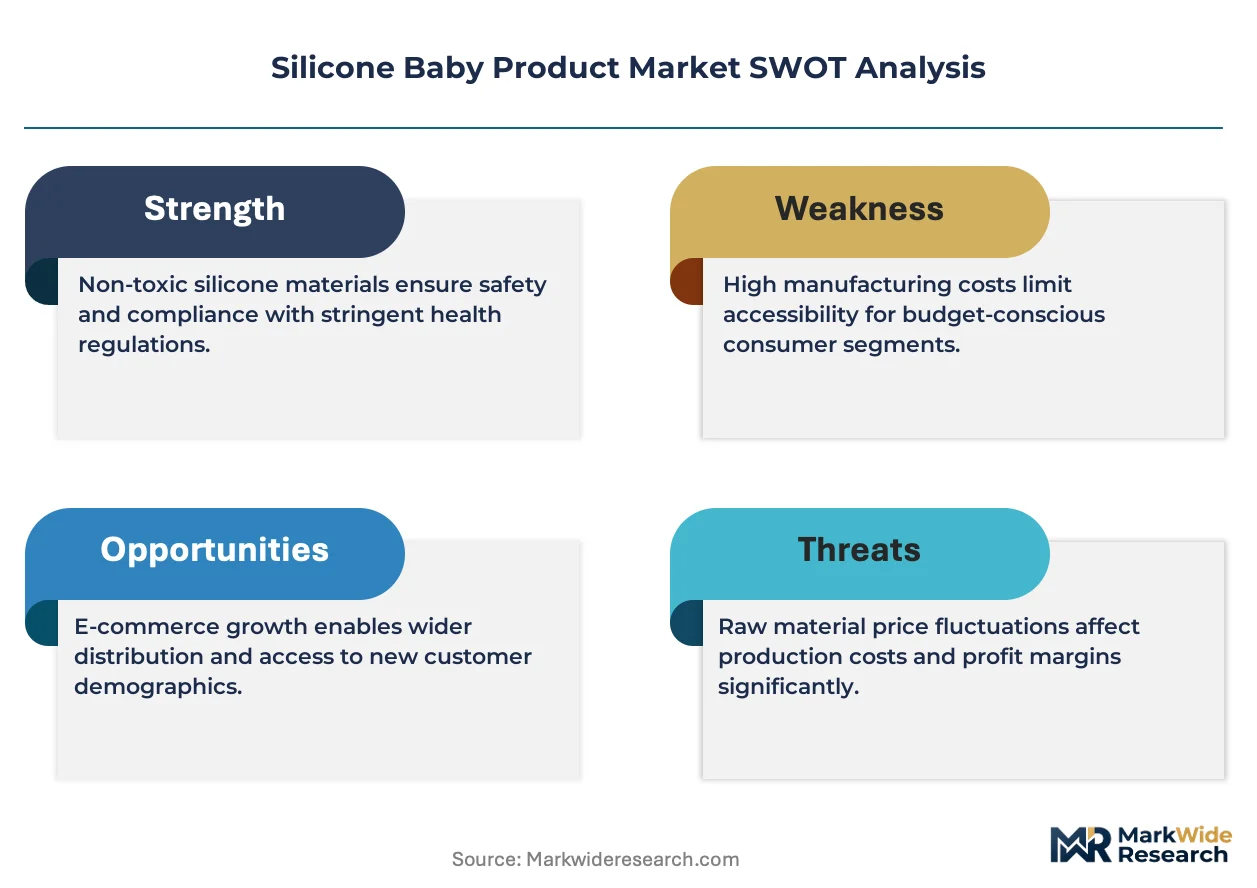
Platinum-cured liquid silicone rubber (LSR) injection molding is compressing production economics and forcing mid-tier molders into automation arms races or niche retreat. FDA food-contact notification requirements and REACH monomer residual limits now function as de facto capacity gates, privileging capitalized producers with dedicated compliance infrastructure.
Growth Catalysts
- EU REACH compliance migration:Parents in Germany and France now screen products for siloxane residual certificates before purchase, converting regulatory adherence into shelf-access currency.
- Hospital-channel credentialing:Pediatric dental associations in Italy and Spain endorse orthodontic-grade silicone pacifiers, creating institutional pull-through for premium SKUs.
- China's GB 4806.11 food-grade standard:Domestic manufacturers achieving NMPA-equivalent certification capture middle-class parents upgrading from TPE alternatives.
Market Restraints
- Platinum catalyst cost volatility:Automotive sector demand for silicone HCR strains catalyst allocation, squeezing margins for baby-goods molders without long-term supply contracts.
- Single-source medical-grade silicone dependency:Wacker and Dow control 70%+ of pharmaceutical-grade LSR feedstock, concentrating input risk for teething toy producers.
- Per- and polyfluoroalkyl substance contamination tracing:ECHA's expanding PFAS restriction scope threatens forced reformulation of anti-stick surface treatments across entire product lines.
Strategic Opportunities
- Subscription-based direct-to-parent replenishment:DTC platforms bypass retail slotting fees while capturing lifetime value through staged feeding-set upgrades.
- Biobased silicone feedstock adoption:Renewable methanol-to-silicone pathways under development by German chemical consortia promise Scope 3 emissions reduction for sustainability-positioned brands.
- India's BIS certification gap:Domestic manufacturers meeting FSSAI food-contact standards face limited competition from organized players in tier-2 cities.
Industry Challenges
- Liquid injection molding technician scarcity:LSR process engineering expertise concentrates in Guangdong and Bavaria, creating hiring bottlenecks for new entrants.
- FDA 510(k) equivalence determination delays:Novel nipple flow-rate designs face 12-18 month review timelines, compressing product refresh cycles.
- Multi-standard certification stacking:Simultaneous GB, REACH, and FDA compliance requires redundant testing protocols that strain QA bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Baby Product Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bibs, Bottles, Teething Toys, Spoons End User: Parents, Guardians, Childcare Centers, Retailers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Feature: BPA-Free, Durable, Eco-Friendly, Heat Resistant |
| Companies Covered | JEWELIVES, NEWTOP SILICONE, Melikey Silicone, Pigeon Corporation, KEAN, Mushie, JUTION Silicone, MAM Baby Articles AG, Z.S.R International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Baby Product Market Trends and Innovations
Material science advances and channel disintermediation are restructuring how silicone baby goods reach parents and how those products demonstrate safety credentials. Three developments merit particular attention.
Self-bonding LSR-to-thermoplastic overmolding is fragmenting the traditional assembly model for hybrid bottles and sippy cups. German automotive suppliers repurposing two-shot molding lines for consumer goods are cutting unit costs for complex multi-material designs. This capability compression enables regional molders to compete with Asian volume producers on customization lead times.
EU F-Gas Regulation phase-down schedules are accelerating medical-grade silicone refrigeration dependency audits across European supply chains. Molded component suppliers must now document cold-chain integrity for temperature-sensitive LSR shipments or face ECHA enforcement actions. Italian and Polish converters are investing in passive thermal packaging to maintain -20°C stability during truck-based distribution.
Certification-driven preference sorting is reshaping retail assortment strategies. Parents in California and New York now cross-reference FDA food-contact substance notifications against Environmental Working Group databases before purchase. Specialty retailers respond by front-of-store positioning products with third-party OEKO-TEX or bluesign verification, displacing unbadged competitors to digital clearance channels.
Silicone Baby Product Market Segmentation
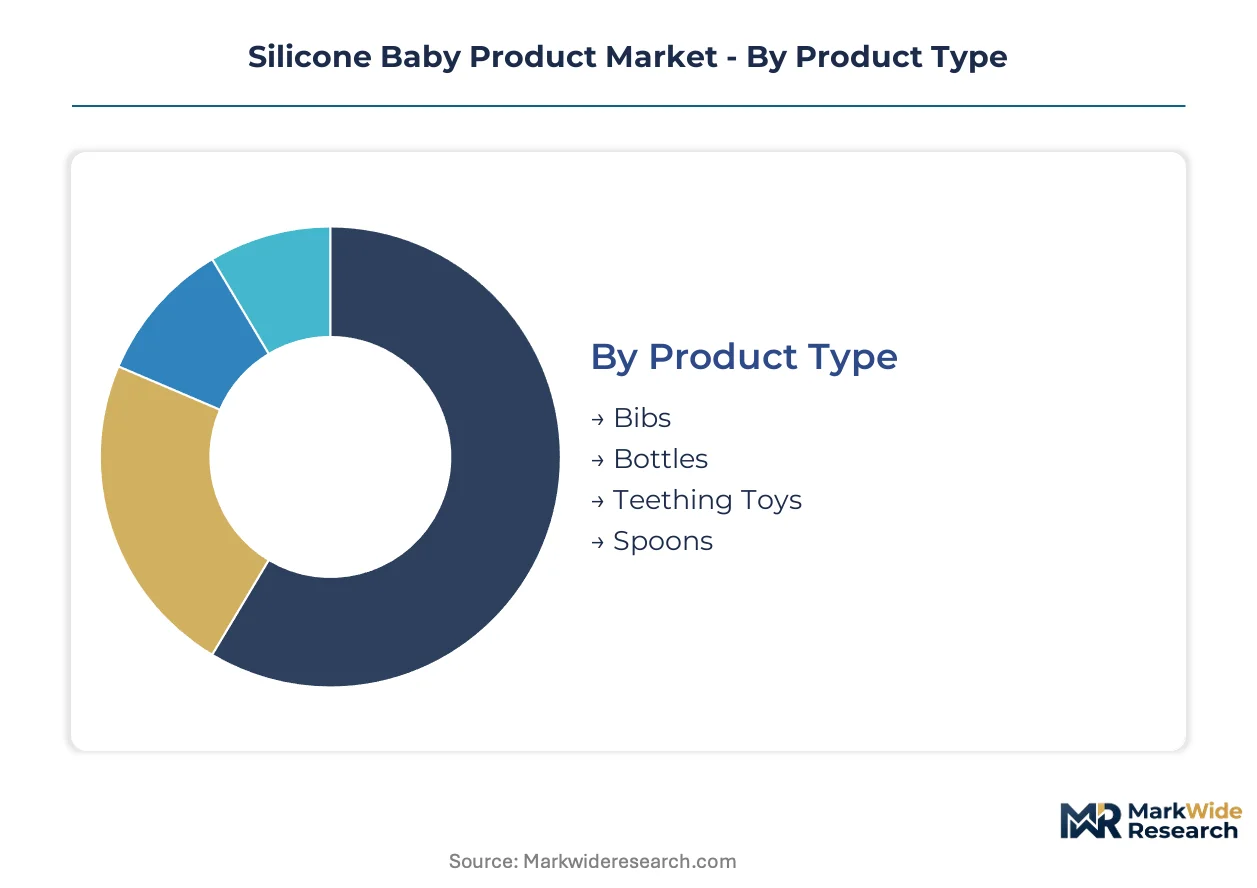
Silicone baby goods fragment across four dimensions that dictate manufacturing priorities and channel economics. Product type determines mold complexity and sterilization protocols. End-user concentration shapes bulk versus unit packaging requirements. Distribution channel selection governs margin retention and compliance documentation depth. Feature differentiation increasingly functions as a regulatory threshold rather than a premium markup vehicle.
Product Type:
Substitution pressure from TPE and natural rubber alternatives weighs heaviest on commoditized formats where parents prioritize cost over longevity.
- Teething Toys:Platinum-cured LSR formulations with Shore A 40-60 hardness dominate orthodontic-grade designs. German and Italian pediatric dental associations drive institutional endorsement demand. FDA 510(k) equivalence timelines for novel textures compress product refresh cycles to 18-24 months.
- Bottles:Hybrid LSR-to-polypropylene overmolding enables anti-colic venting systems. Parents in California and New York cross-reference FDA food-contact notifications against Environmental Working Group databases before purchase.
- Bibs:Food-grade silicone with integrated crumb-catchers displaces fabric alternatives in EU REACH-compliant markets. Lightweight designs suit travel and daycare bulk procurement.
- Spoons:Single-piece molded utensils with temperature-sensitive color-change additives address scald-risk concerns. China's GB 4806.11 certification requirements filter out uncertified exporters.
Teething toys retain volume leadership; bottles hold the steepest expansion curve.
End User:
Cost-tier stratification separates institutional procurement from direct-to-parent premium positioning.
- Parents:Millennial and Gen-Z buyers in North America and Europe drive BPA-free and heat-resistant feature adoption. Subscription-based replenishment models capture lifetime value through staged feeding-set upgrades.
- Childcare Centers:Commercial sterilization durability requirements favor thicker-wall LSR constructions. Bulk purchasing concentrates in Germany and France where facility licensing mandates material traceability.
- Guardians:Grandparent purchasers prioritize gift-packaged premium SKUs with third-party OEKO-TEX verification. Specialty store positioning displaces unbadged competitors.
- Retailers:Private-label buyers demand compressed lead times from automated liquid injection molders. JEWELIVES leverages volume scale to sustain cost advantages against artisanal producers.
Parents command the dominant revenue share; childcare centers are climbing fastest on institutional credentialing expansion.
Distribution Channel:
Geography determines whether cold-chain integrity documentation or slotting-fee avoidance governs channel selection.
- Online Retail:Direct-to-parent platforms bypass traditional supermarket aisle economics. EU F-Gas Regulation phase-down schedules force passive thermal packaging investments for temperature-sensitive LSR shipments.
- Specialty Stores:Front-of-store positioning for FDA- and REACH-certified products drives premium realization. Italian and Polish retailers invest in bluesign-verified assortment curation.
- Supermarkets:Mass-market volume concentrates in China where domestic manufacturing scales meet middle-class consumption growth. GB standard compliance functions as shelf-access currency.
- Direct Sales:Hospital-channel credentialing through pediatric nursing networks anchors premium pacifier placement. MAM Baby Articles AG differentiates via orthodontic design heritage.
Online retail leads volume contribution; specialty stores gain share fastest on certification-driven preference sorting.
Feature:
Margin compression is most severe where features have transitioned from premium differentiators to baseline compliance requirements.
- BPA-Free:Platinum-cured polydimethylsiloxane eliminates plasticizer migration risks associated with conventional polymers. EMA food-contact material standards shape European certification requirements.
- Heat Resistant:Thermal degradation resistance through repeated sterilization cycles now functions as a market-entry threshold rather than a markup vehicle. Parents expect dishwasher and microwave compatibility.
- Eco-Friendly:Biobased silicone feedstock adoption through renewable methanol-to-silicone pathways promises Scope 3 emissions reduction. German chemical consortia pilot production scale-up.
- Durable:Extended product lifespans reduce replacement frequency and compress replenishment revenue. Childcare center procurement prioritizes wear-resistance specifications.
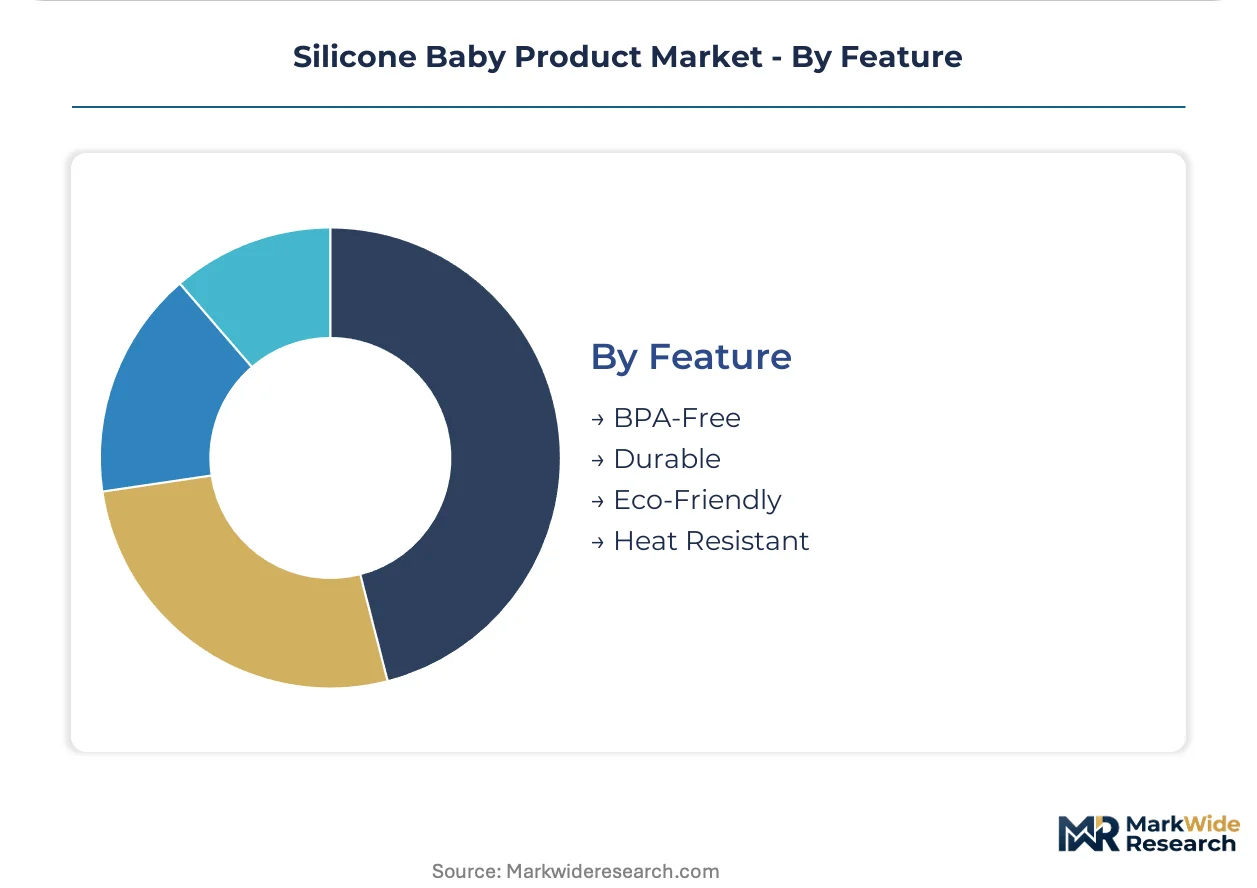
BPA-Free and heat resistant features retain universal penetration; eco-friendly positioning is expanding most quickly on sustainability-driven brand differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows reveal asymmetric regulatory compliance burdens across manufacturing bases. Countries with domestic silicone feedstock capacity and streamlined food-grade certification pathways capture disproportionate value in finished goods trade.
China
Domestic consumption of platinum-cured LSR feeding accessories accelerates among urban middle-class parents upgrading from TPE alternatives. GB 4806.11 food-grade silicone standards filter out uncertified imports while NMPA-equivalent certification functions as shelf-access currency for local manufacturers. The Yangtze River Delta and Pearl River Delta host automated liquid injection molding clusters where JEWELIVES and Z.S.R International Group sustain cost advantages at volume.
United States
Millennial and Gen-Z parents in California and New York cross-reference FDA food-contact substance notifications against Environmental Working Group databases before purchase. FDA 510(k) equivalence determination timelines of 12-18 months compress product refresh cycles for novel nipple designs. The Southeast and Midwest concentrate private-label manufacturing for mass-market retailers seeking compressed lead times.
Germany
Parents screen products for siloxane residual certificates before purchase, converting REACH compliance into retail positioning currency. EU F-Gas Regulation phase-down schedules force passive thermal packaging investments for temperature-sensitive LSR shipments. Bavaria hosts LSR process engineering expertise clusters where automotive suppliers repurpose two-shot molding lines for consumer goods.
India
Domestic manufacturers meeting FSSAI food-contact standards face limited competition from organized players in tier-2 cities. BIS certification gaps create first-mover advantages for compliant local producers. Maharashtra and Gujarat concentrate emerging molding capacity serving both domestic demand and export markets.
Italy
Pediatric dental associations endorse orthodontic-grade silicone pacifiers, creating institutional pull-through for premium SKUs. ECHA enforcement actions on cold-chain integrity documentation favor converters investing in passive thermal packaging. Lombardy and Emilia-Romagna host specialty retailers curating bluesign-verified assortments.
Silicone Baby Product Market Competitive Landscape
Concentration sits with automated liquid injection molders and heritage pediatric nursing brands. The vendor base stratifies across capital-intensive volume producers, orthodontic design specialists, and regional private-label fabricators. Three archetypes dominate: automated molders with compliance infrastructure, hospital-channel credential holders, and subscription-based direct-to-parent platforms. Competitive moves center on automation arms races and certification-driven retail positioning.
Within the heritage pediatric nursing tier, Pigeon Corporation and MAM Baby Articles AG occupy positions anchored by decades of institutional credibility. Among automated volume producers, JEWELIVES exemplifies cost-advantage sustainability through scale. Z.S.R International Group represents Chinese manufacturing consolidation serving both domestic GB-standard compliance and export FDA notification requirements.
| Leading Market Players |
|---|
| JEWELIVES |
| NEWTOP SILICONE |
| Melikey Silicone |
| Pigeon Corporation |
| KEAN |
| Mushie |
| JUTION Silicone |
| MAM Baby Articles AG |
| Z.S.R International Group |
| Others |
Pricing and Supply Chain Analysis
Platinum-cured liquid silicone rubber displacing thermoplastic elastomers in feeding accessories is redrawing manufacturing geography toward Guangdong and Bavaria while compressing margin structures for molders without automated injection lines. Parents in California and Germany now cross-reference FDA food-contact notifications and REACH siloxane certificates before purchase, converting compliance documentation into retail positioning currency that separates premium-tier from commodity-tier suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in silicone baby goods. Price differentiation rests on FDA 510(k) certification tier and Shore A hardness specification, with orthodontic-grade LSR commanding premiums over food-grade alternatives. Cost compression in the standard tier is intensifying because automotive sector demand for silicone HCR strains platinum catalyst allocation. Childcare center procurement teams exhibit highest price sensitivity due to bulk volume requirements, while grandparent gift purchasers show lowest sensitivity to unit pricing.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are forcing Italian and Polish converters toward passive thermal packaging investments for temperature-sensitive LSR shipments. Feedstock concentration in Germany, China, and the United States shapes raw material access, with Wacker and Dow controlling pharmaceutical-grade LSR supply. The supply chain draws from platinum catalysts, medical-grade silicone base polymers, and precision mold tooling. Single-source medical-grade silicone dependency creates structural vulnerability for teething toy producers. Distribution runs through direct-to-parent subscription platforms, specialty retailers with front-of-store certification positioning, and mass-market supermarket channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down schedules and REACH compliance migration are disrupting established supply chains while creating first-mover advantages for cold-chain-certified molders. This regulatory inflection compresses product refresh cycles and privileges capitalized producers with dedicated compliance infrastructure.
For Market Incumbents: Consolidate automated liquid injection molding capacity in the Yangtze River Delta and Pearl River Delta to defend against mid-tier automation arms races. Acquire passive thermal packaging capabilities or partner with Bavarian automotive suppliers repurposing two-shot molding lines. Certification investment in simultaneous GB 4806.11, REACH, and FDA compliance functions as the priority defensive lever against emerging Chinese manufacturers with NMPA-equivalent credentials.
For New Entrants and Emerging Players: India's BIS certification fast-track creates white-space access in tier-2 cities where FSSAI-compliant domestic manufacturers face limited organized competition. Target subscription-based direct-to-parent replenishment models bypassing retail slotting fees. Hospital-channel credentialing through pediatric dental associations in Italy and Spain offers the most penetrable institutional entry point.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated molders with compliance infrastructure over artisanal producers. Long-term viability across the projection horizon hinges on biobased silicone feedstock adoption and Scope 3 emissions positioning. Acquisition target archetype: mid-cap LSR processors with dual GB-FDA certification stacks. Watch ECHA's expanding PFAS restriction scope as the signal for forced material reformulation across entire product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Liquid Injection Molding Scale-Up | JEWELIVES sustains cost advantages at volume against artisanal competitors. |
| Backward Integration into Platinum Catalyst Supply | Long-term supply contracts with Wacker or Dow reduce input risk exposure. |
| Direct-to-Consumer Subscription Launch | Staged feeding-set upgrades capture lifetime value while bypassing retail economics. |
| Biobased Silicone Feedstock Adoption | German chemical consortia pilot renewable methanol-to-silicone pathways for Scope 3 reduction. |
| Hospital-Channel Credentialing Expansion | MAM Baby Articles AG leverages orthodontic design heritage for institutional pull-through. |
Research Methodology
The analysis maps platinum-cured LSR teething toys, hybrid overmolded bottles, food-grade bibs, and temperature-sensitive spoons, each validated through procurement managers at childcare centers, pediatric dental association credentialing officers, brand managers at specialty retailers, and liquid injection molding process engineers. Primary interviews with these stakeholders combined with secondary validation against FDA food-contact substance notifications, ECHA REACH compliance databases, China's GB 4806.11 standards, and customs trade flow records. Bottom-up unit economics triangulated against top-down market sizing across the segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-user concentration, distribution channel selection, and feature differentiation as core segmentation dimensions. CAGRs were derived from trend extrapolation of millennial and Gen-Z parent adoption curves, institutional procurement expansion, and channel shift dynamics. Forecast inputs included platinum catalyst cost volatility indices and EU F-Gas Regulation implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained middle-class consumption growth in China and continued REACH-FDA regulatory convergence would require recalibration. Forecasts reflect documented assumptions about sterilization durability requirements and subscription model penetration rates. Practitioners should keep alternative scenarios live as ECHA PFAS restriction scope and biobased silicone production scale evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
France Baby Care Products Market
Baby Products
Baby Bottle Warmers Market
Baby Products
Baby Cradles Market
Baby Products
Baby Tableware Market
Baby Products
Soft Sole Baby Shoes Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Children Products Market
Baby Products
Baby Care Products Market
Baby Products
Italy Baby Care Products Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Smart Pacifier Market
Baby Products
Brazil Baby Care Products Market
Baby Products
Global Baby Pajamas and Sleepwears Market