
 India Baby Care Products Market | 2026-2036
India Baby Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Baby Care Products Market Outlook
Urban hospital maternity wards and pediatric clinics are rebalancing toward premium disposable diaper bundles and medicated wipes as institutional procurement standards tighten. Himalaya Global Holdings Ltd. leverages its Ayurvedic ingredient sourcing network to dominate natural-positioned baby oils and lotions in South Indian states. Johnson & Johnson sustains brand trust through decades-long relationships with private maternity chains and government immunization outreach programs. Honasa Consumer Pvt. Ltd. competes aggressively via direct-to-parent digital subscription models that bypass traditional wholesale markups entirely.
India baby care products encompass formulated skincare, hygiene disposables, and nutritional supplements engineered for infants up to thirty-six months, with pH-balanced surfactant systems and hypoallergenic textile layers serving as critical technical parameters for skin-safe performance. Diapers and wipes together anchor the bulk of volume throughput, though lotions and oils carry superior per-unit margin profiles due to concentrated herbal actives and smaller batch production economics. The sales channel structure is fragmenting as online platforms capture urban parent loyalty through subscription replenishment, while supermarkets retain decisive influence in semi-urban catchments where tactile product evaluation still drives purchase confidence.
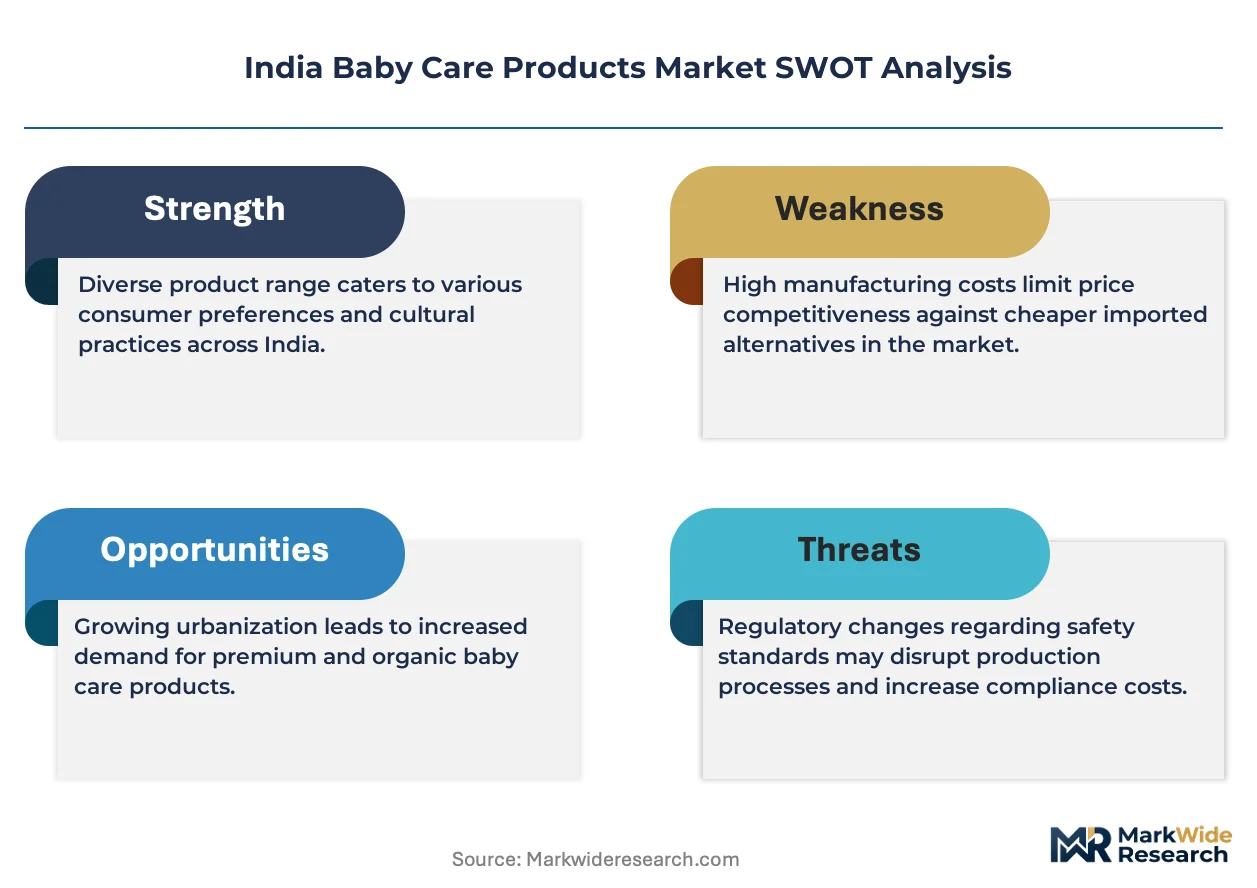
BIS certification mandates for infant cosmetic safety and the CDSCO framework governing nutritional fortification claims create dual compliance gateways that filter out unorganized competitors lacking laboratory testing infrastructure. The PLI scheme for domestic FMCG manufacturing further tilts procurement incentives toward local production facilities with scale-verified quality systems. Stakeholders must monitor evolving FSSAI labeling requirements for baby food adjacencies and anticipate state-level maternity benefit expansions that could redirect institutional purchasing toward certified national suppliers over imported alternatives.
Market Dynamics
Urban millennial parents in tier-1 and tier-2 cities are compressing purchase cycles through digital-first subscription models while BIS certification mandates filter out unorganized competitors lacking laboratory infrastructure.
Growth Catalysts
- PLI scheme incentives:The government's production-linked incentive scheme for domestic FMCG manufacturing redirects procurement toward local facilities with scale-verified quality systems.
- E-commerce logistics expansion:Organized retail penetration in Maharashtra, Karnataka, and Tamil Nadu supports sustained volume growth through last-mile delivery infrastructure.
- Institutional procurement tightening:Urban hospital maternity wards are rebalancing toward premium disposable diaper bundles as procurement standards elevate.
Market Restraints
- Input cost volatility:Concentrated herbal actives sourcing from Ayurvedic networks creates margin pressure when monsoon patterns disrupt agricultural yields.
- Regulatory friction:Dual CDSCO and FSSAI compliance gateways for nutritional fortification claims extend product launch timelines by 8-14 months.
- Supply concentration risk:pH-balanced surfactant systems depend on specialized chemical imports through Mumbai and Chennai port clusters.
Strategic Opportunities
- Semi-urban tactile retail:Supermarkets in tier-3 catchments retain decisive influence where product evaluation still drives purchase confidence.
- Ayurvedic ingredient convergence:Natural-positioned formulations combining traditional herbals with modern dermatological testing capture parent trust.
- State maternity benefit expansions:Evolving state-level programs could redirect institutional purchasing toward certified national suppliers.
Industry Challenges
- Certification timeline compression:BIS mandatory quality certification for infant skincare formulations requires extended laboratory validation cycles.
- Skill scarcity in formulation science:pH-balanced surfactant engineering and hypoallergenic textile layer design demand specialized talent pools concentrated in Bangalore and Hyderabad.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Baby Care Products Market |
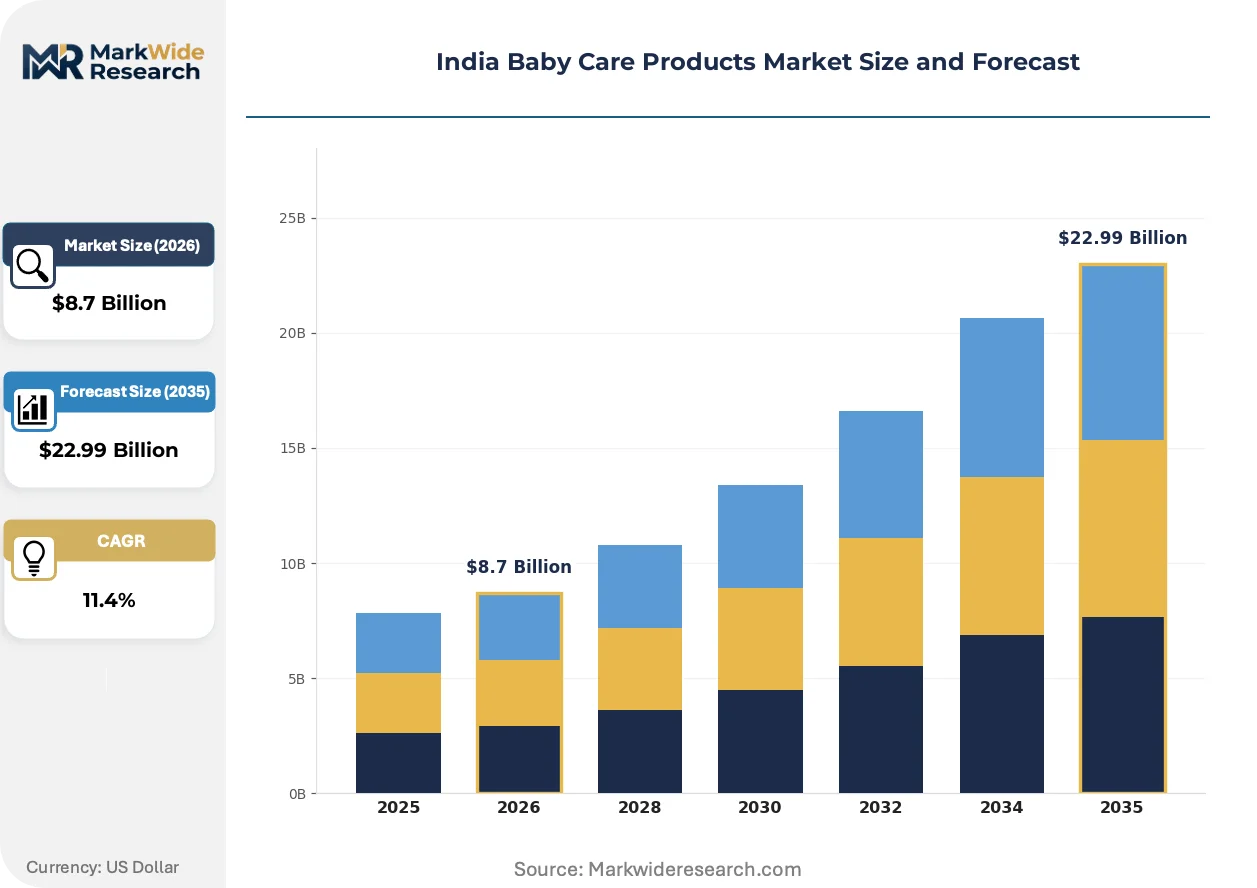
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diapers, Wipes, Lotions, Oils Sales Channel: Online, Supermarkets, Drugstores, Specialty Stores Customer Type: Parents, Caregivers, Hospitals, Clinics Brand Type: Local Brands, International Brands, Organic Options, Eco-Friendly |
| Companies Covered | Procter & Gamble Co., Johnson & Johnson, Nestlé SA, Kimberly-Clark Corporation, Himalaya Global Holdings Ltd., Dabur India Ltd., Honasa Consumer Pvt. Ltd., Patanjali Ayurved Ltd., Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Baby Care Products Market Strategic Shifts
Subscription-based replenishment models are fragmenting traditional wholesale structures while regulatory digitization accelerates compliance verification timelines.
Plant-derived surfactant systems are overtaking petroleum-based alternatives in premium diaper and wipe formulations. Tier-1 urban parents are adopting these at compressed switching cycles of 60-90 days. The shift is compressing margin structures for legacy chemical suppliers while enabling Ayurvedic-positioned brands to command shelf-space premiums.
BIS certification digitization is streamlining infant cosmetic safety verification through centralized laboratory data portals. The industrial consequence is accelerated batch-release timelines for organized manufacturers with captive testing facilities. South Indian states with established Ayurvedic testing infrastructure are responding fastest to this procedural shift.
Direct-to-parent digital subscriptions are displacing traditional distributor networks in metropolitan catchments. Urban millennial buyers now expect automated replenishment with pediatrician-curated bundles. Maharashtra and Karnataka display the highest platform loyalty metrics as hospital discharge protocols integrate branded starter kits.
India Baby Care Products Market Segmentation
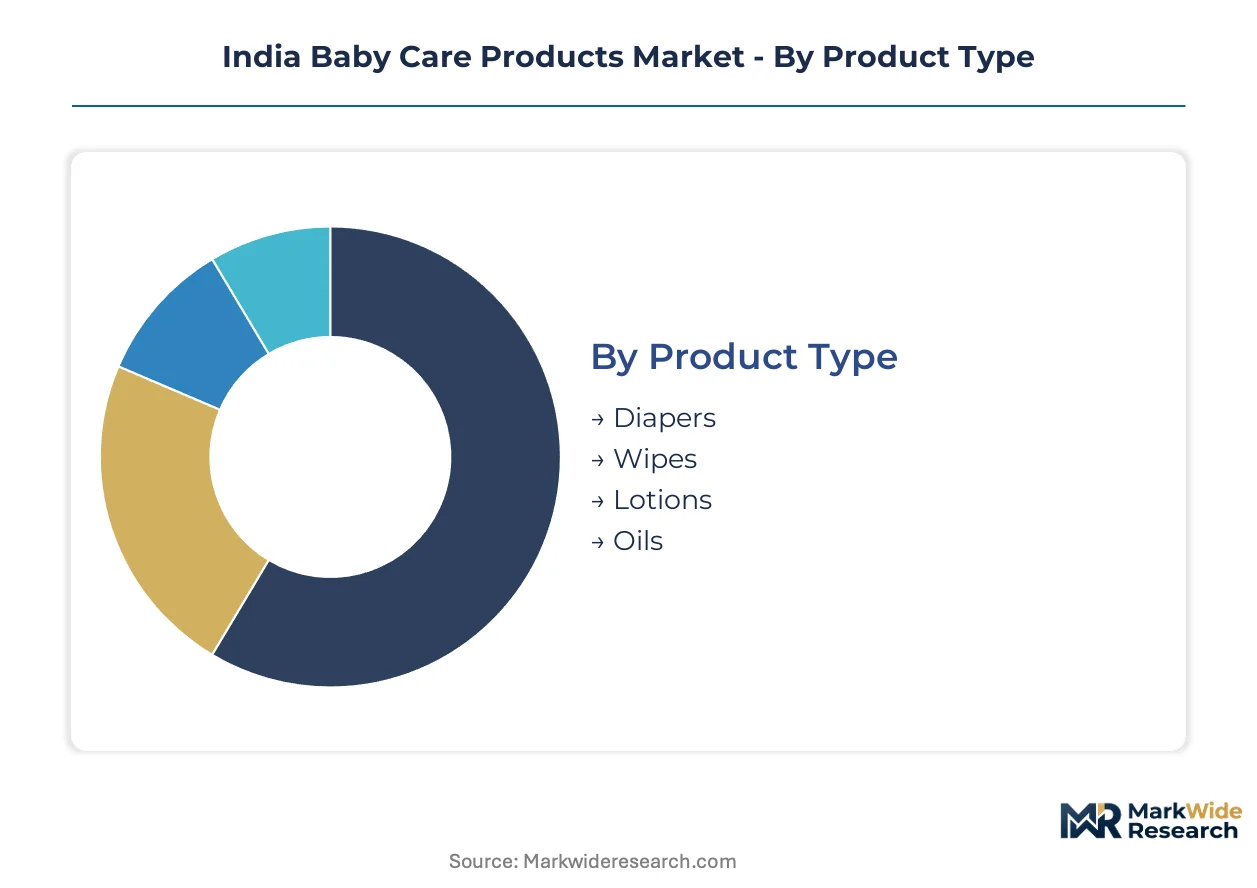
Product portfolios in the India baby care products market fragment across four intersecting dimensions, each carrying distinct margin profiles and compliance burdens. Understanding where volume concentrates versus where premiums extract reveals procurement leverage points for both manufacturers and institutional buyers.
Product Type:
Diapers anchor volume throughput while lotions and oils command superior per-unit economics through concentrated herbal actives and smaller-batch production.
- Diapers:Disposable diaper bundles with hypoallergenic textile layers and plant-derived absorbent cores dominate institutional procurement from urban hospital maternity wards. Maharashtra and Karnataka absorb the highest throughput volumes where e-commerce logistics infrastructure supports subscription replenishment cycles.
- Lotions:pH-balanced surfactant systems infused with Ayurvedic herbals target parent preference for natural-positioned dermatological safety. Tamil Nadu's established Ayurvedic testing infrastructure accelerates BIS certification timelines for regional manufacturers.
- Wipes:Medicated wipe formulations with aloe vera and chamomile extracts serve clinical hygiene protocols in pediatric clinics.
- Oils:Cold-pressed sesame and almond oil blends retain traditional positioning in semi-urban catchments where tactile product evaluation drives purchase confidence.
Mature deployment sits with diapers. Newer deployment is concentrated in lotions with Ayurvedic ingredient convergence.
Sales Channel:
Channel fragmentation accelerates as digital-first subscription models displace traditional distributor networks in metropolitan catchments while physical retail retains decisive influence in tier-3 cities.
- Online:Direct-to-parent digital platforms with automated replenishment and pediatrician-curated bundles capture urban millennial loyalty. Honasa Consumer's subscription models bypass wholesale markups entirely in Maharashtra and Karnataka.
- Supermarkets:Organized retail penetration in tier-2 cities enables tactile product evaluation for parents prioritizing immediate availability over delivery convenience.
- Drugstores:Pharmacy chains with certified pharmacist consultation support medicated wipe and lotion purchases for post-natal care regimens.
- Specialty Stores:Mother-and-child boutiques in South Indian states curate premium organic and eco-friendly assortments with Ayurvedic ingredient transparency.
Volume leadership belongs to online channels. Margin expansion concentrates in specialty stores with certified natural positioning.
Customer Type:
Procurement authority splits between individual decision-makers and institutional buyers with tightening certification requirements.
- Parents:Urban millennial parents in tier-1 cities compress purchase cycles through premiumization and digital-first behaviors, prioritizing BIS-certified safety claims.
- Caregivers:Extended family members and domestic childcare providers in semi-urban households favor economy-tier disposables with established brand recognition.
- Hospitals:Urban hospital maternity wards rebalance procurement toward premium disposable diaper bundles as institutional standards elevate under CDSCO framework alignment.
- Clinics:Private pediatric clinics integrate branded starter kits into discharge protocols, creating captive demand for lotion and oil adjacencies.
Institutional volume concentrates with hospitals. Individual spending growth is climbing the fastest among tier-1 parents.
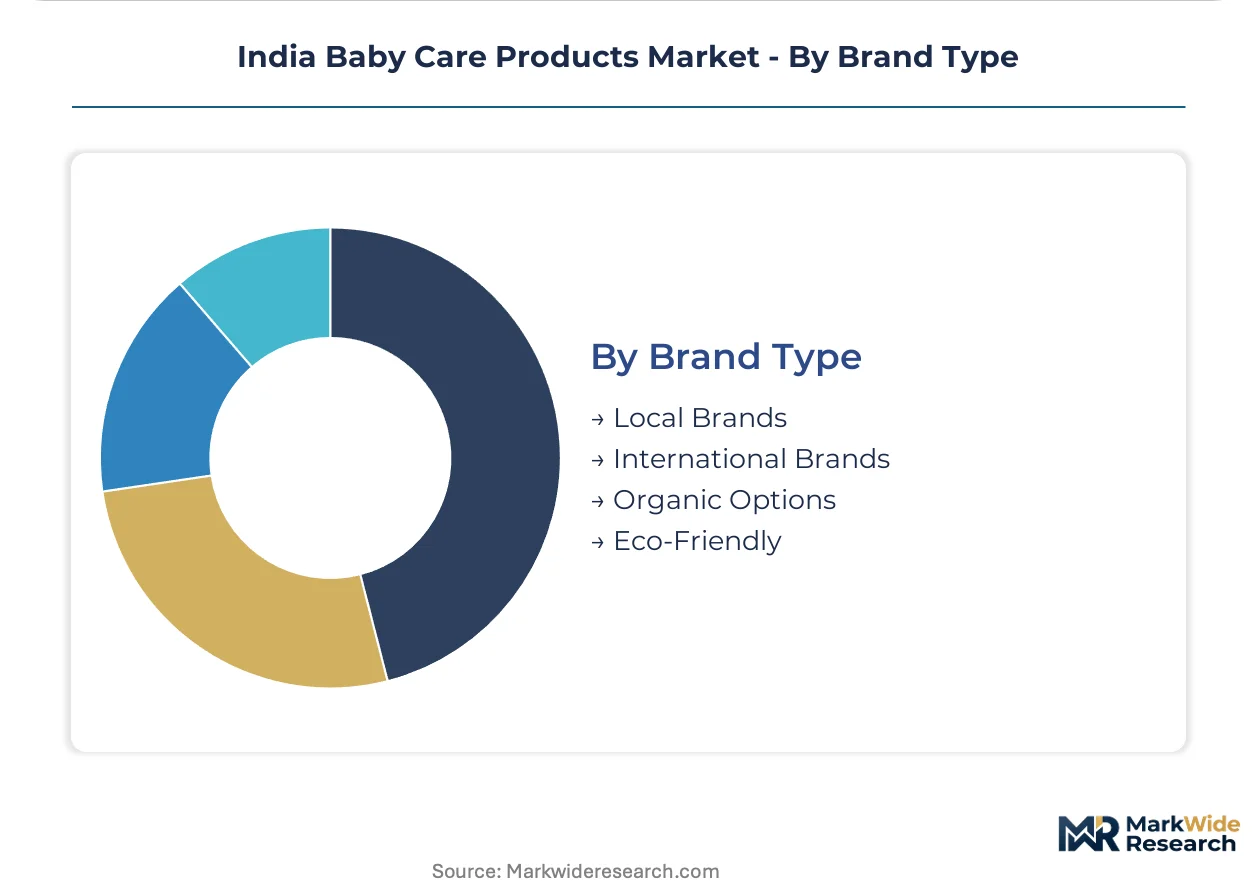
Brand Type:
Brand positioning stratifies across certification tiers, with Ayurvedic heritage and eco-friendly claims commanding shelf-space premiums.
- Local Brands:Domestic manufacturers leverage PLI scheme incentives and captive BIS testing facilities in Bangalore and Hyderabad to compress batch-release timelines.
- International Brands:Decades-long relationships with private maternity chains sustain trust, though import dependency for specialized surfactants creates margin pressure.
- Organic Options:FSSAI-aligned labeling for chemical-free claims targets parent anxiety around infant skin sensitivity, with South Indian states responding fastest to certification digitization.
- Eco-Friendly:Biodegradable diaper cores and plant-derived packaging address urban environmental consciousness in Karnataka and Maharashtra metropolitan catchments.
Established penetration rests with local brands. Steepest expansion trajectory belongs to organic options with dual BIS-FSSAI compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives and BIS certification infrastructure are concentrating manufacturing investment in designated special economic zones across Maharashtra, Karnataka, Tamil Nadu, Telangana, and Gujarat. These five states collectively anchor domestic production capacity for infant skincare and hygiene disposables.
Maharashtra
Mumbai and Pune metropolitan corridors drive premium diaper subscription volumes through dense e-commerce logistics networks. The state's FSSAI regional laboratory accelerates nutritional supplement labeling approvals for fortified baby foods. Industrial clusters in Thane and Nashik house PLI-registered facilities producing pH-balanced surfactant systems for lotion formulations.
Karnataka
Bangalore's formulation science talent pool supplies specialized surfactant engineering capabilities for hypoallergenic textile layer design. CDSCO zonal offices in the city streamline clinical trial approvals for medicated wipe products. Mysuru and Hubli-Dharwad manufacturing belts concentrate Ayurvedic ingredient processing for cold-pressed oil blends.
Tamil Nadu
Chennai port clusters handle specialized chemical imports for surfactant-dependent production lines. The state's established Ayurvedic testing infrastructure compresses BIS certification timelines for herbal-positioned lotions. Coimbatore and Madurai industrial zones produce biodegradable diaper cores targeting urban environmental consciousness.
Telangana
Hyderabad's pharmaceutical research ecosystem feeds talent into pediatric dermatology formulation teams. State-level maternity benefit expansions are redirecting institutional procurement toward certified national suppliers over imported alternatives. Medchal and Ranga Reddy districts host contract manufacturing facilities serving D2C subscription brands.
Gujarat
Surat and Ahmedabad chemical processing hubs supply petroleum-alternative plant-derived surfactants for premium wipe formulations. The state's port infrastructure reduces import lead times for specialized textile layer materials. Gandhinagar regulatory coordination offices facilitate dual CDSCO-FSSAI compliance for nutritional fortification claims.
India Baby Care Products Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with Ayurvedic heritage players commanding shelf-space premiums in lotions while multinational hygiene giants anchor diaper volumes. The competitive structure tiers across three archetypes: legacy Ayurvedic houses with captive ingredient networks, multinational FMCG majors with institutional procurement relationships, and digital-native D2C challengers with subscription-first models. Dominant competitive moves include portfolio diversification into adjacent nutritional supplements and backward integration into captive Ayurvedic ingredient sourcing.
Within the Ayurvedic heritage tier, Himalaya Global Holdings Ltd. and Dabur India Ltd. occupy positions defined by decades-long herb cultivation networks and South Indian testing infrastructure access. Johnson & Johnson exemplifies the multinational institutional model through private maternity chain relationships, while Honasa Consumer Pvt. Ltd. anchors the digital-native archetype with direct-to-parent subscription infrastructure that bypasses traditional wholesale markups entirely in Maharashtra and Karnataka metropolitan catchments.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Johnson & Johnson |
| Nestlé SA |
| Kimberly-Clark Corporation |
| Himalaya Global Holdings Ltd. |
| Dabur India Ltd. |
| Honasa Consumer Pvt. Ltd. |
| Patanjali Ayurved Ltd. |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Formulation science talent concentration in Bangalore and Hyderabad feeds labor-cost differentials that widen pricing-tier spreads between premium Ayurvedic-positioned lotions and economy-tier disposables. This workforce geography compresses margin structures for mid-tier players while enabling certified manufacturers to extract shelf-space premiums through BIS-validated safety claims.
Pricing Analysis
Compressed lead times command measurable premiums in Maharashtra and Karnataka metropolitan catchments where subscription replenishment cycles dominate. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and Ayurvedic ingredient transparency. Cost compression in economy tiers intensifies because raw surfactant imports face port congestion at Mumbai and Chennai clusters. Individual parents in tier-1 cities show lowest price sensitivity for pediatrician-curated bundles, while extended family caregivers in tier-3 catchments prioritize established brand recognition at entry price points.
Supply Chain Analysis
pH-balanced surfactant systems rest on specialized chemical imports through Mumbai and Chennai port clusters, with secondary feedstock dependencies on Gujarat's petroleum-alternative plant-derived processing hubs. Raw material inputs center on concentrated herbal actives from Karnataka's Ayurvedic cultivation networks, hypoallergenic textile layers from Tamil Nadu's industrial zones, and absorbent core polymers from domestic petrochemical streams. Single-source vulnerability concentrates in monsoon-dependent agricultural yields for sesame and almond oil feedstocks. Distribution runs through direct-to-parent digital platforms in metropolitan catchments and supermarket wholesale networks in semi-urban tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India baby care products market reads as a cost-of-compliance story where BIS mandatory quality certification for infant skincare formulations creates a barrier-to-entry moat for organized manufacturers with captive laboratory infrastructure.
For Market Incumbents: Cement institutional procurement relationships through backward integration into captive Ayurvedic ingredient sourcing networks in Karnataka and Tamil Nadu. Deepen hospital maternity ward partnerships before state-level maternity benefit expansions redirect purchasing toward certified national suppliers. Prioritize BIS certification digitization investments to compress batch-release timelines against emerging digital-native challengers.
For New Entrants and Emerging Players: Subscription-first replenishment algorithms offer a technology-first wedge into Maharashtra and Karnataka metropolitan catchments where platform loyalty metrics already favor automated pediatrician-curated bundles. Target semi-urban tier-3 supermarket channels where tactile product evaluation still drives purchase confidence and organized retail penetration remains underdeveloped. Deploy direct-to-parent digital models with bypassed wholesale markups as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic contract manufacturers possessing PLI-registered facilities and dual CDSCO-FSSAI compliance capabilities given government procurement incentives tilting toward local production. Long-term viability across the analysis window favors archetypes with integrated formulation science talent pools and captive testing infrastructure. Watch for state-level maternity benefit program expansions as the inflection indicator redirecting institutional volume toward certified national suppliers over import-dependent alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ayurvedic Sourcing | Captive herb cultivation networks in Karnataka compress input cost volatility from monsoon disruption. |
| BIS Certification Digitization Investment | Centralized laboratory data portals accelerate batch-release timelines against unorganized competitors. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models bypass wholesale markups in Maharashtra and Karnataka metropolitan catchments. |
| State Maternity Benefit Program Alignment | Certified national suppliers capture redirected institutional procurement from urban hospital wards. |
| Semi-Urban Supermarket Channel Expansion | Tactile product evaluation in tier-3 cities retains decisive influence over digital-native alternatives. |
Study Parameters
Trade publications, BIS regulatory filings, and CDSCO approval databases formed the secondary backbone, supplemented by customs records tracking surfactant import flows through Mumbai and Chennai ports. Primary interviews with brand managers at Ayurvedic heritage houses, category buyers at organized retail chains, supply planners at diaper manufacturers, and procurement leads at private maternity hospital chains validated demand-side assumptions. Bottom-up volume modeling across product type, sales channel, and customer type segments was cross-checked against top-down macroeconomic consumption indicators.
Historical trendline analysis tracked segment-level growth trajectories across the projection horizon without anchoring to specific base periods. The analytical framework modeled four segmentation dimensions: product type with technical parameter differentiation, sales channel with digital-physical hybrid dynamics, customer type with institutional-individual split, and brand type with certification tier stratification. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce penetration rates and PLI scheme incentive uptake. Industry-specific forecast inputs included monsoon pattern correlations for herbal active yields and port congestion indices for surfactant import lead times.
Several conditions sit outside the modeled scope, including unforeseen regulatory amendments to FSSAI labeling requirements, abrupt shifts in state-level maternity benefit program designs, and extreme weather events disrupting Karnataka's Ayurvedic cultivation networks. Forecasts reflect documented assumptions about urban millennial parent behavioral continuity and e-commerce logistics infrastructure expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Automatic Baby Swing Market
Baby Products
Global Smart Connected Baby Monitors Market
Baby Products
Cloth Diapers Market
Baby Products
Stroller Rental Market
Baby Products
Baby Swaddle Wrap Market
Baby Products
South Korea Baby Care Products Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Walker Market
Baby Products
Maternity Products Market
Baby Products
Puppy Teething Toys Market
Baby Products
Home Care Packaging Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Global Baby Play Mats Market
Baby Products
South Africa Baby Care Products Market
Baby Products
Kids Training Pant Market
Baby Products
Diaper Pails Market