
 Kids Training Pant Market | 2026-2036
Kids Training Pant Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Training Pant Market Intelligence
Consolidation among large childcare chains is repositioning procurement power toward institutional buyers who negotiate bulk contracts with manufacturers. Kimberly-Clark leverages its North American distribution network to supply national daycare operators with consistent volume commitments. Ontex Group anchors its competitive stance through European private-label partnerships with pharmacy and grocery retailers. Procter & Gamble competes by sustaining brand recognition among first-time parents through pediatric clinic sampling programs.
Kids training pants are absorbent, elastic-waist garments engineered with superabsorbent polymer cores and breathable outer laminates to manage toddler transitional hygiene between diapers and underwear. Manufacturing employs hot-melt adhesive bonding and ultrasonic sealing to create leak-resistant leg cuffs without rigid fasteners that restrict movement. Pull-ups dominate volume in the product type category due to their alignment with self-dressing motor skill development in children aged eighteen to thirty-six months. Breathable laminates command premium positioning within the material dimension as parents prioritize dermatological comfort and reduced thermal irritation during extended wear. Daycare centers and preschools represent the fastest-expanding application channel, driven by facility mandates for individually packaged, name-labeled garments that simplify inventory management.
The US FDA oversees absorbent hygiene products as medical devices when marketed with therapeutic claims, while the EPA regulates chemical emissions from adhesive and film manufacturing processes. REACH compliance in Europe restricts certain absorbent polymers and fragrance additives, forcing reformulation investments for exporters serving EU member states. China's SAMR enforces GB standards for infant product safety, including migration limits on formaldehyde and soluble heavy metals in textile layers. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that could mandate take-back programs for disposable training pant components.
Market Dynamics
Consolidation among national daycare chains is compressing procurement timelines and forcing manufacturers to restructure volume commitments around institutional specifications for individually packaged, name-labeled garments.
Growth Catalysts
- Urban Middle-Class Transition:Chinese parents in tier-one and tier-two cities are abandoning traditional cloth diapers for disposable training solutions as household incomes rise and apartment living constrains laundry facilities.
- REACH Compliance Investments:European chemical safety frameworks are accelerating reformulation of absorbent polymers and fragrance additives, creating first-mover advantages for manufacturers with certified clean-label portfolios.
- SAMR Enforcement:China's GB standards for infant product safety are tightening migration limits on formaldehyde and soluble heavy metals, disqualifying smaller regional competitors and concentrating shelf space among compliant suppliers.
Market Restraints
- Superabsorbent Polymer Feedstock Volatility:Petroleum-derived acrylate monomers expose margins to crude price swings and refinery capacity constraints in the US Gulf Coast.
- Adhesive Supply Concentration:Hot-melt adhesive formulations depend on a narrow base of specialty chemical suppliers clustered in Germany and the Netherlands, creating single-source vulnerability.
- California EPR Legislation:Pending extended producer responsibility mandates for disposable hygiene components threaten to impose take-back infrastructure costs without established recycling pathways for multi-layer laminates.
Strategic Opportunities
- Indian Urban Penetration:Metro areas in Maharashtra and Karnataka show accelerating trial rates for pull-up formats among dual-income households with limited domestic help.
- Pediatric Clinic Sampling:Direct-to-parent distribution through well-baby appointments bypasses retail markup and builds brand preference before store-aisle decision points.
- Biodegradable Core Materials:Convergence of cellulose-based absorbents and compostable outer films aligns with EU Green Deal procurement preferences in Scandinavian municipal childcare contracts.
Industry Challenges
- Ultrasonic Sealing Technician Scarcity:Leak-resistant leg cuff manufacturing requires specialized equipment operators with polymer welding expertise that outpaces vocational training output.
- Multi-Jurisdiction Certification Lag:Simultaneous FDA medical device registration, REACH dossier preparation, and SAMR GB testing extends product launch timelines by fourteen to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Training Pant Market |
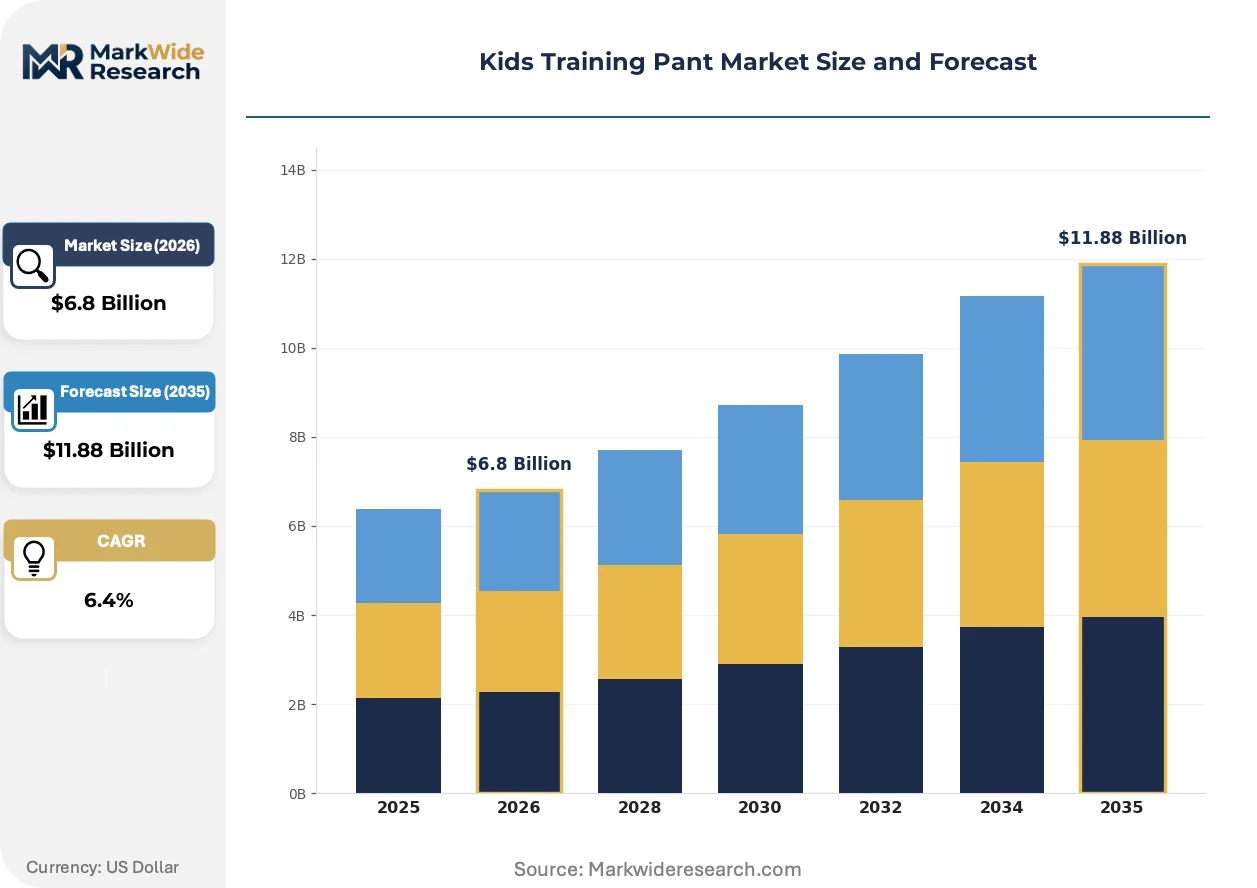
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pull-Ups, Tape-Style Pants, Pants with Reusable Covers, Pants with Disposable Covers Material: Non-Woven Fabric, Polyethylene Film, Absorbent Polymer, Cotton, Breathable Laminates Application: Home Use, Daycare Centers, Preschools, Outdoor Activities, Travel Customer Type: Parents, Caregivers, Pediatric Clinics, Childcare Providers, Hospitals |
| Companies Covered | Hanesbrands, Ontex Group, Procter & Gamble, Daio Paper Corporation, KAO, Kimberly-Clark, Bambino Mio, The Honest Company, Gerber Childrenswear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Training Pant Market Strategic Shifts & Innovations
Material science breakthroughs and channel restructuring are compressing traditional supply hierarchies while regulatory fragmentation forces parallel compliance investments across multiple jurisdictions.
Plant-based superabsorbent polymers derived from modified starches are decentralizing capacity planning for manufacturers seeking to reduce petrochemical dependency. European private-label suppliers are adopting these materials fastest, driven by retailer sustainability scorecards. This decentralization is fragmenting raw material sourcing strategies and complicating inventory hedging across regional production networks.
REACH restrictions on certain fragrance additives and absorbent polymers are forcing systematic reformulation of core product lines for EU market access. Manufacturers serving multiple geographies must maintain parallel SKUs with divergent chemical compositions. Private-label partnerships with pharmacy chains face the steepest compliance cost escalation due to narrower margin structures.
Institutional procurement through consolidated daycare chains is displacing fragmented retail purchasing as the dominant volume channel. National operators now negotiate direct manufacturer contracts with customized packaging specifications. This concentration is most advanced in the United States, where three childcare chains control procurement for over twelve thousand licensed facilities.
Kids Training Pant Market Segmentation
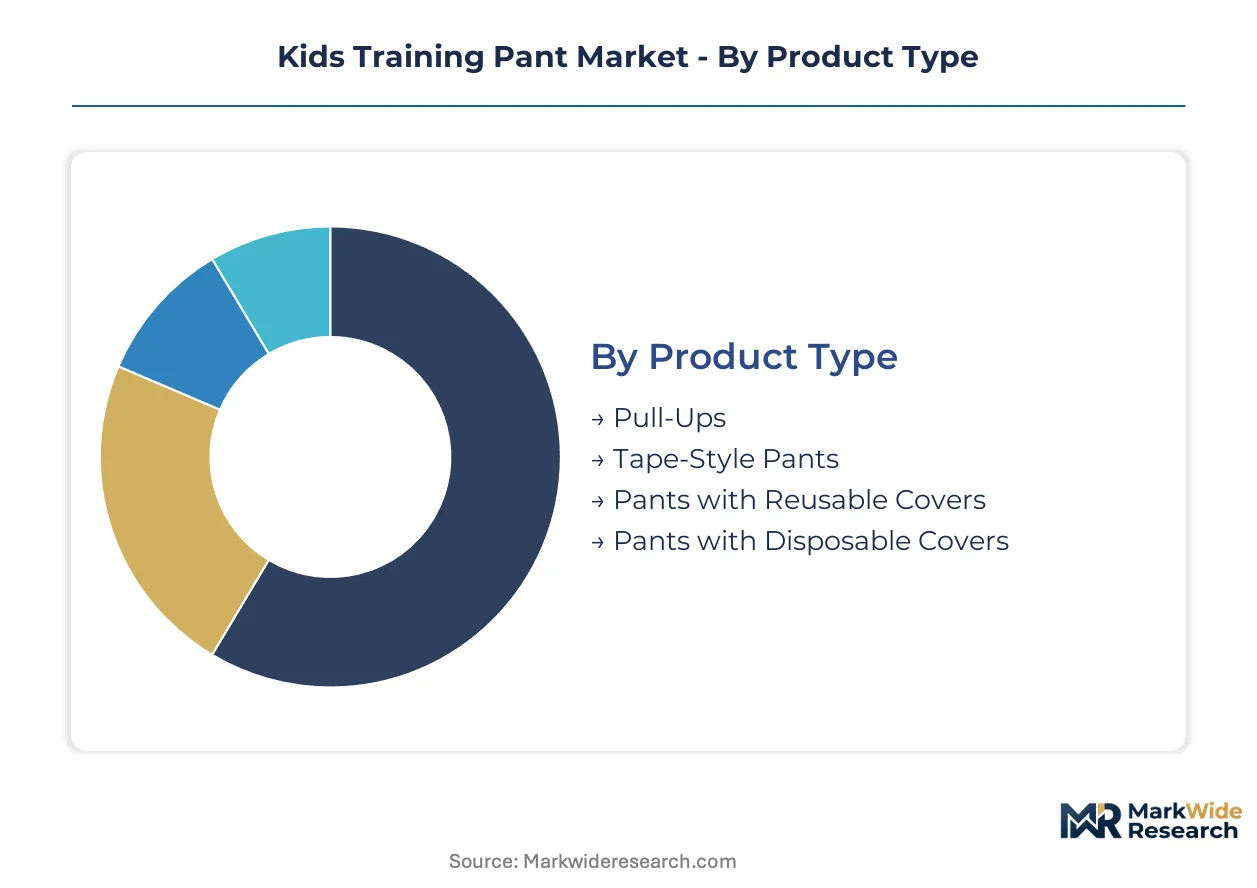
Segmentation in the kids training pant market reveals how manufacturing capacity aligns unevenly across product architectures, material technologies, and procurement channels. Supply concentration in specific segments creates margin pressure and competitive entry barriers that reshape stakeholder positioning.
Product Type:
Supply concentration clusters around formats with established converting equipment and adhesive bonding infrastructure, leaving niche configurations dependent on contract manufacturers.
- Pull-Ups:Elastic-waist garments with superabsorbent polymer cores and tear-away side seams dominate volume production. Demand concentrates in US daycare chains and Chinese urban households where self-dressing skill development drives parental preference. Hot-melt adhesive throughput and ultrasonic sealing capacity constrain supply expansion.
- Tape-Style Pants:Refastenable side tabs with hook-and-loop closures serve toddlers with delayed motor development or specific medical needs. Procurement runs through pediatric clinics in Germany and hospital discharge programs in Japan where occupational therapists influence product selection. Smaller batch sizes fragment manufacturing efficiency.
- Pants with Reusable Covers:Waterproof PUL outer shells with snap-in absorbent inserts appeal to sustainability-focused parents in Scandinavian municipal childcare systems. Limited domestic washing infrastructure in emerging markets restricts geographic expansion.
- Pants with Disposable Covers:Hybrid systems combining biodegradable inner pads with compostable outer layers target EU Green Deal procurement criteria. Pilot programs in Dutch and Belgian daycare chains test volume feasibility.
Pull-Ups absorb the bulk of installed capacity; pants with disposable covers are expanding most quickly.
Material:
Cost tier stratification separates commodity inputs from certified clean-label portfolios that command procurement preference in regulated European and Asian markets.
- Breathable Laminates:Microporous polyethylene films bonded to non-woven substrates reduce thermal irritation and dermatological complaints during extended wear. Premium positioning in Japanese pharmacy retail and South Korean department store channels reflects parental willingness to pay for comfort certification. REACH compliance documentation adds 12-18% to raw material sourcing costs.
- Absorbent Polymer:Cross-linked sodium polyacrylate granules determine fluid retention capacity and garment slimness. Petroleum-derived acrylate monomer supply from US Gulf Coast refineries exposes margins to feedstock volatility. Reformulation investments for phthalate-free alternatives concentrate in German and Dutch specialty chemical suppliers.
- Non-Woven Fabric:Spunbond-meltblown-spunbond polypropylene layers provide acquisition and distribution layers. Standardized specifications enable multi-source procurement from Chinese and Southeast Asian textile converters.
- Polyethylene Film:Extruded backsheet materials offer cost-optimized moisture barrier performance. Volume buyers in Indian mass retail negotiate directly with polymer resin distributors to bypass converter markups.
- Cotton:Natural fiber acquisition layers and outer covers serve niche organic certification segments. Limited domestic spinning capacity in Brazil and Argentina constrains Latin American supply security.
Breathable laminates command the steepest margin premiums; absorbent polymer represents the largest absolute spend category.
Application:
Customer type concentration is shifting procurement power toward institutional buyers with customized packaging specifications and volume commitment structures.
- Daycare Centers:Licensed facilities mandate individually wrapped, name-labeled garments to satisfy health inspection protocols and simplify inventory management. US national chains negotiate direct manufacturer contracts with 90-day procurement cycles. Kimberly-Clark and Ontex Group maintain dedicated institutional sales divisions.
- Home Use:Parental purchasing through mass retail and e-commerce channels prioritizes brand recognition and unit economics. Pediatric clinic sampling programs by Procter & Gamble intercept decision-making before store-aisle comparison.
- Preschools:Transition-focused programs for three-to-five-year-olds require slimmer profiles than standard toddler formats. Procurement runs through regional education cooperatives in France and Italy with fragmented specification authority.
- Outdoor Activities:Extended-wear designs with enhanced leak guards serve camping and travel use cases. Seasonal demand spikes complicate production planning for contract manufacturers.
- Travel:Compact packaging and disposal bag inclusion address airport and hotel convenience needs. Duty-free retail in Dubai and Singapore generates impulse purchase volume.
Home use retains the widest customer base; daycare centers are gaining share fastest.
Customer Type:
Volume concentration among consolidated childcare chains is compressing margin structures while fragmenting specification requirements across regulatory jurisdictions.
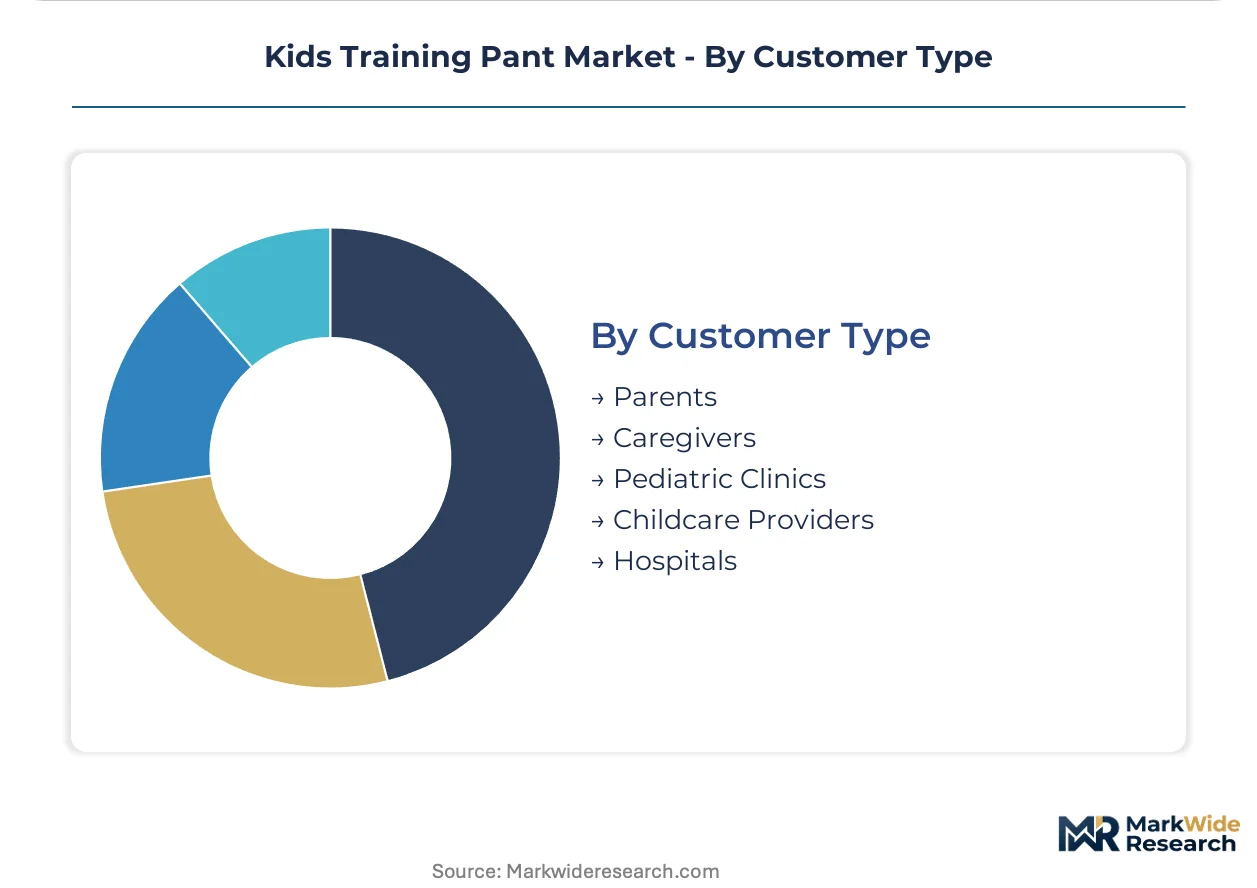
- Childcare Providers:National and regional daycare operators consolidate procurement for multi-site networks with standardized product configurations. US chains controlling over twelve thousand licensed facilities negotiate bulk contracts with exclusive supply arrangements.
- Parents:First-time and experienced caregivers drive trial and repeat purchase through retail and direct-to-consumer channels. Chinese urban middle-class parents in tier-one cities exhibit highest per-capita consumption intensity.
- Pediatric Clinics:Well-baby appointment sampling programs build brand preference before competitive exposure. Japanese and South Korean clinic networks maintain strict product registration requirements.
- Caregivers:Extended family members and domestic staff influence purchasing in multi-generational households. Limited brand loyalty creates price sensitivity in Indian metro areas.
- Hospitals:Neonatal intensive care and pediatric discharge programs specify medical-grade materials with therapeutic claims. FDA device registration requirements extend procurement qualification timelines.
Childcare providers absorb the bulk of institutional volume; pediatric clinics are expanding most quickly as a channel for brand establishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class parents in tier-one Chinese cities drive the steepest volume expansion for disposable training solutions, while institutional procurement through consolidated daycare networks restructures demand geography across multiple continents.
United States
Three national childcare chains control procurement for over twelve thousand licensed facilities, negotiating direct manufacturer contracts with customized packaging specifications. The EPA and state-level frameworks tighten restrictions on phthalates and volatile organic compounds in infant textiles. Manufacturing capacity clusters in Wisconsin and South Carolina serve institutional buyers with consistent volume commitments.
China
Tier-one and tier-two cities exhibit accelerating abandonment of traditional cloth diapers as household incomes rise and apartment living constrains laundry facilities. SAMR enforces GB standards for infant product safety with tightening migration limits on formaldehyde and soluble heavy metals. Yangtze River Delta manufacturing hubs concentrate compliant supplier capacity for domestic and export markets.
Germany
REACH compliance investments accelerate reformulation of absorbent polymers and fragrance additives, creating first-mover advantages for certified clean-label portfolios. ECHA restrictions disqualify smaller regional competitors from EU market access. Specialty chemical suppliers in North Rhine-Westphalia and Baden-Württemberg dominate phthalate-free adhesive formulation.
Japan
Pediatric clinic sampling programs build brand preference before store-aisle decision points, with well-baby appointment distribution bypassing retail markup. PMDA maintains strict product registration requirements for medical-grade materials with therapeutic claims. Kansai region manufacturing clusters serve pharmacy retail channels with premium breathable laminate specifications.
India
Metro areas in Maharashtra and Karnataka show accelerating trial rates for pull-up formats among dual-income households with limited domestic help. BIS standards for infant textile safety create compliance barriers for unorganized sector suppliers. Mumbai-Pune industrial corridor hosts emerging converting capacity for mass-market breathable laminate production.
Kids Training Pant Market Key Industry Players
North American producers anchor one tier; European specialists hold private-label partnerships with pharmacy and grocery retailers. The vendor base stratifies across three tiers: multinational hygiene conglomerates with institutional sales divisions, regional private-label converters with flexible batch capabilities, and niche organic specialists with limited geographic reach. Strategic moves concentrate on M&A to secure daycare chain contracts and capacity expansion in high-growth Asian markets.
Among the multinational tier, Kimberly-Clark and Procter & Gamble represent divergent channel strategies—one leveraging North American distribution networks for institutional volume, the other sustaining brand recognition through pediatric clinic sampling. Ontex Group anchors the European private-label position through pharmacy and grocery retail partnerships. These three exemplify how scale and channel specialization determine competitive positioning.
| Leading Market Players |
|---|
| Hanesbrands |
| Ontex Group |
| Procter & Gamble |
| Daio Paper Corporation |
| KAO |
| Kimberly-Clark |
| Bambino Mio |
| The Honest Company |
| Gerber Childrenswear |
| Others |
Cost & Logistics Intelligence
Backward integration into superabsorbent polymer production anchors supply security for North American manufacturers while simultaneously insulating margin structures from petroleum feedstock volatility. This captive sourcing strategy concentrates pricing power among vertically integrated producers who negotiate long-term offtake agreements with institutional daycare chains.
Pricing Analysis
Volume-margins split sharply between institutional procurement and retail channels. Three-tier pricing structure across premium, standard, and economy levels separates breathable laminate SKUs with REACH documentation from commodity polyethylene-backed alternatives. Pricing pressure stems from consolidated daycare chains demanding customized packaging at contract-manufacturing rates. Home-use parents exhibit highest price sensitivity; pediatric clinic sampling programs bypass this entirely.
Supply Chain Analysis
Ultrasonic sealing technician scarcity in Wisconsin and South Carolina manufacturing clusters constrains capacity expansion for leak-resistant leg cuff production. Raw material flows draw from German and Dutch specialty adhesive suppliers, US Gulf Coast acrylate monomer refineries, and Yangtze River Delta non-woven converters. Single-source vulnerability in hot-melt adhesive formulations creates chokepoint exposure. Distribution runs through dedicated institutional sales divisions serving national childcare chains alongside mass retail and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based superabsorbent polymers are displacing petroleum-derived acrylate cores, compressing reformulation timelines for manufacturers serving EU Green Deal procurement criteria. This materials transition rewards first-movers with certified clean-label portfolios.
For Market Incumbents: Cement institutional channel control through exclusive supply arrangements with consolidating daycare chains. Prioritize REACH-compliant adhesive reformulation investments to disqualify smaller regional competitors from European pharmacy retail. Backward integration into modified starch absorbent production reduces petrochemical dependency.
For New Entrants and Emerging Players: Municipal childcare cooperatives in Scandinavian markets represent an underserved buyer archetype with compostable procurement mandates. Target biodegradable core material pilots in Dutch and Belgian daycare chains. Bypass retail markup through direct-to-parent subscription models in Indian metro areas.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational hygiene conglomerates seeking institutional sales divisions. Five-to-ten year viability hinges on SAMR compliance infrastructure for Chinese market access. Watch biodegradable material cost parity with petroleum-derived alternatives as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Core Material Scale-Up | Cellulose-based absorbents align with EU Green Deal municipal procurement criteria in Scandinavian markets. |
| REACH-Compliant Adhesive Reformulation | Phthalate-free hot-melt formulations from North Rhine-Westphalia suppliers secure European pharmacy retail shelf space. |
| Institutional Sales Division Expansion | Dedicated teams serving US national daycare chains capture volume commitments with 90-day procurement cycles. |
| Pediatric Clinic Sampling Programs | Well-baby appointment distribution in Japan and South Korea builds brand preference before retail exposure. |
| Yangtze River Delta Manufacturing Footprint | GB-compliant production hubs concentrate capacity for Chinese domestic and export market requirements. |
Research Approach
Trade databases, regulatory filings, and customs records formed the secondary backbone, supplemented by primary interviews with plant managers at converting facilities, procurement leads at national daycare chains, category buyers at pharmacy retailers, and R&D directors at specialty adhesive suppliers. Bottom-up and top-down triangulation validated volume estimates across product architectures and material tiers.
Bottom-up modeling aggregated segment-level demand patterns while top-down cross-checks anchored totals against macroeconomic indicators. Segmentation dimensions included product format, material certification grade, application channel, and regional regulatory cluster. CAGRs derived from trend extrapolation of urban middle-class penetration rates and institutional procurement consolidation trajectories, with SAMR enforcement timelines and REACH restriction phases as industry-specific inputs.
Revisions become necessary when SAMR tightens GB migration limits, California EPR legislation mandates take-back infrastructure, or biodegradable materials achieve cost parity with petroleum-derived alternatives. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Japan Baby Care Product Market
Baby Products
Baby Prams and Strollers Market
Baby Products
Crib Mattress Market
Baby Products
Automatic Baby Swing Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Nail Trimmer Market
Baby Products
Baby Food Dispensing Spoon Market
Baby Products
Baby Seat Liners Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Kids Activity Box Market
Baby Products
North America Baby Bottle Market
Baby Products
Baby Wipes Market
Baby Products
Baby Bottle Market
Baby Products
Baby Bedding Market
Baby Products
Baby Walker Market
Baby Products
Infant Care and Baby Care Equipment Market