
 Baby Wet Wipes Market | 2026-2036
Baby Wet Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Wet Wipes Market Insights
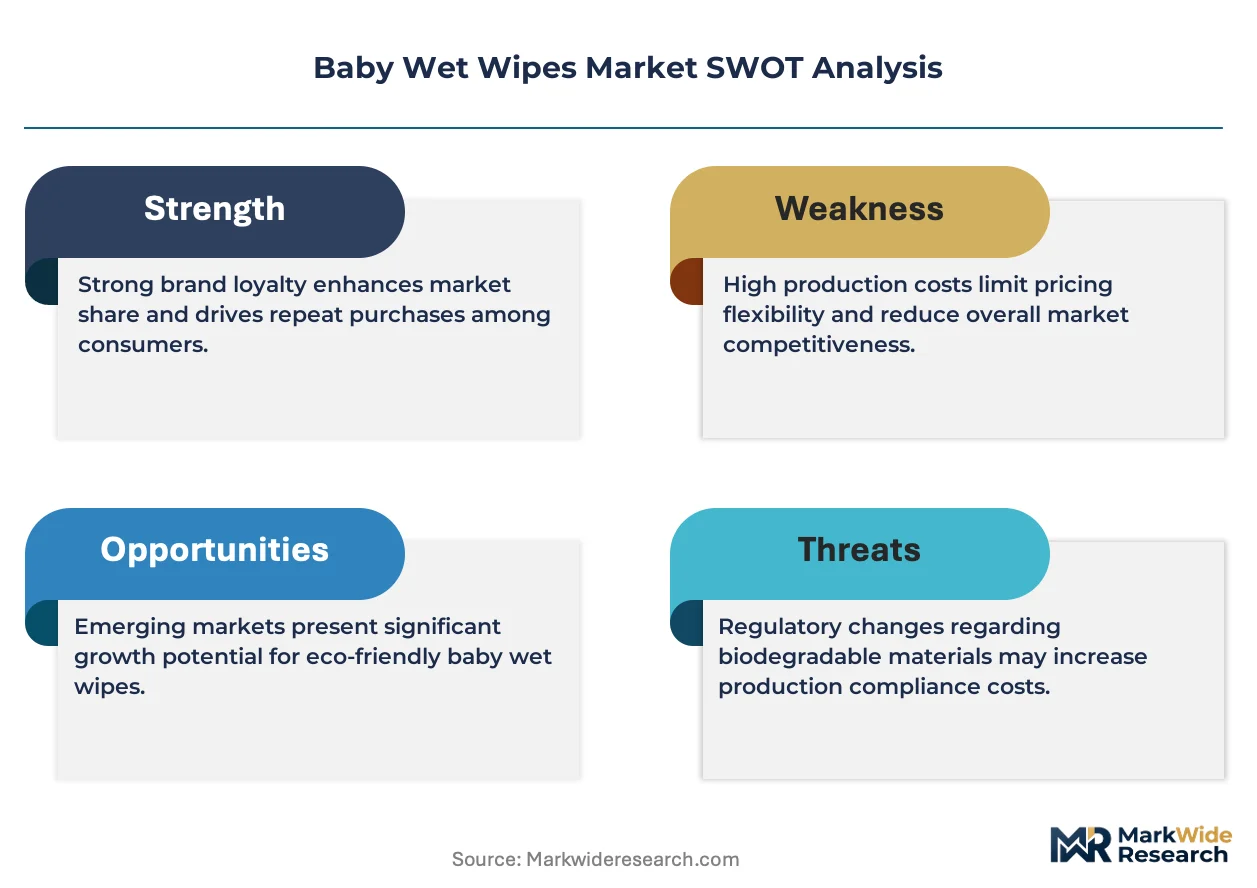
Hospital and daycare procurement is shifting toward bulk-format, dermatologically tested baby wet wipes as institutional hygiene protocols tighten. Procter & Gamble leverages its global distribution network to sustain shelf dominance in mass retail channels. Kimberly-Clark Corporation anchors North American supply through integrated nonwoven substrate production. Albaad specializes in private-label manufacturing, competing on cost flexibility for European pharmacy chains.
Baby wet wipes are pre-moistened disposable cloths, typically composed of spunlace nonwoven fabric saturated with purified water, mild surfactants, and preservative systems, designed for infant skin cleansing and hygiene maintenance. Alcohol-free formulations dominate hospital and neonatal care applications where skin barrier integrity is critical. Fragrance-free segments command premium shelf positioning in pharmacy chains as pediatric dermatologist recommendations concentrate there. Biodegradable substrates represent the fastest-growing product type as EU Green Deal packaging mandates and consumer waste-consciousness reshape procurement criteria.
FDA cosmetic labeling requirements and EPA disinfectant claims oversight shape product classification and marketing boundaries in the United States. ECHA REACH compliance and the EU Single-Use Plastics Directive impose material traceability and biodegradability thresholds that manufacturers must navigate for European market access. China's NMPA and GB standards for infant care products enforce microbial limit and ingredient disclosure rules that foreign entrants must satisfy. Stakeholders should monitor evolving substrate certification schemes and regional chemical restriction timelines to anticipate reformulation costs and sourcing pivots.
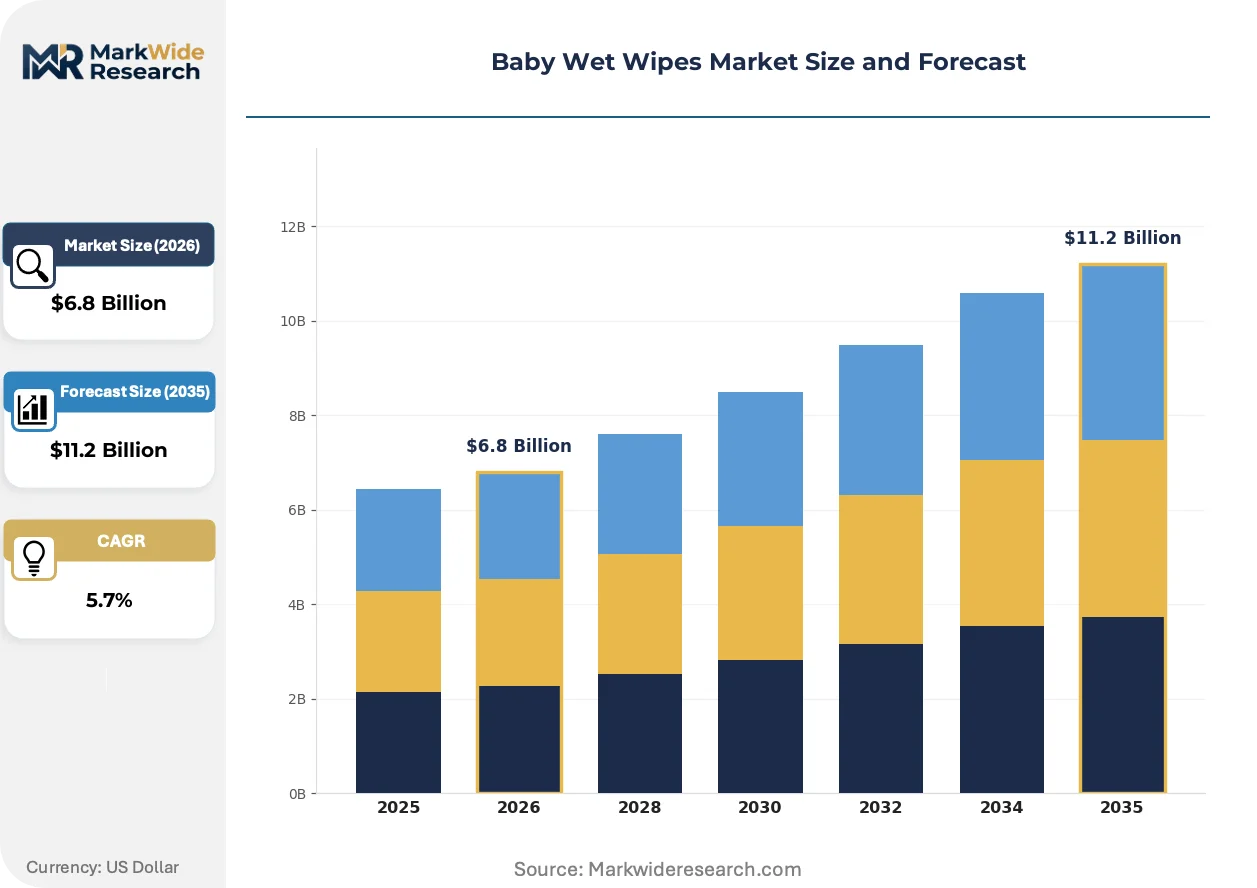
Market Dynamics
Water-free manufacturing technologies and plant-based substrate innovations are compressing production costs while EU Green Deal packaging mandates force rapid material transitions across European supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:Biodegradable substrate demand accelerates as manufacturers reformulate to meet material traceability thresholds for European market access.
- Neonatal care protocols:Hospital hygiene standards tighten institutional procurement criteria, expanding dermatologically tested alcohol-free formulation requirements.
- China urban middle-class expansion:Premium-format adoption concentrates in tier-one cities as disposable income growth reshapes infant care purchasing patterns.
Market Restraints
- Spunlace nonwoven supply concentration:Integrated substrate producers in Asia control critical raw material flows, creating input cost volatility for independent converters.
- Purified water sourcing constraints:Regional aquifer depletion and quality standards raise production economics in water-stressed manufacturing zones.
- Preservative system restrictions:ECHA REACH chemical hazard classifications limit formulation flexibility, extending reformulation timelines for European distribution.
Strategic Opportunities
- India pharmacy channel expansion:Pediatric dermatologist recommendation networks remain underdeveloped, creating first-mover positioning for fragrance-free premium entrants.
- Daycare bulk-format procurement:Institutional hygiene protocol standardization opens private-label manufacturing contracts at volume scale.
- Plant-based substrate convergence:Bamboo-cellulose hybrid materials intersect with composting infrastructure development to unlock premium pricing tiers.
Industry Challenges
- Microbiological validation timelines:NMPA microbial limit testing protocols extend product registration cycles for foreign manufacturers entering Chinese distribution.
- Legacy wet-line equipment retooling:Water-free process adoption demands capital redeployment from established saturation machinery, straining mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Wet Wipes Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance-Free, Alcohol-Free, Biodegradable, Moisturizing End User: Parents, Caregivers, Nurseries, Retailers Packaging Type: Plastic Packs, Flexible Pouches, Canisters, Refillable Packs Distribution Channel: Supermarkets, Online Retail, Pharmacy Chains, Convenience Stores |
| Companies Covered | Nice-Pak Products, The Clorox Company, Procter & Gamble, Diamond Wipes International, Albaad, Kimberly-Clark Corporation, Rockline Industries, SYWIPE, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Wet Wipes Market Trends and Innovations
Formulation chemistry and substrate engineering are converging to redefine product performance benchmarks while regulatory chemistry restrictions accelerate material substitution cycles.
Spunlace nonwoven fabrication utilizing regenerated cellulose fibers delivers enhanced biodegradability without compromising tensile strength during wet use. European pharmacy chains and institutional buyers are accelerating specification of these substrates in tender documents. Plant-based material engineering is expanding into premium product tiers previously dominated by petroleum-derived alternatives.
ECHA REACH substance restriction candidate list expansions are forcing preservative system redesigns across alcohol-free formulation portfolios. Manufacturers face compressed reformulation windows as sunset dates approach for legacy biocidal actives. Fragrance-free segments in German and French pharmacy channels are responding fastest, converting shelf space to EU Green Deal-compliant packaging formats.
Hospital procurement departments are consolidating vendor relationships around dermatological certification bundles rather than discrete product categories. Bulk-format contracts now specify integrated substrate and formulation compliance, displacing fragmented sourcing from multiple suppliers. This concentration pattern is most visible in Nordic healthcare systems where national tendering authorities centralize hygiene product acquisition.
Baby Wet Wipes Market Segmentation
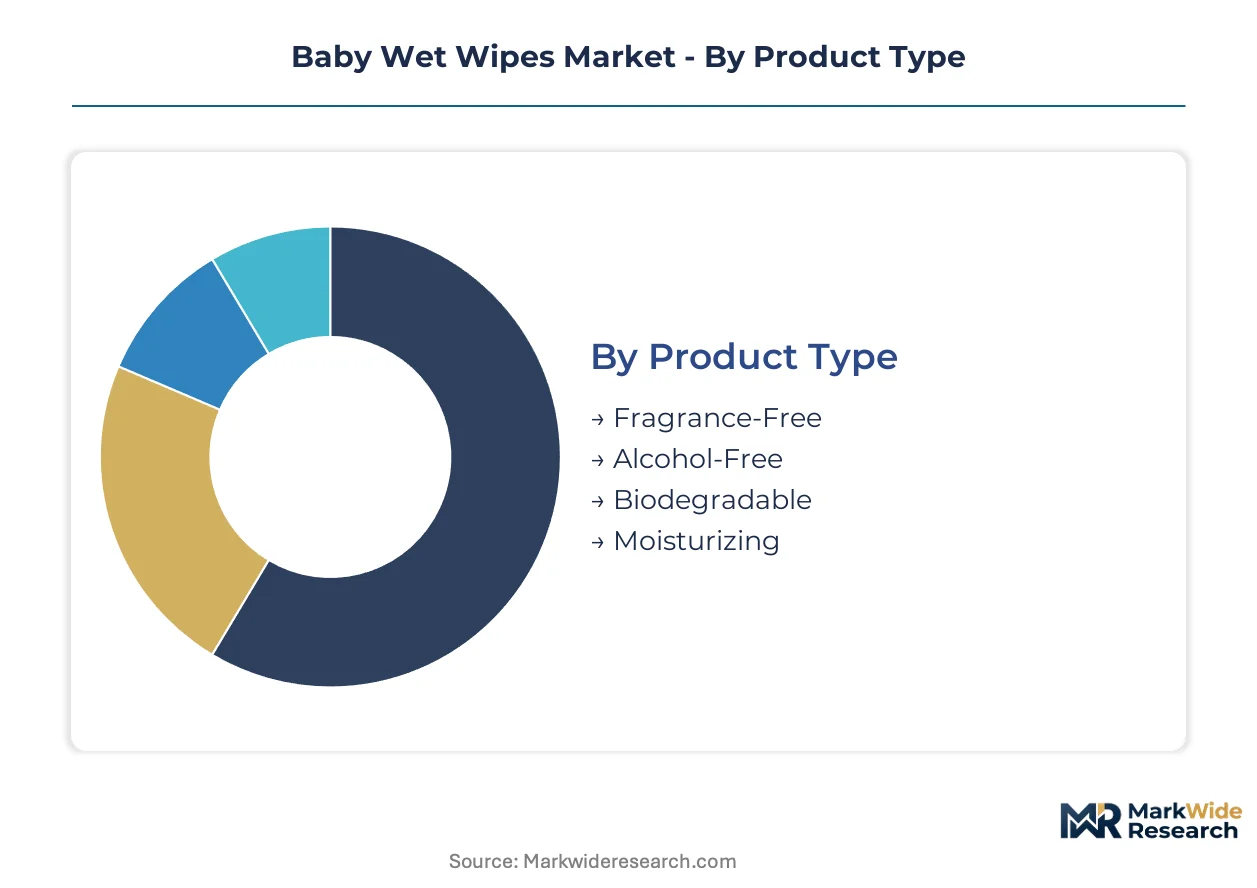
Product differentiation in baby wet wipes hinges on dermatological certification tiers and substrate material choices. Parents trade up through fragrance-free and biodegradable formats as pediatric guidance and EU packaging mandates reshape purchase criteria.
Product Type:
Upgrade cycles accelerate when households transition from basic cleansing to dermatologist-validated formats, with preservative chemistry and substrate biodegradability driving replacement decisions.
- Fragrance-Free:Eliminates synthetic perfume compounds to reduce infant skin irritation risk. Pharmacy chains in Germany and France allocate expanded shelf space following pediatric dermatologist recommendations. Demand concentrates in urban households with allergy-sensitive infants.
- Biodegradable:Utilizes bamboo-cellulose or regenerated cellulose substrates engineered for composting infrastructure compatibility. EU Green Deal packaging mandates and municipal composting expansion in Nordic cities accelerate procurement specification. This segment climbs the fastest in volume ranking.
- Alcohol-Free:Excludes ethanol and isopropyl alcohol to preserve neonatal skin barrier integrity. Hospital procurement departments specify these formulations for NICU and maternity ward protocols.
- Moisturizing:Incorporates glycerin, aloe vera, or ceramide additives for dry skin conditions. Premium positioning targets winter seasonal purchasing in temperate climates.
Fragrance-Free sits at the top of the volume ranking, with Biodegradable climbing the fastest.
End User:
Cost tier differentiation separates mass retail purchasing from institutional procurement, with volume scale and compliance documentation requirements widening the service gap between segments.
- Parents:Individual households purchasing for home diaper changing and on-the-go hygiene. Chinese tier-one city parents drive premium-format adoption through e-commerce subscription models.
- Nurseries:Institutional daycare facilities requiring bulk-format supply with dermatological certification bundles. Nordic national tendering authorities centralize procurement specifications.
- Caregivers:Extended family members and professional child-minders purchasing mid-tier formats. Price sensitivity runs higher than parent-directed purchasing.
- Retailers:Private-label program managers specifying substrate and formulation parameters for contract manufacturers. European pharmacy chains prioritize EU Green Deal-compliant packaging formats.
Parents command the highest absolute volume, with Nurseries expanding most quickly as institutional hygiene protocols standardize.
Packaging Type:
Application context determines format selection, with portability requirements and usage frequency shaping container engineering and closure mechanism specifications.
- Plastic Packs:Rigid polypropylene containers with snap-lid moisture retention systems. Standard for home bathroom placement and high-frequency usage patterns.
- Flexible Pouches:Laminated film structures with resealable adhesive strips. Diaper bag portability drives demand in commuter-heavy metropolitan areas.
- Canisters:Cylindrical dispensers with pop-up sheet delivery mechanisms. Dominates North American mass retail shelf placement.
- Refillable Packs:Reduced-plastic pouch inserts designed for permanent dispenser bases. Sustainability-conscious households in Scandinavian markets prefer this format.
Plastic Packs retain volume leadership, with Refillable Packs gaining share fastest among sustainability-motivated purchasers.
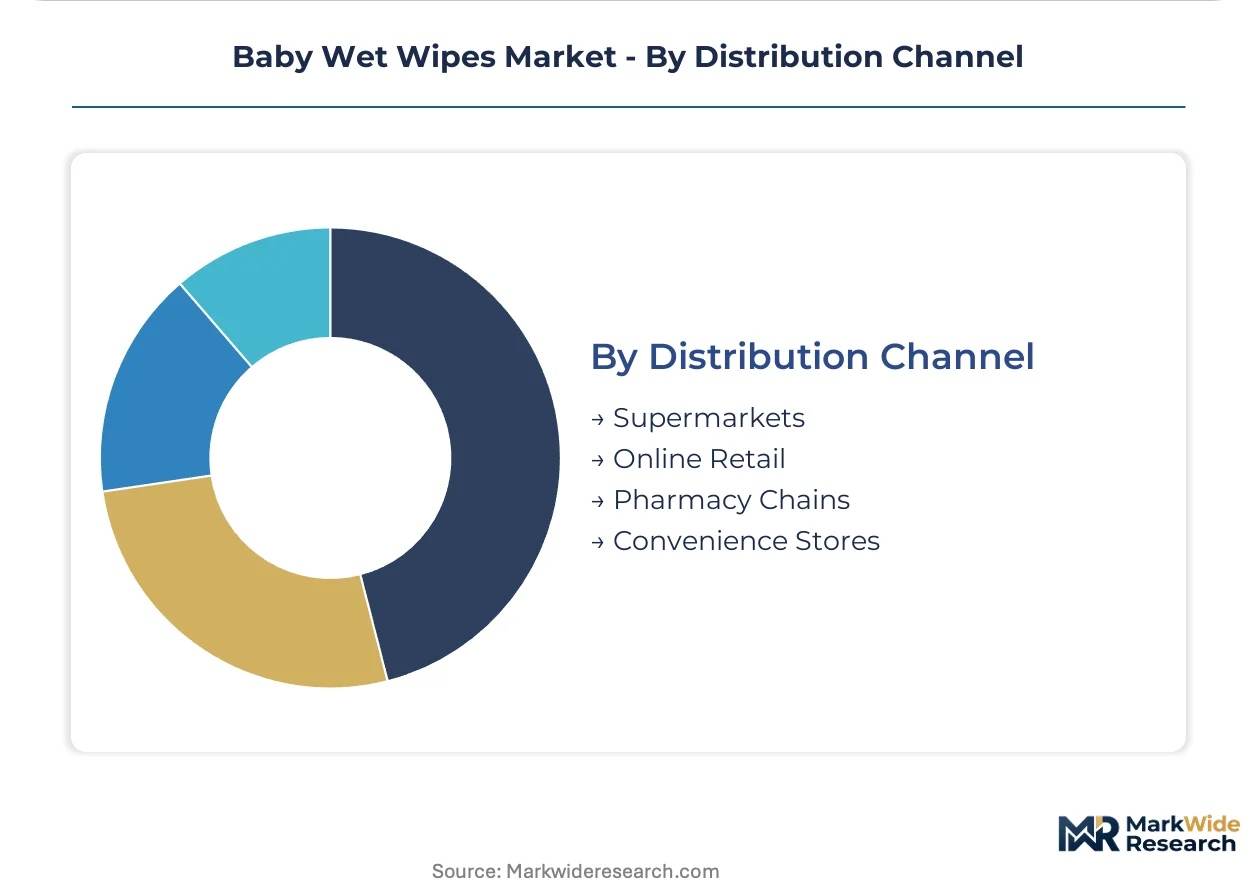
Distribution Channel:
Customer type fragmentation across channels creates pricing stratification, with recommendation authority and purchase urgency varying by point of sale.
- Pharmacy Chains:German and French networks leverage pediatric dermatologist endorsement to command premium positioning. ECHA REACH compliance documentation supports trust transfer.
- Online Retail:E-commerce platforms enable subscription replenishment and bulk purchasing. Chinese marketplace ecosystems concentrate premium-format discovery.
- Supermarkets:Mass retail channels emphasize promotional pricing and multi-pack value formats. Shelf placement competition intensifies between multinational brand portfolios.
- Convenience Stores:Emergency replenishment and travel-size purchasing at premium per-unit pricing. Urban density and transit accessibility determine store viability.
Pharmacy Chains anchor premium volume, with Online Retail expanding most quickly through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting private-label manufacturing toward jurisdictions with lower compliance burdens, while premium-format production clusters in markets with stringent dermatological certification requirements.
United States
Hospital procurement consolidation and NICU hygiene protocol standardization drive institutional demand. FDA cosmetic labeling requirements and EPA disinfectant claims oversight shape formulation boundaries. The Midwest manufacturing corridor around Wisconsin and Illinois hosts spunlace nonwoven substrate production serving North American converters.
Germany
Pharmacy chain premium positioning and pediatric dermatologist endorsement networks concentrate demand. ECHA REACH compliance and the EU Single-Use Plastics Directive impose material traceability mandates. The North Rhine-Westphalia industrial cluster anchors private-label manufacturing for European pharmacy distribution.
China
Urban middle-class expansion in tier-one cities accelerates premium-format adoption through e-commerce subscription models. NMPA microbial limit testing and GB standards for infant care products enforce ingredient disclosure rules. The Yangtze River Delta manufacturing belt concentrates water-free process adoption and plant-based substrate innovation.
India
Pharmacy channel underdevelopment in pediatric dermatologist recommendation networks creates first-mover positioning gaps. BIS standards and CDSCO regulations govern infant care product safety specifications. Maharashtra and Gujarat industrial zones host emerging private-label contract manufacturing capacity for domestic pharmacy chains.
France
Fragrance-free premium segments command expanded pharmacy shelf space following pediatric guidance. ANSM cosmetic safety oversight and EU Green Deal packaging mandates accelerate biodegradable substrate procurement. The Île-de-France region concentrates brand headquarters and regulatory compliance expertise for European market access.
Baby Wet Wipes Market Competitive Landscape
Capacity expansion dominates the current landscape as substrate producers and finished goods manufacturers retool for water-free processes and plant-based material transitions. The vendor base separates into three tiers: integrated multinational brand portfolios with captive distribution, specialized private-label contract manufacturers, and regional converters serving institutional procurement. Strategic archetypes include dermatological certification bundlers, sustainability-focused substrate innovators, and cost-flexible private-label specialists. M&A activity concentrates around substrate technology acquisitions, while geographic expansion targets underpenetrated pharmacy channels in emerging markets.
Among North American-based multinationals, Procter & Gamble and Kimberly-Clark Corporation exemplify integrated brand-distribution archetypes with captive nonwoven substrate production. Albaad represents the European private-label specialist model competing on cost flexibility for pharmacy chain contracts. These three anchors illustrate the structural divide between brand-led and contract manufacturing competitive vectors.
| Leading Market Players |
|---|
| Nice-Pak Products |
| The Clorox Company |
| Procter & Gamble |
| Diamond Wipes International |
| Albaad |
| Kimberly-Clark Corporation |
| Rockline Industries |
| SYWIPE |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement departments concentrate demand for dermatologically certified bulk formats, anchoring contract-based pricing that rewards volume scale and compliance bundling over spot-market flexibility.
Pricing Analysis
Distributor margins in European pharmacy chains absorb ECHA REACH compliance documentation costs, compressing netbacks for manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates fragrance-free pharmacy formats from mass retail value packs. Price erosion runs through standard-tier private-label contracts as Asian converters expand capacity. Parents purchasing through e-commerce subscription models show lowest price sensitivity; caregivers in convenience channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with spunlace nonwoven substrate production concentrated in China, South Korea, and Germany. Raw material flows draw from purified water aquifers, regenerated cellulose pulp, and preservative chemical feedstocks. Tariff exposure on Chinese substrate imports threatens European converter margins. Distribution runs through integrated multinational brand networks, private-label contract manufacturers, and regional institutional procurement tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-free manufacturing technology costs diverge sharply between China's Yangtze River Delta cluster and European legacy wet-line facilities, creating arbitrage opportunities for capital redeployment.
For Market Incumbents: Deploy dermatological certification bundling to lock hospital procurement contracts against private-label erosion. Capture spunlace substrate supply through backward integration into regenerated cellulose fiber production. E-commerce subscription churn threatens recurring revenue stability. For New Entrants and Emerging Players: Direct-to-consumer pharmacy channels in India offer lowest competitive density among major markets. Fragrance-free premium positioning leverages underdeveloped pediatric dermatologist recommendation networks. White-label manufacturing contracts with Nordic national tendering authorities provide volume scale without brand investment. For Investors and Strategic Acquirers: Private-label contract manufacturers with EU Green Deal-compliant substrate capabilities are the most active acquirer in this space. Long-term viability hinges on water-free process adoption timelines. Watch NMPA microbial testing protocol simplification as signal for Chinese market entry inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Free Process Adoption | Compresses production economics while satisfying EU aquifer protection mandates. |
| Plant-Based Substrate Transition | Unlocks premium pharmacy shelf positioning under Green Deal compliance. |
| Hospital Procurement Consolidation | Captures institutional volume through dermatological certification bundling. |
| E-Commerce Subscription Infrastructure | Secures recurring revenue from Chinese tier-one city parent households. |
| Private-Label Contract Manufacturing | Exploits cost flexibility gaps in European pharmacy chain sourcing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged brand managers at multinational consumer goods companies, category buyers at European pharmacy chains, plant managers at spunlace nonwoven facilities, and procurement officers at Nordic hospital systems. Secondary validation drew from customs trade records, Nielsen retail audit data, ECHA substance restriction timelines, and NMPA registration disclosure databases. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Segment-weighting distributed volume and value estimates across product type, end user, packaging format, and distribution channel dimensions. CAGRs were derived from slope analysis of historical trajectory and policy-inflected inflection points. Forecast inputs incorporated ECHA REACH sunset date schedules, EU municipal composting infrastructure buildout curves, and Chinese e-commerce penetration rates for infant care subscriptions.
The model assumes a particular technology adoption path; alternative pathways for water-free manufacturing scale-up would alter the outlook. Forecasts reflect substrate innovation timelines, regulatory enforcement intensity variations, and aquifer depletion patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
China Maternity Goods Market
Baby Products
Portable Cribs Market
Baby Products
Baby Wipes Market
Baby Products
Baby Stroller Market
Baby Products
Baby Changing Station Market
Baby Products
Baby Bottle Holder Market
Baby Products
Netherlands Baby Care Products Market
Baby Products
Puppy Teething Toys Market
Baby Products
Global Pregnancy Pillow Market
Baby Products
Baby Cradles Market
Baby Products
Baby High Chair Market
Baby Products
Baby Slings Market
Baby Products
Baby Gift Basket Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Travel Pillow Market
Baby Products
Baby Nipple/Teat Market