
 PTBCHA Market | 2026-2036
PTBCHA Market Size, Share, and Industry Trends Forecast 2026-2036
PTBCHA Market Analytics
Multi-source procurement for specialty aroma chemicals is restructuring how fragrance houses secure PTBCHA supply. Eternis Fine Chemicals anchors its position through backward integration into cyclohexane derivatives. LANXESS dominates European supply chains with captive production of bicyclic intermediates. Givaudan SA differentiates via dedicated R&D pipelines for proprietary PTBCHA-based accords.
PTBCHA (para-tert-butylcyclohexyl acetate) is a bicyclic ester with a molecular weight near 212.3 g/mol, synthesized through acetylation of para-tert-butylcyclohexanol and valued for its woody-amber odor profile in fine fragrance compounding. The organic tea product type commands premium positioning due to natural-origin labeling requirements, while online stores represent the fastest-growing distribution channel as direct-to-consumer fragrance sampling expands. Specialty stores retain the deepest margin pools through personalized consultation services.
REACH registration in Europe, EPA TSCA oversight in the United States, and BIS chemical standards in India collectively elevate analytical testing burdens for PTBCHA exporters. ECHA substance evaluation protocols now scrutinize persistent biodegradation metrics for fragrance ingredients. Stakeholders must monitor regulatory divergence between EU hazard classification updates and emerging state-level chemical disclosure rules in the US.
Market Dynamics
REACH substance evaluation protocols are tightening biodegradation benchmarks for fragrance intermediates, forcing specialty chemical houses to revalidate purity specifications across European supply chains. This regulatory compression is accelerating capital deployment into analytical testing infrastructure and backward integration into cyclohexane derivative production.
Growth Catalysts
- Fine fragrance compounding:Specialty perfume houses in Germany and the United States are expanding PTBCHA procurement for woody-amber accord formulations. This demand concentrates in Western European luxury manufacturing clusters.
- Evolving EPA guidelines:Updated TSCA oversight for chemical intermediates in North America is elevating purity benchmarks. Exporters must now meet stricter analytical documentation requirements for US-bound shipments.
- Natural-origin labeling:Organic tea product variants command premium positioning as clean-label mandates propagate across European and Indian consumer markets.
Market Restraints
- Cyclohexane feedstock volatility:Para-tert-butylcyclohexanol precursor costs fluctuate with petrochemical cracking margins. This input cost instability compresses formulation margins for mid-tier compounders.
- European supply concentration:Captive production of bicyclic intermediates dominates regional supply chains. Dependence on German and Dutch manufacturing clusters creates geographic vulnerability to ECHA regulatory shocks.
- Biodegradation scrutiny:ECHA persistence assessments now classify certain fragrance aldehydes as potential aquatic hazards. This technical limitation restricts formulation flexibility in rinse-off applications.
Strategic Opportunities
- Indian flavor compounding:Underpenetrated demand from domestic fragrance houses offers expansion white space. BIS chemical standards alignment remains the entry threshold for imported intermediates.
- Direct-to-consumer sampling:Online stores represent the fastest-growing distribution channel. Digital fragrance subscription models bypass traditional specialty store intermediaries.
- EU Green Deal alignment:Bio-based acetylation processes qualify for circular economy funding. Proprietary R&D pipelines can leverage this policy tailwind for carbon footprint reduction claims.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise for trace impurity detection is concentrated among aging specialists in European contract laboratories.
- REACH registration timelines:Extended substance evaluation periods delay market entry for modified purity grades. Lead times now stretch 18-24 months for new supplier qualification.
- Legacy formulation integration:Substituting PTBCHA for restricted ambergris replacers requires sensory panel recalibration and stability retesting across existing perfume portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PTBCHA Market |
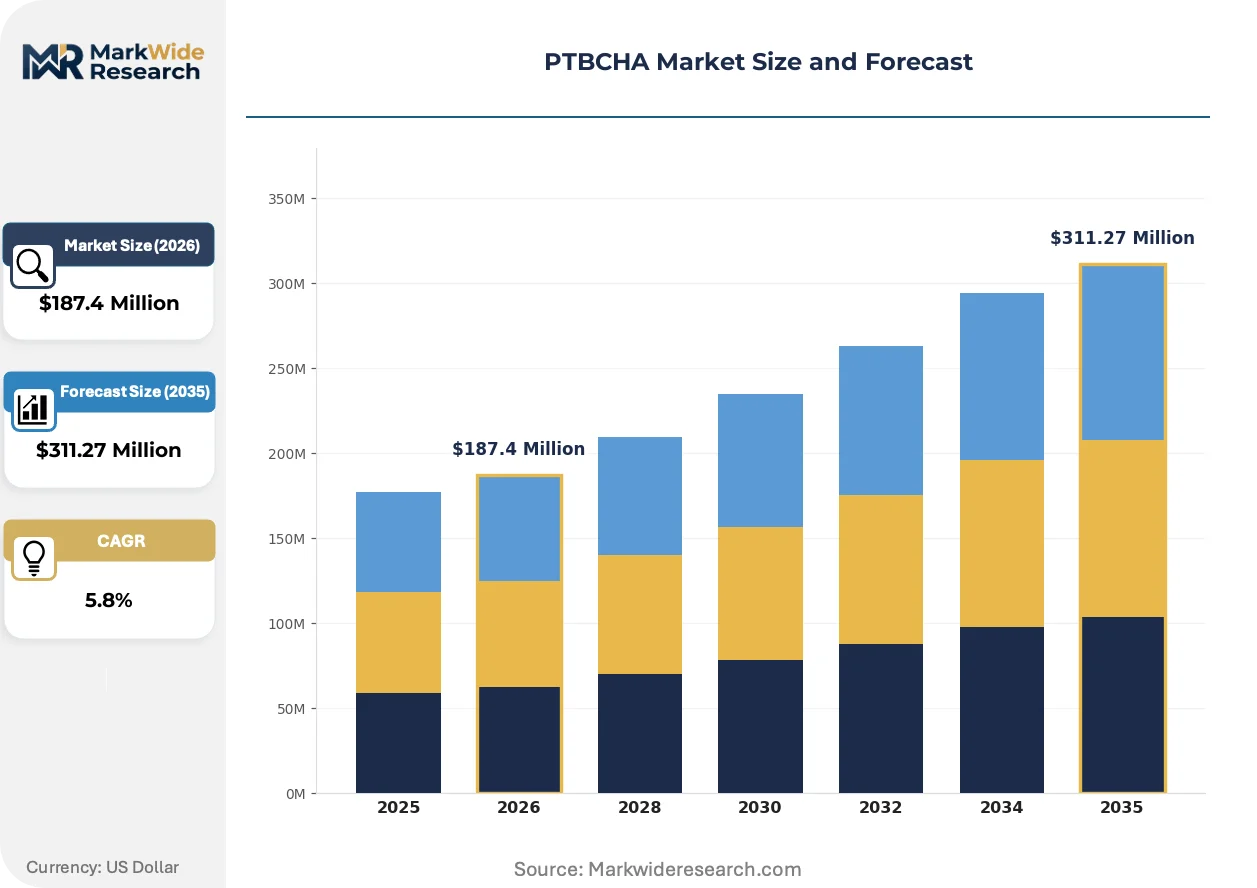
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tea, Herbal Infusion, Natural Supplement, Functional Beverage End User: Retail Consumers, Health Enthusiasts, Fitness Professionals, Wellness Centers Distribution Channel: Online Stores, Health Food Shops, Supermarkets, Specialty Stores Packaging Type: Bags, Bottles, Cans, Loose Leaf |
| Companies Covered | LANXESS, BASF SE, International Flavours & Fragrances, Privi Organics, Eternis Fine Chemicals Ltd., Berje Inc., Firmenich Inc., Symrise AG, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PTBCHA Market Evolving Landscape
Continuous flow acetylation reactors are displacing batch synthesis across specialty aroma chemical manufacturing. This process intensification is compressing cycle times and reducing solvent waste profiles for cyclohexyl derivative production.
Automated high-throughput screening platforms are automating odorant performance evaluation for PTBCHA-based accords. Givaudan SA and competing fragrance houses deploy these systems to compress formulation iteration cycles from months to weeks. The technology is automating sensory panel substitution for initial compound ranking, though human perfumers retain final accord approval authority.
ECHA's 2024 updated guidance on persistent, bioaccumulative and toxic substances is reclassifying certain bicyclic aldehydes for aquatic hazard labeling. Fine fragrance formulators must now reformulate rinse-off products or absorb higher waste treatment costs. German and French luxury houses are responding by diverting PTBCHA toward leave-on perfume concentrations where biodegradation thresholds are less stringent.
Direct procurement from specialty chemical manufacturers is displacing distributor intermediaries for volume fragrance houses. Eternis Fine Chemicals and LANXESS now manage dedicated account teams for Givaudan SA and Firmenich-scale buyers. This channel consolidation is most visible in Western European supply corridors where backward-integrated producers can guarantee lot-to-lot consistency for high-purity grades.
PTBCHA Market Segmentation
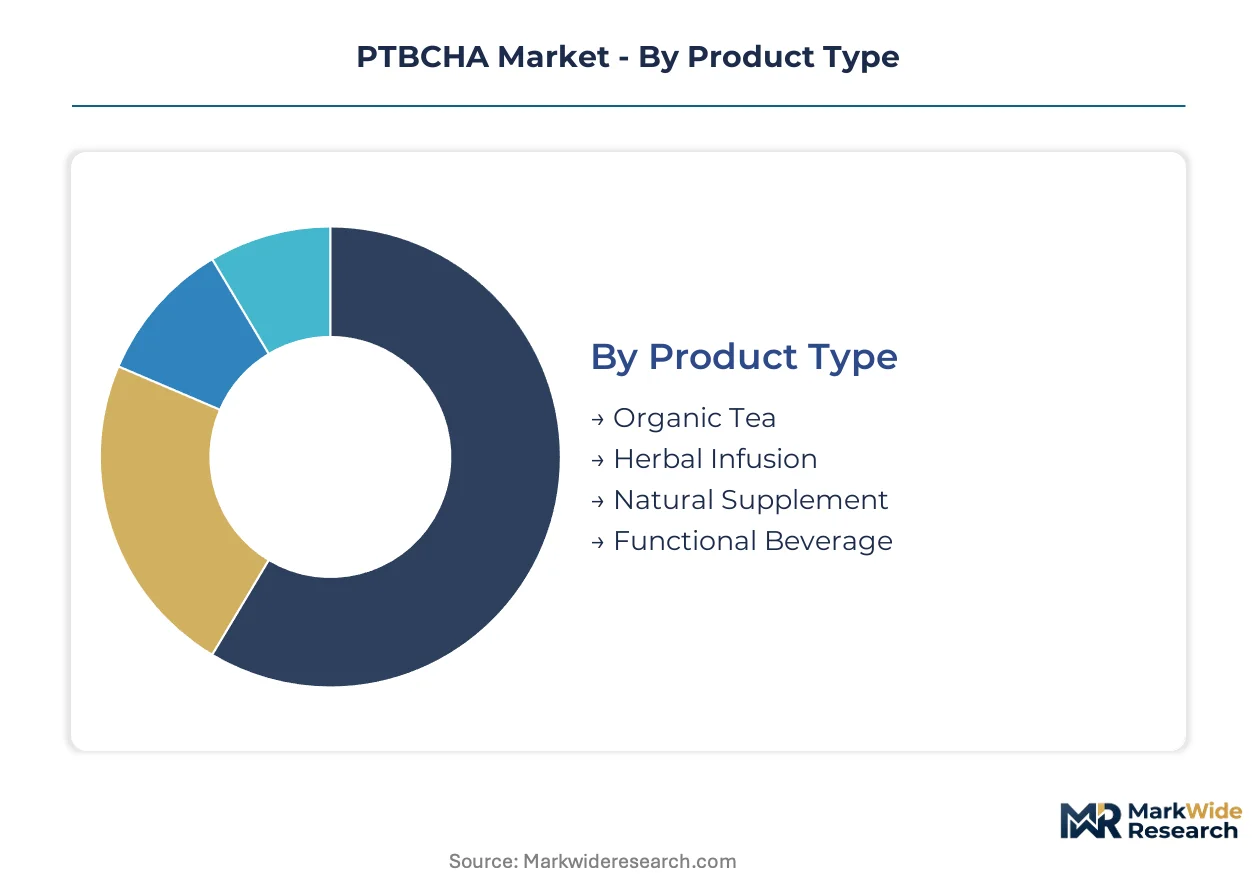
PTBCHA procurement patterns diverge sharply across product formulations and channel structures. Fragrance houses calibrate purity grades and volume commitments differently for each segment, creating tiered supply relationships with specialty chemical manufacturers.
Product Type:
Specification requirements for woody-amber accord integration determine grade differentiation across product categories.
- Organic Tea:Natural-origin labeling mandates in Germany and France command premium-grade PTBCHA with full REACH documentation. Specialty fragrance houses in Grasse and Geneva prioritize this segment for luxury perfume lines requiring clean-label certification.
- Herbal Infusion:Standard-grade bicyclic ester suffices for botanical fragrance compounding. Demand concentrates in mid-tier personal care formulations where cost efficiency outweighs certification premiums.
- Natural Supplement:Food-grade purity specifications apply for ingestible aroma applications. BIS standards in India create additional analytical thresholds for imported PTBCHA.
- Functional Beverage:Flavor masking applications utilize technical-grade material with relaxed organoleptic benchmarks. Volume procurement dominates over purity premiums.
Mature deployment sits with Organic Tea. Newer deployment is concentrated in Functional Beverage.
End User:
Customer sophistication levels reshape contract structures and technical service intensity for PTBCHA suppliers.
- Retail Consumers:Mass-market fragrance brands drive high-volume, standardized-grade procurement. E-commerce sampling platforms in the United States are expanding this segment's reach through direct-to-consumer woody-amber product launches.
- Health Enthusiasts:Clean-label preferences elevate demand for certified-organic PTBCHA derivatives. German and Dutch natural cosmetics manufacturers anchor this niche with stringent biodegradability requirements.
- Fitness Professionals:Sports fragrance applications require stability-tested grades for high-perspiration formulations. Technical documentation demands exceed standard commercial specifications.
- Wellness Centers:Aromatherapy diffusion systems utilize lower-concentration PTBCHA blends. Spa chains in India represent an underpenetrated demand pocket with growing procurement volumes.
Volume concentration favors Retail Consumers. Margin expansion is climbing the fastest in Health Enthusiasts.
Distribution Channel:
Channel selection determines lot-size flexibility, documentation depth, and speed-to-market for PTBCHA shipments.
- Online Stores:Digital fragrance subscription models bypass traditional intermediaries. Direct procurement from Eternis Fine Chemicals and LANXESS enables smaller lot sizes with compressed lead times for emerging perfume houses.
- Health Food Shops:Natural-product retailers demand full supply chain transparency including REACH registration numbers. Documentation burdens elevate supplier qualification costs.
- Supermarkets:Mass-market personal care brands drive pallet-scale procurement with standardized specifications. Price sensitivity compresses margins for mid-tier compounders.
- Specialty Stores:Personalized consultation services support premium-grade PTBCHA with dedicated technical support. French and Italian luxury fragrance boutiques retain the deepest margin pools through exclusive accord formulations.
Established volume flows through Supermarkets. Channel expansion is gaining share fastest in Online Stores.
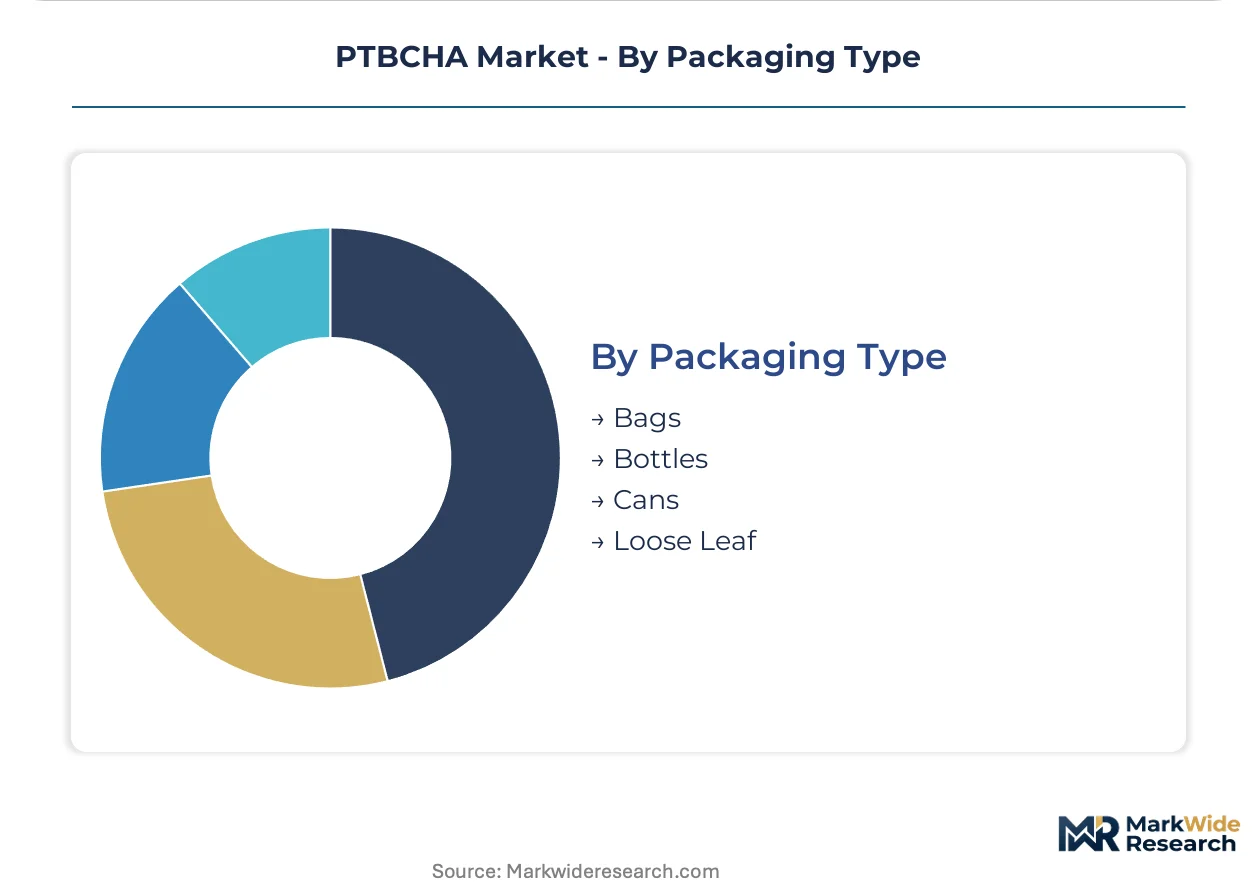
Packaging Type:
Material compatibility and shelf-stability requirements dictate formulation adjustments across container formats.
- Bags:Flexible packaging for solid perfume applications requires oxidation-resistant PTBCHA grades. Sampling programs in the United States favor this format for travel-size fragrance distribution.
- Bottles:Glass containment for fine perfume concentrates demands highest-purity material to prevent interaction with alcohol bases. German luxury houses specify lot-to-lot consistency for premium spray formulations.
- Cans:Aerosol compatibility necessitates pressure-tested stability validation. Technical-grade specifications suffice for mass-market body spray applications.
- Loose Leaf:Bulk aromatherapy diffusion materials utilize standard technical grades with minimal packaging overhead. Wellness centers in India source through this channel for cost efficiency.
Precision requirements peak with Bottles. Format experimentation is expanding most quickly in Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European luxury fragrance manufacturing clusters absorb the majority of PTBCHA volume, with German and French specialty houses driving specification-grade procurement for woody-amber accord formulations.
Germany
Fine perfume compounders in the Cologne-Düsseldorf corridor are expanding high-purity PTBCHA procurement for clean-label fragrance lines. REACH registration requirements under ECHA substance evaluation protocols now mandate persistent biodegradation documentation for all imported bicyclic esters. The Lower Rhine chemical manufacturing belt hosts backward-integrated cyclohexane derivative producers supplying captive intermediates to domestic fragrance houses.
United States
Specialty aroma chemical distributors in New Jersey and California are reporting accelerated demand from direct-to-consumer fragrance subscription platforms. EPA TSCA oversight for chemical intermediates now requires enhanced analytical documentation for purity verification of imported PTBCHA shipments. The New York metropolitan area anchors East Coast procurement, with fragrance houses in Manhattan and northern New Jersey consolidating supplier relationships through dedicated account teams.
France
Grasse-based luxury perfume manufacturers are diverting PTBCHA toward leave-on fragrance concentrations to circumvent ECHA aquatic hazard labeling for rinse-off applications. ANSM cosmetic safety guidelines align with EU Green Deal circular economy criteria, favoring bio-based acetylation process claims. The Provence-Alpes-Côte d'Azur region retains the deepest concentration of artisanal fragrance houses requiring lot-to-lot consistency for premium spray formulations.
India
Domestic flavor compounders in Maharashtra and Gujarat are expanding PTBCHA procurement for natural-origin labeling requirements in export-oriented tea and herbal infusion products. BIS chemical standards create analytical entry thresholds for imported bicyclic intermediates, with CDSCO oversight extending to ingestible aroma applications. Mumbai and Ahmedabad manufacturing clusters are developing technical capabilities for gas chromatography-mass spectrometry testing to meet European exporter documentation demands.
Switzerland
Geneva-based fragrance R&D facilities are deploying automated high-throughput screening platforms to compress formulation iteration cycles for PTBCHA-based accords. Swissmedic cosmetic ingredient guidelines and REACH alignment through bilateral agreements govern import documentation for specialty chemical manufacturers. The Basel chemical manufacturing corridor hosts precision synthesis operations supplying high-purity grades to adjacent French and German luxury houses.
PTBCHA Market Competitive Landscape
Backward integration into cyclohexane derivative production dominates the current landscape, with specialty chemical manufacturers securing captive supply of para-tert-butylcyclohexanol precursors. The vendor base structures across three tiers: multinational diversified chemical conglomerates with fragrance divisions, mid-cap specialty aroma chemical houses with regional manufacturing footprints, and boutique compounders serving niche perfumery accounts. Competitive positioning crystallizes around purity grade certification, REACH registration depth, and dedicated technical service intensity. Capacity expansion in Western European corridors and strategic partnerships for Indian market access represent the dominant competitive vectors.
Among diversified chemical conglomerates, LANXESS and BASF SE exemplify the backward-integrated archetype with cyclohexane derivative production anchoring European supply chains. Eternis Fine Chemicals Ltd. occupies a position within the specialty aroma chemical tier, representing mid-cap manufacturers with focused R&D pipelines for proprietary accord development. These three entities illustrate the competitive spectrum from petrochemical-derived captive supply to dedicated fragrance intermediate specialization.
| Leading Market Players |
|---|
| LANXESS |
| BASF SE |
| International Flavours & Fragrances |
| Privi Organics |
| Eternis Fine Chemicals Ltd. |
| Berje Inc. |
| Firmenich Inc. |
| Symrise AG |
| Givaudan SA |
| Others |
Value Network & Pricing Analysis
REACH certification grade bifurcation separates premium-grade PTBCHA with full biodegradation documentation from technical-grade material for functional applications, concentrating pricing power with backward-integrated German and Dutch producers while forcing mid-tier compounders toward distributor intermediaries with compressed margins.
Pricing Analysis
Volume-scale supermarket procurement anchors the low-margin tier with standardized specifications, while specialty stores extract premium positioning through lot-to-lot consistency guarantees for fine fragrance formulations. Price differentiation hinges on REACH registration depth and gas chromatography-mass spectrometry certification tier. Cost compression in technical-grade material is intensifying because cyclohexane feedstock volatility feeds through para-tert-butylcyclohexanol precursor costs. Supermarket buyers exhibit highest price sensitivity; luxury fragrance houses in Grasse and Geneva demonstrate lowest sensitivity due to accord-specific formulation lock-in.
Supply Chain Analysis
Regional distribution centers in the Cologne-Düsseldorf corridor and Rotterdam-Antwerp hub handle bulk cyclohexane derivative consolidation before final-mile specialty chemical delivery. Supply concentrates in Germany, the Netherlands, and India, with the latter emerging as a testing and documentation hub for export-oriented production. Raw material flows draw from petrochemical cracking operations, acetic anhydride acetylation agents, and catalyst systems for continuous flow reactor operations. Single-source vulnerability sits with European ECHA regulatory shocks that can disqualify entire supplier cohorts. Distribution runs through direct account teams for volume fragrance houses, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PTBCHA supply consolidation favors producers with captive cyclohexane derivative operations, as REACH substance evaluation timelines and analytical testing infrastructure costs force smaller compounders toward exit or acquisition.
For Market Incumbents: Hedge against ECHA aquatic hazard reclassification by accelerating bio-based acetylation process claims that qualify for EU Green Deal circular economy funding. Deepen backward integration into para-tert-butylcyclohexanol production to insulate margin structures from petrochemical feedstock volatility. Lock in dedicated account team relationships with Givaudan SA and Firmenich-scale buyers before channel consolidation completes. For New Entrants and Emerging Players: Domestic flavor compounders in Maharashtra and Gujarat represent the most penetrable buyer archetype, as BIS chemical standards alignment creates qualification barriers that favor technical service intensity over scale. Target wellness center chains in India with lower-concentration PTBCHA blends for aromatherapy diffusion systems, where documentation burdens remain minimal. Deploy direct-to-consumer digital fragrance subscription partnerships as the go-to-market angle to bypass entrenched specialty store intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialty aroma chemical houses with REACH registration depth and automated high-throughput screening capabilities given accelerating formulation iteration compression. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than commodity scale. Monitor ECHA substance evaluation protocol updates as the inflection signal for supplier qualification timeline extensions that advantage incumbent registrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive para-tert-butylcyclohexanol production insulates margin structures from cyclohexane feedstock volatility. |
| REACH Registration Investment | Extended substance evaluation timelines create qualification moats that disadvantage unregistered competitors. |
| Bio-based Acetylation Transition | EU Green Deal circular economy funding eligibility supports carbon footprint reduction claims for luxury fragrance lines. |
| Direct Account Team Deployment | Dedicated technical service relationships with Givaudan SA and Firmenich displace distributor intermediaries. |
| Automated High-throughput Screening | Geneva-based R&D facilities compress formulation iteration cycles from months to weeks for PTBCHA-based accords. |
Research Methodology
Trade databases, ECHA substance evaluation registers, and SEC 10-K filings from specialty chemical manufacturers formed the secondary backbone for supply chain mapping and regulatory timeline assessment. Primary interviews with fragrance house procurement directors, cyclohexane derivative plant managers, and analytical laboratory technical directors validated purity grade specifications and REACH documentation requirements. Bottom-up and top-down triangulation reconciled volume estimates from customs data with disclosed capacity figures from backward-integrated producers.
Bottom-up modeling aggregated segment-level demand across organic tea, herbal infusion, natural supplement, and functional beverage product categories, while top-down validation cross-checked against disclosed procurement volumes from major fragrance houses. Segmentation dimensions included grade tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement patterns and capacity expansion announcements. Industry-specific forecast inputs incorporated ECHA biodegradation benchmark evolution and EPA TSCA oversight tightening trajectories.
Revisions become necessary when ECHA aquatic hazard reclassification protocols extend substance evaluation timelines or when cyclohexane cracking margin volatility disrupts para-tert-butylcyclohexanol precursor economics. Forecasts reflect documented assumptions around regulatory compliance trajectories and feedstock cost stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Tick Repellent Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Global Weight Loss Services Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Health Check-Up Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Reusable Face Mask Market
Personal Health
Menopause Wellness Market
Personal Health
Earwax Removal Products Market
Personal Health
Menstrual Cup Market
Personal Health
Sleep Mask Market
Personal Health
Patient Health Management Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Health Coaching Market