
 Maldives Hospitality Market | 2026-2036
Maldives Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Maldives Hospitality Market Insights
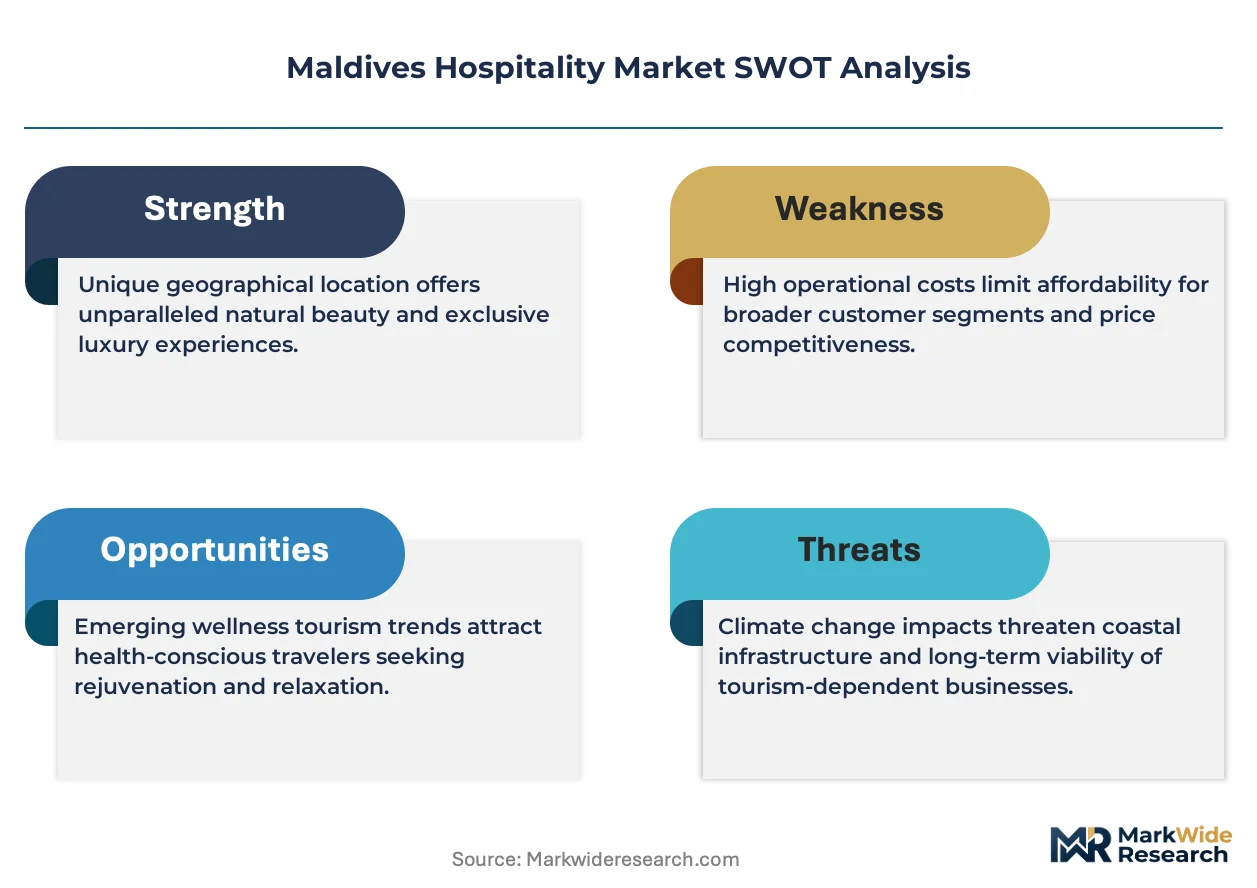
The capital-intensity divergence between overwater villa developers and guesthouse operators is bifurcating competitive dynamics across the Maldivian archipelago. Soneva leverages its deep vertical integration into sustainable food production and waste management systems to command premium positioning. Crown & Champa Resorts anchors its portfolio across multiple atolls with standardized operational templates that reduce per-unit development costs.
Maldives hospitality encompasses lodging, food service, recreation, and guest-experience management delivered across dispersed coral atolls where supply chains depend on maritime logistics and desalinated water infrastructure. The sector functions as a destination-service export industry where foreign exchange earnings hinge on per-guest spending duration and ancillary activity capture. Luxury Resorts and Overwater Villas capture the dominant share of revenue pools due to elevated average daily rates and mandatory seaplane or speedboat transfers. Boutique Hotels and Guesthouses represent the fastest-expanding tier as regulatory caps on resort-island density redirect developer interest toward inhabited island permits.
The Ministry of Tourism and the Environmental Protection Agency jointly enforce carrying-capacity limits and reef-protection buffers that constrain new supply expansion. Maldives Customs Service and the Tourism Goods and Services Tax framework shape operational cost structures for imported food, fuel, and construction materials. Stakeholders must monitor whether the government's inhabited-island tourism policy creates viable alternatives to the traditional one-island-one-resort model or fragments brand coherence across dispersed properties.
Market Dynamics
The Maldives' one-island-one-resort model faces structural pressure from the government's inhabited-island tourism policy, which redirects development permits toward local population centers and fragments the traditional luxury enclave model. This regulatory pivot is compressing the capital efficiency gap between seaplane-accessible resort islands and speedboat-accessible guesthouse clusters.
Growth Catalysts
- Environmental Carrying-Capacity Frameworks:The Ministry of Tourism's reef-protection buffers and density caps force developers toward higher-yield per-unit designs, elevating average spending per guest.
- Ultra-High-Net-Worth Concentration:Leisure travelers from Germany, the United Kingdom, and China are extending average length of stay through multi-atoll itineraries and extended villa charters.
- Desalination and Solar Hybridization:Resort operators deploying reverse-osmosis plants paired with photovoltaic arrays are reducing diesel import dependency and stabilizing operational cost structures.
Market Restraints
- Maritime Supply Chain Fragility:Food, construction materials, and fuel move through Male port consolidation, exposing operators to customs clearance delays and TGST layering.
- Seaplane Transfer Bottlenecks:Maldivian aviation infrastructure limits inter-atoll connectivity, constraining guest mobility and compressing feasible property dispersion.
- Reef Degradation Thresholds:Coral bleaching events and lagoon sedimentation are narrowing viable development sites within protected atoll buffers.
Strategic Opportunities
- Gaafu Dhaalu and Thaa Atoll Expansion:Southern atolls with untapped reef systems offer lower land-lease costs and differentiation through remoteness positioning.
- Integrated Wellness and Longevity Programming:Medical tourism hybrids combining ayurvedic treatment with marine therapy are capturing extended-stay segments beyond traditional leisure.
- Community-Based Tourism Permits:Regulatory pathways for local island guesthouses enable brand extension into experiential cultural segments without resort-island capital outlay.
Industry Challenges
- Specialized Marine Construction Labor:Stilt-foundation engineering and coral-reef pile-driving expertise concentrates among a limited contractor pool, extending development timelines.
- TGST Compliance Complexity:Tourism Goods and Services Tax reporting across imported inventory, in-house production, and subcontracted services creates audit exposure for multi-atoll portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maldives Hospitality Market |
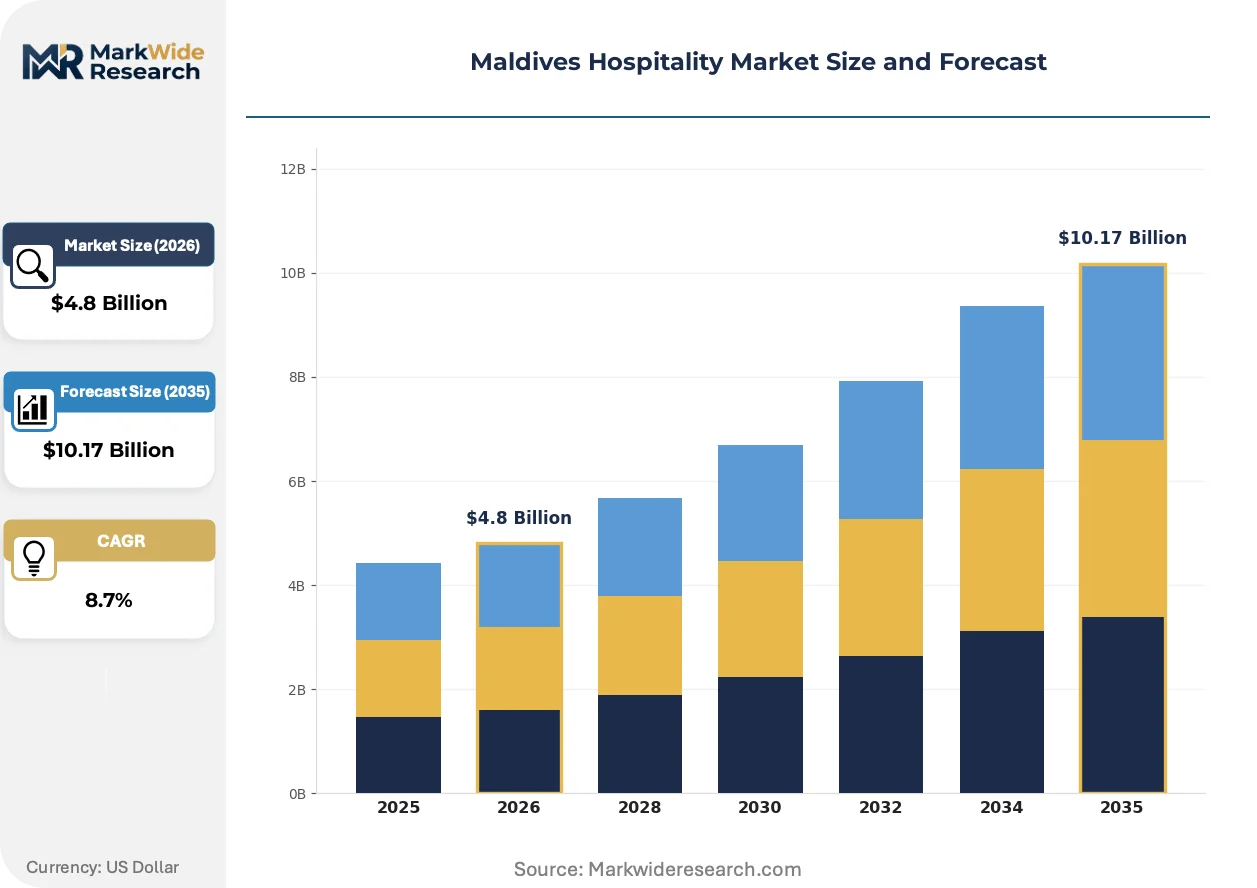
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Luxury Resorts, Boutique Hotels, Overwater Villas, Guesthouses Customer Type: Leisure Travelers, Business Travelers, Family Groups, Couples Service Type: All-Inclusive, Half Board, Bed & Breakfast, Self-Catering Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps |
| Companies Covered | AccorHotels, Crown & Champa Resorts, Marriott International, Minor Hotels, Universal Resorts, Hilton Worldwide, Hyatt Hotels Corporation, Soneva, InterContinental Hotels Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maldives Hospitality Market Trends and Innovations
Sustainability certification and digital guest-experience platforms are restructuring competitive differentiation in Maldivian hospitality, moving beyond amenity wars toward operational transparency and personalized service architecture.
Modular prefabrication for overwater villa construction is decomposing traditional on-site building timelines. Soneva and boutique developers are adopting factory-built units shipped from Sri Lanka and Dubai, compressing reef-disturbing construction windows from 18 months to under 8 months. This shift is reducing lagoon sedimentation exposure and accelerating capital recovery cycles for new atoll entries.
The Ministry of Tourism's mandatory Environmental Impact Assessment protocols, enforced jointly with the Environmental Protection Agency, are elevating compliance costs for new resort approvals. Developers must now submit reef-health baselines and 10-year monitoring commitments before lease activation. North Male Atoll applicants face the strictest scrutiny given cumulative development density, pushing permit seekers toward southern atoll frontiers.
Direct booking platforms and property-managed loyalty programs are displacing traditional Online Travel Agency dependency among repeat-visitor segments. Luxury resorts in Baa and Raa atolls are capturing 40-60% of reservations through owned channels, reducing commission drag and enabling dynamic packaging of seaplane transfers and diving excursions. This channel migration is most pronounced among European source markets with established Maldives travel histories.
Maldives Hospitality Market Segmentation
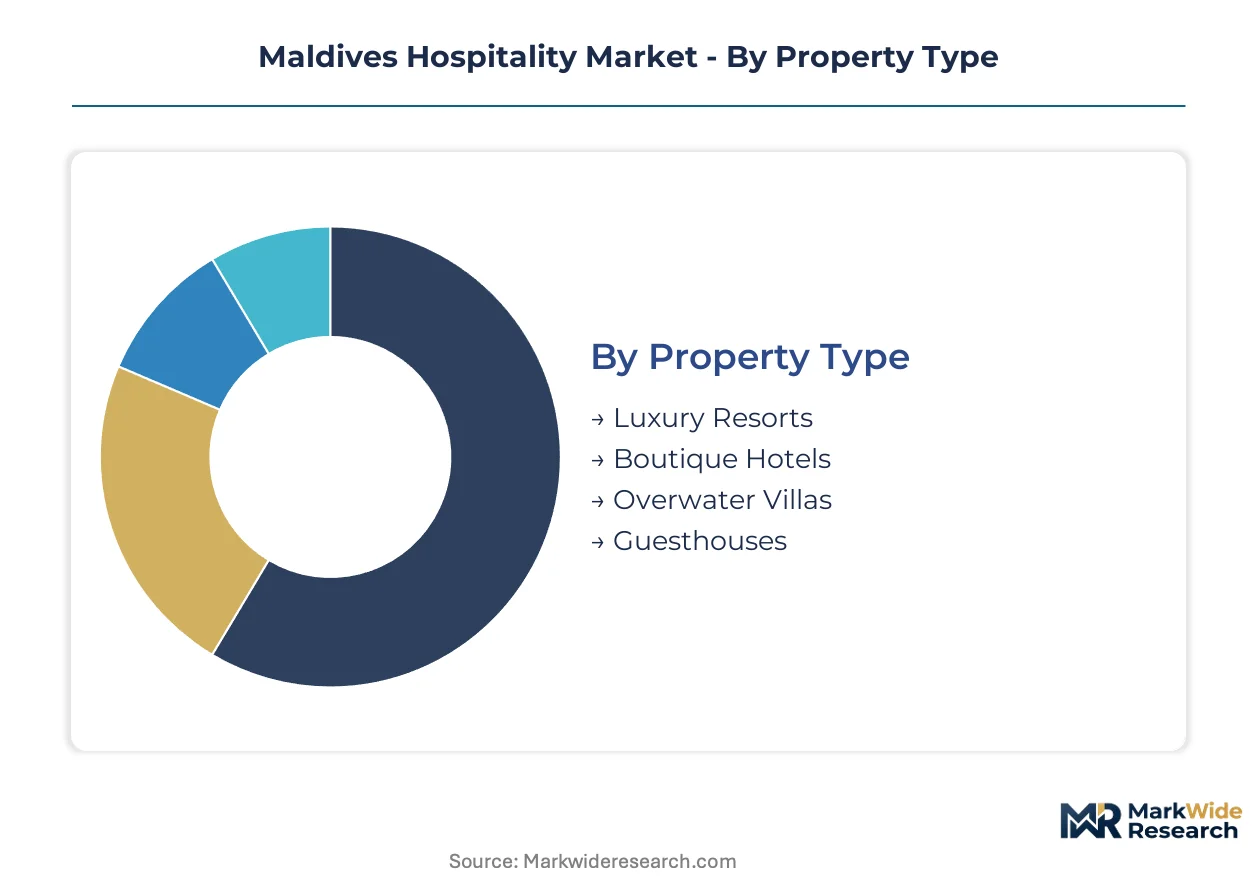
The Maldives hospitality sector fragments across property tiers, customer profiles, and service architectures that each face distinct regulatory and operational constraints. Understanding these divisions clarifies where capital efficiency diverges and where permit scarcity reshapes competitive positioning.
Property Type:
The Ministry of Tourism's Environmental Protection Agency enforces reef-protection buffers and density caps that vary sharply by development category, compressing feasible supply expansion differently across each tier.
- Luxury Resorts:One-island-one-resort configurations dominate revenue concentration through elevated average daily rates and mandatory seaplane transfers. The North Male Atoll corridor concentrates existing inventory, while southern atoll permits face lower cumulative density scrutiny.
- Overwater Villas:Stilt-foundation engineering over coral lagoons commands premium positioning but triggers strict Environmental Impact Assessment protocols. Modular prefabrication from Sri Lankan and Dubai factories is compressing construction windows and reducing sedimentation exposure.
- Boutique Hotels:Smaller-scale operations on inhabited islands access speedboat-transfer catchments rather than seaplane dependency.
- Guesthouses:Local-island permits under government redirection policy enable lower capital entry without resort-island lease costs.
Luxury Resorts handle the majority of throughput; Guesthouses are expanding most quickly on share as regulatory caps redirect developer interest.
Customer Type:
Per-guest spending duration and ancillary capture rates diverge substantially across travel motivations, with direct implications for transfer logistics and programming design.
- Leisure Travelers:Ultra-high-net-worth segments from Germany, the United Kingdom, and China extend length of stay through multi-atoll itineraries. Extended villa charters and diving excursions drive ancillary revenue capture beyond accommodation.
- Couples:Honeymoon and anniversary segments prioritize privacy and overwater inventory, accepting premium pricing for seaplane-accessible remoteness. Repeat-visitor rates exceed other leisure categories, enabling direct booking channel migration.
- Family Groups:Multi-generational travel demands larger villa configurations and child-focused programming.
- Business Travelers:Corporate retreat and incentive segments concentrate in proximity to Male International Airport.
Leisure Travelers anchor revenue volume; Couples are climbing the fastest as repeat-visit loyalty programs reduce Online Travel Agency dependency.
Service Type:
Board-structure selection determines food import exposure and kitchen labor intensity, with desalination and solar hybridization investments affecting operational cost stability.
- All-Inclusive:Fixed-price packaging captures guest spending upfront but concentrates food cost risk. Soneva's vertical integration into sustainable food production and waste management systems exemplifies premium positioning through operational control.
- Half Board:Breakfast and dinner inclusion balances predictability with lunch flexibility for excursion-based guests.
- Bed & Breakfast:Minimal service overlay suits guesthouse cost structures on inhabited islands.
- Self-Catering:Kitchen-equipped inventory appeals to extended-stay segments in local-island permits.
All-Inclusive handles the majority of throughput; Self-Catering is gaining share fastest as community-based tourism permits proliferate.
Booking Channel:
Channel economics reshape margin structures differently across repeat-visitor segments versus first-time arrivals, with transfer packaging capabilities influencing direct capture success.
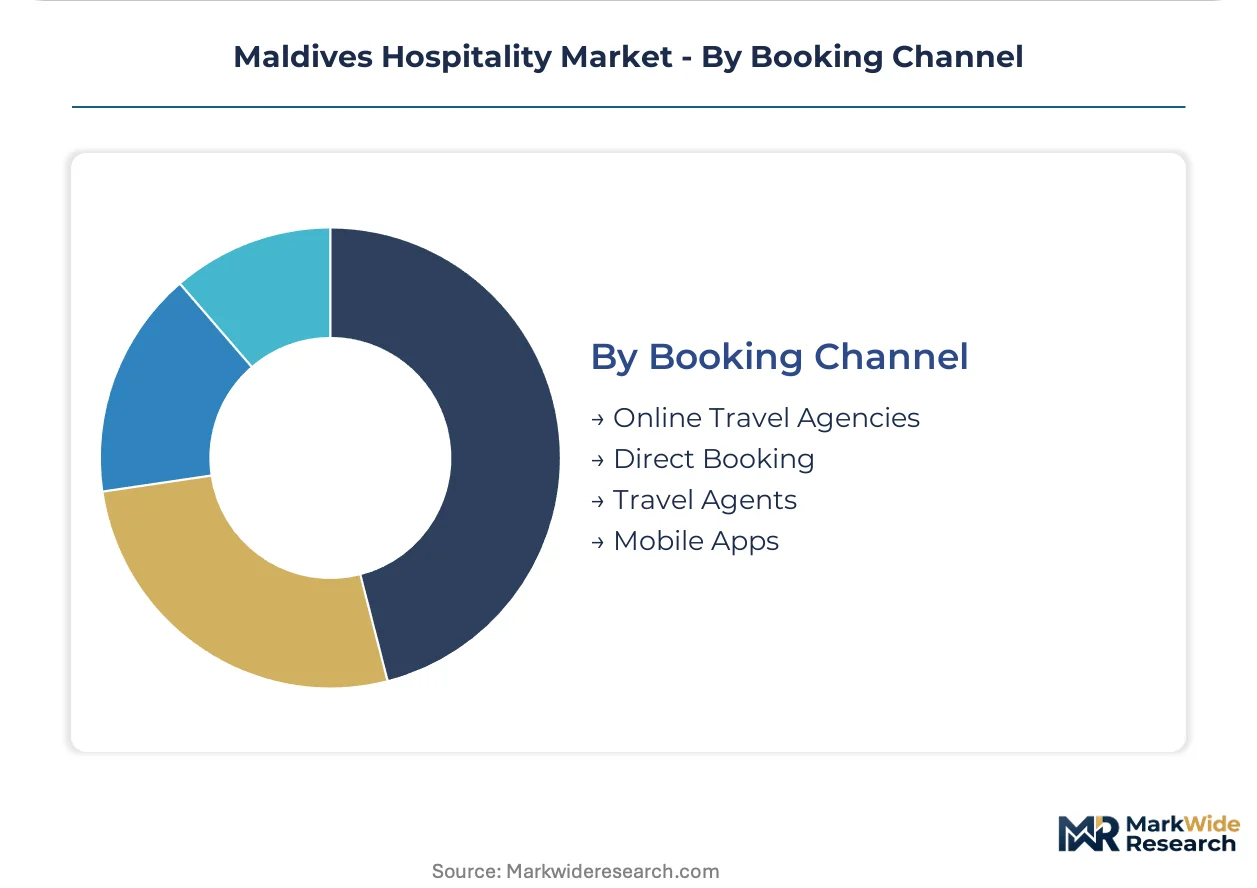
- Direct Booking:Property-owned platforms and loyalty programs capture 40-60% of reservations in established European source markets. Dynamic packaging of seaplane transfers and diving excursions reduces commission drag.
- Online Travel Agencies:Global platforms dominate first-time visitor acquisition but face displacement among Maldives-experienced travelers.
- Travel Agents:Traditional intermediaries retain relevance in emerging source markets with limited direct flight connectivity.
- Mobile Apps:Last-minute inventory clearance and upgrade bidding tools target younger demographic segments.
Online Travel Agencies handle the majority of throughput; Direct Booking is expanding most steeply as repeat-visitor databases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travelers from Germany and the United Kingdom demonstrate the highest price inelasticity for overwater villa inventory, while emerging source markets in India and Southeast Asia exhibit greater sensitivity to transfer-inclusive packaging and guesthouse alternatives.
North Male Atoll
Ultra-high-net-worth European demand concentrates in this corridor, where seaplane-accessible luxury resorts command the longest average length of stay. The Ministry of Tourism enforces cumulative density caps and reef-protection buffers that constrain new supply expansion. Hulhumale and Male serve as the primary maritime logistics hubs, with customs consolidation creating operational bottlenecks for imported construction materials.
Baa Atoll
UNESCO Biosphere Reserve status attracts marine tourism specialists and diving-centric properties with elevated environmental compliance requirements. The Environmental Protection Agency mandates reef-health baselines and decade-long monitoring commitments for new lease activations. Dharavandhoo and Eydhafushi anchor the atoll's speedboat-transfer guesthouse clusters under inhabited-island permit pathways.
Raa Atoll
Repeat-visitor segments from established European markets drive direct booking channel migration, reducing Online Travel Agency dependency. Solar hybridization and reverse-osmosis investments stabilize operational cost structures for remote properties. Ungoofaaru and Meedhoo support the atoll's emerging wellness and longevity programming segments.
Gaafu Dhaalu Atoll
Untapped reef systems and lower land-lease costs attract developers seeking remoteness differentiation beyond North Male saturation. The Ministry of Tourism applies reduced cumulative density scrutiny for southern atoll applicants. Thinadhoo and Fuvahmulah serve as regional logistics nodes with expanding speedboat connectivity.
Thaa Atoll
Extended-stay medical tourism hybrids combining ayurvedic treatment with marine therapy capture niche segments beyond traditional leisure. Community-based tourism permits enable local island guesthouse development without resort-island capital outlay. Vilufushi and Thimarafushi concentrate emerging experiential cultural programming.
Maldives Hospitality Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Maldivian archipelago. The market structures around a tiered configuration where global hospitality conglomerates, regional portfolio operators, and single-island boutique developers coexist under distinct regulatory constraints. Three archetypes dominate: vertically integrated sustainability specialists, multi-atoll standardizers, and global brand licensors. Competitive moves concentrate on modular prefabrication adoption and direct booking platform development.
Within the sustainability-integrated tier, Soneva exemplifies deep operational control through captive food production and waste management systems. Crown & Champa Resorts anchors the multi-atoll standardizer archetype with replicated operational templates across dispersed properties. Among global brand licensors, Marriott International and Hilton Worldwide occupy positions leveraging loyalty program density to reduce commission drag.
| Leading Market Players |
|---|
| AccorHotels |
| Crown & Champa Resorts |
| Marriott International |
| Minor Hotels |
| Universal Resorts |
| Hilton Worldwide |
| Hyatt Hotels Corporation |
| Soneva |
| InterContinental Hotels Group |
| Others |
Pricing and Supply Chain Analysis
Modular prefabrication from Sri Lankan and Dubai factories is displacing traditional on-site construction, compressing development timelines from eighteen months to under eight months while simultaneously reducing lagoon sedimentation exposure and reshaping capital recovery economics for southern atoll entries.
Pricing Analysis
Ancillary revenue from seaplane transfers, diving excursions, and extended villa charters drives lifetime value capture beyond accommodation rates. Three-tier pricing structure across luxury resorts, overwater villas, and guesthouse tiers reflects differential access costs and environmental compliance burdens. Pricing pressure stems from TGST layering on imported food and fuel alongside customs clearance delays at Male port. European ultra-high-net-worth leisure travelers exhibit lowest price sensitivity, while emerging Indian and Southeast Asian segments prioritize transfer-inclusive packaging.
Supply Chain Analysis
Male port consolidation creates a chokepoint where food, construction materials, and fuel undergo customs clearance before maritime distribution to dispersed atoll properties. Supply draws from Sri Lanka for modular villa components, Dubai for prefabricated building systems, and India for food staples and hospitality equipment. Diesel dependency for desalination and power generation exposes operators to commodity price volatility. Distribution runs through speedboat and seaplane operators serving resort islands and inhabited guesthouse clusters respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The government's inhabited-island tourism policy fragments the traditional one-island-one-resort model, creating white-space opportunities across community-based permits and experiential cultural programming.
For Market Incumbents: Compound brand coherence through direct booking platform investment and loyalty program density to reduce Online Travel Agency dependency. Anchor operational templates across multi-atoll portfolios to amortize compliance costs. Counter regulatory fragmentation by securing long-term monitoring commitments under Environmental Protection Agency protocols before cumulative density caps tighten further. For New Entrants and Emerging Players: Environmental Impact Assessment fast-track pathways in Gaafu Dhaalu and Thaa Atolls enable lower land-lease entry with reduced scrutiny. Target southern atoll remoteness positioning where reef-health baselines face lighter cumulative development review. Pursue community-based tourism permits on local islands to bypass resort-island capital outlay requirements entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with multi-atoll standardizers holding replicated operational templates across dispersed properties. Five-to-ten year viability hinges on solar hybridization and reverse-osmosis investments stabilizing diesel-exposed cost structures. Monitor Ministry of Tourism permit allocation velocity as inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Adoption | Factory-built units from Sri Lankan suppliers compress reef-disturbing construction windows and accelerate capital recovery. |
| Direct Booking Platform Development | Owned channels capturing repeat-visitor segments reduce commission drag and enable dynamic transfer packaging. |
| Solar Hybridization Investment | Photovoltaic arrays paired with desalination plants reduce diesel import dependency and stabilize operational costs. |
| Community-Based Tourism Permit Acquisition | Local island guesthouse development bypasses resort-island lease costs and accesses speedboat-transfer catchments. |
| Integrated Wellness Programming Launch | Medical tourism hybrids combining ayurvedic treatment with marine therapy capture extended-stay segments beyond leisure. |
Research Methodology
Desk research of Maldives Customs Service trade records, Ministry of Tourism permit databases, and Environmental Protection Agency assessment filings preceded structured interviews with resort development executives, atoll logistics coordinators, and guesthouse permit holders. Primary fieldwork with marine construction contractors and seaplane operators validated secondary data on inter-atoll connectivity constraints. Bottom-up property inventory counts triangulated against top-down tourism receipts aggregation.
Variance decomposition across property type, customer segment, service architecture, and atoll geography informed analytical framework construction over the projection horizon. CAGRs derived from spend-per-guest duration modeling and ancillary capture rate assumptions. Forecast inputs incorporated reef-protection buffer expansion scenarios and TGST compliance cost trajectories.
Decision-makers should treat outputs as directional under stable regulatory enforcement and diesel price assumptions; material deviation in Environmental Protection Agency scrutiny intensity would warrant model refresh. Practitioners should keep alternative scenarios live as inhabited-island tourism policy implementation and southern atoll infrastructure development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
India Outbound Tourism Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Tourism Vehicle Rental Market