
 Asia Pacific Wellness Travel Market | 2026-2036
Asia Pacific Wellness Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wellness Travel Market Insights
The EU Green Deal's extraterritorial supply-chain disclosure requirements is pivoting Asia Pacific wellness resort operators toward carbon-accountable sourcing. Four Seasons Hotels leverages its captive organic farm network across Bali and Maldives to sustain ingredient traceability. Banyan Tree Holdings anchors its competitive position through deep vertical integration into tropical horticulture and indigenous therapy training academies. Accor competes via its multi-brand portfolio spanning economy wellness hostels to ultra-luxury thermal retreats.
Asia Pacific wellness travel encompasses structured itineraries combining preventive health services, therapeutic activities, and restorative environments within dedicated hospitality facilities, typically integrating medical screenings, nutrition programming, and movement disciplines across stays of three to fourteen nights. Spa Services and Holistic Therapies dominate current revenue pools, though Yoga Retreats represent the fastest-growing segment as post-pandemic stress-management demand reshapes booking patterns. Wellness Enthusiasts and Retirees concentrate margin capture, while All-Inclusive Packages sustain higher per-guest economics than Customizable Itineraries through predictable occupancy and ancillary spend.
Thailand's Ministry of Public Health wellness tourism certification, Japan's METI sustainable tourism standards, and Australia's TGA guidelines for on-site medical services collectively elevate compliance thresholds for cross-border operators. These frameworks shape product architecture by mandating accredited practitioner ratios, facility hygiene protocols, and environmental impact disclosures that determine market access. Stakeholders must monitor regulatory divergence between ASEAN harmonization efforts and national-level certification schemes when allocating capital across multi-country portfolios.
Market Dynamics
Japan's METI sustainable tourism standards and Thailand's wellness certification mandates are compressing operator margins while forcing rapid facility upgrades across the Asia Pacific wellness travel corridor.
Growth Catalysts
- Preventive health services integration:Medical screening protocols embedded within resort stays attract high-net-worth Wellness Enthusiasts seeking diagnostic value alongside leisure. Thailand's Ministry of Public Health certification validates these hybrid offerings.
- EU Green Deal supply-chain disclosure:Extraterritorial carbon-accountability requirements push Asia Pacific operators toward organic farm networks and traceable ingredient sourcing, opening premium positioning for compliant estates.
- Post-pandemic stress-management demand:Yoga Retreats capture fastest-growing segment status as corporate wellness programs fund structured employee recovery itineraries across Bali, Phuket, and Chiang Mai.
Market Restraints
- Accredited practitioner scarcity:Thailand's mandatory practitioner-to-guest ratios and Japan's METI facility standards create bottlenecks in indigenous therapy training pipeline expansion.
- Organic input cost volatility:Captive farm networks in tropical horticulture face climate-driven yield instability, compressing margin predictability for vertically integrated operators.
- ASEAN regulatory divergence:Harmonization gaps between national certification schemes force multi-country portfolio operators to maintain parallel compliance architectures.
Strategic Opportunities
- Vietnam's underpenetrated central coast:Da Nang to Hoi An corridor lacks integrated wellness estate density, offering first-mover positioning for thermal retreat development.
- Digital health convergence:Wearable biometric monitoring fused with traditional movement disciplines enables personalized programming that commands extended stay durations.
- Australia's TGA medical service guidelines:On-site diagnostic licensing creates regulatory tailwind for operators embedding accredited preventive health services within hospitality frameworks.
Industry Challenges
- Indigenous therapy practitioner certification timelines:Australia's TGA and Thailand's Ministry of Public Health impose multi-year accreditation windows that delay service line expansion.
- Legacy property retrofit capex intensity:Japan's METI energy efficiency and hygiene protocol upgrades demand substantial capital redeployment from aging resort stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wellness Travel Market |
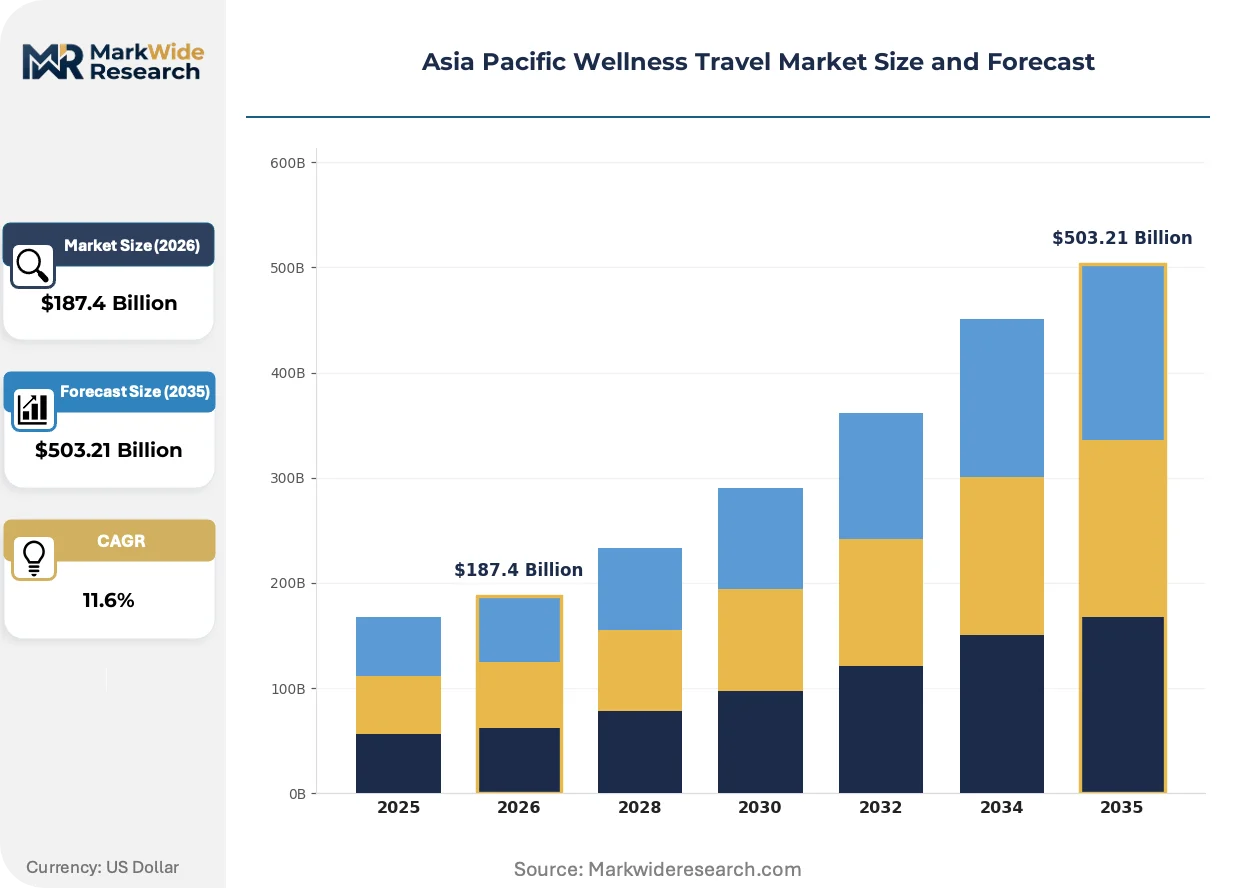
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spa Services, Yoga Retreats, Holistic Therapies, Wellness Cruises Customer Type: Leisure Travelers, Business Travelers, Retirees, Wellness Enthusiasts Package Type: All-Inclusive Packages, Customizable Itineraries, Group Packages, Family Packages Facility Type: Resorts, Retreat Centers, Hotels, Health Spas |
| Companies Covered | Four Seasons Hotels, Banyan Tree Holdings, Accor, Hyatt Hotels Corporation, Minor International, Marriott International, InterContinental Hotels Group, Six Senses Hotels Resorts Spas, Hilton Worldwide, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wellness Travel Market Trends and Innovations
Biometric personalization and carbon-accountable sourcing are restructuring how wellness estates design stays, with regulatory compliance now serving as a direct revenue driver rather than cost center.
Digital health platforms are absorbing guest data streams from wearable devices to tailor movement programming, nutrition timing, and sleep architecture in real-time. High-end retreat operators in Phuket and Maldives deploy these systems to compress guest-to-practitioner ratio economics while sustaining premium positioning. The technology is absorbing traditional static itinerary models into dynamic, responsive wellness protocols.
Japan's METI sustainable tourism standards now mandate environmental impact disclosures that determine market access for inbound-focused estates. Operators must document carbon intensity across supply chains, elevating captive organic sourcing from competitive advantage to compliance necessity. Thailand's resort corridor from Phuket to Chiang Mai responds by accelerating farm-to-table infrastructure investment.
Corporate wellness procurement now favors fixed-duration, outcome-specified contracts over individual leisure bookings. Human resources departments at technology and financial services firms negotiate group rates for structured recovery programs. This buyer concentration is most visible in Singapore and Sydney, where employers subsidize three-to-seven-night preventive health itineraries as retention instruments.
Asia Pacific Wellness Travel Market Segmentation
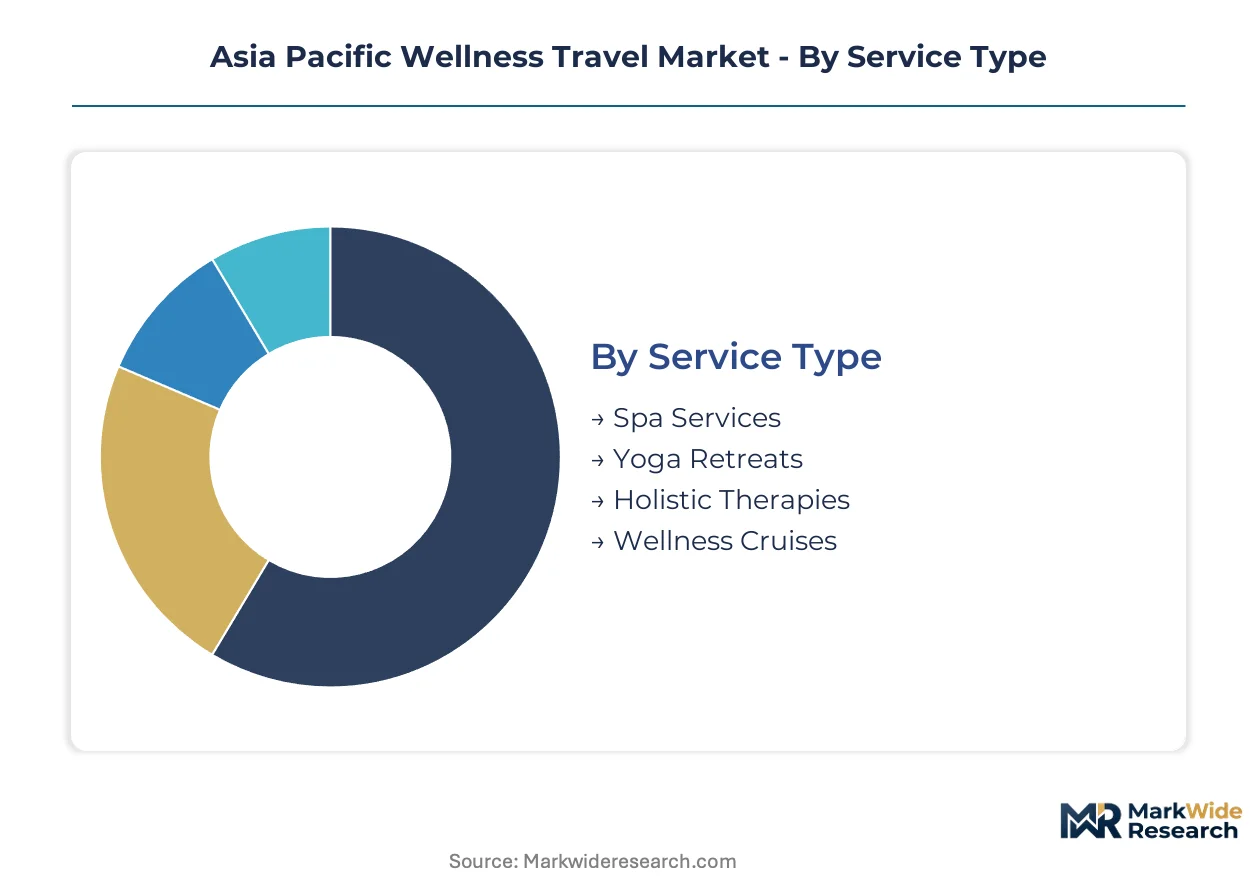
Wellness travel operators in Asia Pacific architect revenue streams around service modality, guest profile, and stay configuration. Each segmentation axis carries distinct margin profiles and capital intensity requirements that shape portfolio construction decisions.
Service Type:
Upgrade cycles in service delivery now center on digital health integration and carbon-accountable sourcing rather than facility refurbishment alone.
- Spa Services:Therapeutic treatments combining indigenous modalities with accredited practitioner protocols dominate current revenue pools. Thailand's Ministry of Public Health certification mandates elevate hygiene and training standards across Phuket and Chiang Mai resort corridors.
- Yoga Retreats:Structured movement programming of three-to-fourteen night duration captures post-pandemic stress-management demand from corporate wellness procurement. Bali's Ubud cluster and India's Rishikesh anchor supply concentration for instructor-led intensive formats.
- Holistic Therapies:Integrative approaches fusing Ayurvedic, TCM, and naturopathic protocols require extended practitioner training timelines.
- Wellness Cruises:Floating facilities along Vietnam's Halong Bay and Myanmar's Irrawaddy deliver itinerant programming with lower fixed-cost exposure.
Spa Services sits at the top of the volume ranking, with Yoga Retreats climbing the fastest.
Customer Type:
Margin concentration follows guest lifetime value and ancillary spend elasticity rather than booking frequency alone.
- Wellness Enthusiasts:High-repeat guests seeking diagnostic value through embedded medical screenings drive premium positioning. Japan's METI sustainable tourism standards validate their preference for carbon-accountable estates.
- Retirees:Extended-stay guests averaging seven-to-fourteen nights sustain predictable occupancy and high spa-to-room ratios across Thailand's integrated wellness estates.
- Leisure Travelers:Shorter-duration guests mixing wellness with cultural tourism generate lower per-night economics.
- Business Travelers:Compressed-stay demand from Singapore and Sydney corporate accounts favors outcome-specified recovery programming.
Wellness Enthusiasts command the premium tier, with Business Travelers expanding most quickly through employer-subsidized procurement.
Package Type:
Cost tier stratification separates predictable occupancy models from customization-heavy offerings with higher operational complexity.
- All-Inclusive Packages:Fixed-duration, bundled pricing covering accommodation, meals, and core therapies sustains higher per-guest economics through predictable ancillary capture. Australia's TGA-compliant medical service add-ons deepen value proposition for preventive health seekers.
- Customizable Itineraries:Modular programming allowing guest-directed service selection carries higher staffing flexibility costs and variable margin outcomes.
- Group Packages:Corporate and affinity-block bookings concentrate demand into shoulder seasons with negotiated rate structures.
- Family Packages:Multi-generational programming combining adult wellness with supervised youth activities expands addressable market.
All-Inclusive Packages anchor revenue stability, with Customizable Itineraries gaining share fastest among independent luxury travelers.
Facility Type:
Supply concentration in purpose-built retreats versus converted hospitality stock determines compliance cost burdens and positioning latitude.
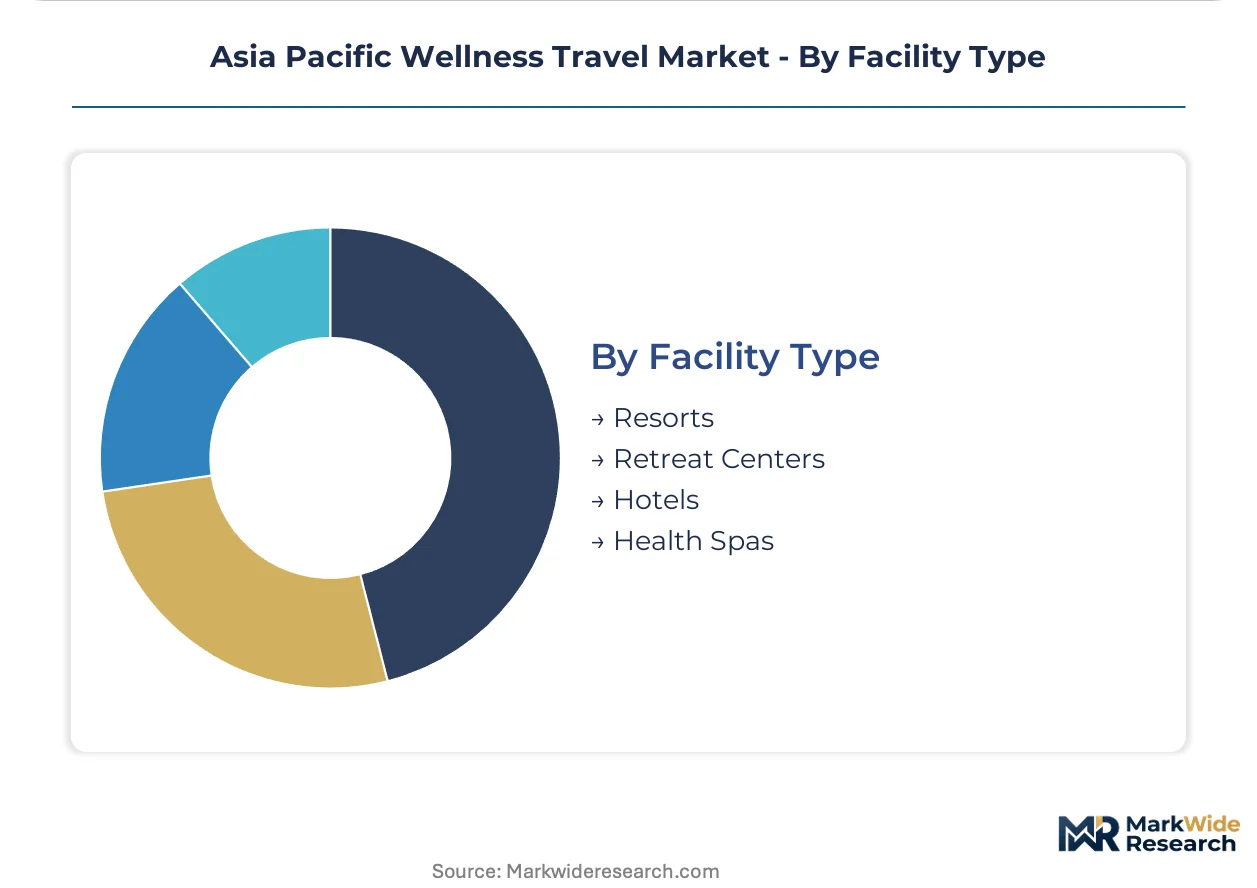
- Resorts:Integrated wellness estates from Phuket to Maldives combining accommodation, therapeutic facilities, and captive organic sourcing represent the capital-intensive core of regional supply.
- Retreat Centers:Single-purpose facilities optimized for immersive programming achieve highest practitioner-to-guest ratios and outcome measurability.
- Hotels:Wellness-programmed urban and resort properties compete on location convenience with lighter service depth.
- Health Spas:Day-use and short-stay facilities without accommodation component serve local demand and cruise excursion segments.
Resorts dominate capital deployment, with Retreat Centers showing steepest expansion trajectory among purpose-built new developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand pioneered Asia Pacific wellness tourism in the 1990s through Ayurvedic and traditional Thai therapy resorts in Phuket. Japan and Australia subsequently developed regulatory frameworks that elevated clinical standards across the region. Today's market spans purpose-built estates from Bali to Queensland, with national certification schemes determining operator access.
Thailand
Medical screening protocols embedded in resort stays attract Wellness Enthusiasts seeking diagnostic value alongside leisure. The Ministry of Public Health wellness tourism certification mandates accredited practitioner-to-guest ratios and facility hygiene standards. Phuket to Chiang Mai corridor hosts integrated wellness estates commanding premium positioning through captive organic sourcing.
Japan
Onsen thermal traditions and preventive health culture sustain demand for structured recovery itineraries among domestic and inbound guests. METI sustainable tourism standards mandate environmental impact disclosures and energy efficiency upgrades for market access. Kyushu and Hokkaido retreat clusters respond with carbon-accountable supply chain documentation and digital health platform integration.
Australia
TGA guidelines for on-site medical services create regulatory pathway for diagnostic-embedded hospitality offerings targeting corporate wellness procurement. Queensland and New South Wales coastal estates leverage these standards to differentiate preventive health programming. Byron Bay and Noosa clusters concentrate new development capital around accredited practitioner training pipelines.
Indonesia
Ubud's yoga retreat density and Bali's organic farm networks attract post-pandemic stress-management demand from employer-subsidized corporate accounts. The national tourism ministry coordinates with provincial authorities on wellness estate classification standards. Lombok and Sumba emerging corridors offer lower land costs for thermal retreat and immersive programming developments.
Vietnam
Da Nang to Hoi An central coast remains underpenetrated relative to regional supply density, offering first-mover positioning for integrated estate development. Provincial investment promotion agencies target foreign operators with land use incentives for healthcare-hospitality hybrid projects. Halong Bay wellness cruise segments serve excursion demand with lower fixed-cost exposure than land-based facilities.
Asia Pacific Wellness Travel Market Competitive Landscape
Capital-heavy resort owners compete with asset-light management companies across Asia Pacific wellness travel. The market structure concentrates around integrated estate operators with captive supply chains, fragmented boutique retreat centers, and multi-brand hospitality conglomerates. Three archetypes dominate: vertically integrated tropical estate developers, urban wellness-programmed hotel operators, and specialized immersive retreat center managers. Competitive dynamics center on M&A-driven portfolio expansion and regulatory compliance certification acquisition.
Among integrated estate developers, Four Seasons Hotels and Banyan Tree Holdings exemplify the captive organic sourcing archetype through Bali and Maldives farm networks. Accor occupies a position spanning economy wellness hostels to ultra-luxury thermal retreats through multi-brand portfolio architecture. Hyatt Hotels Corporation anchors the management-contract tier, representing asset-light expansion models that separate property ownership from operational expertise.
| Leading Market Players |
|---|
| Four Seasons Hotels |
| Banyan Tree Holdings |
| Accor |
| Hyatt Hotels Corporation |
| Minor International |
| Marriott International |
| InterContinental Hotels Group |
| Six Senses Hotels Resorts Spas |
| Hilton Worldwide |
| Others |
Pricing and Supply Chain Analysis
Accredited indigenous therapy practitioners concentrated across Thailand's Phuket-Chiang Mai corridor and Japan's Kyushu-Hokkaido clusters create labor-cost differentials that widen pricing-tier spreads between METI-certified estates and uncertified competitors. Thailand's Ministry of Public Health mandatory practitioner-to-guest ratios elevate staffing costs for compliant operators, forcing three-tier pricing stratification that separates carbon-accountable integrated estates from modular retreat centers and day-use spa facilities.
Pricing Analysis
All-inclusive bundled pricing covering accommodation, meals, and core therapies dominates revenue architecture across Asia Pacific wellness estates. Price differentiation hinges on METI sustainable tourism certification grade and captive organic sourcing traceability, with carbon-accountable estates commanding premium positioning over conventional competitors. Pricing pressure intensifies in the standard tier as ASEAN regulatory divergence forces parallel compliance investments that compress margins. Wellness Enthusiasts seeking diagnostic-embedded medical screenings exhibit lowest price sensitivity, while Leisure Travelers mixing wellness with cultural tourism drive volume at compressed per-night economics.
Supply Chain Analysis
Workforce availability constraints in Thailand, Indonesia, and Vietnam shape supply chain configuration for wellness estate development and operation. Captive organic farm networks in Bali and Maldives draw from tropical horticulture expertise, while indigenous therapy practitioner pipelines rest on multi-year accreditation timelines mandated by Australia's TGA and Thailand's Ministry of Public Health. Single-source vulnerability pervades accredited practitioner training academies, where certification bottlenecks limit service line expansion. Distribution runs through direct booking platforms and corporate wellness procurement channels concentrated in Singapore and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where compliance certification increasingly determines market access and pricing power. Japan's METI sustainable tourism standards represent the pivotal regulatory milestone, embedding environmental impact disclosure requirements that reshape operator investment priorities and buyer procurement criteria across the region.
For Market Incumbents: Lock in practitioner training pipeline control through accredited academy partnerships or in-house certification programs to defend against emerging boutique retreat competitors. METI facility upgrade mandates threaten aging resort stock with stranded asset risk; prioritize energy efficiency retrofit capex in Japan and Thailand over expansion into unproven geographies. Deepen backward integration into tropical horticulture to secure organic input cost predictability against climate-driven yield volatility. For New Entrants and Emerging Players: The price-point gap between ultra-luxury thermal retreats and economy wellness hostels creates white-space opportunity for mid-market integrated estates with streamlined service depth. Vietnam's Da Nang-Hoi An corridor offers lowest competitive density for first-mover thermal retreat positioning. Corporate wellness procurement channels in Singapore and Sydney provide concentrated demand access through outcome-specified contract structures that reduce customer acquisition cost versus individual leisure marketing. For Investors and Strategic Acquirers: Hospitality conglomerates with multi-brand portfolio architecture are the most active acquirer in this space, seeking vertical integration into captive supply chains and indigenous therapy training infrastructure. Long-term viability over the coming decade hinges on regulatory compliance certification moats rather than location or facility quality alone. Monitor divergence between ASEAN harmonization progress and national-level certification scheme proliferation as the critical inflection indicator for multi-country portfolio capital allocation efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Organic Farm Network Expansion | Four Seasons and Banyan Tree leverage Bali-Maldives farm infrastructure to sustain ingredient traceability under EU Green Deal disclosure mandates. |
| Accredited Practitioner Training Academy Investment | Banyan Tree anchors competitive positioning through indigenous therapy training pipelines that satisfy Thailand's Ministry of Public Health certification ratios. |
| Digital Health Platform Integration | Wearable biometric monitoring deployment across Phuket and Maldives estates compresses guest-to-practitioner economics while extending stay duration. |
| METI Compliance Retrofit Program | Japan's sustainable tourism standards force energy efficiency and hygiene protocol upgrades that determine market access for inbound-focused estates. |
| Corporate Wellness Procurement Channel Development | Human resources departments at Singapore and Sydney technology and financial services firms negotiate group rates for structured recovery programs. |
Research Methodology
Multiple input streams — structured interviews with resort operations executives, wellness program directors, and corporate wellness procurement officers; regulatory filing analysis from Thailand's Ministry of Public Health, Japan's METI, and Australia's TGA; and trade data from hospitality investment databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from tourism ministry statistics, wellness estate development permits, and corporate wellness contract disclosures. Cross-referencing primary stakeholder intelligence against published certification standards and facility investment records ensured data integrity across market sizing and competitive positioning assessments.
Historical booking pattern analysis was cross-referenced against panel input from resort revenue managers and wellness program pricing strategists to construct projection frameworks. Segmentation modeling spanned service type, guest profile, package configuration, and facility archetype dimensions across the analysis window. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts and corporate wellness procurement growth curves. Forecast inputs incorporated METI compliance timeline assumptions and ASEAN harmonization scenario weighting.
Caveats apply where regulatory divergence acceleration, climate-driven organic input cost spikes, or practitioner certification pipeline failures could materially shift the outlook. Forecasts embed assumptions regarding sustained employer-subsidized wellness travel demand and continued carbon-accountability premium capture. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Incentive Travel Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
Educational Tourism Market