
 Travel and Tourism Market | 2026-2036
Travel and Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Travel and Tourism Market Outlook
Corporate buyer concentration is restructuring travel procurement, with multinational enterprises consolidating spend through preferred supplier agreements and integrated booking platforms. Booking Holdings leverages its agency network to capture this consolidated demand, while Navan competes through direct corporate subscription models that bypass traditional commission structures. Expedia Group anchors its position in leisure segments where individual travelers still fragment across comparison sites.
Travel and tourism encompasses the commercial organization of temporary movement of persons for leisure, business, or other purposes, combining transportation infrastructure, lodging assets, destination services, and financial protection instruments into coordinated consumption packages. The sector operates through inventory aggregation systems that match perishable supply—airline seats, hotel room-nights, tour capacity—with time-sensitive demand across global distribution networks. Accommodations and transportation command the dominant value share, while mobile apps represent the fastest-expanding booking channel as smartphone penetration eliminates friction in last-minute itinerary changes. Tour operations retain higher margin pools in experiential and adventure sub-categories where customization commands premium pricing.
The EU Green Deal and its Fit for 55 regulatory package impose escalating carbon disclosure obligations on aviation and hospitality providers, reshaping capital allocation toward lower-emission fleet and property assets. The FAA's operational certification requirements for new urban air mobility entrants create compliance barriers that filter which technology platforms can integrate aerial services into multimodal itineraries. Stakeholders must monitor how biometric identity standards proliferate across border control agencies and whether interoperability failures fragment seamless travel ambitions.
Market Dynamics
Corporate travel procurement is consolidating around centralized platforms as enterprises enforce duty-of-care compliance and negotiated rate compliance, compressing traditional agency commission structures while expanding direct subscription revenue models.
Growth Catalysts
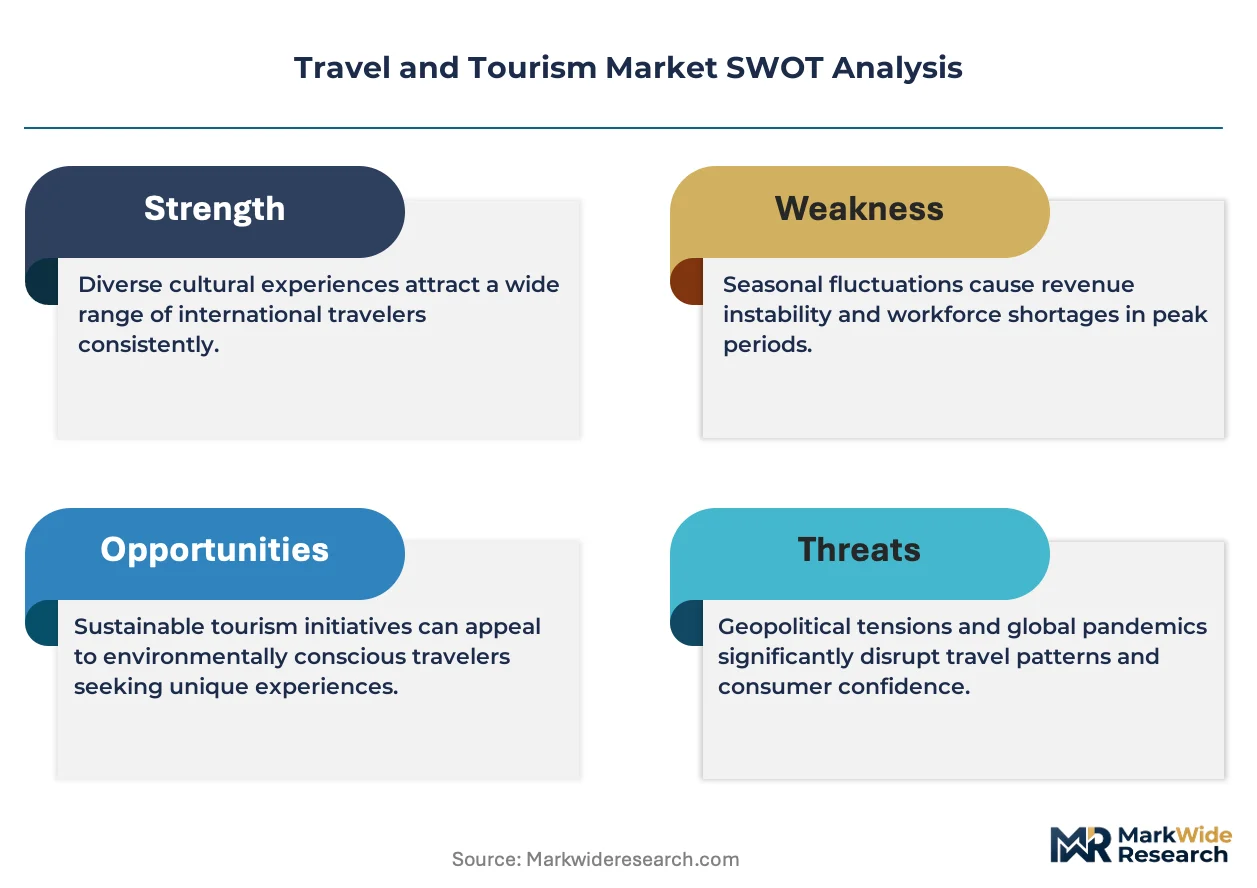
- EU Green Deal carbon disclosure mandates:Aviation and hospitality providers face escalating reporting obligations that redirect capital toward lower-emission assets, creating retrofit demand across European fleet and property portfolios.
- India's outbound middle-class expansion:Accelerating international departure volumes from tier-2 and tier-3 cities generate new route development and destination marketing investment from carriers and tourism boards.
- Urban air mobility certification pathways:FAA operational requirements for electric vertical take-off and landing vehicles are opening multimodal itinerary integration opportunities for early-mover technology platforms.
Market Restraints
- Jet fuel price volatility:Airlines face margin compression from unhedged energy exposure, forcing capacity discipline and fleet utilization trade-offs during price spike periods.
- Biometric interoperability failures:Fragmented identity verification standards across border control agencies create friction in seamless travel corridors, limiting passenger throughput efficiency.
- Short-term rental regulatory clampdown:Municipal zoning restrictions in Barcelona, Amsterdam, and Lisbon reduce available inventory and compress platform supply elasticity.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea Development destinations require integrated destination management systems, creating white space for experiential tour operators and luxury hospitality developers.
- AI-driven dynamic packaging:Real-time itinerary assembly combining flights, ground transport, and activities is converging with predictive demand modeling to capture last-minute booking windows.
- Corporate subscription bypass models:Direct enterprise relationships that eliminate traditional GDS fees are capturing consolidated spend from multinational procurement functions.
Industry Challenges
- Aviation workforce pipeline gaps:Pilot, mechanic, and air traffic controller shortages constrain capacity restoration and route expansion timelines across North American and European carriers.
- Legacy PMS integration complexity:Hotel property management system fragmentation impedes unified guest data platforms and personalized service delivery at scale.
- Carbon offset verification credibility:Inconsistent standards for emission reduction claims expose hospitality brands to greenwashing liability and regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel and Tourism Market |
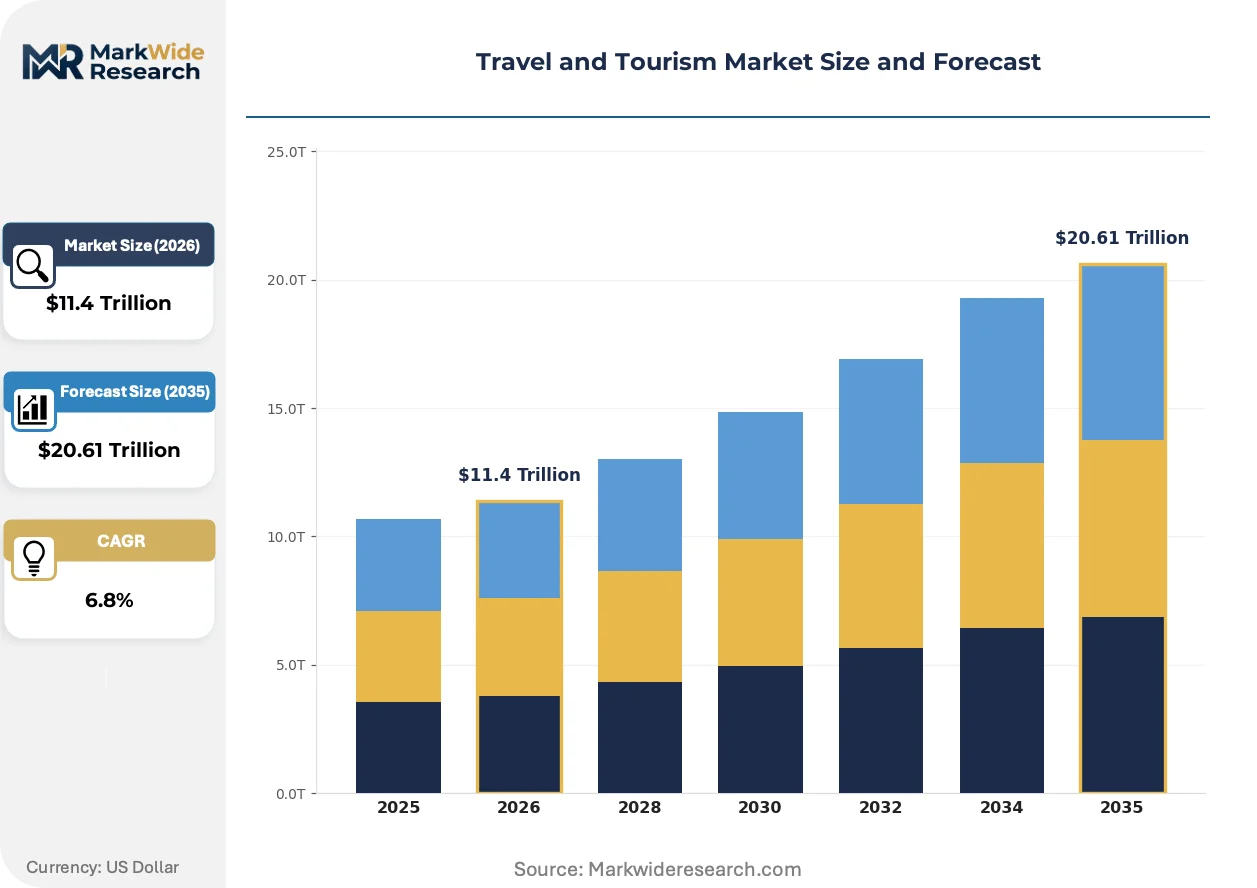
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $20.61 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodations, Transportation, Tour Operations, Travel Insurance Customer Type: Leisure Travelers, Business Travelers, Group Tours, Solo Travelers Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps Destination Type: Urban Areas, Rural Areas, Adventure Spots, Cultural Sites |
| Companies Covered | Booking Holdings, Navan, Delta Air Lines, Agoda, Priceline, Expedia Group, Trip.com Group, Skyscanner, Hilton Worldwide Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel and Tourism Market Strategic Shifts
Digital identity verification and artificial intelligence are restructuring how travelers discover, book, and experience destinations, compressing friction points while raising data governance stakes.
Biometric facial recognition is converging with mobile boarding pass systems at airport touchpoints. Major hub operators in Singapore, Dubai, and Amsterdam are deploying end-to-end identity corridors that eliminate document checks. This convergence is compressing passenger processing times and redefining staffing models across ground handling contracts.
The EU's Fit for 55 regulatory package imposes escalating sustainable aviation fuel blending mandates and carbon border adjustments on intra-European routes. Airlines are responding with fleet renewal commitments and operational efficiency investments. Short-haul carriers face the steepest compliance cost curves as regional aircraft replacement cycles accelerate.
Experience-driven travelers are displacing traditional package tour purchases with modular, self-assembled itineraries booked through mobile applications. Southeast Asian and Latin American destinations are capturing this demand rotation as infrastructure investment improves last-mile connectivity. Direct supplier relationships are fragmenting traditional agency intermediation in these corridors.
Travel and Tourism Market Segmentation
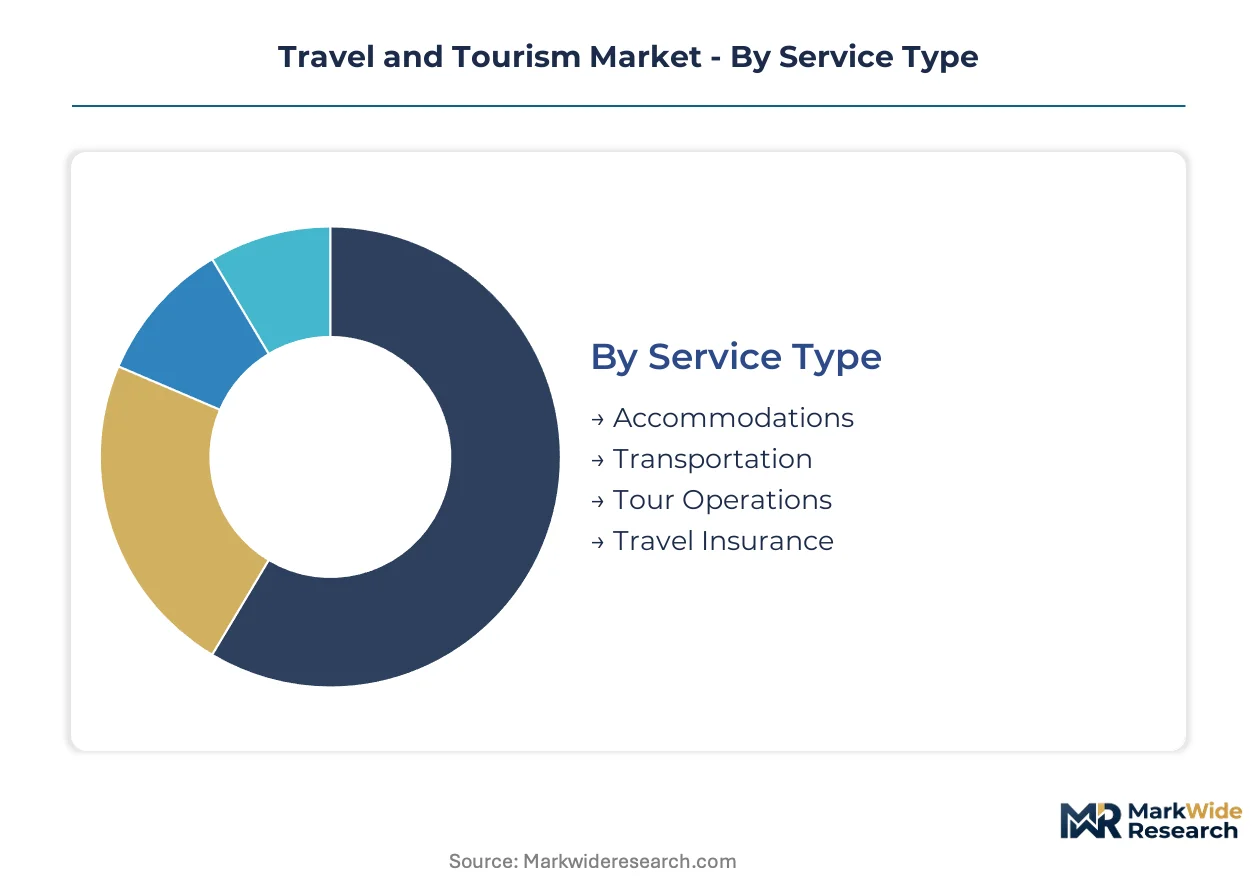
Travel and tourism segmentation reveals how service configuration, customer motivation, and channel preference fragment revenue pools across radically different operational models. Standardized transportation inventory competes with hyper-customized experiential packages for the same consumer wallet.
Service Type:
Customization intensity varies dramatically from commoditized seat-miles to bespoke itinerary design across this category.
- Accommodations:Property assets range from limited-service economy lodging to full-service resorts with integrated F&B and spa operations. India's tier-2 city hotel development and Saudi Arabia's giga-project luxury pipeline concentrate capital deployment in branded and independent properties respectively.
- Transportation:Scheduled airline capacity, rail networks, rental fleets, and emerging urban air mobility platforms coordinate multimodal movement. EU Green Deal carbon disclosure mandates are redirecting fleet investment toward lower-emission aircraft and electrified ground transport across European carrier portfolios.
- Tour Operations:Packaged experiences combining guides, activities, and logistics into fixed-departure or private itineraries. Adventure and experiential sub-categories command premium pricing through customization.
- Travel Insurance:Financial protection instruments covering trip cancellation, medical evacuation, and baggage loss. Corporate duty-of-care compliance is expanding group policy penetration.
Most installed capacity flows through Transportation. Expansion is steepest in Accommodations.
Customer Type:
Volume concentration and margin profile diverge sharply between price-sensitive mass leisure and contracted corporate accounts.
- Leisure Travelers:Individual and family consumers booking discretionary trips with flexible timing and destination choice. Mobile app penetration is eliminating friction in last-minute itinerary changes for this segment.
- Business Travelers:Corporate-account road warriors operating under negotiated rate agreements and centralized booking platform mandates. Duty-of-care compliance requirements are consolidating procurement around preferred supplier relationships.
- Group Tours:Organized departures for affinity groups, educational institutions, and incentive travel programs. Commission compression is forcing operators toward direct subscription models.
- Solo Travelers:Individual explorers seeking flexible, self-directed experiences without group coordination constraints. Southeast Asian and Latin American destinations are capturing this demand rotation.
Leisure Travelers absorb the largest volume share. Solo Travelers are climbing the fastest as demographic shifts and remote work enable independent mobility.
Booking Channel:
Channel economics fragment between high-commission intermediary networks and zero-commission direct relationships.
- Online Travel Agencies:Digital platforms aggregating inventory from multiple suppliers into comparison-driven booking environments. Consolidated corporate spend is restructuring commission structures.
- Direct Booking:Supplier-owned websites and loyalty programs capturing reservations without intermediary fees. Hotel chains are investing in property management system integration to enable personalized service delivery.
- Travel Agents:Human advisors providing consultation, complex itinerary assembly, and crisis support. Traditional agency models face compression from self-service digital alternatives.
- Mobile Apps:Smartphone-native interfaces enabling spontaneous booking, real-time itinerary modification, and location-based service discovery. Smartphone penetration is accelerating this channel's expansion.
Online Travel Agencies currently dominate transaction volume. Mobile Apps are gaining share fastest as last-minute booking behavior proliferates.
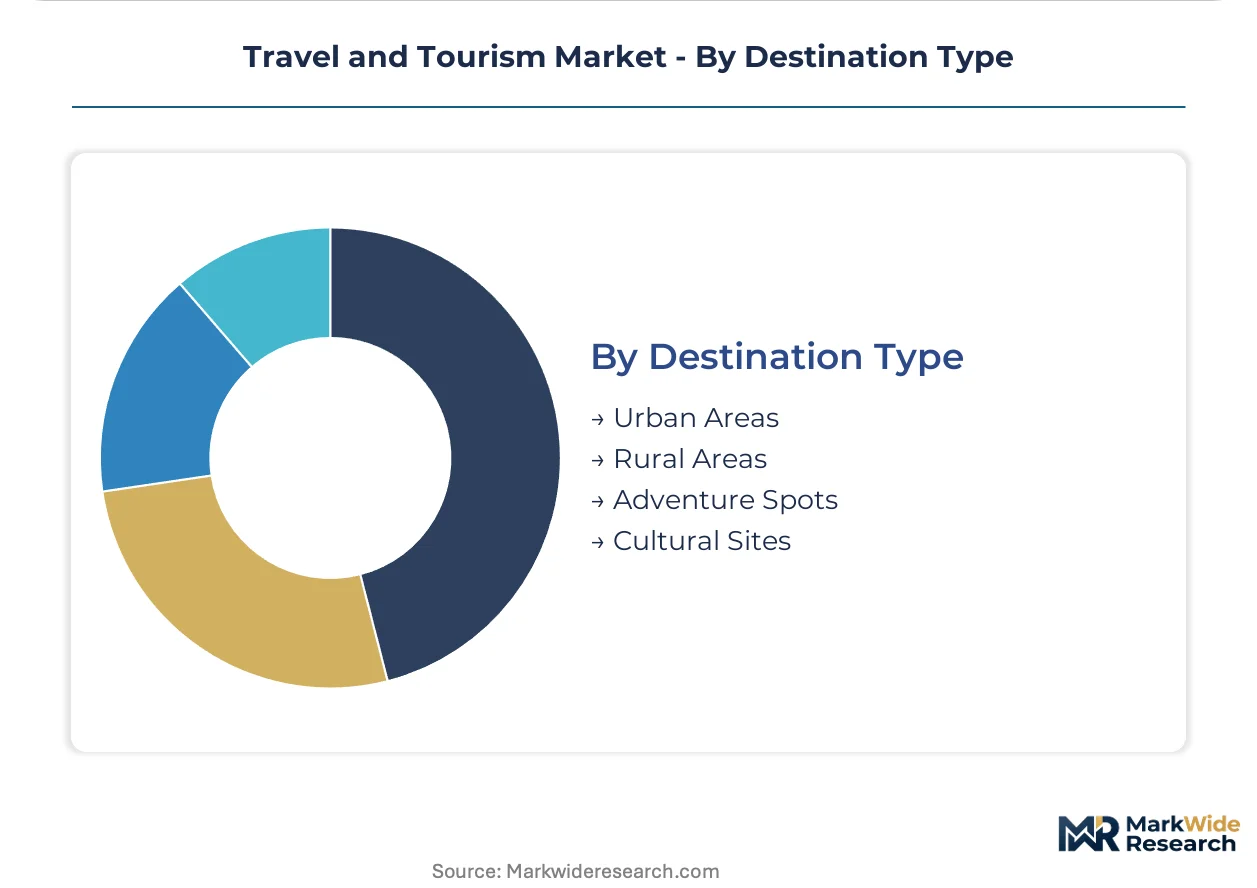
Destination Type:
Infrastructure maturity and experiential positioning create distinct competitive arenas across physical geography.
- Urban Areas:Metropolitan destinations with dense lodging inventory, convention infrastructure, and multimodal transport connectivity. Short-term rental regulatory clampdowns in Barcelona, Amsterdam, and Lisbon are compressing supply elasticity.
- Rural Areas:Countryside and small-town destinations emphasizing agritourism, wellness retreats, and nature immersion. Last-mile connectivity gaps constrain accessibility.
- Adventure Spots:Locations prioritizing physical activity, extreme sports, and wilderness exploration. Nepal's trekking corridors and Patagonia's expedition infrastructure exemplify this positioning.
- Cultural Sites:Heritage destinations anchored by historical monuments, archaeological zones, and living traditions. Italy's UNESCO clusters and Japan's temple circuits concentrate visitation.
Urban Areas command the dominant share of bed-nights. Adventure Spots show the steepest expansion trajectory as experiential travel preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce concentrations in hospitality operations, aviation maintenance, and destination management anchor competitive positioning across major travel economies. Talent pipelines for pilots, hotel management, and experience design differentiate regional growth trajectories.
United States
Corporate travel procurement consolidation and leisure demand recovery drive booking platform expansion. FAA certification requirements for urban air mobility vehicles create compliance frameworks for electric vertical take-off and landing integration. Orlando and Las Vegas hospitality clusters concentrate investment in integrated resort management systems.
Germany
Business travel rate negotiations and sustainability reporting obligations reshape corporate procurement patterns. EU Green Deal carbon disclosure mandates redirect Lufthansa fleet investment toward lower-emission aircraft. Munich and Frankfurt aviation hubs anchor multimodal itinerary development for European corporate accounts.
China
Domestic tourism infrastructure expansion and outbound visa facilitation accelerate reservation platform growth. MIIT data governance standards impose localization requirements on international booking engines. Shanghai and Guangzhou metropolitan corridors concentrate luxury hospitality development and high-speed rail connectivity investment.
India
Tier-2 and tier-3 city middle-class expansion generates international departure volume growth for carriers and destination marketers. DGFT outward remittance frameworks shape payment infrastructure for overseas travel bookings. Mumbai and Delhi-NCR aviation clusters anchor route development toward Southeast Asian and Middle Eastern destinations.
Saudi Arabia
Giga-project destination development creates demand for integrated destination management and experiential tour operations. SFDA hospitality standards and tourism licensing frameworks regulate service quality for NEOM and Red Sea Development sites. Riyadh and Jeddah urban corridors concentrate hotel investment ahead of projected visitor arrival targets.
Travel and Tourism Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across inventory aggregation, property ownership, and airline operations. The market structure tiered between global platform operators, regional carrier networks, and asset-heavy hospitality owners. Three archetypes dominate: digital marketplace aggregators capturing fragmented demand, full-service airlines controlling seat inventory, and branded hotel chains managing property portfolios. Competitive moves concentrate on strategic partnerships between platforms and suppliers, plus direct subscription models that bypass traditional commission structures.
Within the digital marketplace tier, Booking Holdings and Expedia Group occupy positions as inventory aggregators spanning multiple travel verticals. Trip.com Group anchors the Asia-Pacific demand vector. Among hospitality owners, Hilton Worldwide Holdings exemplifies the asset-light brand management archetype. Delta Air Lines sits within the network carrier tier controlling premium cabin yield management. Navan represents the emerging corporate subscription model that eliminates traditional GDS fee structures through direct enterprise relationships.
| Leading Market Players |
|---|
| Booking Holdings |
| Navan |
| Delta Air Lines |
| Agoda |
| Priceline |
| Expedia Group |
| Trip.com Group |
| Skyscanner |
| Hilton Worldwide Holdings |
| Others |
Value Chain & Pricing Dynamics
Corporate procurement consolidation around centralized booking platforms is compressing traditional agency commission structures and forcing suppliers toward direct subscription models that eliminate intermediary fees. This buyer-side restructuring reshapes how airlines, hotel chains, and tour operators configure pricing architectures and manage inventory allocation across fragmented distribution networks.
Pricing Analysis
Capacity additions in Saudi Arabia's giga-project pipeline are reshaping price floors in the luxury hospitality tier as NEOM and Red Sea Development properties absorb premium positioning. Three-tier pricing structure across premium, standard, and economy levels dominates airline seat inventory and hotel room categories, with EU Green Deal carbon disclosure mandates adding compliance cost layers that carriers pass through as environmental surcharges. Price differentiation hinges on loyalty program tier status and corporate contract volume, with leisure travelers in India's tier-2 cities showing highest price sensitivity while multinational enterprise accounts negotiate fixed-rate agreements that insulate against spot market volatility.
Supply Chain Analysis
Jet fuel logistics and sustainable aviation fuel blending mandates are elevating energy procurement costs for European carriers under EU Green Deal frameworks. Aircraft manufacturing concentrates in the United States, France, and Germany, while hospitality property development draws steel, glass, and smart building systems from China, India, and South Korea. Supply chain risk centers on single-source vulnerability for avionics components and semiconductors critical to next-generation fleet management systems. Distribution runs through global distribution system networks, direct supplier platforms, and mobile app channels that fragment inventory visibility across corporate and leisure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between EU Green Deal compliance costs in Europe and regulatory flexibility in Gulf Cooperation Council destinations, where Saudi Arabia's tourism licensing frameworks attract capital seeking lower carbon reporting burdens. This geographic differential rewards early positioning in emerging destination management systems.
For Market Incumbents: Acquire experiential tour operation assets in Saudi Arabia's giga-project corridor to capture destination management white space before competitive density increases. Consolidate loyalty program data platforms to defend against Navan-style corporate subscription models that bypass traditional global distribution system fees. Reinforce fleet renewal commitments toward lower-emission aircraft as EU Fit for 55 mandates accelerate compliance cost curves for lagging carriers. For New Entrants and Emerging Players: Enter via urban air mobility certification pathways opened by FAA operational requirements for electric vertical take-off and landing vehicles, integrating aerial services into multimodal itineraries before incumbent platforms establish dominance. Target India's tier-2 and tier-3 city outbound segments where middle-class expansion generates underbanked route development demand. Deploy AI-driven dynamic packaging engines that assemble real-time itineraries combining flights, ground transport, and activities for last-minute booking windows. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light hospitality brand managers and corporate travel subscription platforms that eliminate intermediary commission structures. Long-term viability favors operators with direct enterprise relationships and proprietary guest data platforms that enable personalized service delivery at scale. Monitor biometric identity standard proliferation across border control agencies as the signal to watch for seamless travel corridor development that compresses passenger processing friction.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate Subscription Platform Launch | Eliminates GDS fees for enterprise accounts while capturing consolidated spend from multinational procurement functions. |
| Sustainable Aviation Fuel Supply Agreement | Secures blending stock for EU Green Deal compliance while hedging against jet fuel price volatility exposure. |
| Biometric Identity Corridor Partnership | Integrates facial recognition systems with mobile boarding passes at Singapore, Dubai, and Amsterdam hub operations. |
| Experiential Tour Operator Acquisition | Captures premium pricing in adventure sub-categories where customization commands margin pools above commoditized packages. |
| Direct Booking Platform Investment | Reduces intermediary commission burden while enabling property management system integration for personalized service delivery. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline yield management executives, hotel chain revenue strategists, corporate travel procurement officers, and destination marketing organization leads with secondary validation against IATA operational statistics, ICAO carbon reporting frameworks, STR hospitality performance data, and customs/trade records for aviation fuel and construction materials. Bottom-up fleet capacity and room-night inventory modeling triangulated against top-down macroeconomic demand projections.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity, recovery trajectory inflection points, and current normalization patterns across the analysis window. Segmentation dimensions modeled include service type, customer motivation, booking channel preference, and destination infrastructure maturity, with CAGRs derived from trend extrapolation weighted against regulatory intervention scenarios. Forecast inputs incorporated EU Green Deal implementation timelines, India's outward remittance flow projections, and urban air mobility certification pathway progressions.
Inputs from airline operational filings and hospitality property development databases were available through the study window; gaps in real-time corporate travel spend aggregation introduce uncertainty bands around subscription platform adoption velocity. Forecasts reflect documented assumptions regarding biometric interoperability standardization and sustainable aviation fuel production scale-up. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
US Outbound Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Africa Wellness Tourism Market
Travel and Tourism
Digital Travel Market