
 Dark Tourism Market | 2026-2036
Dark Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Tourism Market Outlook
Guided experience revenue is tilting from standardized group packages toward personalized, small-format historical immersion. Atlas Obscura leverages its digital-native content platform to curate niche itineraries across unconventional sites. Chornobyl Tours anchors Ukrainian exclusion-zone operations through direct government licensing and radiological safety partnerships. TUI AG competes by integrating dark tourism modules into broader European cultural packages, extending its distribution reach.
Dark tourism encompasses travel to sites associated with death, tragedy, or historical suffering, requiring curatorial frameworks that balance educational mission with visitor emotional safety and physical hazard mitigation. Its commercial purpose centers on transforming historically significant locations into sustainable visitation economies through interpretive infrastructure, controlled access protocols, and revenue-sharing with preservation authorities. Memorials and historical sites command the deepest visitor engagement and longest average dwell times, while virtual reality experiences represent the fastest-growing structural segment as operators deploy immersive pre-visit and accessibility tools. Battlefields retain mature, volume-driven economics with lower per-visitor yields but substantial group-tour throughput.
Ukraine's State Agency of Tourism Development and Poland's Ministry of Culture and National Heritage jointly shape operational standards through radiological safety mandates and heritage preservation requirements, restricting unlicensed site access and elevating compliance costs for new entrants. The EU's Digital Services Act and GDPR frameworks additionally govern how operators collect, process, and retain visitor behavioral data from EU-origin bookings. Stakeholders must monitor evolving national heritage-site privatization debates and their impact on concession licensing structures.
Market Dynamics
Immersive digital pre-visit technologies are compressing the traditional guided-tour value chain, forcing operators to restructure revenue models around experiential depth rather than access control alone.
Growth Catalysts
- GDPR-compliant data frameworks:The EU's data protection standards create operational clarity for visitor behavioral tracking, enabling personalized itinerary algorithms across Polish and Ukrainian heritage corridors.
- Radiological safety certification:Ukraine's State Agency of Tourism Development mandates licensed exclusion-zone protocols, professionalizing Chornobyl access and filtering unqualified competitors.
- Independent traveler segment expansion:Solo visitors seeking unscripted historical engagement now outpace group-tour bookings, pulling investment toward modular, self-directed platform architectures.
Market Restraints
- Heritage-site concession concentration:Auschwitz-Birkenau Memorial and Museum controls access licensing for Central Europe's densest dark tourism cluster, creating single-point dependency for regional operators.
- Radiological monitoring equipment costs:Dosimetry and contamination detection hardware requires specialized procurement channels with limited supplier diversity.
- EU Digital Services Act compliance overhead:Content moderation and algorithmic transparency obligations impose fixed-cost burdens disproportionately affecting small-format tour operators.
Strategic Opportunities
- Virtual reality accessibility tools:Immersive pre-visit technologies open exclusion-zone experiences to mobility-limited demographics previously barred by physical access constraints.
- Battlefield heritage corridors in Poland:Underdeveloped sites beyond Auschwitz-Birkenau offer white-space potential for operators willing to build interpretive infrastructure from baseline.
- Cross-border Polish-Ukrainian itineraries:Joint heritage trails linking Holocaust memorials with exclusion-zone programming create differentiated multi-day products unavailable to single-country competitors.
Industry Challenges
- Interpretive historian talent scarcity:Operators struggle to recruit guides capable of balancing educational rigor with emotional safety protocols at trauma-associated sites.
- Legacy booking system integration:Government heritage authorities often operate on paper-based or outdated digital platforms, forcing private operators to maintain parallel reservation infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Tourism Market |
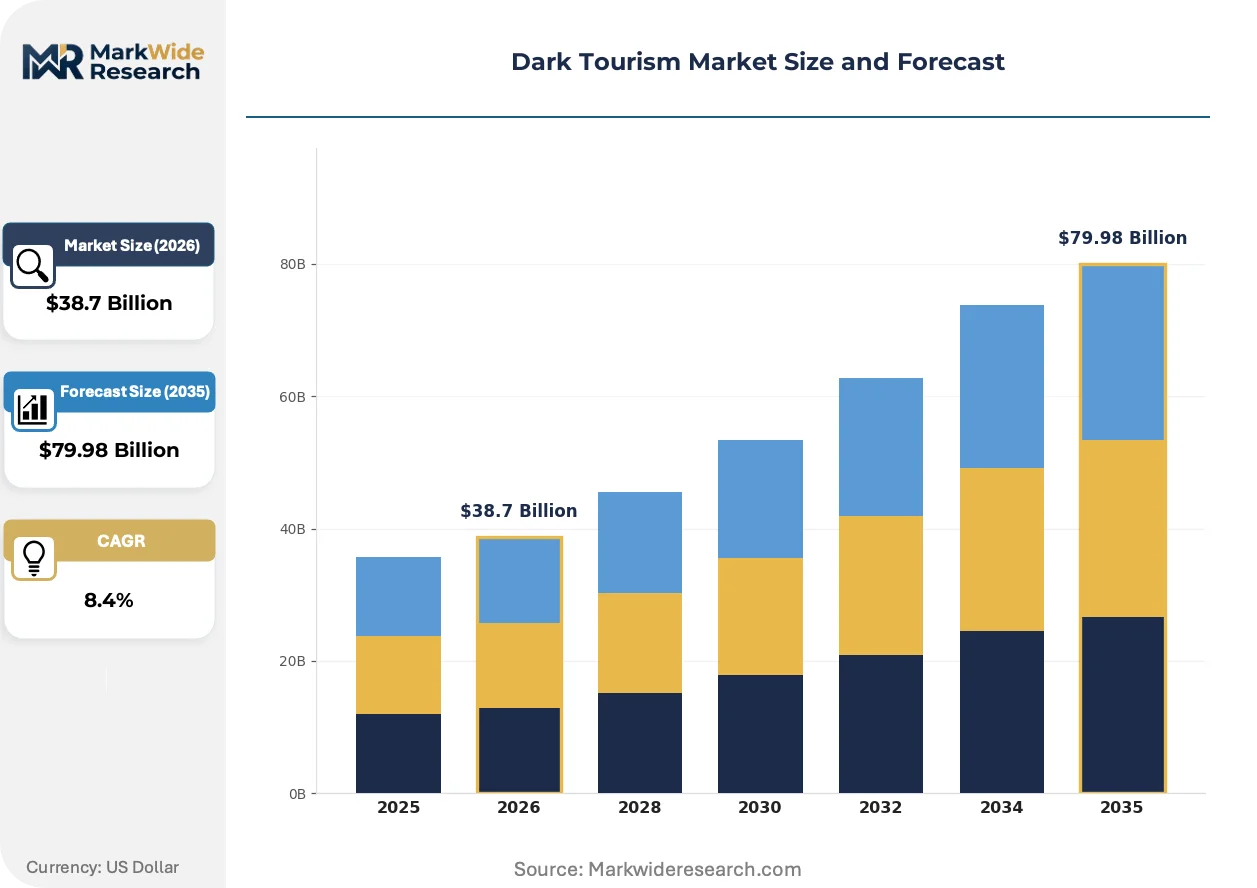
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Attraction Type: Battlefields, Museums, Historical Sites, Memorials Visitor Demographics: Age Groups, Educational Background, Income Levels, Travel Interests Experience Type: Tours, Virtual Reality, Guided Experiences, Self-Guided Purpose of Visit: Education, Reflection, Adventure, Cultural Exploration |
| Companies Covered | Expedia Group, Inc., Atlas Obscura, Viator, Inc., Chornobyl Tours, Auschwitz-Birkenau Memorial and Museum, GetYourGuide AG, TUI AG, Lupine Travel Company, Booking Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Tourism Market Strategic Shifts
Visitor expectation is pivoting from passive observation toward participatory historical reconstruction, compressing the acceptable lag between booking and immersive engagement.
Spatial audio and haptic feedback systems are rendering obsolete the traditional static exhibit format at memorial sites. Independent travelers under forty now expect multi-sensory narrative environments as baseline. This technology compression is collapsing the distinction between pre-visit education and on-site immersion, forcing operators to invest in continuous content refresh cycles.
GDPR enforcement through EU member-state data protection authorities is tightening visitor data retention policies across booking platforms. Operators must now implement automated deletion workflows and explicit consent architectures. Heritage sites with direct-to-visitor digital channels face the steepest compliance recalibration, particularly in Poland where Auschwitz-Birkenau's online reservation system processes cross-border EU traffic.
Direct platform bookings are displacing traditional travel agency intermediation for dark tourism products. Younger demographic segments now research and purchase exclusion-zone and memorial access through specialized digital-native curators rather than consolidated tour operators. This channel fragmentation is most pronounced in Ukrainian and Polish urban departure points where mobile-first penetration exceeds legacy travel infrastructure coverage.
Dark Tourism Market Segmentation
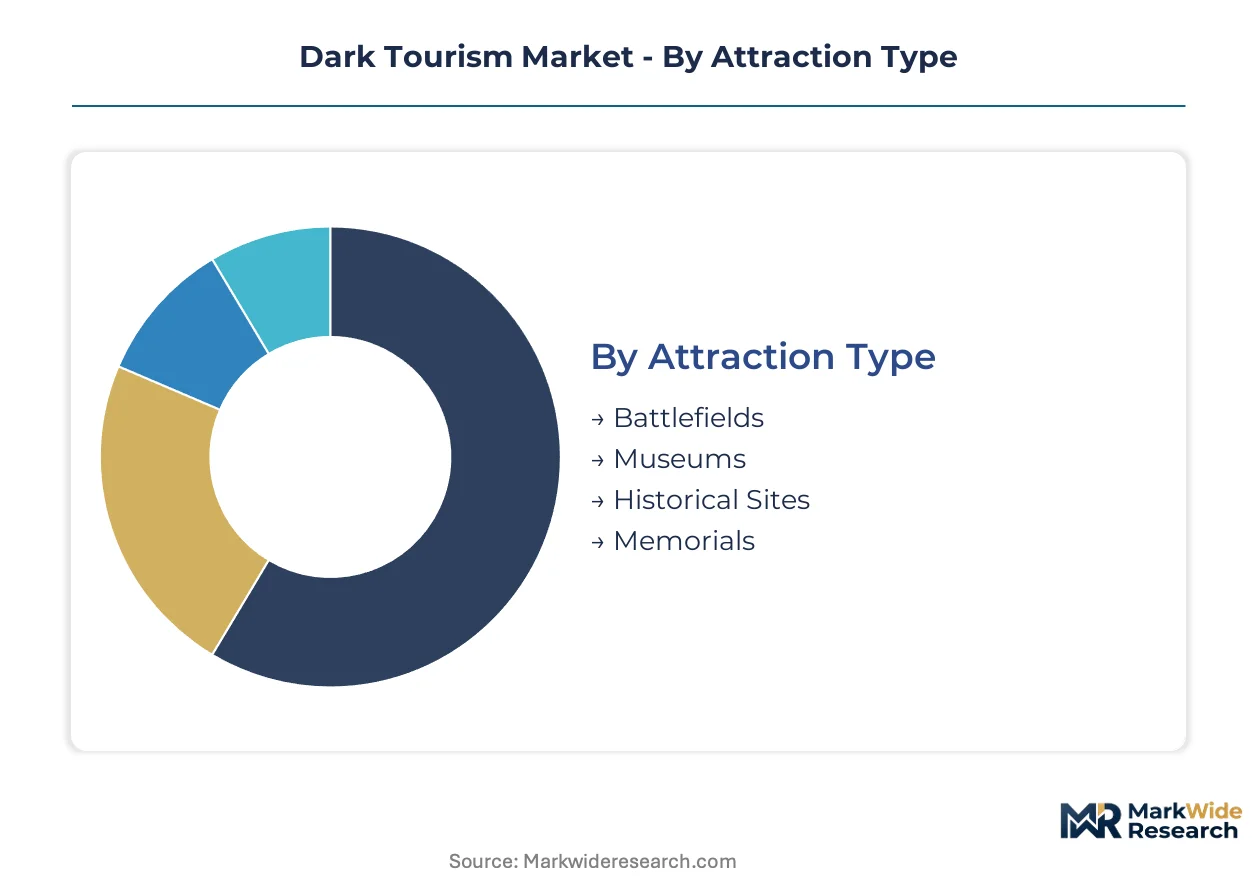
Dark tourism operators must align service intensity with segment-specific emotional and safety requirements. Each visitor category demands distinct interpretive frameworks, access protocols, and post-visit support structures that reshape revenue model design.
Attraction Type:
Service complexity scales with site hazard profiles and emotional intensity, driving divergent staffing and infrastructure investment patterns across attraction categories.
- Memorials:Auschwitz-Birkenau and comparable sites command extended dwell times and specialized guide training. Poland's Ministry of Culture and National Heritage mandates licensed interpretation protocols that elevate operational overhead. Visitor engagement concentrates in Central European heritage corridors where preservation authorities control access licensing.
- Historical Sites:Chornobyl exclusion-zone operations require radiological monitoring partnerships with Ukraine's State Agency of Tourism Development. Dosimetry equipment and contamination detection protocols create capital barriers that professionalize market entry.
- Museums:Curatorial frameworks balance educational mission with trauma-sensitive presentation. GDPR compliance shapes visitor data collection across Polish and Ukrainian institutional booking systems.
- Battlefields:Volume-driven economics with standardized group-tour throughput. Lower per-visitor yields demand scale-oriented distribution partnerships.
Memorials hold the largest share; momentum sits with historical sites as radiological safety certification professionalizes exclusion-zone access.
Visitor Demographics:
Demographic stratification determines booking channel preference and experience customization depth, with younger segments driving platform-native purchasing behaviors.
- Age Groups:Independent travelers under forty now dominate direct platform bookings for Ukrainian and Polish urban departure points. Mobile-first penetration exceeds legacy travel infrastructure coverage in these corridors.
- Travel Interests:Solo visitors seeking unscripted historical engagement outpace group-tour bookings, pulling investment toward modular self-directed architectures.
- Educational Background:Academic and professional historians demand primary-source access and archival components unavailable in standardized packages.
- Income Levels:Pricing stratification separates premium small-format immersion from economy group-tour access across Auschwitz-Birkenau and Chornobyl itineraries.
Age groups anchor current revenue; travel interests are climbing the fastest as unscripted engagement preferences reshape product design.
Experience Type:
Technology deployment intensity varies by format, with immersive systems compressing the traditional guided-tour value chain and restructuring operator economics.
- Virtual Reality:Spatial audio and haptic feedback systems render static exhibits obsolete. Pre-visit technologies open exclusion-zone experiences to mobility-limited demographics previously barred by physical access constraints.
- Guided Experiences:Personalized small-format historical immersion displaces standardized group packages. Atlas Obscura curates niche itineraries across unconventional sites through digital-native content platforms.
- Tours:TUI AG integrates dark tourism modules into broader European cultural packages, extending distribution reach through consolidated operator networks.
- Self-Guided:Modular platform architectures serve independent travelers with unscripted engagement preferences, particularly in Polish and Ukrainian urban markets.
Guided experiences retain the largest share; virtual reality gains share fastest as accessibility tools expand addressable demographics.
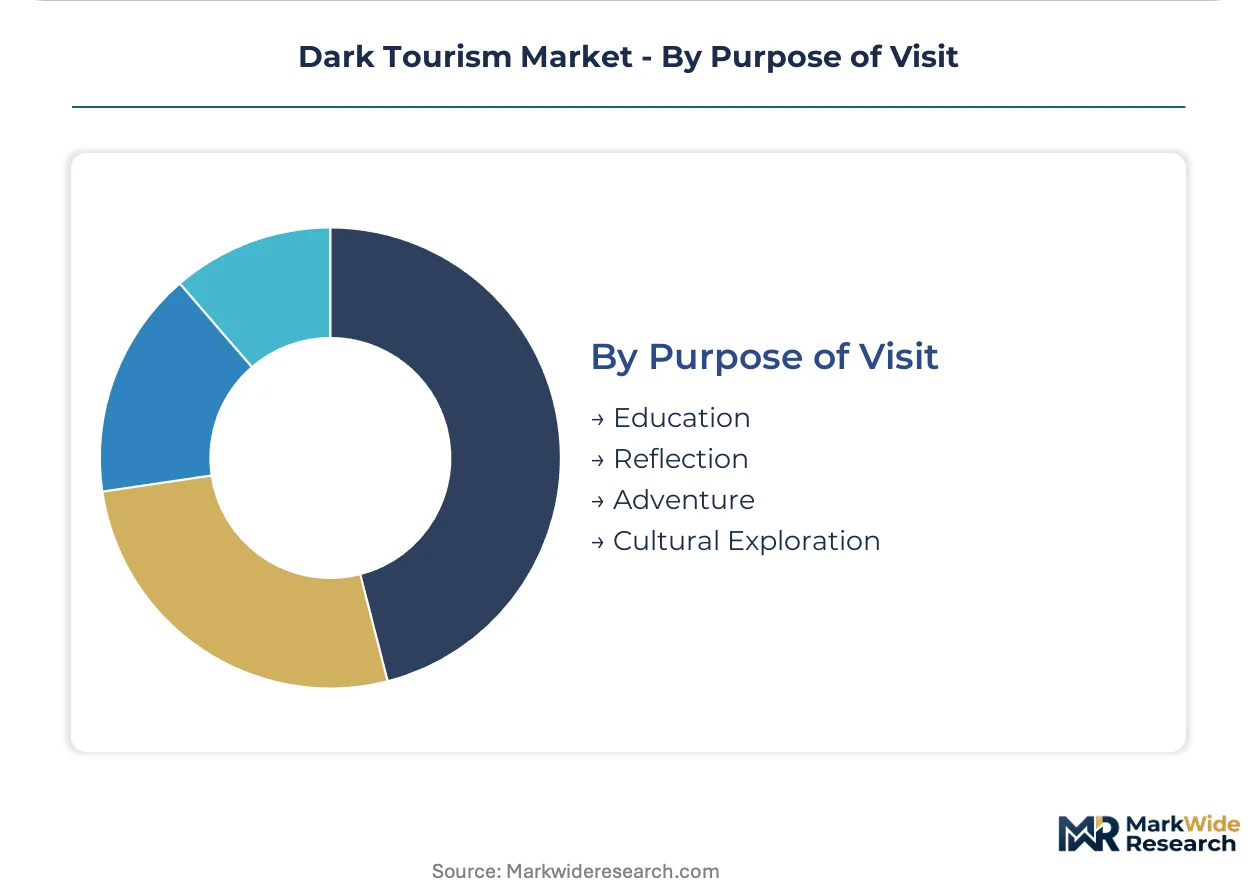
Purpose of Visit:
Visit motivation shapes content depth, emotional safety protocol intensity, and post-experience support requirements that differentiate operator service models.
- Education:Curriculum-aligned programming requires partnerships with academic institutions and credentialed historian recruitment. Interpretive talent scarcity constrains scalable delivery at trauma-associated sites.
- Reflection:Memorial sites with controlled pacing and psychological support resources serve visitors processing grief or historical trauma.
- Adventure:Exclusion-zone and hazard-adjacent experiences attract risk-tolerant segments demanding specialized safety briefings and equipment.
- Cultural Exploration:Broader heritage integration positions dark tourism within extended European cultural itineraries.
Education commands the largest share; reflection shows steepest expansion trajectory as emotional safety protocols professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across dark tourism corridors. Polish memorial sites command premium pricing with limited demand sensitivity, while Ukrainian exclusion-zone operators compete aggressively on entry fees to attract volume.
Poland
Auschwitz-Birkenau Memorial and Museum anchors Central European visitation with extended dwell times and specialized guide licensing. The Ministry of Culture and National Heritage mandates credentialed interpretation protocols that elevate operational overhead. Kraków serves as the primary departure hub, with secondary battlefield heritage corridors developing near Wrocław and Gdańsk.
Ukraine
Chornobyl exclusion-zone access concentrates independent traveler demand seeking radiologically certified immersion. The State Agency of Tourism Development enforces dosimetry equipment standards and licensed operator partnerships. Kyiv-based tour aggregators coordinate radiological safety briefings before zone transit.
Germany
Memorial site visitation concentrates in Berlin and Munich with strong educational group-tour throughput. Federal heritage preservation frameworks govern concentration camp site access and interpretive standards. The capital's documentation centers attract sustained academic and professional historian segments.
United States
Domestic dark tourism clusters around Civil War battlefields and September 11 memorial sites with volume-driven economics. National Park Service regulations standardize access protocols at federally managed historical sites. New York City and Gettysburg anchor the densest visitation infrastructure.
United Kingdom
Tower of London and Scottish battlefield sites serve heritage-education segments with established group-tour distribution. Historic England and Historic Environment Scotland coordinate preservation standards with commercial access licensing. Edinburgh and York develop interpretive infrastructure for trauma-associated historical narratives.
Dark Tourism Market Competitive Environment
Digital-native curators and consolidated travel conglomerates split the market between experiential depth and distribution reach. The competitive structure tilts toward platform-based intermediation rather than asset-heavy site ownership. Three archetypes dominate: specialized exclusion-zone operators with direct government licensing, digital content platforms curating niche itineraries, and integrated travel groups embedding dark modules within broader cultural packages. Dominant competitive moves include cross-border itinerary bundling and immersive technology partnerships that compress pre-visit education timelines.
Among platform-based intermediaries, GetYourGuide AG and Booking Holdings Inc. occupy positions emphasizing direct consumer booking channels over traditional agency networks. Within the specialized operator tier, Chornobyl Tours exemplifies the government-licensed exclusion-zone archetype through radiological safety partnerships and direct State Agency of Tourism Development authorization. These three anchors represent divergent strategic vectors: scale-driven aggregation, niche experiential curation, and hazard-adjacent site-specific professionalization.
| Leading Market Players |
|---|
| Expedia Group, Inc. |
| Atlas Obscura |
| Viator, Inc. |
| Chornobyl Tours |
| Auschwitz-Birkenau Memorial and Museum |
| GetYourGuide AG |
| TUI AG |
| Lupine Travel Company |
| Booking Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at licensed Chornobyl exclusion-zone operators drives premium pricing for radiologically certified tours while forcing marginal providers toward cost-cutting equipment substitutions. This utilization squeeze concentrates pricing power with Ukraine's State Agency of Tourism Development partners and elevates compliance costs for new market entrants.
Pricing Analysis
After-sales revenue from extended interpretation packages and archival access subscriptions drives lifetime value for specialized operators. Three-tier pricing structure across premium small-format immersion, standard group access, and economy virtual-reality alternatives dominates the market. Price differentiation centers on guide certification tier and radiological safety equipment grade. Cost compression in economy virtual-reality tiers is intensifying because platform-native curators commoditize pre-visit content. Academic and professional historian segments show least price sensitivity; independent travelers under forty exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on radiological monitoring equipment limit dosimetry hardware flows into Ukrainian exclusion-zone operations. Supply concentrates in Germany, Poland, and specialized Japanese manufacturers for contamination detection systems. Component dependencies include Geiger-Müller tubes, lithium fluoride thermoluminescent dosimeters, and GPS-integrated mapping units. Single-source vulnerability runs through German-certified dosimetry calibration services. Distribution runs through Kyiv-based tour aggregators coordinating directly with State Agency of Tourism Development licensed operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern dark tourism value capture as direct-to-visitor booking architectures displace traditional agency intermediation. Interoperability between memorial reservation systems and mobile-native curators is reshaping competitive moats.
For Market Incumbents: Insulate core Auschwitz-Birkenau and Chornobyl access licenses through deeper radiological safety partnerships and exclusive historian recruitment pipelines. Vertical integration into archival primary-source repositories counters digital-native curators commoditizing interpretive content. Channel control over direct platform bookings preserves margin structure against aggregator compression.
For New Entrants and Emerging Players: Build out underdeveloped Polish battlefield heritage corridors near Wrocław and Gdańsk where interpretive infrastructure remains baseline. Cross-border Polish-Ukrainian itinerary bundling offers white-space penetration unavailable to single-country incumbents. Go-to-market leverage rests on modular self-directed platform architectures serving independent traveler preferences in urban departure hubs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among government-licensed exclusion-zone operators with radiological safety certification moats. Long-term viability over the next decade favors platform-native curators with content refresh capabilities and heritage-site direct booking integrations. Acquisition targets should demonstrate GDPR-compliant data architectures and automated deletion workflows. The signal to watch is Poland's Ministry of Culture privatization debates affecting concession licensing structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Radiological Safety Certification Investment | Ukraine's State Agency mandates licensed exclusion-zone protocols that filter unqualified competitors. |
| Cross-Border Itinerary Bundling | Joint Polish-Ukrainian heritage trails create differentiated multi-day products unavailable to single-country operators. |
| Virtual Reality Accessibility Development | Immersive pre-visit technologies expand addressable demographics to mobility-limited visitors previously barred from exclusion zones. |
| Platform-Native Content Curation | Atlas Obscura's digital architecture demonstrates niche itinerary monetization beyond standardized group packages. |
| GDPR-Compliant Data Infrastructure | Automated deletion workflows satisfy EU Digital Services Act obligations for Polish and Ukrainian booking channels. |
Study Parameters
A standing panel of licensed exclusion-zone tour operators, memorial site interpretation directors, heritage preservation procurement managers, and mobile platform booking architects provided ongoing calibration throughout the study period. Primary interviews with Ukrainian State Agency of Tourism Development officials and Poland's Ministry of Culture licensing administrators combined with secondary validation against EU Digital Services Act regulatory filings, GDPR enforcement decisions by national data protection authorities, and heritage-site concession documentation. Bottom-up itinerary pricing analysis and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed low, baseline, and high visitation assumptions across attraction type, visitor demographic, experience format, and purpose of visit segmentation dimensions. CAGRs were derived from trend extrapolation moderated by regulatory capacity constraints and safety protocol evolution. Forecast inputs incorporated radiological monitoring equipment procurement cycles and memorial site preservation funding allocations.
Stress conditions across Chornobyl exclusion-zone access permit volatility, Auschwitz-Birkenau concession renewal timelines, and EU data protection enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about independent traveler platform adoption curves and immersive technology deployment rates. Material shifts in Poland's heritage-site privatization trajectory or Ukraine's radiological safety certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Sustainable Traveling Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
UK Outbound Travel Market