
 United Kingdom Casino Tourism Market | 2026-2036
United Kingdom Casino Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Casino Tourism Market Analytics
The UK Green Deal's hospitality decarbonization targets is shifting operator capital toward energy-efficient gaming floors and low-carbon hotel retrofits. The Rank Group leverages its provincial estate footprint to sustain regional visitor flows outside London. Genting Casinos UK anchors its competitive position through super-premium table gaming salons in Birmingham and Manchester. Flutter Entertainment differentiates via cross-platform loyalty integration between its digital and physical casino touchpoints.
Casino tourism denotes travel undertaken primarily to participate in licensed gambling activities within integrated hospitality environments, typically encompassing table games with house edges between 0.5% and 25%, electronic gaming machines with programmed return-to-player ratios, and adjacent entertainment services designed to extend visitor dwell time. Luxury Hotels command the deepest margin pools as bundled room-and-gaming packages lift per-visitor spend above standalone gambling visitation. Slot Machines dominate floor space allocation and revenue yield across most UK properties, while Sports Betting represents the fastest-growing gaming type through in-play digital integration within physical venues. High-Rollers sustain disproportionate profitability despite representing a narrow customer base, whereas Casual Gamblers drive volume throughput during off-peak periods.
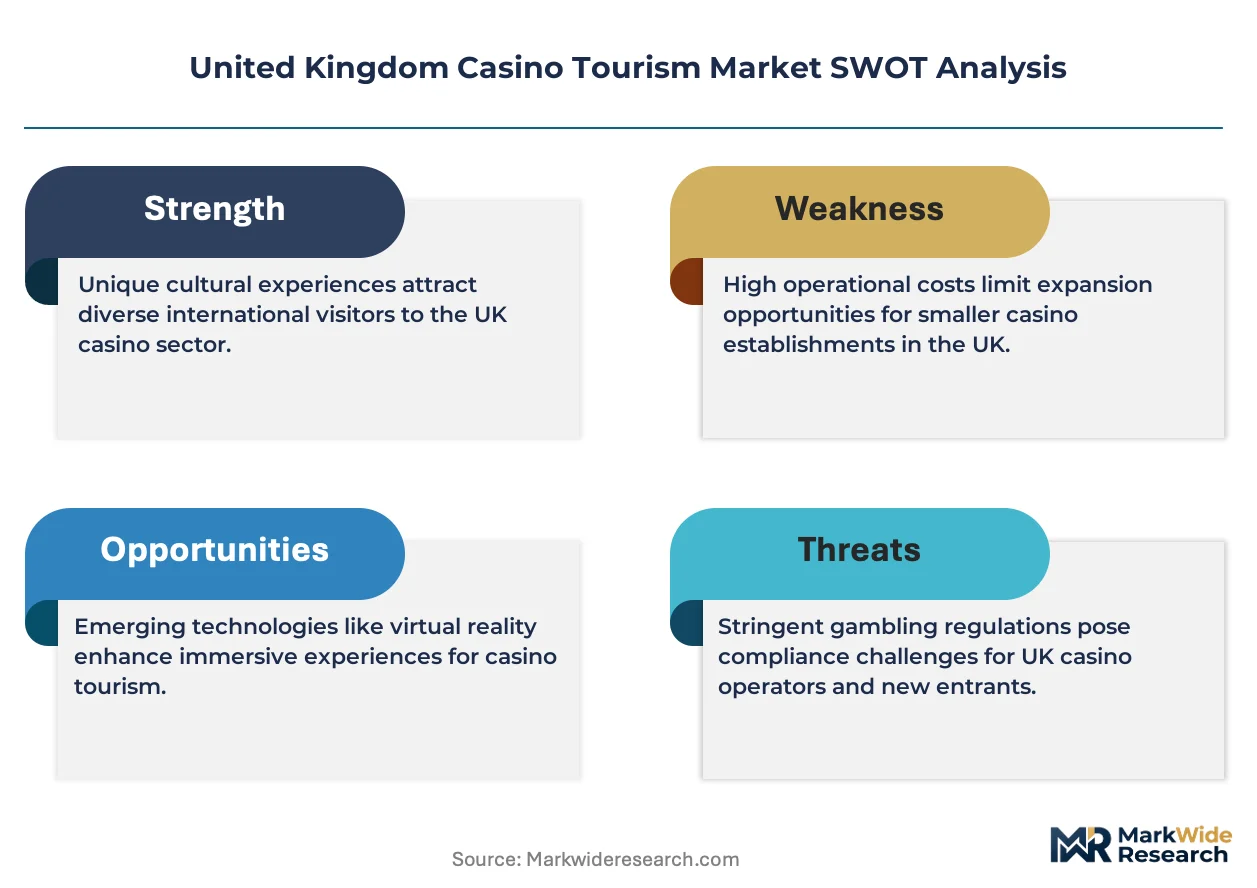
The UK Gambling Commission enforces licensing conditions that mandate responsible gambling infrastructure, directly shaping floor design and staff training investments across all operators. HM Revenue & Customs oversees point-of-consumption tax collection that influences pricing architecture for both domestic and inbound visitors. Local authority planning departments in Westminster, Birmingham, and Glasgow control premises permissions, creating fragmented market access conditions. Stakeholders must monitor pending affordability check regulations that threaten to alter customer onboarding economics and VIP program structures.
Market Dynamics
The UK Gambling Commission's affordability check mandate is forcing operators to restructure customer onboarding workflows and VIP relationship management. This regulatory pressure concentrates capital expenditure on compliance infrastructure rather than gaming floor expansion.
Growth Catalysts
- Cross-platform loyalty integration:Digital-physical wallet convergence enables seamless player fund transfers between online accounts and casino floor chips. Birmingham and Manchester integrated resorts leverage this to extend visitor session duration.
- HM Revenue & Customs point-of-consumption framework:Standardized tax collection across remote and land-based channels reduces pricing arbitrage between domestic and inbound visitors. Westminster operators benefit from simplified duty reconciliation.
- Super-premium table gaming salons:Dedicated high-roller environments with bespoke hospitality services attract international whale traffic. Glasgow's emerging casino cluster experiments with this format to differentiate from London saturation.
Market Restraints
- Local authority planning fragmentation:Westminster, Birmingham, and Glasgow maintain divergent premises permission standards. Operator expansion timelines stretch unpredictably across municipal boundaries.
- Energy retrofit capex burden:The UK Green Deal's hospitality decarbonization targets mandate low-carbon hotel retrofits. Legacy properties face stranded asset risk without efficiency upgrades.
- Slot machine floor space economics:Programmed return-to-player ratios compress margin per square meter against rising real estate costs. Regional estates outside London struggle to justify footprint maintenance.
Strategic Opportunities
- Provincial estate revitalization:Rank Group's regional footprint demonstrates sustained visitor flows outside London saturation. Secondary cities offer untapped high-roller package potential with lower competitive density.
- In-play sports betting integration:Digital wagering interfaces within physical venues merge two gaming types. Flutter Entertainment's cross-platform architecture provides template for floor-based deployment.
- Responsible gambling infrastructure monetization:UK Gambling Commission-mandated staff training and self-exclusion systems create compliance-as-service export potential. Scottish and Welsh regulatory alignment expands addressable market for trained personnel.
Industry Challenges
- Affordability check implementation complexity:Pending financial verification requirements demand real-time income assessment capabilities. VIP program structures require fundamental redesign to maintain profitability under stricter onboarding.
- Anti-money laundering protocol staffing:Enhanced UK Gambling Commission surveillance obligations expand specialist compliance headcount requirements. Talent scarcity in forensic accounting and suspicious activity reporting drives wage inflation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Casino Tourism Market |
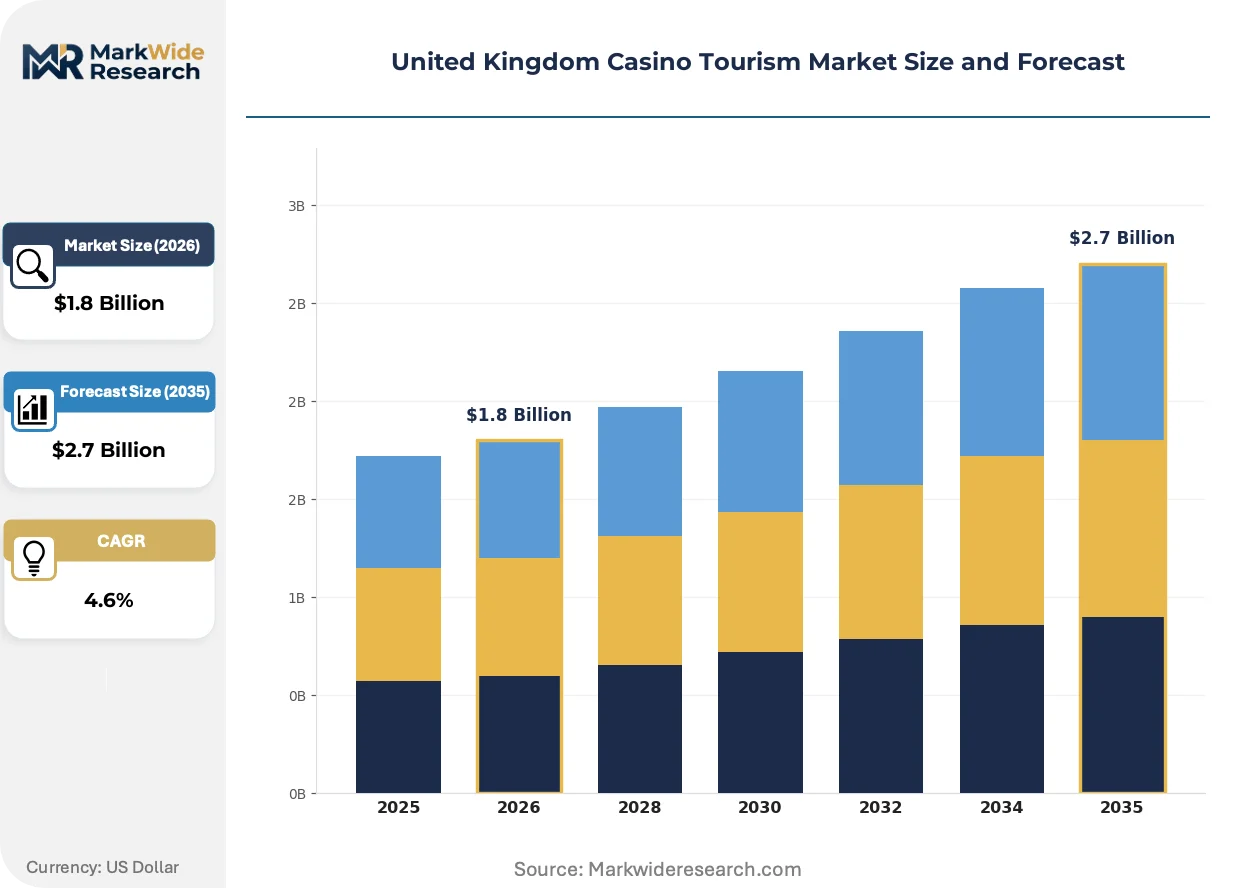
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Luxury Hotels, Entertainment Venues, Cultural Experiences, Guided Tours Customer Type: High-Rollers, Casual Gamblers, Tourists, Local Visitors Gaming Type: Slot Machines, Table Games, Sports Betting, Poker Rooms Package Offerings: All-Inclusive Deals, Weekend Getaways, Group Packages, Loyalty Programs |
| Companies Covered | The Rank Group, Aspers Group, Genting Casinos UK, Caesars Entertainment EMEA, Metropolitan Gaming, Flutter Entertainment, Entain, Evoke, Bet365, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Casino Tourism Market Evolving Landscape
Digital-physical convergence is dismantling traditional boundaries between remote gambling and on-premise visitation. Operators now architect unified player journeys across touchpoints rather than treating channels as separate profit centers.
RFID-enabled chip tracking is modularizing casino floor analytics. Genting Casinos UK deploys sensor-embedded gaming tokens to capture real-time betting velocity and player migration patterns. This granularity compresses decision cycles for table configuration and staff deployment. House edge optimization now operates on hourly rather than monthly feedback loops.
The UK Gambling Commission's strengthened anti-money laundering protocols are reshaping surveillance infrastructure investment. Operators must deploy enhanced due diligence systems capable of real-time transaction monitoring. High-roller salons in Birmingham and Manchester face disproportionate compliance cost escalation relative to mass-market floors. Westminster properties absorb these burdens through consolidated back-office functions serving multiple venues.
High-roller travel packages are displacing standalone gambling visitation as the dominant revenue architecture. Luxury hospitality chains bundle dedicated casino floor access with accommodation and entertainment credits. Scotland's emerging integrated resort pipeline targets this segment to bypass London's competitive saturation. Procurement of these packages increasingly flows through concierge networks rather than direct operator marketing.
United Kingdom Casino Tourism Market Segmentation
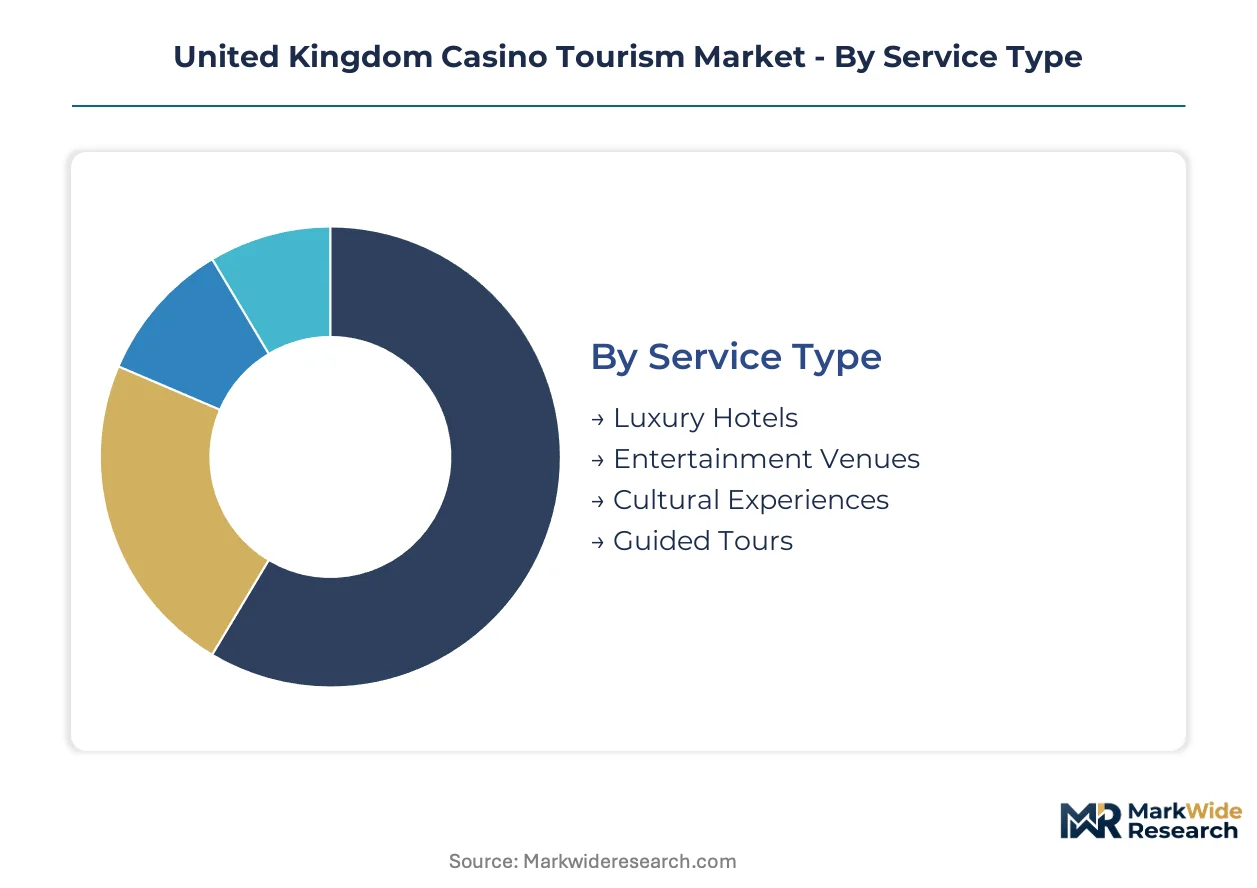
Casino tourism segmentation in the United Kingdom reveals how operator investment flows toward bundled hospitality experiences rather than standalone gambling provision. Understanding these divisions exposes where margin pools concentrate and which visitor archetypes sustain profitability across London's West End cluster and emerging provincial estates.
Service Type:
Technology and specification differentiation separates properties competing for extended dwell time versus transactional visitation.
- Luxury Hotels:Integrated resort concepts combine accommodation, gaming floors, and entertainment venues under single ownership. Westminster operators leverage these assets to capture high-roller spend through bundled room-and-gaming packages that lift per-visitor yield above standalone casino entry.
- Entertainment Venues:Adjacent theatres, restaurants, and nightlife spaces extend session duration through programmed event calendars. Birmingham and Manchester integrated resorts anchor visitor spend through live performance programming that reduces pure gambling dependency.
- Cultural Experiences:Heritage site proximity and curated local tours differentiate regional estates from London saturation. Rank Group's provincial footprint incorporates these elements to sustain visitor flows outside the capital.
- Guided Tours:Structured itineraries package multiple gaming venues with transportation logistics. Scotland's emerging casino cluster experiments with this format to aggregate dispersed regional supply.
Mature deployment sits with Luxury Hotels. Newer deployment is concentrated in Cultural Experiences.
Customer Type:
Cost tier stratification determines how operators architect floor space, staffing ratios, and compliance infrastructure investments.
- High-Rollers:Disproportionate profitability concentration despite narrow customer base. Super-premium salons in Birmingham and Manchester attract international whale traffic through bespoke hospitality services and dedicated floor access.
- Casual Gamblers:Volume throughput drivers during off-peak periods with compressed margin per visit. Regional estates outside London depend on this segment to justify fixed cost coverage across extended operating hours.
- Tourists:Inbound visitation seeking integrated entertainment rather than pure gambling motivation. Westminster properties capture this flow through concierge network procurement of bundled packages.
- Local Visitors:Repeat patronage sustaining baseline revenue during low-season tourism troughs. Glasgow's emerging cluster targets this segment to build predictable demand before scaling high-roller infrastructure.
Profit contribution concentrates with High-Rollers. Volume expansion is climbing fastest among Tourists.
Gaming Type:
Application-specific technology requirements shape capital allocation between electronic systems and human-dealer infrastructure.
- Slot Machines:Programmed return-to-player ratios dominate floor space allocation across most UK properties. Westminster operators deploy RFID-enabled chip tracking to optimize real-time betting velocity and player migration patterns.
- Table Games:House edge mechanics between 0.5% and 25% require skilled dealer labor and surveillance overhead. Super-premium salons concentrate this offering for high-roller segments in Birmingham and Manchester.
- Sports Betting:Digital wagering interfaces merge remote and on-premise participation through in-play integration. Flutter Entertainment's cross-platform architecture provides template for floor-based deployment.
- Poker Rooms:Rake-based revenue models with lower house edge dependence on tournament frequency and player liquidity. Regional estates struggle to sustain critical mass outside London's deeper talent pools.
Floor space dominance sits with Slot Machines. Technology convergence is expanding most quickly in Sports Betting.
Package Offerings:
Customer acquisition economics vary sharply between direct operator marketing and intermediary channel distribution.
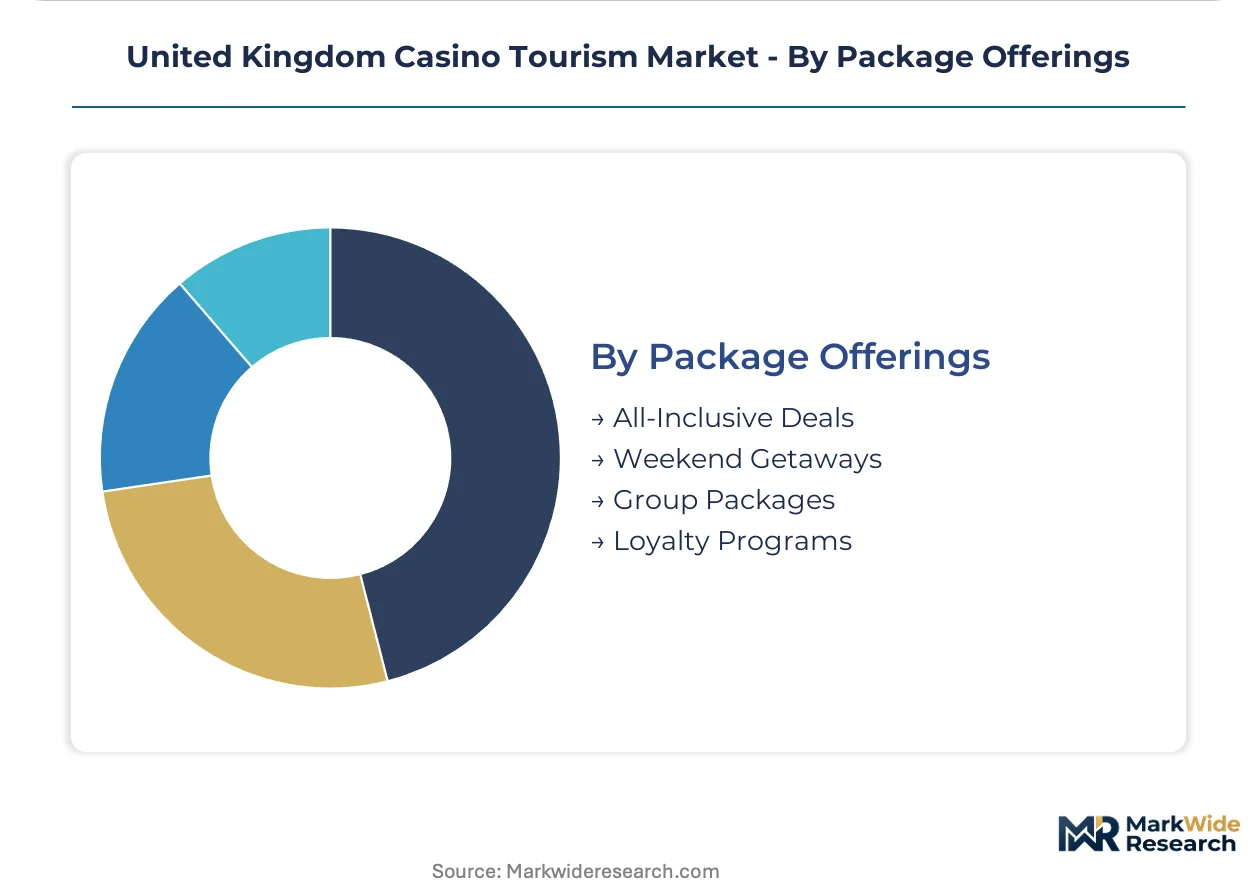
- All-Inclusive Deals:Bundled accommodation, gaming credits, and entertainment access displace standalone gambling visitation. Scotland's integrated resort pipeline targets this format to bypass London competitive saturation.
- Weekend Getaways:Short-duration packages optimize regional estate utilization during peak leisure travel windows. Rank Group's provincial footprint leverages these offerings to sustain occupancy outside business travel corridors.
- Group Packages:Aggregated demand through corporate event planners and tour operators reduces customer acquisition cost. Glasgow properties experiment with this channel to build baseline volume.
- Loyalty Programs:Cross-platform wallet integration enables seamless fund transfers between digital accounts and casino floor chips. Genting Casinos UK deploys this architecture to extend visitor session duration.
Revenue concentration sits with All-Inclusive Deals. Digital integration is gaining share fastest in Loyalty Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's West End cluster anchors United Kingdom casino tourism demand through integrated resort concentration along Leicester Square and Piccadilly. The capital's hospitality infrastructure captures disproportionate high-roller spend via bundled gaming and accommodation packages. Regional estates outside London face divergent regulatory and competitive conditions across England, Scotland, and Wales.
London and the Southeast
Westminster properties command premium positioning through super-premium table gaming salons and concierge-network package distribution. The UK Gambling Commission's licensing conditions mandate responsible gambling infrastructure investments that reshape floor design and staff training. Westminster's consolidated back-office functions serve multiple venues, absorbing compliance cost burdens more efficiently than dispersed regional estates.
Midlands
Birmingham integrated resorts attract international whale traffic through bespoke hospitality services and dedicated high-roller environments. HM Revenue and Customs point-of-consumption tax collection standardizes pricing architecture for domestic and inbound visitors. Birmingham's emerging casino cluster experiments with RFID-enabled chip tracking and real-time betting velocity analytics to compress decision cycles for table configuration.
North England
Manchester properties leverage cross-platform loyalty integration to extend visitor session duration through seamless digital-physical wallet convergence. Local authority planning departments control premises permissions, creating fragmented market access conditions that stretch operator expansion timelines unpredictably. Manchester's super-premium salons differentiate from London saturation through lower competitive density and emerging integrated resort concepts.
Scotland
Glasgow's emerging casino cluster targets local visitor segments to build predictable demand before scaling high-roller infrastructure. The UK Green Deal's hospitality decarbonization targets mandate low-carbon hotel retrofits that threaten stranded asset risk for legacy properties without efficiency upgrades. Scotland's integrated resort pipeline experiments with all-inclusive bundled packages to bypass London competitive saturation through concierge network procurement.
Wales
Cardiff and regional Welsh properties depend on casual gambler volume throughput during off-peak periods to justify fixed cost coverage across extended operating hours. Welsh regulatory alignment with UK Gambling Commission standards expands addressable market for trained compliance personnel. Rank Group's provincial estate footprint incorporates cultural experience proximity to sustain visitor flows outside capital concentration.
United Kingdom Casino Tourism Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance infrastructure and high-roller salon differentiation. The vendor base concentrates around integrated resort operators with hospitality chain backing and standalone regional estate specialists with localized footprint density. Three archetypes dominate: luxury hospitality-integrated conglomerates deploying cross-platform loyalty systems, provincial estate specialists sustaining regional visitor flows, and digital-physical convergence platforms merging remote and on-premise participation. Dominant competitive moves include portfolio diversification into bundled travel packages and geographic expansion through municipal planning permission acquisition.
Within the integrated resort tier, Genting Casinos UK and Caesars Entertainment EMEA exemplify luxury hospitality-backed positioning through super-premium salon deployment and consolidated back-office compliance functions. Flutter Entertainment occupies the digital-physical convergence archetype, anchoring cross-platform architecture that enables seamless fund transfers between online accounts and casino floor chips. The Rank Group represents the provincial estate specialist model, sustaining regional visitor flows outside London saturation through cultural experience bundling and weekend getaway package optimization.
| Leading Market Players |
|---|
| The Rank Group |
| Aspers Group |
| Genting Casinos UK |
| Caesars Entertainment EMEA |
| Metropolitan Gaming |
| Flutter Entertainment |
| Entain |
| Evoke |
| Bet365 |
| Others |
Value Network & Pricing Analysis
Specialist compliance talent concentration in London and the Southeast widens pricing-tier spreads between Westminster's consolidated back-office operators and dispersed regional estates. Labor-cost differentials for forensic accounting and suspicious activity reporting expertise compress margins outside the capital while enabling premium service bundling within it.
Pricing Analysis
Value-based pricing anchored to per-visitor yield and session duration dominates bundled hospitality packages. Three-tier pricing structure across premium, standard, and economy levels separates super-premium salon access from mass-market floor entry and casual gambler throughput tiers. Cost compression in regional slot machine economics intensifies because programmed return-to-player ratios face rising real estate costs. Casual gamblers exhibit highest price sensitivity to entry fees and minimum bets, while high-rollers demonstrate lowest sensitivity to bundled package premiums.
Supply Chain Analysis
Direct-to-operator procurement channels handle specialized gaming equipment and surveillance technology deployment for integrated resorts. Manufacturing concentration rests in Germany, Japan, and the United States for precision table gaming apparatus and RFID-enabled chip systems. Raw material dependencies include semiconductor components for electronic gaming machines, specialized alloys for gaming tokens, and optical-grade glass for surveillance infrastructure. Single-source vulnerability in compliance software licensing creates supply chain risk for real-time transaction monitoring systems. Distribution runs through authorized equipment distributors and direct manufacturer relationships serving Westminster, Birmingham, and Manchester operator clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as affordability check mandates force capital-constrained regional operators toward exit or acquisition. Compliance infrastructure investments disproportionately burden smaller estates lacking consolidated back-office scale.
For Market Incumbents: Lock in high-roller relationship economics through super-premium salon exclusivity and cross-platform loyalty integration before affordability verification disrupts VIP onboarding workflows. Acquire distressed regional estates in Birmingham and Manchester to consolidate compliance functions and capture secondary city high-roller demand. The UK Gambling Commission's pending financial verification requirements threaten standalone operator viability.
For New Entrants and Emerging Players: The price-point gap between London premium packages and regional economy-tier visitation offers white-space entry. Scotland's emerging Glasgow cluster presents the most penetrable geography given lower competitive density and nascent integrated resort pipeline. Deploy cultural experience bundling as go-to-market angle to differentiate from pure gambling positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with provincial estate specialists given regulatory alignment forcing consolidation toward scaled compliance infrastructure. Long-term viability favors operators with hospitality chain backing and consolidated back-office functions serving multiple venues. Monitor UK Gambling Commission affordability check implementation timelines as inflection indicator for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform Loyalty Integration | Flutter Entertainment's architecture enables seamless digital-physical fund transfers extending session duration. |
| Super-Premium Salon Expansion | Genting Casinos UK deploys bespoke hospitality services attracting international whale traffic to Birmingham and Manchester. |
| Provincial Estate Revitalization | Rank Group sustains regional visitor flows outside London saturation through cultural experience bundling. |
| Compliance Infrastructure Consolidation | Westminster operators absorb UK Gambling Commission burdens through shared back-office functions serving multiple venues. |
| RFID-Enabled Floor Analytics | Real-time betting velocity tracking compresses decision cycles for table configuration and staff deployment. |
Research Methodology
Independent corroboration across UK Gambling Commission licensing records, HM Revenue and Customs tax collection disclosures, and local authority planning databases underwrites the qualitative findings. Primary interviews with casino operations directors, compliance officers, hospitality procurement managers, and gaming floor supervisors combined with secondary validation from UKGC enforcement reports and operator regulatory filings. Bottom-up venue-level capacity modeling and top-down national tourism expenditure triangulation anchored market sizing.
Comparable-period anchoring to pre-pandemic visitation baselines and post-regulatory-shift operational data established forecast reference points across the analysis window. Segmentation modeling incorporated service type, customer tier, gaming format, and package structure dimensions with regional regulatory cluster variations. CAGRs derived from visitor volume projections, per-capita spend trajectories, and compliance cost escalation curves informed the projection horizon. Industry-specific inputs included high-roller package penetration rates and slot machine floor space yield metrics.
Inputs from UK Gambling Commission enforcement databases and operator licensing applications were available through the study window; gaps in real-time affordability check implementation timelines introduce uncertainty bands around VIP program restructuring forecasts. Forecasts reflect assumptions regarding regulatory implementation pace and high-roller travel package demand elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
North America Pet Travel Services Market