
 Living and Dining Room Furniture Market | 2026-2036
Living and Dining Room Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Living and Dining Room Furniture Market Foresight
Vietnamese wood processing clusters are restructuring their export-oriented finishing capacity to serve North American and European contract buyers. IKEA leverages its captive flat-pack logistics network to sustain margin compression in mass-market sofas and dining sets. Ashley Furniture Industries anchors its position through vertical control over domestic upholstery cut-and-sew operations. RH differentiates via gallery-based experiential retail that commands premium positioning in solid wood dining tables and leather seating.
Living and dining room furniture encompasses freestanding and fixed-installation pieces designed for residential social, meal, and leisure functions, typically constructed from solid timber, engineered wood substrates, metal framing, or upholstered composites with finishing processes including veneering, lacquering, and textile application. Sofas and upholstered chairs concentrate the highest absolute revenue pools due to material intensity and replacement cycles, while modular and space-saving functionality segments are expanding fastest in urban density corridors where square footage constraints dictate flexible configurations. Wood materials still dominate value capture in premium tiers, though metal and glass combinations are gaining share in contemporary and modern style segments targeting younger demographic cohorts.
EPA formaldehyde emission standards under the Toxic Substances Control Act and California Air Resources Board Phase 2 certifications govern composite wood product eligibility for US residential sales, directly shaping supplier qualification and material substitution decisions. EU REACH chemical restrictions and the Ecodesign for Sustainable Products Regulation are extending compliance obligations to cover full material disclosure and recyclability thresholds for furniture placed on European markets. Stakeholders must monitor how diverging transatlantic chemical and circularity frameworks will fragment sourcing strategies and test the adaptability of existing Asian manufacturing footprints.
Market Dynamics
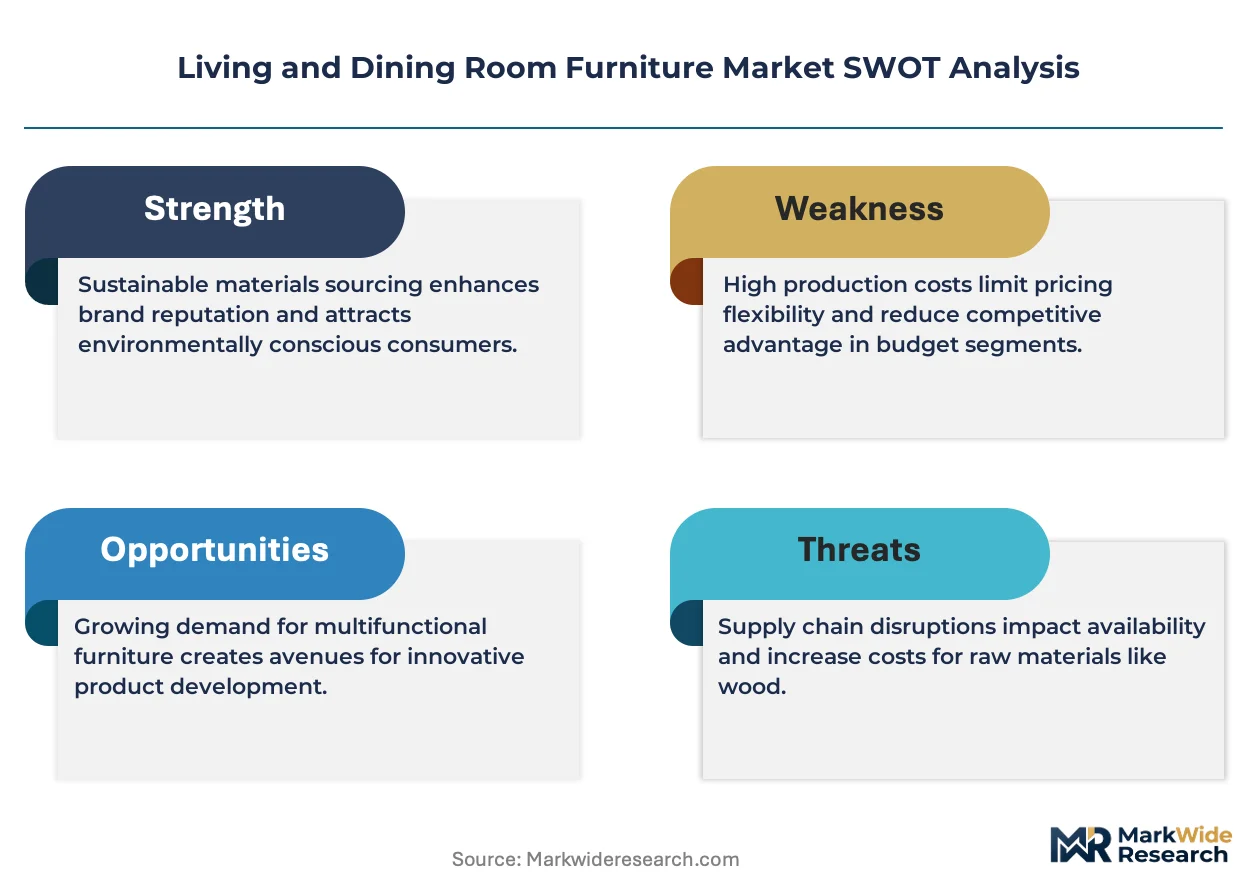
California's CARB Phase 2 formaldehyde emissions standards are forcing engineered wood substrate substitutions across North American supply chains, while Vietnamese processing clusters restructure finishing capacity to retain contract buyer relationships. This regulatory-material tension defines current competitive positioning.
Growth Catalysts
- Suburban furnished unit expansion:Residential real estate developers in the United States are bundling complete living and dining packages into new construction, creating pull-through demand for coordinated furniture suites.
- REACH chemical disclosure mandates:EU Ecodesign for Sustainable Products Regulation requirements for full material traceability are accelerating supplier consolidation toward certified manufacturers with established documentation systems.
- Compact urban housing stock:China's tier-one city apartment density is concentrating demand for modular configurations that reconfigure between social and meal functions within constrained square footage.
Market Restraints
- Formaldehyde compliance costs:EPA Toxic Substances Control Act testing and certification expenses for composite wood products compress margins for small-scale manufacturers without captive laboratory resources.
- Container freight volatility:Transpacific shipping rate fluctuations from Vietnamese and Malaysian export hubs create working capital strain for contract furniture buyers with fixed-price agreements.
- Solid timber scarcity:Premium grade hardwood availability constraints in North American and European sourcing regions limit production scale-up for solid wood dining table segments.
Strategic Opportunities
- Gallery-based experiential retail:Flagship showroom formats in major metropolitan areas enable premium positioning through tactile material demonstration and interior design consultation services.
- Flat-pack logistics optimization:Investment in automated packaging lines and last-mile delivery partnerships opens direct-to-consumer channels bypassing traditional furniture retail markups.
- Low-emission substrate innovation:Soy-based and bio-adhesive alternatives to urea-formaldehyde resins offer differentiation for manufacturers targeting LEED-certified residential construction projects.
Industry Challenges
- Upholstery craft labor shortages:Cut-and-sew operations in the United States face recruitment gaps for skilled sewing machine operators, constraining domestic production expansion.
- Multi-jurisdiction certification complexity:Simultaneous compliance with California Air Resources Board, EPA, and EU REACH frameworks extends product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Living and Dining Room Furniture Market |
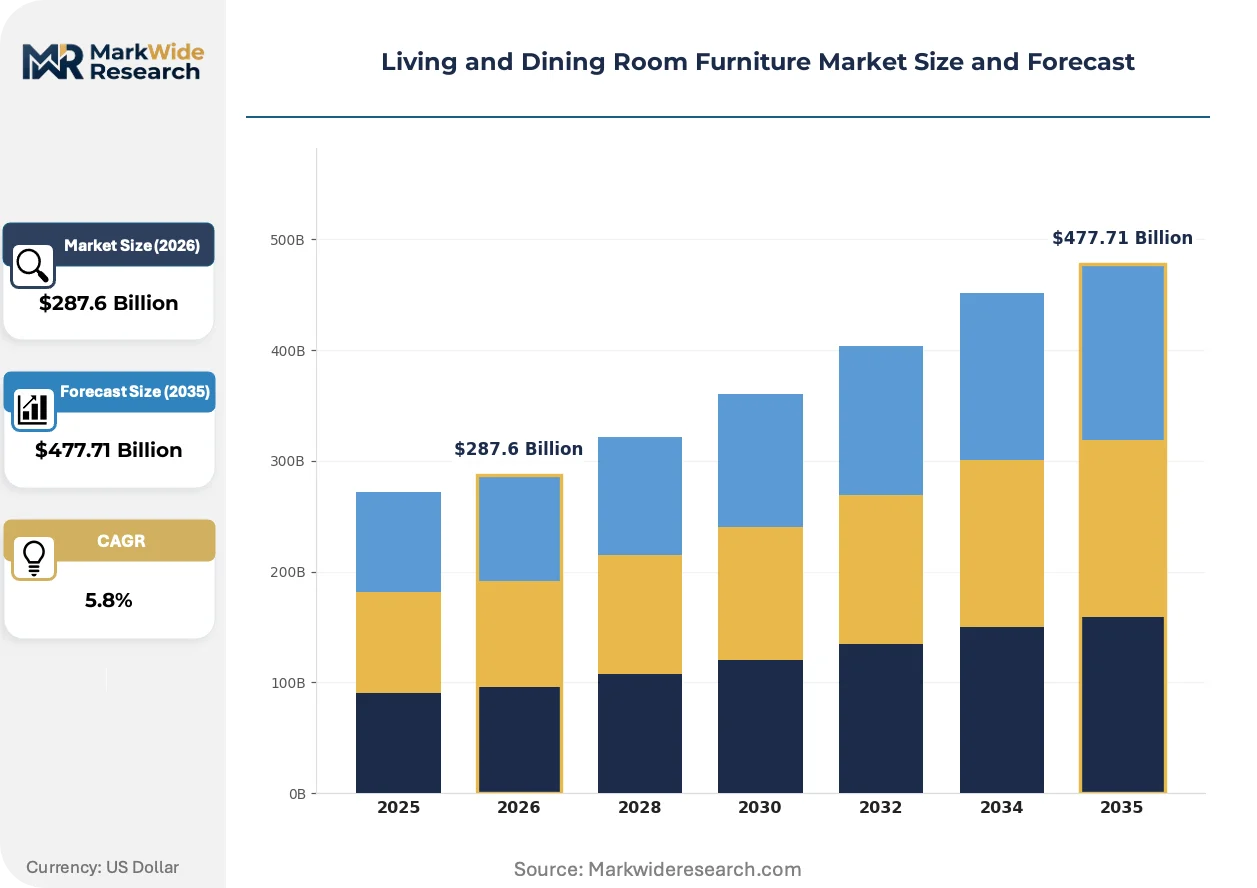
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $477.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Dining Tables, Coffee Tables, Chairs Material: Wood, Metal, Upholstered, Glass Style: Modern, Traditional, Rustic, Contemporary Functionality: Multi-functional, Space-saving, Customizable, Modular |
| Companies Covered | IKEA, Ashley Furniture Industries, La-Z-Boy Inc., Williams-Sonoma, Inc, RH, Natuzzi S.p.A., Flexform S.p.A., Kimball International, Global Furniture USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Living and Dining Room Furniture Market Shifts & Advancements
Digital visualization tools and automated manufacturing systems are compressing traditional furniture design-to-delivery cycles, while regulatory chemical restrictions reshape material specifications across premium and mass-market tiers.
Advanced CNC routing and robotic sanding systems are integrating into solid wood dining table production lines, enabling complex joinery and surface finishing at throughput rates previously achievable only in engineered wood manufacturing. North American mid-market manufacturers are adopting these capital-intensive systems to defend domestic production against lower-cost import competition. The technology is integrating quality consistency and customization flexibility that were historically traded off against each other.
EU Ecodesign for Sustainable Products Regulation digital product passport requirements are mandating granular material disclosure and end-of-life recyclability documentation for furniture placed on European markets. This regulatory framework is disqualifying suppliers with opaque Asian manufacturing footprints and favoring vertically integrated producers with controlled chain-of-custody systems. Upholstered seating categories face particular compliance burden due to textile foam and adhesive complexity.
Direct-to-consumer channel expansion is displacing traditional furniture retail intermediaries, with buyers expecting augmented reality visualization and white-glove assembly services previously bundled through brick-and-mortar showrooms. Younger demographic cohorts in United States coastal metropolitan areas demonstrate highest adoption of this purchasing pattern. The shift concentrates logistics investment requirements on manufacturers while compressing traditional retail margin pools.
Living and Dining Room Furniture Market Segmentation
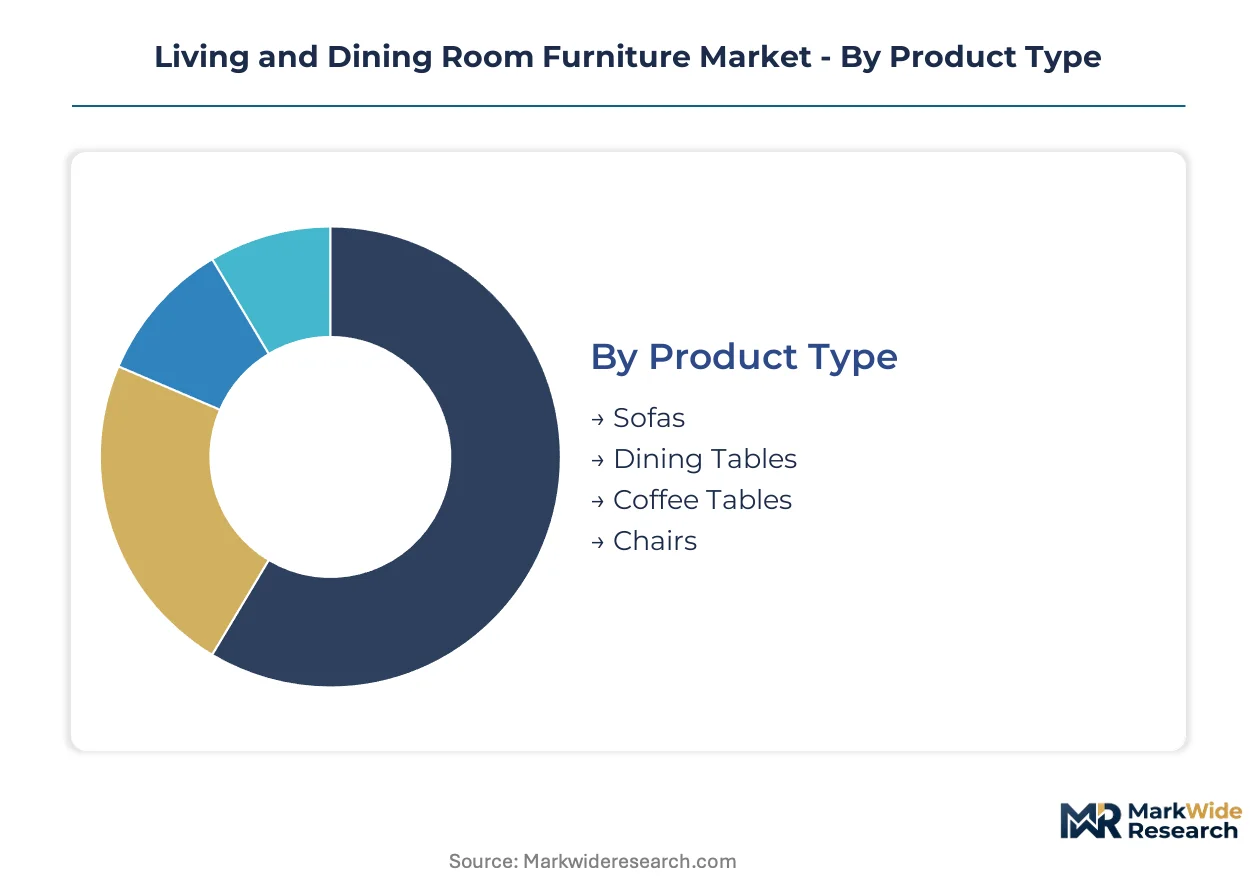
Furniture purchasing decisions cascade through multiple filtering criteria, from room-specific functional needs to material durability expectations and aesthetic alignment with residential architecture. Understanding how these dimensions intersect reveals where manufacturers must concentrate design investment and where distribution channels face the greatest fragmentation pressure.
Product Type:
Capital requirements vary sharply across furniture categories, with upholstered pieces demanding specialized sewing infrastructure and foam processing equipment that fixed-frame products avoid.
- Sofas:Multi-component assemblies combining hardwood frames, steel spring systems, high-density foam cushioning, and textile or leather upholstery. Demand clusters in suburban North American new construction where developers specify coordinated living room suites for furnished rental inventory. Labor intensity in cut-and-sew operations constrains domestic scaling.
- Dining Tables:Surface and support structures ranging from solid timber slabs to engineered wood substrates with veneer finishes, often incorporating metal or glass accent elements. China's tier-one cities concentrate demand for extendable and drop-leaf configurations that adapt to compact urban dining spaces. CARB Phase 2 compliance costs disproportionately impact this category due to substrate surface area exposure.
- Coffee Tables:Low-profile accent pieces typically combining wood, metal, or glass materials in rectangular, round, or organic shapes.
- Chairs:Seating units spanning dining, accent, and lounge applications with frame construction in wood, metal, or upholstered composites.
Most installed capacity flows through Sofas. Expansion is steepest in Dining Tables.
Material:
Cost tier stratification follows raw material scarcity and processing complexity, with premium positioning commanding substantial markups over mass-market alternatives.
- Wood:Solid timber and engineered substrates including hardwoods, softwoods, plywood, MDF, and particleboard with veneer or laminate surfacing. North American premium dining table production faces hardwood availability constraints that limit scale-up. EPA formaldehyde testing requirements under TSCA reshape supplier qualification for composite wood products.
- Upholstered:Fabric, leather, or synthetic coverings applied over foam cushioning and frame structures, requiring textile sourcing and sewing assembly capabilities. Vietnamese processing clusters are restructuring finishing capacity to retain North American and European contract relationships amid REACH chemical disclosure mandates.
- Metal:Steel, aluminum, or iron framing and accent elements offering structural durability and contemporary aesthetic appeal.
- Glass:Tempered or laminated glass tabletops and shelving components combined with metal or wood support structures.
Wood commands the broadest manufacturing footprint. Upholstered segments are climbing the fastest as flat-pack logistics networks expand direct-to-consumer penetration.
Style:
Customer type differentiation separates generational cohorts and housing vintage preferences, with younger buyers gravitating toward cleaner lines and older households maintaining traditional investment patterns.
- Modern:Minimalist forms with neutral palettes, clean edges, and functional simplicity emphasizing open spatial flow. United States coastal metropolitan areas show highest adoption among demographic cohorts purchasing through direct-to-consumer channels with augmented reality visualization tools.
- Contemporary:Current design expressions blending multiple influences with updated proportions and mixed material applications. Gallery-based experiential retail formats in major metropolitan areas enable premium positioning through tactile material demonstration.
- Traditional:Ornamented profiles, rich wood tones, and classic proportions referencing historical furniture conventions.
- Rustic:Distressed finishes, reclaimed wood aesthetics, and organic textures evoking rural or artisanal production origins.
Modern styling accounts for the greatest production volume. Contemporary segments show the steepest expansion trajectory among younger purchasers.
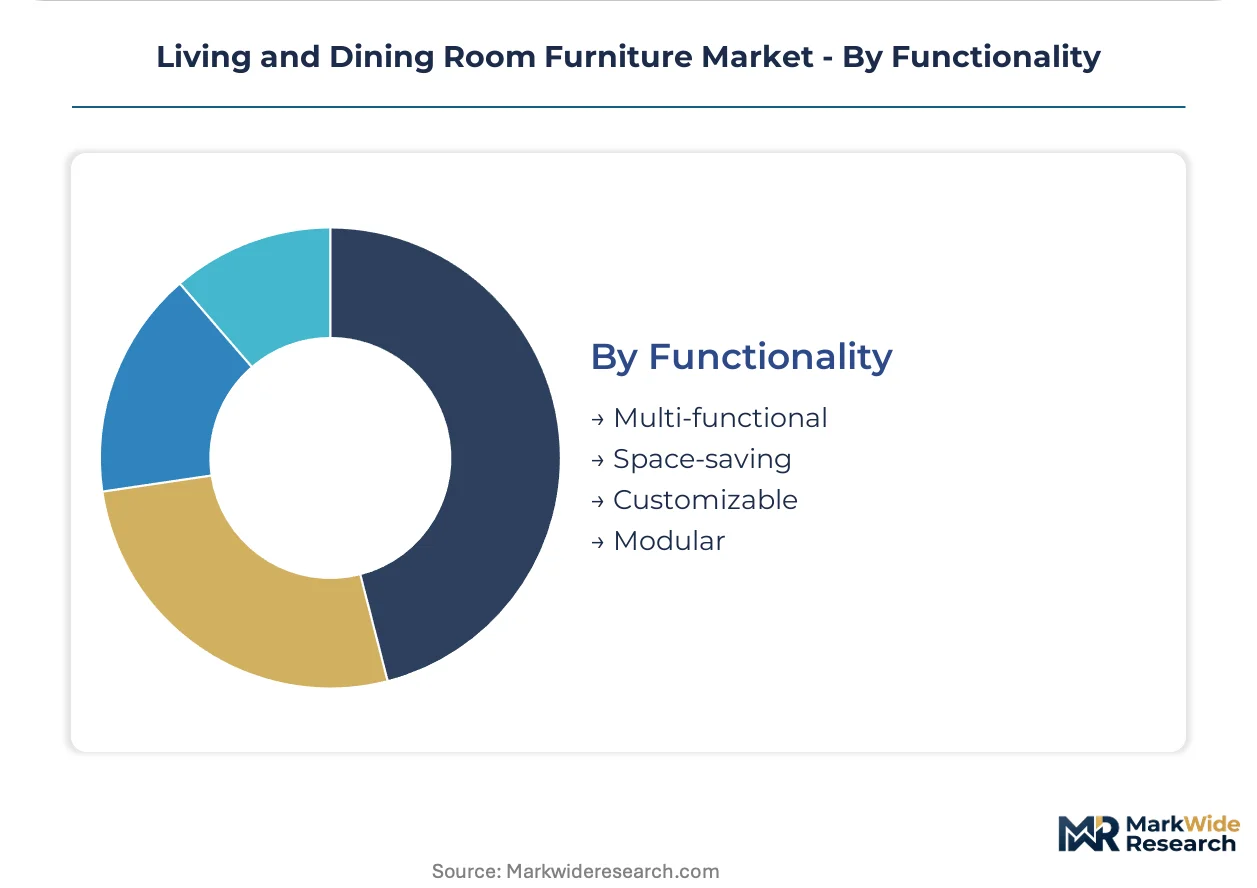
Functionality:
Application context determines which performance attributes command price premiums, with urban density constraints creating specialized demand for transformative and compact solutions.
- Modular:Component-based systems allowing reconfiguration, expansion, or relocation across room layouts and residence changes. China's compact urban apartments favor sectional sofas and storage-integrated dining configurations that reconfigure between social and meal functions.
- Space-saving:Collapsible, nesting, or wall-mounted designs maximizing usable floor area in constrained square footage. IKEA's captive flat-pack logistics network sustains margin compression in this segment through automated packaging and last-mile optimization.
- Multi-functional:Furniture serving dual purposes such as storage beds, extendable tables, or convertible seating.
- Customizable:Made-to-order dimensions, finishes, and configurations addressing non-standard room proportions or personal aesthetic preferences.
Modular systems carry the heaviest design engineering investment. Space-saving configurations are gaining share fastest in tier-one Asian and European urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns reflect divergent regulatory compliance costs, with Vietnamese wood processing clusters capturing contract volume from Chinese competitors facing escalating EPA and EU documentation requirements. This arbitrage dynamic concentrates finishing capacity reorganization in Southeast Asian export hubs while North American and European buyers diversify sourcing to mitigate certification risk.
United States
Suburban residential developers in Texas and Florida are expanding furnished unit offerings, creating coordinated demand for living and dining suites. EPA Toxic Substances Control Act formaldehyde testing requirements under TSCA reshape supplier qualification for composite wood products. North Carolina's upholstery manufacturing corridor faces skilled sewing operator shortages that constrain domestic cut-and-sew scaling.
Germany
EU Ecodesign for Sustainable Products Regulation mandates are accelerating supplier consolidation toward certified manufacturers with established documentation systems. REACH chemical disclosure requirements extend compliance obligations to full material traceability. Baden-Württemberg's precision manufacturing clusters are integrating automated CNC routing systems into solid wood dining table production lines.
China
Tier-one city apartment density in Shanghai and Beijing concentrates demand for modular configurations that reconfigure between social and meal functions. MIIT and SAMR oversight of GB standards for indoor air quality shapes engineered wood substrate specifications. Pearl River Delta manufacturing clusters are restructuring export-oriented finishing capacity amid diverging transatlantic chemical frameworks.
Vietnam
Export-oriented wood processing clusters in Binh Duong and Dong Nai provinces are restructuring finishing capacity to retain North American and European contract buyer relationships. Lower compliance documentation burdens relative to Chinese competitors attract sourcing diversification from US retailers. Ho Chi Minh City logistics hubs are expanding automated packaging lines for flat-pack furniture exports.
Italy
Gallery-based experiential retail formats in Milan and Rome enable premium positioning through tactile material demonstration and interior design consultation services. EU digital product passport requirements under the Ecodesign Regulation favor vertically integrated producers with controlled chain-of-custody systems. Brianza furniture manufacturing district anchors high-end upholstered seating and solid wood dining specialization.
Living and Dining Room Furniture Market Competitive Landscape
North American producers anchor the mid-market upholstered tier; European specialists hold premium solid wood and leather positioning. The vendor base stratifies across mass-market flat-pack logistics players, vertically integrated domestic manufacturers, and gallery-based experiential retailers. Three archetypes dominate: scale-driven supply chain optimizers, craft-intensive upholstery houses, and design-forward premium brands. Competitive moves concentrate on automated manufacturing investment and direct-to-consumer channel expansion bypassing traditional retail intermediaries.
Among scale-driven logistics optimizers, IKEA exemplifies flat-pack network efficiency and automated packaging integration. RH occupies a position within the premium experiential tier through gallery-based retail formats commanding solid wood and leather price premiums. Ashley Furniture Industries anchors domestic vertical control over upholstery cut-and-sew operations, representing the integrated mid-market archetype.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| La-Z-Boy Inc. |
| Williams-Sonoma, Inc |
| RH |
| Natuzzi S.p.A. |
| Flexform S.p.A. |
| Kimball International |
| Global Furniture USA |
| Others |
Supply & Pricing Matrix
Hardwood lumber costs cascade from North American sawmills through three distinct pricing tiers, with premium solid wood dining tables capturing scarcity markups while engineered wood substrates compress margins under EPA formaldehyde testing requirements.
Pricing Analysis
Distributor markups separate gallery-based experiential retail from flat-pack direct-to-consumer channels, with RH commanding premium positioning through tactile material demonstration while IKEA sustains margin compression via automated packaging integration. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and vertical integration depth. Price erosion runs through mass-market upholstered segments as Vietnamese finishing capacity expands. Developer-specified furnished units demonstrate lowest price sensitivity; budget-conscious direct-to-consumer buyers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from North American and European contract buyers mandate simultaneous qualification of Vietnamese and Malaysian processing clusters to mitigate certification risk. Geographic concentration centers on Vietnam, China, and Indonesia for wood substrate fabrication and finishing operations. Raw material flows draw from North American hardwood forests, Southeast Asian rubberwood plantations, and European beech supplies. Single-source vulnerability persists in premium grade timber availability. Distribution runs through specialized furniture retailers, direct-to-consumer platforms, and developer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as residential construction cycles and replacement demand for upholstered seating create predictable revenue pools across economic conditions.
For Market Incumbents: Acquire automated CNC routing and robotic sanding capabilities to defend domestic solid wood production against lower-cost import competition. Ashley Furniture Industries exemplifies backward integration into cut-and-sew operations that constrains competitor scaling. Prioritize CARB Phase 2 and EU REACH certification investment to disqualify fragmented Asian suppliers from contract buyer qualification lists.
For New Entrants and Emerging Players: LEED-certified residential developers represent an underserved buyer archetype demanding low-emission substrate innovation and material traceability documentation. White-space concentration sits in soy-based bio-adhesive alternatives to urea-formaldehyde resins for premium sustainable construction projects. Direct-to-consumer channels with augmented reality visualization tools offer the most penetrable go-to-market angle for coastal metropolitan area penetration.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification complexity extends product development timelines beyond small-scale manufacturer capital endurance. Long-term viability favors vertically integrated producers with controlled chain-of-custody systems and established documentation infrastructure. Target acquisition archetype: mid-market manufacturers with captive laboratory resources and existing EPA or EU certification portfolios. The signal to watch is transpacific shipping rate stabilization that would restore margin predictability for import-dependent contract buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Emission Substrate Innovation | Soy-based bio-adhesives differentiate manufacturers targeting LEED-certified residential construction projects. |
| Automated Packaging Integration | Flat-pack logistics optimization opens direct-to-consumer channels bypassing traditional furniture retail markups. |
| Gallery-Based Experiential Retail | Flagship showroom formats in major metropolitan areas enable premium positioning through tactile material demonstration. |
| Backward Integration into Cut-and-Sew | Domestic upholstery operations constrain competitor scaling amid skilled sewing operator recruitment gaps. |
| Digital Product Passport Compliance | EU Ecodesign Regulation documentation requirements favor vertically integrated producers with controlled chain-of-custody systems. |
Research Methodology
Direct dialogue with residential real estate developers, furniture procurement managers at retail chains, upholstery manufacturing plant managers, and logistics specialists at Southeast Asian export hubs grounded qualitative insights. Secondary validation drew from EPA TSCA filings, CARB certification databases, EU Ecodesign Regulation documentation, customs trade data, and SEC 10-K disclosures from publicly traded furniture manufacturers. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to ensure consistency.
Segmentation outputs across product type, material, style, functionality, and regional regulatory cluster were modeled throughout the forecast period. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift dynamics. Key inputs included residential construction permit flows, transpacific shipping rate indices, and formaldehyde emission standard compliance cost curves.
Underlying measurement precision varies by segment; solid wood dining tables and upholstered seating carry tighter precision than emerging modular configurations. Forecasts reflect assumptions around regulatory enforcement continuity and shipping cost normalization. Deviation in EPA or EU chemical restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture & Home Decor
Australia Office Furniture Market
Furniture & Home Decor
Adirondack Chairs Market
Furniture & Home Decor
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture & Home Decor
Toy Storage Market
Furniture & Home Decor
United States Laminate Flooring Market
Furniture & Home Decor
Wood and Laminate Flooring Market
Furniture & Home Decor
Asia-Pacific Luxury Furniture Market
Furniture & Home Decor
Dining Table Market
Furniture & Home Decor
Accent Tables Market
Furniture & Home Decor
Kitchen and Dining Furniture Market
Furniture & Home Decor
Wall Clock Market
Furniture & Home Decor
ASEAN Laminate Flooring Market
Furniture & Home Decor
Ceramic Wash Basin Market
Furniture & Home Decor
US Mattress Bases Market
Furniture & Home Decor
North America Wall Bed Market
Furniture & Home Decor
Canopy Beds Market