
 Kids Athleisure Wear Market | 2026-2036
Kids Athleisure Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Athleisure Wear Market Insights
EU REACH chemical restrictions on textile dyes and finishes is broadening the addressable market for certified sustainable kids athleisure across European retail channels. Nike leverages its Flyknit manufacturing scale to reduce material waste in children's footwear lines. Adidas anchors its position through Primegreen recycled polyester platforms that meet emerging buyer sustainability mandates. PUMA competes via its Forever Better sustainability framework, which extends to junior collections with third-party material certifications.
Kids athleisure wear encompasses performance-oriented apparel and footwear engineered for children aged two to fourteen, blending elastic fiber compositions—typically cotton-spandex or polyester-elastane blends with 5-15% stretch content—with moisture-wicking constructions to bridge athletic function and casual daily use. The category serves parents seeking single-purchase solutions that transition between school, recreation, and organized sports without dedicated uniform changes. Tops and bottoms occupy the dominant volume position within product type segmentation, though footwear commands disproportionate margin pools due to technical sole engineering and brand licensing premiums. School-age and tweens segments generate the fastest trajectory within age group breakdowns, as independent purchasing influence and peer social visibility intensify in these cohorts.
The US Consumer Product Safety Commission governs flammability and small-part standards for children's apparel, while OEKO-TEX Standard 100 certification operates as a de facto market-access requirement across premium European and North American retail channels. China's GB 31701 national textile safety standard for infants and children creates parallel compliance obligations for manufacturing sources. Stakeholders must monitor evolving chemical restriction schedules and certification tier migrations, as downstream retailers consolidate supplier lists around multi-standard compliance rather than single-market adherence.
Market Dynamics
REACH chemical restrictions and OEKO-TEX certification mandates are compressing supplier margins while simultaneously opening premium positioning for compliant manufacturers who can absorb multi-standard testing costs.
Growth Catalysts
- US youth sports participation:School-age children require versatile apparel that transitions from classroom to practice fields without wardrobe changes, expanding functional demand for moisture-wicking cotton-spandex blends.
- REACH dye restrictions:European chemical limitations on azo dyes and formaldehyde finishes are redirecting procurement toward certified sustainable suppliers, creating first-mover advantages for compliant brands.
- Recycled polyester engineering:Primegreen and comparable recycled fiber platforms are reducing virgin plastic dependency while meeting parental sustainability preferences in premium retail channels.
Market Restraints
- Elastane cost volatility:Spandex fiber prices fluctuate with petroleum derivatives and specialized polymer supply, squeezing margin predictability for stretch-content manufacturers.
- Asian manufacturing concentration:Zhejiang and Guangdong provinces dominate cut-and-sew capacity, creating single-source vulnerability for brands without diversified production footprints.
- Flammability standard divergence:US CPSC 16 CFR Part 1615/1616 sleepwear rules conflict with European EN 14878 ignition requirements, forcing parallel SKU development for cross-Atlantic distribution.
Strategic Opportunities
- Indian middle-class expansion:Urban school enrollment growth in Mumbai, Bangalore, and Delhi NCR is generating first-time athleisure demand among parents prioritizing Western-influenced children's fashion.
- Subscription wardrobe models:Size-outgrowth cycles in ages two to eight create natural replenishment demand that rental and trade-in platforms can capture with circular logistics infrastructure.
- EU Green Deal textile strategy:Extended producer responsibility mandates and digital product passport requirements will favor vertically integrated manufacturers with traceable supply chains.
Industry Challenges
- Multi-standard certification timelines:Simultaneous OEKO-TEX Standard 100, GOTS, and bluesign approvals require six-to-nine-month lead times that conflict with fast-fashion seasonal calendars.
- Technical talent scarcity:Apparel engineers with expertise in both performance fabric construction and children's safety regulations command premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Athleisure Wear Market |
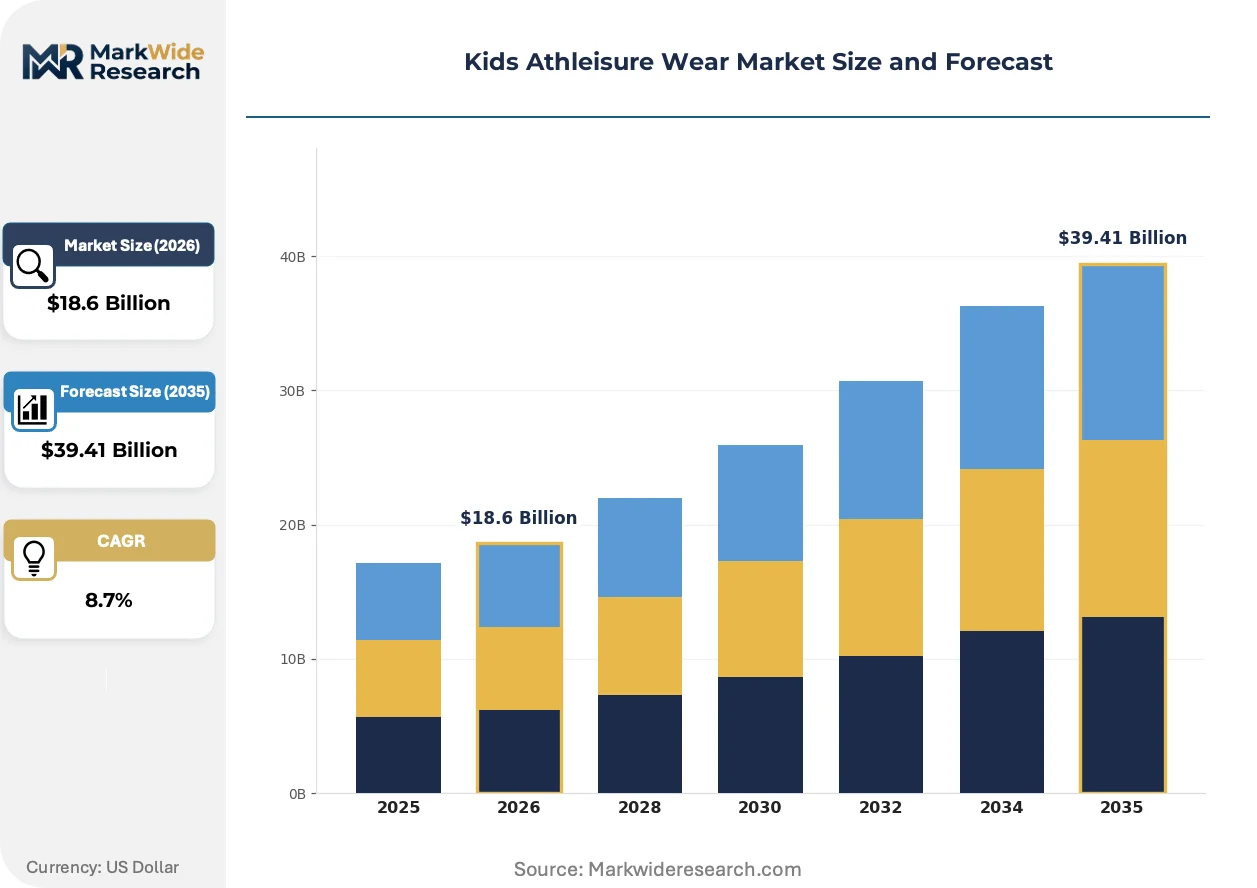
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $39.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Bottoms, Footwear, Accessories Material: Cotton, Polyester, Spandex, Nylon Age Group: Toddlers, Preschool, School-age, Tweens Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets |
| Companies Covered | Nike, Adidas, PUMA, Under Armour, Champion, ANTA, LI-NING, Decathlon, Reebok, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Athleisure Wear Market Trends and Innovations
Material science advances and regulatory digitization are compressing product development cycles while fragmenting distribution channels away from traditional wholesale toward direct-to-parent engagement models.
Seamless knitting technology is overtaking conventional cut-and-sew assembly in children's base layers and leggings. School-age segments adopt these garments fastest due to tagless comfort and reduced seam irritation during extended wear. The shift is compressing labor costs in manufacturing while enabling localized micro-factory production closer to end markets.
EU Ecodesign for Sustainable Products Regulation will mandate recycled content thresholds and digital product passports for textiles entering European retail. Manufacturers must reconfigure material sourcing and data infrastructure to meet 2027 implementation timelines. Children's apparel faces heightened scrutiny given vulnerable-user classification and stricter chemical migration limits.
Parents increasingly favor buy-now-pay-later integration at checkout for seasonal wardrobe refreshes. Specialty children's retailers and direct-to-consumer brands deploy these financing tools most aggressively in US and UK markets. The behavior extends average order values while concentrating payment default risk with platform providers rather than merchandise vendors.
Kids Athleisure Wear Market Segmentation
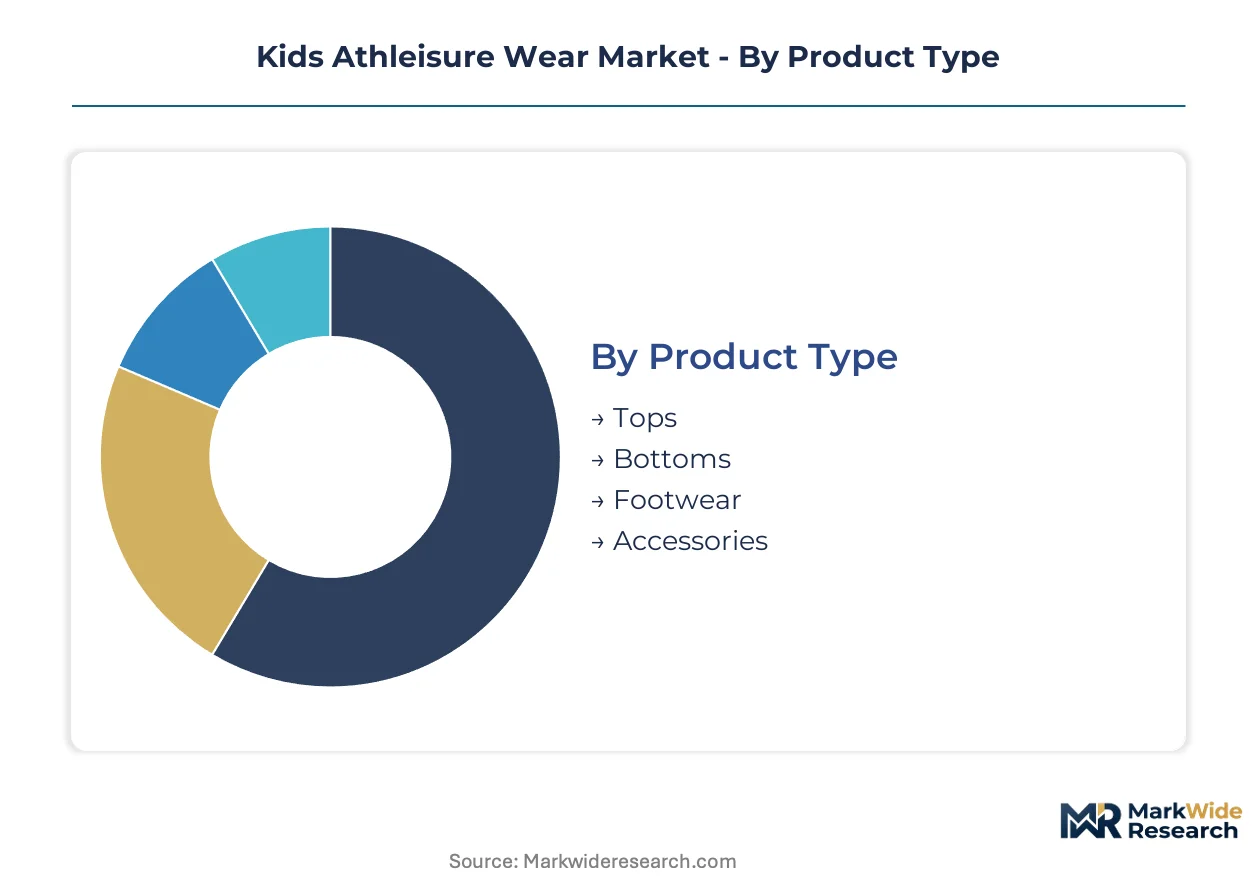
Segmentation in kids athleisure wear reveals how capital allocation, material specifications, and channel economics fragment addressable demand across distinct buyer cohorts. Manufacturers must align production scale with the stretch-content requirements and certification burdens specific to each slice.
Product Type:
Footwear absorbs the highest upfront capital commitment due to technical sole molds and brand licensing premiums, while apparel segments concentrate volume in cut-and-sew capacity.
- Tops:Cotton-spandex blends with 5-15% stretch content dominate construction, engineered for moisture-wicking performance during classroom-to-playground transitions. Demand clusters in United States school districts with relaxed dress codes, where parents prioritize single-garment versatility over dedicated athletic uniforms.
- Bottoms:Leggings and joggers leverage seamless knitting technology to reduce seam irritation during extended wear, with elastic waistbands accommodating rapid size fluctuations in ages two to eight. European retail channels favor these garments for OEKO-TEX compliance visibility.
- Footwear:Technical sole engineering requires specialized polymer injection equipment and multi-density foam layering. Margin pools here exceed apparel due to performance branding premiums and replacement cycles tied to foot growth.
- Accessories:Headbands, socks, and bags complete outfit coordination with lower material complexity but higher inventory velocity in subscription wardrobe models.
Most installed capacity flows through Tops. Expansion is steepest in Footwear.
Material:
Polyester platforms command the largest procurement volumes, though spandex fiber pricing volatility shapes margin predictability across all stretch-dependent segments.
- Cotton:Natural fiber base layer for skin-sensitive toddlers, sourced predominantly from Indian spinning mills serving premium European retail channels with GOTS organic certification.
- Polyester:Recycled fiber engineering through Primegreen-type platforms reduces virgin plastic dependency while meeting parental sustainability preferences in United States and United Kingdom premium channels. This segment concentrates the fastest volume gains as REACH dye restrictions redirect procurement toward certified sustainable suppliers.
- Spandex:Petroleum-derivative polymer supply exposes manufacturers to elastane cost volatility, squeezing margin predictability for 5-15% stretch-content specifications mandatory in athleisure construction.
- Nylon:Lightweight durability drives outerwear and accessory applications, with Chinese Zhejiang province dominating filament yarn production capacity.
Polyester carries the heaviest procurement tonnage. Recycled-content grades are climbing the fastest.
Age Group:
School-age children generate the steepest demand trajectory as independent purchasing influence and peer social visibility intensify in these cohorts.
- Toddlers:Size-outgrowth cycles every three to four months create natural replenishment demand that rental and trade-in platforms target with circular logistics infrastructure.
- Preschool:Playground durability requirements favor reinforced knee panels and stain-resistant finishes, with parents prioritizing cost-per-wear economics over premium branding.
- School-age:Youth sports participation in United States communities drives moisture-wicking cotton-spandex demand for classroom-to-practice transitions. This cohort commands the fastest expansion as casual dress codes spread through public and private school systems.
- Tweens:Peer social visibility and brand consciousness peak here, with direct-to-parent engagement models capturing wallet share through buy-now-pay-later integration at checkout.
School-age segments absorb the largest volume share. Tweens are expanding most quickly.
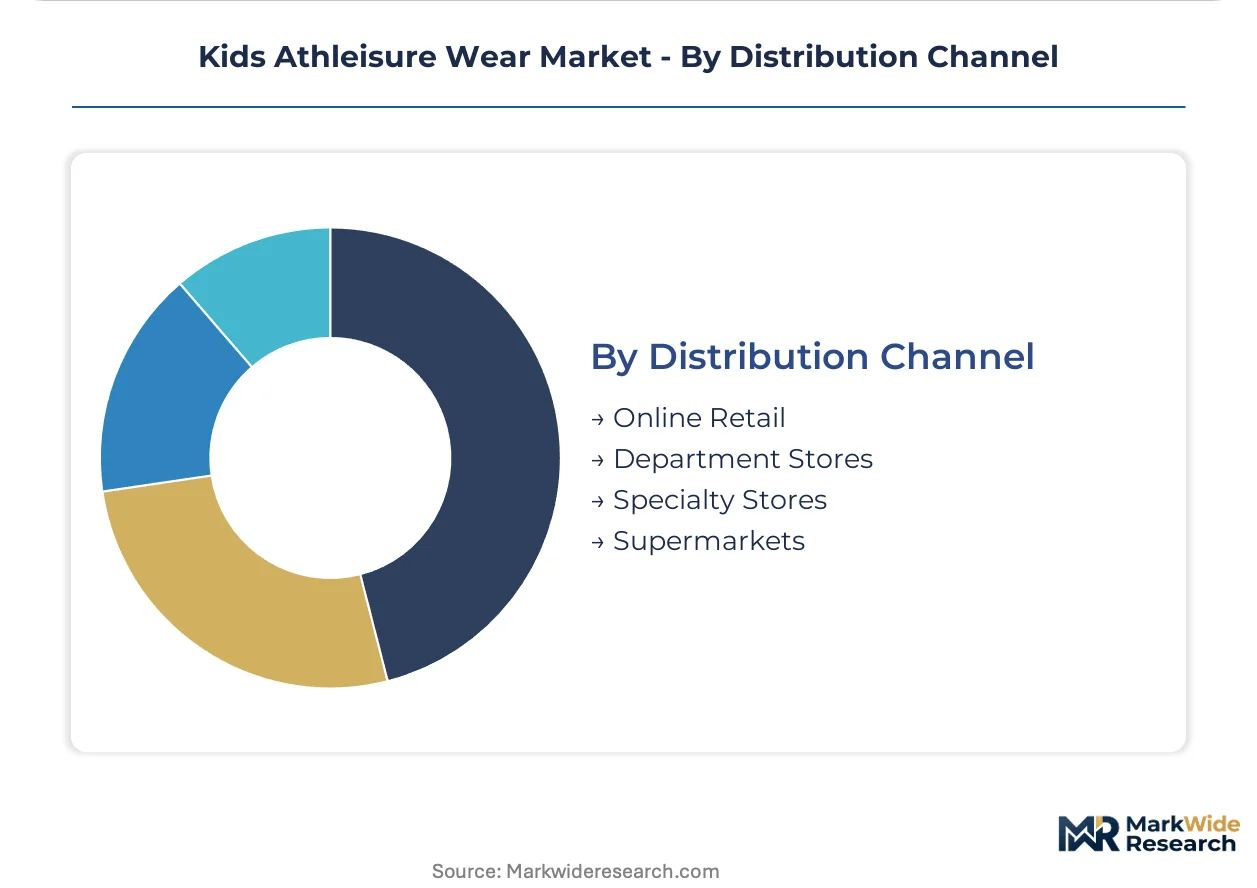
Distribution Channel:
Online retail requires the heaviest technology infrastructure investment, while specialty stores concentrate premium positioning with certified sustainable assortment depth.
- Online Retail:Direct-to-consumer brands deploy aggressive digital acquisition in United States and United Kingdom markets, with financing tools extending average order values while concentrating payment default risk with platform providers.
- Department Stores:Consolidated supplier lists around multi-standard compliance favor large manufacturers with six-to-nine-month OEKO-TEX and GOTS certification timelines already completed.
- Specialty Stores:Curated assortments targeting sustainability-motivated parents command premium pricing for bluesign-approved and OEKO-TEX Standard 100 certified merchandise.
- Supermarkets:Value-tier positioning captures price-sensitive volume in European and North American mass-market channels, with limited stretch-content specifications and basic moisture-wicking constructions.
Online Retail channels move the highest transaction velocity. Specialty Stores are gaining share fastest among premium-positioned parents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apparel engineering talent clusters in coastal manufacturing hubs anchor regional production capabilities, with chemical compliance expertise concentrating in European regulatory centers and technical textile development dominating Asian supply bases.
United States
Youth sports participation and relaxed school dress codes drive moisture-wicking cotton-spandex demand across suburban districts. The US Consumer Product Safety Commission enforces 16 CFR Part 1615/1616 flammability standards that conflict with European ignition rules. Los Angeles and New York Metro host design studios where technical fabric innovation meets direct-to-consumer brand headquarters.
China
GB 31701 national textile safety standards create parallel compliance obligations for infant and children's apparel exports. Zhejiang and Guangdong provinces dominate cut-and-sew capacity with concentrated elastane-blend manufacturing. Guangzhou industrial clusters engineer seamless knitting equipment that compresses labor costs for base layer production.
Germany
REACH chemical restrictions on azo dyes and formaldehyde finishes redirect procurement toward certified sustainable suppliers. ECHA enforcement elevates material standards across premium European retail channels. Bavaria hosts technical textile research centers where recycled polyester engineering advances meet automotive-sector polymer expertise.
India
Urban school enrollment growth in Mumbai, Bangalore, and Delhi NCR generates first-time athleisure demand among middle-class parents. BIS certification requirements align with export-market access protocols for European and North American buyers. Tamil Nadu spinning mills supply GOTS-certified organic cotton to premium private-label programs.
United Kingdom
Buy-now-pay-later integration at checkout extends average order values for seasonal wardrobe refreshes among digitally native parents. OEKO-TEX Standard 100 certification operates as de facto market-access requirement across premium retail channels. London-based direct-to-consumer brands deploy aggressive digital acquisition with financing tools concentrated in UK and US markets.
Kids Athleisure Wear Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. Vertically integrated manufacturers with captive spinning and dyeing capacity face asset-light brands outsourcing to certified cut-and-sew networks. Three archetypes dominate: global sportswear conglomerates with technical footwear engineering, mid-scale private-label specialists with multi-standard compliance depth, and direct-to-consumer entrants with digital-native customer acquisition. Competitive moves concentrate on recycled fiber platform licensing and seamless knitting technology partnerships that compress lead times.
Within the global sportswear tier, Nike, Adidas, and PUMA anchor positioning through manufacturing scale and sustainability framework differentiation. Nike leverages Flyknit production infrastructure across children's footwear lines. Adidas anchors market presence through Primegreen recycled polyester platforms. PUMA competes via third-party material certifications extending to junior collections. These three exemplify how technical sole engineering and brand licensing premiums concentrate margin pools disproportionately in footwear versus apparel segments.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| PUMA |
| Under Armour |
| Champion |
| ANTA |
| LI-NING |
| Decathlon |
| Reebok |
| Others |
Pricing and Supply Chain Analysis
Seamless knitting technology adoption is compressing labor costs in children's base layer production while enabling localized micro-factory placement closer to end markets, simultaneously fragmenting traditional cut-and-sew economics and redistributing margin capture toward equipment-intensive manufacturers with technical knitting expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX Standard 100 certified merchandise from basic moisture-wicking constructions and unbranded mass-market alternatives. Price differentiation rests on certification grade and brand licensing premiums, with technical footwear commanding disproportionate margin pools due to sole engineering complexity. Cost compression in economy tiers is intensifying because of elastane fiber volatility tied to petroleum derivatives. Parents of toddlers exhibit highest price sensitivity due to rapid size-outgrowth cycles, while tween segment buyers show lowest sensitivity as peer social visibility drives brand preference.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Guangdong provinces, where concentrated cut-and-sew capacity for cotton-spandex blends creates exposure to regional disruption. Manufacturing draws from Indian spinning mills for GOTS-certified organic cotton, Chinese filament yarn production for nylon outerwear components, and petroleum-derivative polymer supply for spandex stretch content. Tariff exposure on finished apparel imports into North American and European markets threatens margin stability for brands without diversified production footprints. Distribution runs through consolidated department store supplier lists, direct-to-consumer digital channels, and specialty retail with curated sustainable assortments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kids athleisure functions as a regulatory compounder where EU Ecodesign for Sustainable Products Regulation mandates are elevating compliance costs while simultaneously expanding premium addressable demand for certified manufacturers.
For Market Incumbents: Anticipate margin compression from multi-standard certification timelines that conflict with fast-fashion seasonal calendars by deepening backward integration into captive spinning and dyeing capacity. Prioritize OEKO-TEX Standard 100, GOTS, and bluesign approvals ahead of retailer consolidation around compliant supplier lists. Defend against direct-to-consumer entrants through exclusive distribution partnerships with specialty children's retailers. For New Entrants and Emerging Players: Enter via subscription wardrobe models targeting toddler and preschool segments where size-outgrowth cycles create natural replenishment demand and incumbents lack circular logistics infrastructure. Capture white-space in Indian urban markets where Mumbai, Bangalore, and Delhi NCR middle-class expansion generates first-time athleisure demand among Western-influenced parents. Deploy buy-now-pay-later integration at checkout to extend average order values without assuming payment default risk. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale private-label specialists with multi-standard compliance depth but limited brand recognition, as large sportswear conglomerates trade at manufacturing scale premiums. Long-term viability favors vertically integrated manufacturers with traceable supply chains positioned for EU Green Deal extended producer responsibility mandates. Monitor digital product passport implementation timelines as inflection indicator for compliance infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Technology Partnership | Compresses labor costs for Nike and Adidas while enabling localized micro-factory production. |
| Recycled Polyester Platform Licensing | Primegreen-type engineering reduces virgin plastic dependency for parental sustainability preferences. |
| Multi-Standard Certification Investment | OEKO-TEX and GOTS approvals secure placement on consolidated department store supplier lists. |
| Direct-to-Consumer Digital Launch | Financing tool integration extends average order values among UK and US digitally native parents. |
| Circular Logistics Infrastructure Buildout | Rental and trade-in platforms capture natural replenishment demand from toddler size-outgrowth cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at specialty children's retailers, supply planners, and technical fabric engineers with secondary validation through customs records, Nielsen retail audit data, SEC filings of publicly traded sportswear conglomerates, and certification database tracking from OEKO-TEX and GOTS registries. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Segment-weighting across product type, material composition, age cohort, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from elasticity modeling against youth sports participation rates, school dress code policy shifts, and regulatory implementation schedules. Forecast inputs incorporated REACH chemical restriction phase-in timelines and EU Ecodesign recycled content threshold mandates.
The model holds under stable elastane fiber pricing and continued retailer consolidation around multi-standard compliance; deviation in petroleum derivative volatility or accelerated digital product passport enforcement would shift volume and value outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Japan Pet Boarding Market
Consumer Goods
Global Hair Color Market
Consumer Goods
Fan Market
Consumer Goods
Bags Market
Consumer Goods
Europe Protective Footwear Market
Consumer Goods
South Korea Hair Care Market
Consumer Goods
Fanny Packs Market
Consumer Goods
Diaper Bag Market
Consumer Goods
Lip Products Pigment Market
Consumer Goods
Canister Vacuum Cleaners Market
Consumer Goods
Heated Towel Rail Market
Consumer Goods
Shoe Shine Machine Market
Consumer Goods
Kids Apparel Market
Consumer Goods
Asia Pacific Beauty Fridges Market
Consumer Goods
Electric Dryers Market
Consumer Goods
Soundbar Market