
 Fanny Packs Market | 2026-2036
Fanny Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Fanny Packs Market Analytics
Modular accessory bundling is pivoting how consumers evaluate fanny packs, with brands now pairing base pouches with detachable straps, hip belts, and organizer inserts to expand use cases. JanSport leverages its campus-retail footprint to anchor volume in the student segment. Osprey competes through technical load-distribution features drawn from its backpacking heritage. Cotopaxi differentiates via colorful, repurposed-fabric constructions that signal sustainability credentials.
A fanny pack denotes a small fabric pouch secured to the waist or hip by an adjustable strap, typically constructed from woven synthetics or leather with zippered compartments and a capacity under five liters, designed for hands-free transport of personal items during transit, recreation, or work. Sport Packs lead volume as runners and cyclists demand breathable, bounce-free designs with reflective elements, while Fashion Packs capture expanding margin pools through designer collaborations and premium leather executions. Nylon dominates material selection for its abrasion resistance and water-repellent coatings, though Leather commands price premiums in urban fashion channels.
FDA oversight of textile flammability standards and California's Proposition 65 warning-label mandates shape material sourcing and consumer communication obligations for brands selling into the United States. The Consumer Product Safety Commission monitors drawstring and small-component risks in children's belt bags, influencing design specifications for the Kids end-user segment. Stakeholders must monitor evolving state-level chemical disclosure laws and decide whether to front-load compliance investment or segment product lines by regulatory jurisdiction.
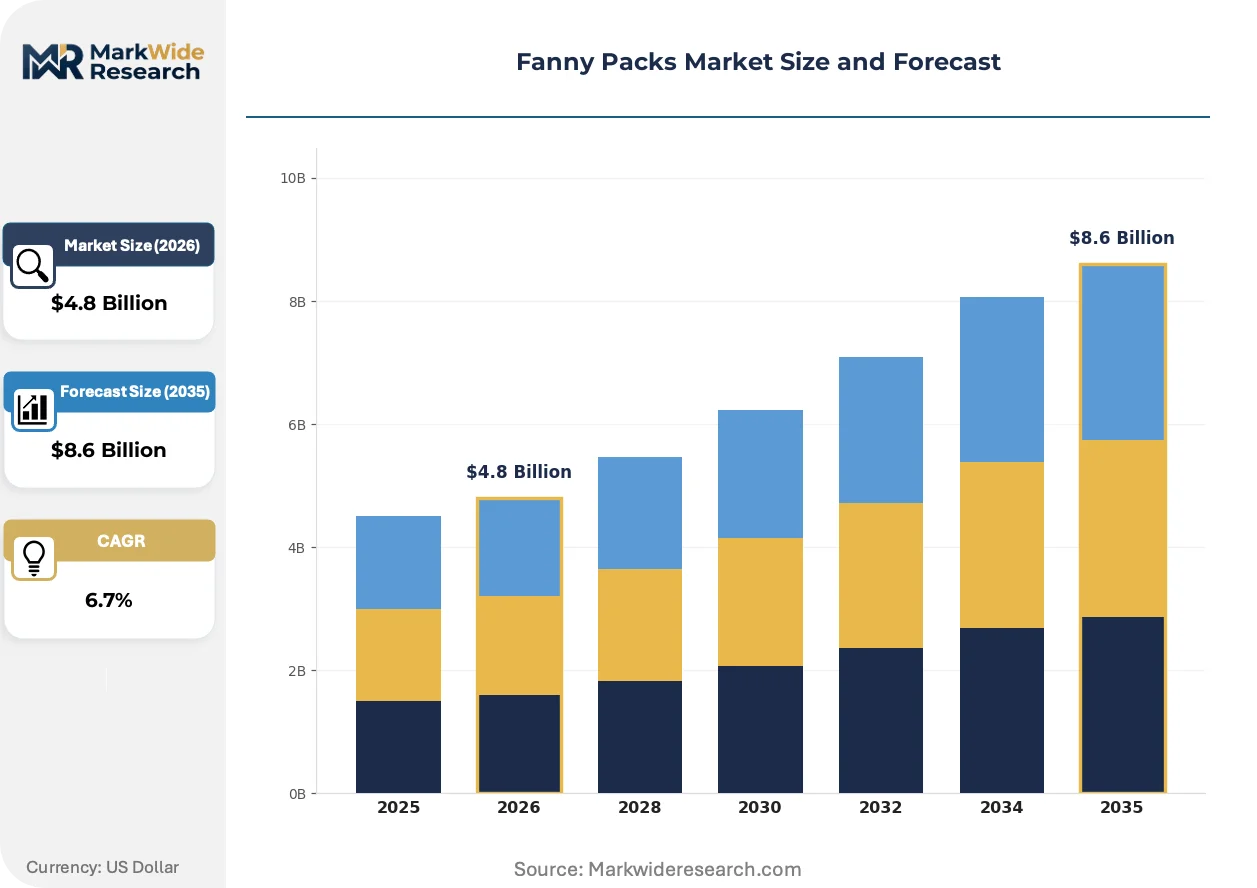
Market Dynamics
Modular accessory bundling is restructuring how consumers evaluate fanny packs, with brands now pairing base pouches with detachable straps and organizer inserts to expand use cases beyond single-purpose waist bags.
Growth Catalysts
- Festival and outdoor recreation culture:Music festivals in the United States and hiking trail networks across Germany are normalizing hands-free carry as essential gear, driving replacement cycles and premium pack adoption.
- REACH chemical compliance:European material disclosure requirements are forcing nylon and polyester suppliers to upgrade coating chemistries, which in turn enables brands to market verified low-toxicity products to health-conscious buyers.
- RFID-blocking fabric integration:Travelers at major international airports are demanding embedded signal shielding for passport and credit card protection, expanding the functional perimeter of basic belt bags.
Market Restraints
- Petrochemical input volatility:Nylon 6,6 and polyester filament prices swing with crude oil benchmarks, compressing margins for mid-tier manufacturers without long-term polymer contracts.
- Concentrated zipper and hardware supply:YKK and a handful of Taiwanese fastener specialists control critical closure components, creating single-source vulnerability for smaller pack brands.
- California Proposition 65 litigation exposure:Warning-label mandates for phthalates and heavy metals in coated fabrics generate compliance costs and reputational risk for direct-to-consumer sellers.
Strategic Opportunities
- India's urban mobility transition:Metro expansion in Mumbai and Bangalore is creating first-time hands-free carry demand among commuters previously reliant on shoulder bags.
- Medical device convergence:Insulin pump and continuous glucose monitor wearers need discreet, secure waist-mounted carry solutions that existing diabetes accessory brands have not fully addressed.
- EU Green Deal circularity incentives:Textile take-back schemes and extended producer responsibility frameworks reward brands building repairable, recyclable pack architectures with preferential shelf placement.
Industry Challenges
- Technical softgoods pattern engineering:Brands lack sufficient talent in 3D body-scanning and parametric pattern design required for bounce-free running packs, forcing reliance on expensive external studios.
- Small-component safety certification:Children's belt bags require CPSC-compliant breakaway hardware and choke-tested zipper pulls, extending product development timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fanny Packs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Packs, Travel Packs, Fashion Packs, Mini Packs Material: Nylon, Polyester, Leather, Canvas End User: Adults, Kids, Travelers, Athletes Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | JanSport, EVOC, Patagonia, REI Co-op, Black Diamond, Osprey, The North Face, Mountainsmith, Cotopaxi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fanny Packs Market Evolving Landscape
Smart fabric integration and circular material sourcing are redefining what consumers expect from waist-worn carry, collapsing the distinction between technical outdoor gear and everyday urban accessories.
Recycled ocean plastic filament is expanding into fanny pack linings and shell fabrics as brands chase verified sustainability credentials. Runners and trail athletes in the Pacific Northwest are adopting these packs fastest, treating material provenance as a performance feature. This shift is compressing demand for virgin nylon in the sport pack segment while raising baseline price floors.
California's Proposition 65 enforcement is tightening disclosure obligations for brands selling coated synthetics into the United States. The state's attorney general actions are forcing reformulation of water-repellent treatments industry-wide. Urban fashion labels with direct California distribution are absorbing the highest compliance costs and passing them through to premium leather alternatives.
Buyers are consolidating purchases around modular systems rather than standalone packs. Festival attendees and international travelers now expect base pouches to accept interchangeable straps, hip belts, and organizer inserts from the same brand ecosystem. This behavior is most visible in United States coastal cities where subscription-style accessory bundles are displacing single-item e-commerce.
Fanny Packs Market Segmentation
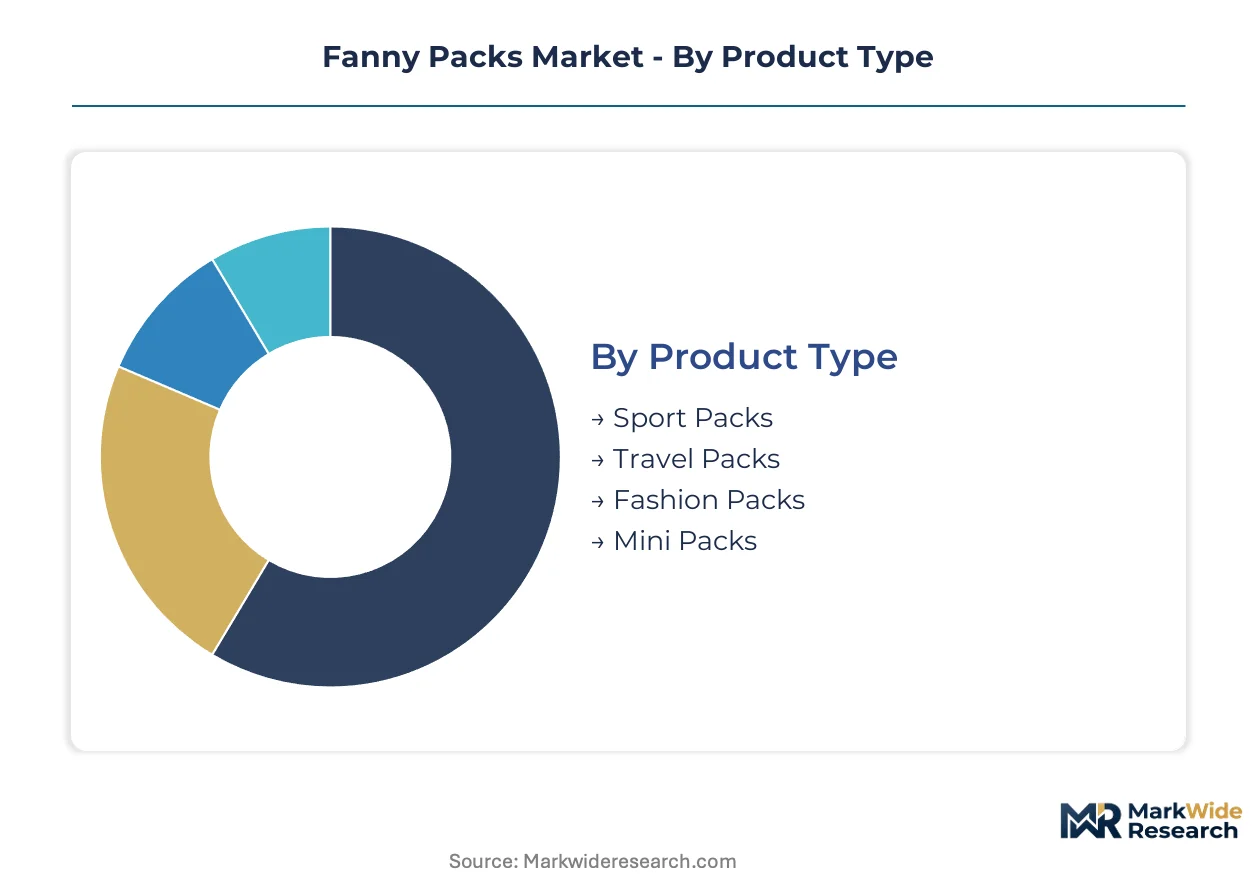
Segmentation in the fanny packs market reveals how replacement cycles and upgrade triggers vary sharply across use cases. Athletes replace sport packs every 18-24 months due to fabric fatigue, while fashion buyers chase seasonal color drops. Understanding these rhythm differences lets brands calibrate inventory and messaging to the right replacement windows.
Product Type:
Upgrade cycles diverge dramatically across product types, with technical users replacing worn gear faster than style-driven buyers who refresh for aesthetics.
- Sport Packs:Engineered with breathable mesh back panels and stabilizing hip belts to eliminate bounce during high-impact movement. Runners and cyclists in the United States drive repeat purchases as sweat and UV exposure degrade elastic components within two seasons.
- Travel Packs:Built around RFID-blocking compartments and TSA-friendly dimensions for seamless airport navigation. International flyers departing from Heathrow and Changi prioritize these features, with replacement triggered by security protocol updates rather than wear.
- Fashion Packs:Designer collaborations and premium leather constructions signal status in urban environments. Trend velocity in Milan and Tokyo drives shorter ownership cycles than functional categories.
- Mini Packs:Sub-two-liter capacities target festival attendees and minimalists seeking phone-and-wallet carry. Ultra-lightweight construction appeals to EDC enthusiasts in Berlin and Brooklyn.
Sport Packs sits at the top of the volume ranking, with Travel Packs climbing the fastest.
Material:
Cost tiers stratify sharply by material, with petrochemical-derived synthetics anchoring mass-market price floors and animal hides commanding 4-6x premiums in boutique channels.
- Nylon:Abrasion-resistant 210D-420D weaves with DWR coatings dominate technical applications. Thru-hikers on the Pacific Crest Trail and Appalachian Trail demand these specifications for multi-month durability.
- Polyester:Recycled filament variants from ocean plastic recovery programs gain traction among sustainability-conscious buyers. REI and Patagonia retail footprints in Seattle and Denver accelerate adoption.
- Leather:Full-grain and top-grain hides from Italian and Argentinian tanneries define luxury positioning. Craftsmanship messaging resonates in Paris and Manhattan heritage retail.
- Canvas:Heavy cotton duck and waxed finishes appeal to workwear aesthetics and heritage revival trends. Artisan makers in Portland and London cultivate limited-batch followings.
Nylon leads absolute volume, though recycled Polyester gains share fastest as brands chase verified sustainability credentials.
End User:
Customer type determines feature prioritization, with safety mandates governing children's designs and performance specifications driving athlete purchases.
- Adults:The broadest addressable base spanning commuters, parents, and casual recreationists. Urban professionals in Chicago and Austin normalize daily carry across work and leisure contexts.
- Kids:CPSC-mandated breakaway hardware and choke-tested components extend development timelines. Parents in suburban United States markets prioritize visible safety certifications over price.
- Travelers:Security-focused buyers seeking anti-theft features and document organization. International departure growth from Dubai and Singapore shapes demand concentration.
- Athletes:Technical users requiring bounce-free stability and moisture management. Marathon training communities in Boston and London drive specification intensity.
Adults commands the largest installed base, with Travelers expanding most quickly as international mobility normalizes post-pandemic.
Distribution Channel:
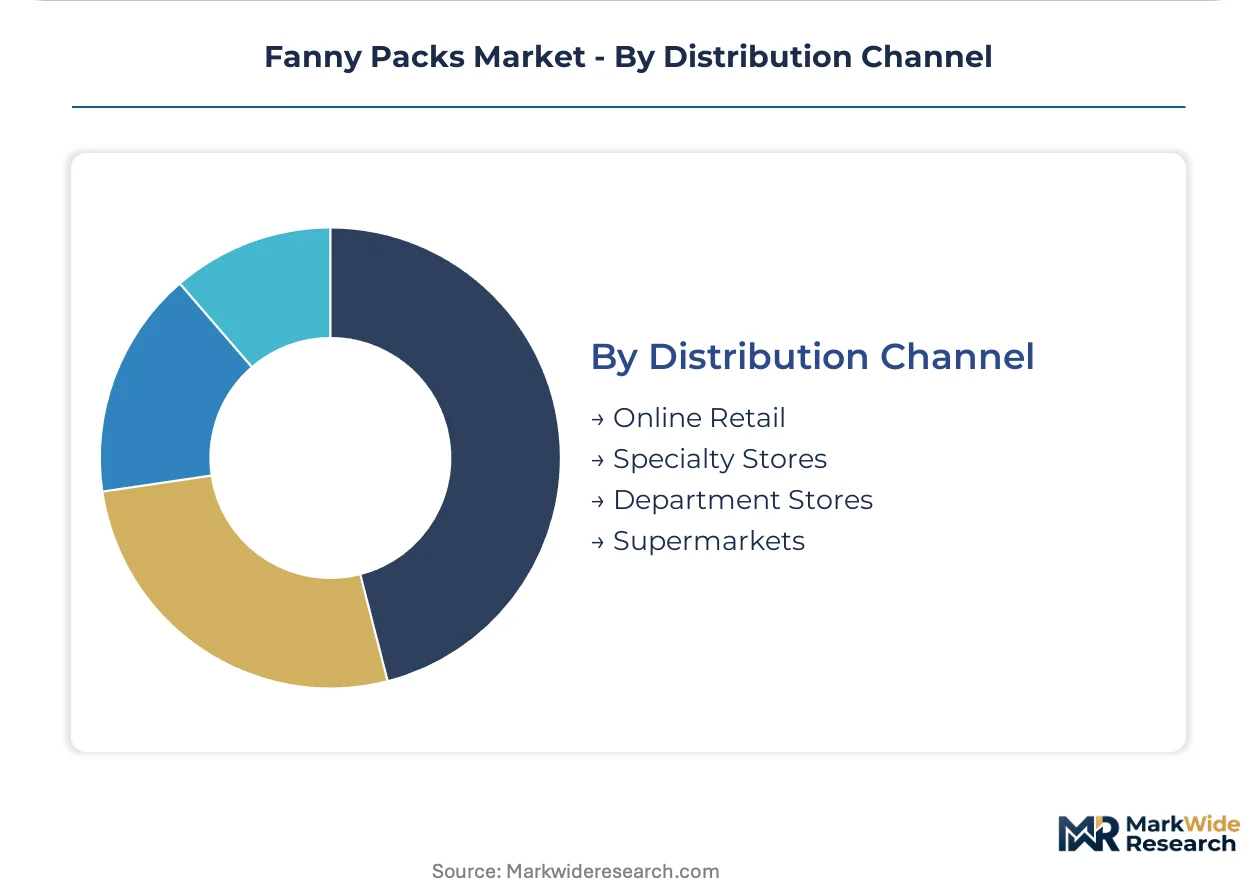
Channel mix reflects how discovery and purchase convenience trade off across buyer maturity stages, with online dominant for replenishment and physical retail critical for fit verification.
- Online Retail:Direct-to-consumer and marketplace platforms capture price-sensitive and convenience-driven transactions. Amazon and brand.com channels in the United States and Germany consolidate share through subscription bundling.
- Specialty Stores:Curated assortments with expert fitting services justify premium positioning. Running specialty chains like Fleet Feet and independent outdoor retailers in Boulder and Chamonix anchor technical pack sales.
- Department Stores:Mid-tier fashion packs reach style-conscious buyers through seasonal floor sets. Macy's and Nordstrom footprints in metropolitan United States markets drive impulse purchases.
- Supermarkets:Mass-market basic packs compete on price for unplanned or entry-level purchases. Walmart and Target distribution in exurban United States locations captures first-time buyers.
Online Retail leads transaction volume, with Specialty Stores climbing fastest as technical buyers prioritize fit expertise and community connection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fanny pack traces its commercial lineage to 1980s outdoor recreation culture in the United States, where brands like Mountainsmith pioneered hip-worn carry for hikers. From this origin, manufacturing and demand have dispersed across distinct national clusters, each shaped by local mobility patterns and regulatory frameworks.
United States
Festival culture in Austin and outdoor recreation across Colorado sustain premium pack demand through replacement-driven purchasing. The Consumer Product Safety Commission enforces breakaway hardware standards for children's belt bags, extending development timelines for youth-oriented lines. Los Angeles and Brooklyn anchor direct-to-consumer brand headquarters, where subscription bundling models displace single-item e-commerce.
Germany
Technical hiking communities along the Alpine Trail network and urban cycling in Berlin normalize hands-free carry as essential mobility infrastructure. REACH chemical compliance through ECHA mandates material disclosure across nylon and polyester coatings, forcing supplier upgrades. Munich and Hamburg concentrate specialty outdoor retail footprints where expert fitting services justify premium positioning.
Japan
Minimalist urban commuters in Tokyo and Osaka drive demand for sub-two-liter mini packs as phone-and-wallet carry solutions. METI oversees textile labeling standards that govern material content claims in domestic distribution. The Kansai region hosts precision zipper and hardware specialists whose components supply regional pack assemblers.
India
Metro expansion in Mumbai and Bangalore creates first-time hands-free carry demand among commuters transitioning from shoulder bags. BIS certification requirements for textile flammability shape import specifications for coated synthetic fabrics. The Delhi-NCR corridor concentrates e-commerce fulfillment infrastructure where Amazon and Flipkart process subscription accessory bundles.
United Kingdom
Festival attendance at Glastonbury and urban cycling in London sustain fashion-pack and sport-pack segments through distinct buyer cohorts. The UK's post-Brexit UKCA marking regime replaces CE conformity assessment for products sold domestically. Manchester and Glasgow anchor independent outdoor retail chains where community connection drives technical pack sales.
Fanny Packs Market Competitive Landscape
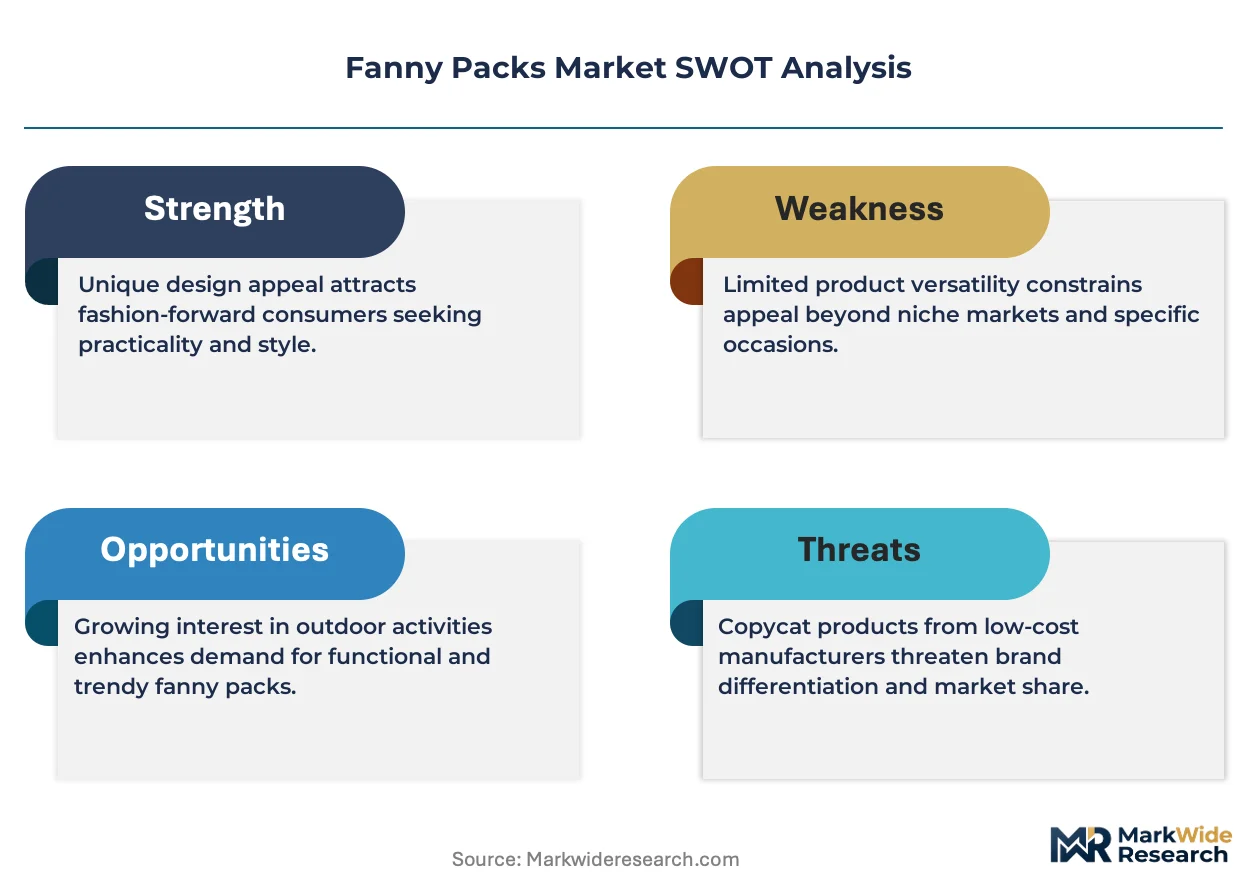
The competitive structure tilts toward heritage outdoor brands with technical credibility and direct-to-consumer insurgents with modular product architectures. Established players leverage decades of load-distribution engineering from backpacking heritage, while newer entrants compete through sustainability signaling and interchangeable accessory ecosystems. Three archetypes dominate: technical outdoor specialists, fashion-forward lifestyle labels, and circular-economy native brands. Consolidation pressure manifests through strategic partnerships between material suppliers and finished-goods brands, alongside geographic expansion into Asian urban mobility markets.
Within the technical specialist tier, JanSport and Osprey exemplify divergent heritage applications. JanSport occupies a position anchored in campus-retail distribution and student-segment volume. Osprey represents load-distribution engineering transferred from backpacking to waist-worn carry. Cotopaxi sits within the circular-economy native archetype, its colorful repurposed-fabric constructions signaling sustainability credentials without explicit performance claims. These three companies illustrate how competitive positioning fragments across technical credibility, distribution scale, and material provenance rather than converging on a single dominant model.
| Leading Market Players |
|---|
| JanSport |
| EVOC |
| Patagonia |
| REI Co-op |
| Black Diamond |
| Osprey |
| The North Face |
| Mountainsmith |
| Cotopaxi |
| Others |
Value Network & Pricing Analysis
Parametric pattern engineers concentrated in Vietnam and Bangladesh feed labor-cost differentials that widen pricing-tier spreads between mass-market nylon packs and precision-fitted technical designs. Brands without captive technical talent absorb premium outsourcing rates that compress margins at the mid-market tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with price differentiation driven by certification grade and after-sales bundling. REACH-compliant coating chemistries and CPSC-certified breakaway hardware command tier premiums. Cost compression in the standard tier is intensifying because petrochemical input volatility squeezes contract manufacturers. Festival attendees and first-time buyers in exurban United States markets exhibit highest price sensitivity, while thru-hikers and international travelers accept premium positioning for verified durability.
Supply Chain Analysis
India's phased manufacturing program and domestic-content incentives for textile assembly are reshaping sourcing decisions for brands serving European and North American markets. Manufacturing concentrates in Vietnam, Bangladesh, and China, with raw material dependencies spanning Taiwanese zipper hardware, Italian tannery outputs, and ocean-recovery polyester filament. Single-source vulnerability around YKK fastener supply creates structural risk for smaller pack brands lacking volume commitments. Distribution runs through direct-to-consumer platforms and specialty outdoor retail chains with expert fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fanny packs market reads as a late-cycle quality story where replacement-driven purchasing and modular upgrade paths favor brands with verified technical credentials. Travelers demanding RFID-blocking integration and festival buyers seeking customizable ecosystems are consolidating purchases around premium specifications.
For Market Incumbents: Lock in long-term polymer contracts to insulate margin positions from crude oil benchmark swings. Secure exclusive distribution partnerships with running specialty chains like Fleet Feet to defend against direct-to-consumer insurgents capturing technical buyers through subscription bundling. For New Entrants and Emerging Players: EU Green Deal circularity incentives in Germany and France open a window for repairable-pack architectures that qualify for preferential retail placement. Target India's metro-expansion corridors in Mumbai and Bangalore with sub-two-liter mini packs priced for first-time hands-free carry demand. For Investors and Strategic Acquirers: Heritage outdoor brands with backpacking-engineering credibility are the most active acquirer in this space, seeking technical softgoods capabilities. The acquisition target archetype is circular-economy-native brands with verified repurposed-fabric supply chains. Watch for inflection when California Proposition 65 enforcement triggers industry-wide coating reformulation costs that favor scaled players.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Accessory Ecosystem Development | Interchangeable straps and organizer inserts from Cotopaxi and JanSport expand use-case capture per customer. |
| REACH-Compliant Coating Reformulation | Low-toxicity DWR chemistries enable premium positioning in ECHA-regulated European markets. |
| RFID-Blocking Fabric Integration | Signal-shielding compartments from Osprey and The North Face address Heathrow and Changi traveler security demands. |
| Direct-to-Consumer Subscription Launch | Accessory bundling models in Los Angeles and Brooklyn displace single-item e-commerce for repeat purchase capture. |
| Extended Producer Responsibility Alignment | Textile take-back schemes in Munich and Hamburg reward repairable architectures with retail shelf preference. |
Research Methodology
Direct dialogue with brand product managers, specialty retail buyers, textile coating chemists, and parametric pattern engineers grounded the qualitative foundation. Secondary validation drew from ECHA REACH substance databases, CPSC recall and compliance records, U.S. Customs textile import data, and outdoor industry association shipment reports. Bottom-up and top-down triangulation reconciled channel-level transaction patterns with macro-level material flow analysis.
Bottom-up modeling tracked replacement-cycle frequencies across sport, travel, fashion, and mini pack segments, while top-down analysis calibrated aggregate value against synthetic fiber consumption and zipper hardware trade flows. Segmentation dimensions spanned product type, material grade tier, end-user safety requirements, and distribution channel format. CAGRs emerged from fitted trend lines applied to verified historical shipment data, with inputs from petrochemical price indices and international departure growth trajectories.
Revisions become necessary when REACH substance restrictions expand beyond current candidate lists, when California Proposition 65 enforcement patterns shift, or when metro-expansion timelines in India accelerate commuter-behavior changes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Global Sleepwear and Loungewear Market
Apparel & Footwear
South Africa Denim Jeans Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Asia-Pacific Lingerie Market
Apparel & Footwear
Erotic Lingerie Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Europe Second-Hand Apparel Market
Apparel & Footwear
Smart Wardrobe Market
Apparel & Footwear
Global Apparel Market
Apparel & Footwear
Apparel Dry Wash Spray Market
Apparel & Footwear
Children's Dresses and Skirts Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Sports Apparel Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
North America E-Commerce Apparel Market
Apparel & Footwear
Ballet Pointe Shoes Market