
 Kids Apparel Market | 2026-2036
Kids Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Apparel Market Outlook
Subscription-based sizing services for growing children is expanding how brands monetize repeat purchases. MMS Clothing leverages its manufacturing scale to serve private-label clients across North America. AEL Apparel specializes in custom-design programs that let boutique buyers configure small-batch collections. Thygesen Textile Vietnam anchors production for European retailers seeking REACH-compliant cut-and-sew capacity.
Kids apparel comprises garments engineered for body proportions from infancy through early adolescence, typically incorporating adjustable features such as elasticized waists, reinforced knees, and flame-resistant sleepwear per CPSC standards. The primary commercial purpose is to provide age-appropriate, safety-certified clothing that accommodates rapid growth cycles while meeting parental expectations for durability and wash performance. Outerwear commands premium positioning due to technical specifications around waterproof-breathable membranes and insulation ratings. Online retailers represent the fastest-expanding sales channel as direct-to-consumer logistics and virtual try-on tools reduce return rates. Cotton maintains volume leadership across material segments, though polyester blends gain share in performance-oriented sub-categories.
The US Consumer Product Safety Commission enforces flammability standards for children's sleepwear and drawstring limitations, while the EU's REACH regulation and OEKO-TEX certification constrain chemical inputs across export supply chains. These frameworks elevate compliance costs for smaller suppliers but create competitive barriers that favor vertically integrated manufacturers with in-house testing laboratories. Stakeholders must monitor evolving state-level extended producer responsibility proposals in California and New York that could mandate textile recycling infrastructure investments.
Market Dynamics
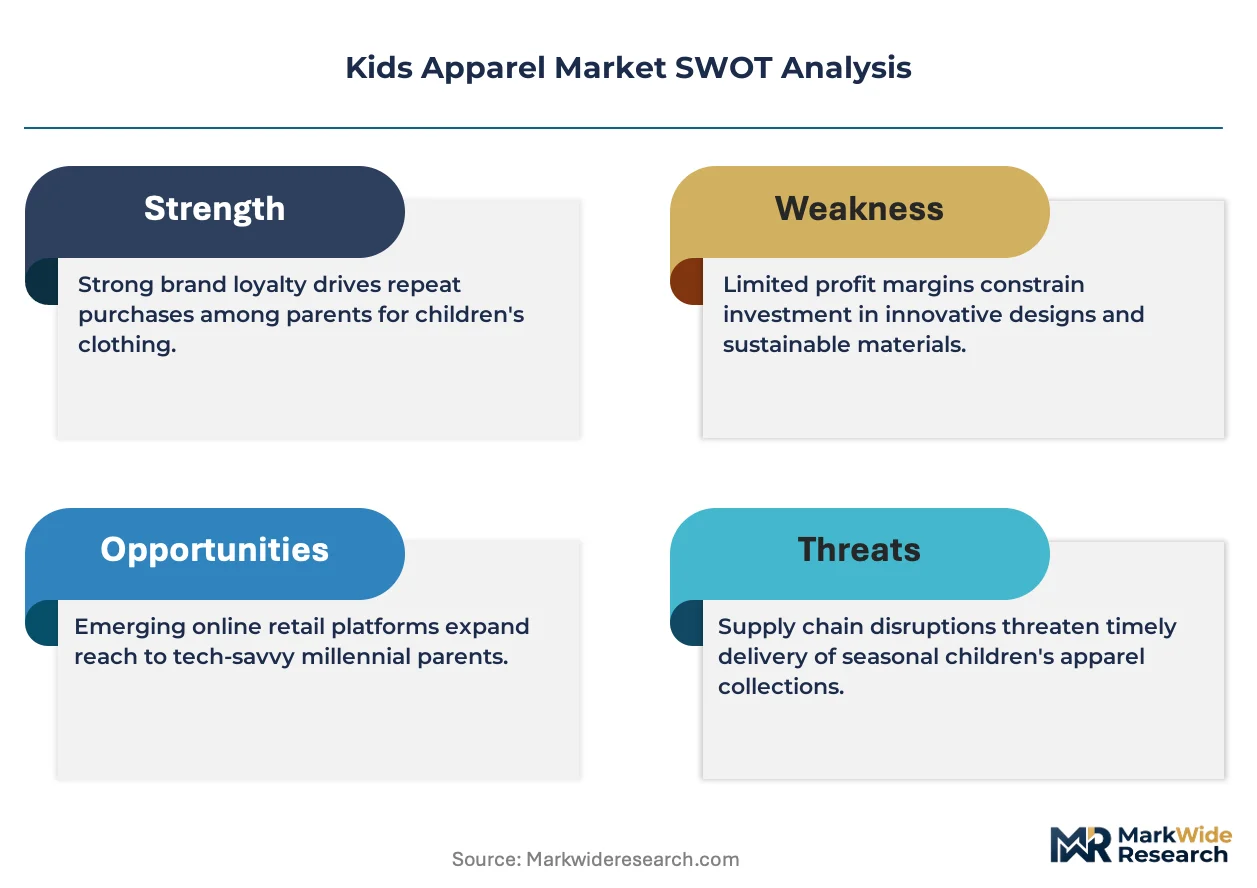
REACH chemical safety mandates are forcing textile reformulation across European supply chains, concentrating compliant production capacity in Vietnam's export-processing zones while fragmenting smaller suppliers unable to absorb testing costs.
Growth Catalysts
- Subscription sizing services:Automated replenishment models for rapidly growing children lock in recurring revenue streams and reduce customer acquisition costs for direct-to-consumer brands.
- REACH compliance clustering:European retailers are consolidating orders with Vietnamese contract manufacturers possessing in-house testing laboratories, accelerating volume migration to Ho Chi Minh City corridor facilities.
- Flame-resistant fiber innovation:Advanced inherent FR polymers eliminate chemical finish applications, streamlining CPSC sleepwear certification timelines for US market entry.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations in Texas and Maharashtra inflate raw material costs unpredictably, compressing margin structures for mid-tier private-label producers.
- Single-country production concentration:Vietnam's dominance in cut-and-sew capacity creates vulnerability to port congestion, labor disputes, or preferential trade agreement renegotiation.
- Drawstring limitation technical constraints:CPSC mechanical hazard standards restrict functional design options for adjustable waist systems in toddler outerwear categories.
Strategic Opportunities
- Extended producer responsibility tailwinds:California and New York state-level textile recycling mandates will create first-mover advantage for brands building reverse logistics infrastructure before federal harmonization.
- Virtual try-on convergence:AR sizing tools combined with AI growth prediction algorithms reduce return rates in online channels, unlocking working capital efficiency for direct-to-consumer operators.
- Performance polyester blend penetration:Moisture-wicking synthetic applications in activewear sub-categories remain underdeveloped for ages 8-14, presenting white space for technical fabric suppliers.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS multi-stage audit cycles delay seasonal collection launches, requiring earlier design finalization and reducing trend responsiveness.
- Legacy ERP integration friction:Size curve optimization algorithms demand data architecture upgrades that smaller contract manufacturers lack capital to implement, creating digital capability gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Apparel Market |
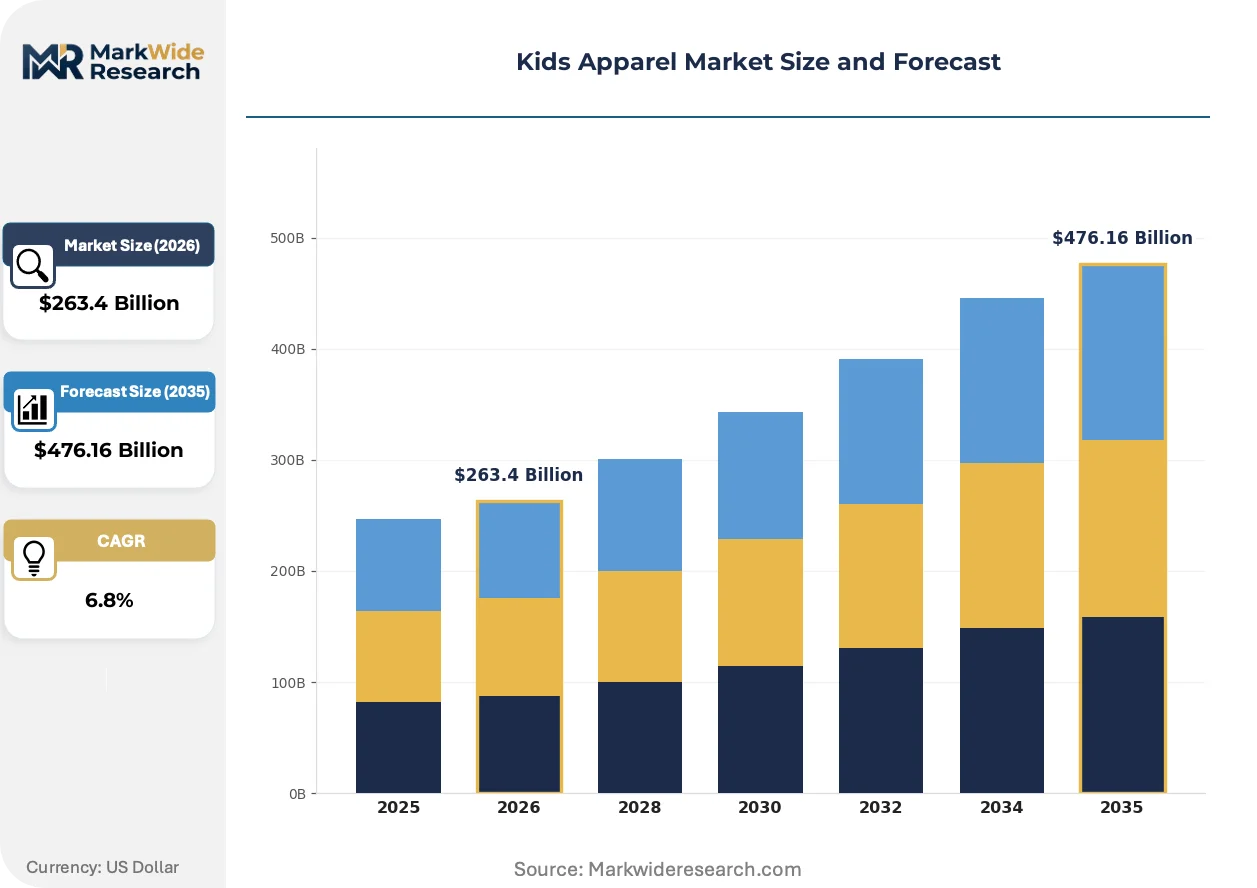
| Market Size in 2026 | $263.4 Billion |
| Market Size in 2035 | $476.16 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shirts, Pants, Dresses, Outerwear Age Group: Toddlers, Preschool, Early Teens, Tweens Material: Cotton, Polyester, Denim, Fleece Sales Channel: Online Retailers, Department Stores, Specialty Boutiques, Discount Stores |
| Companies Covered | MMS Clothing, AEL Apparel, LVMH, Steve Apparel, Thygesen Textile Vietnam, Fruit of the Loom, Hongyu Apparel, Penguin Kids Wear, Appareify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Apparel Market Strategic Shifts
Digital measurement tools and predictive sizing algorithms are compressing the traditional trial-and-error purchase cycle, while regulatory chemical restrictions accelerate material science investment.
Computer vision sizing systems capture 14 body measurements from smartphone cameras, enabling mass customization without physical fitting rooms. Direct-to-consumer brands targeting parents of toddlers are deploying these tools fastest, reducing return processing costs by eliminating fit uncertainty. This automation is automating the size-matching process that previously required multiple purchase attempts.
ECHA's REACH authorization list expansion now covers additional azo dyes and nickel-releasing fasteners, compelling reformulation of textile finishing chemistries. European import testing rejection rates for non-compliant shipments have risen, forcing suppliers to maintain dual inventory streams. Children's sleepwear and accessories with metal components face the steepest compliance cost increases.
Parents of infants are consolidating purchases through bundled subscription boxes rather than transactional seasonal buying, compressing traditional retail calendar cycles. Boutique retailers are losing traffic to algorithm-curated direct shipments that anticipate growth spurts. This pattern concentrates most visibly in urban US markets where two-income households prioritize convenience over tactile evaluation.
Kids Apparel Market Segmentation
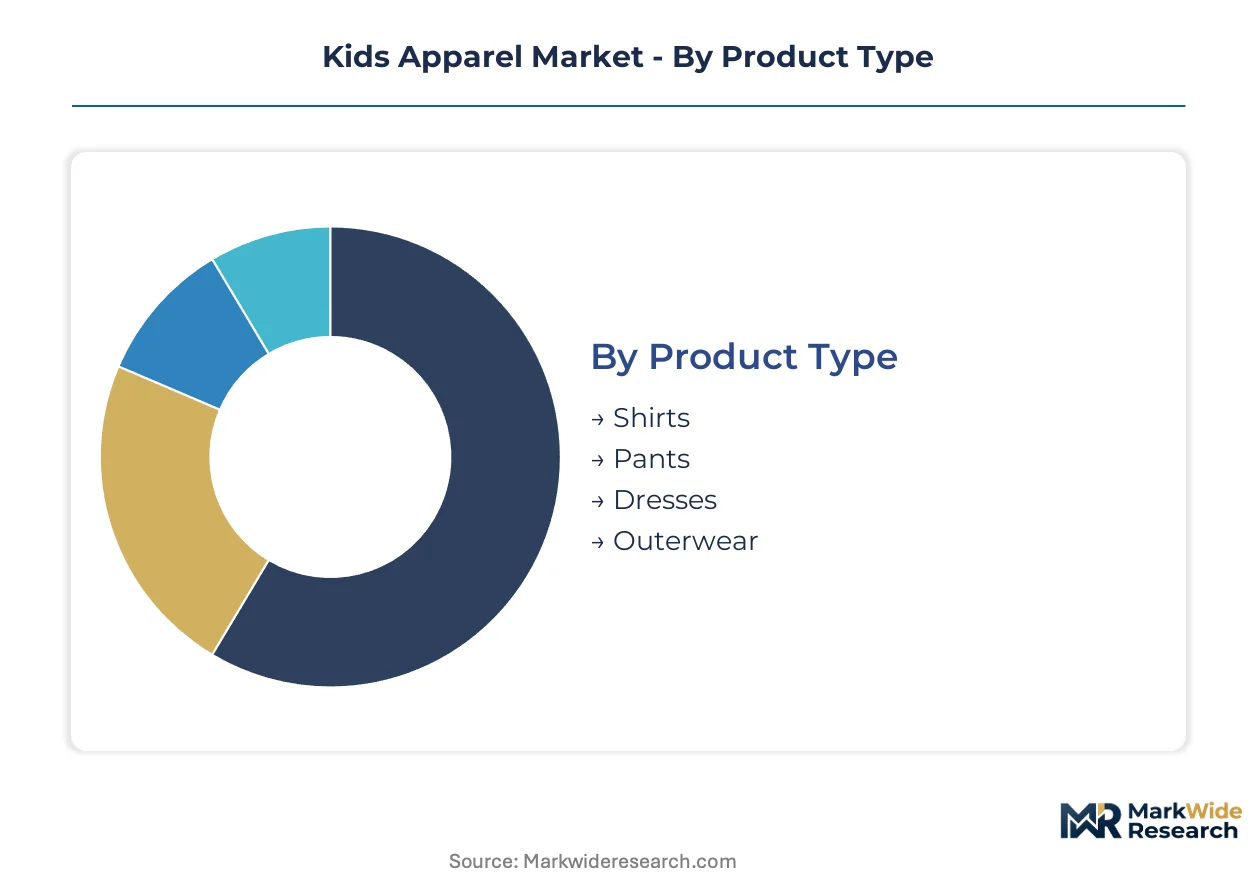
Segmentation in kids apparel determines compliance pathways, margin structures, and channel strategy. Safety certifications vary sharply across age brackets and product categories, reshaping supplier qualification requirements.
Product Type:
Flammability standards from the US CPSC and chemical restrictions under EU REACH create divergent certification burdens across garment categories, with sleep-adjacent products facing the steepest compliance costs.
- Shirts:Everyday knit and woven tops represent the highest-volume category, with OEKO-TEX Standard 100 certification now baseline for European import eligibility. Demand concentrates in basic cotton jersey for toddlers, where subscription services automate replenishment as children outgrow sizes.
- Outerwear:Technical specifications around waterproof-breathable membranes and insulation ratings elevate testing protocols. REACH compliance for DWR finishes and CPSC drawstring limitations restrict design options, concentrating production with Vietnamese manufacturers possessing in-house laboratories.
- Pants:Reinforced knee constructions and adjustable waist systems dominate functional requirements.
- Dresses:Seasonal fashion cycles drive shorter production runs with higher SKU fragmentation.
Leading the category by volume: Shirts. Expanding most quickly: Outerwear.
Age Group:
Size curve complexity and safety regulation intensity scale inversely with child age, with infant and toddler segments demanding the most specialized manufacturing capabilities.
- Toddlers:Rapid growth cycles compress wear time to 3-4 months per size, driving subscription model adoption. CPSC flammability standards for sleepwear and small-part choking hazard rules impose the strictest testing regimes, favoring vertically integrated suppliers with captive labs.
- Early Teens:Fashion consciousness converges with adult sizing standards, reducing safety-specific regulatory burden. Demand clusters in performance polyester blends for activewear, where moisture-wicking specifications from suppliers like AEL Apparel capture premium positioning.
- Preschool:Durability expectations peak as playground wear intensifies.
- Tweens:Brand identity formation drives discretionary spending patterns.
Dominating production volume: Toddlers. Steepest expansion trajectory: Early Teens.
Material:
Raw material selection determines chemical compliance pathways and end-use performance characteristics, with natural and synthetic fibers facing distinct regulatory scrutiny.
- Cotton:Volume leader across all age segments, with GOTS organic certification commanding 15-30% price premiums in European markets. Weather-driven supply volatility in Texas and Maharashtra inflates input costs unpredictably, squeezing mid-tier private-label margins.
- Polyester:Performance applications in activewear sub-categories gain share fastest, with recycled content mandates from EU Green Deal legislation accelerating material science investment. Inherent flame-resistant polymer variants streamline CPSC sleepwear certification for US market entry.
- Denim:Heavyweight construction favors durability positioning in outerwear and pants.
- Fleece:Synthetic pile constructions dominate cold-weather layering applications.
Highest volume position: Cotton. Gaining share fastest: Polyester.
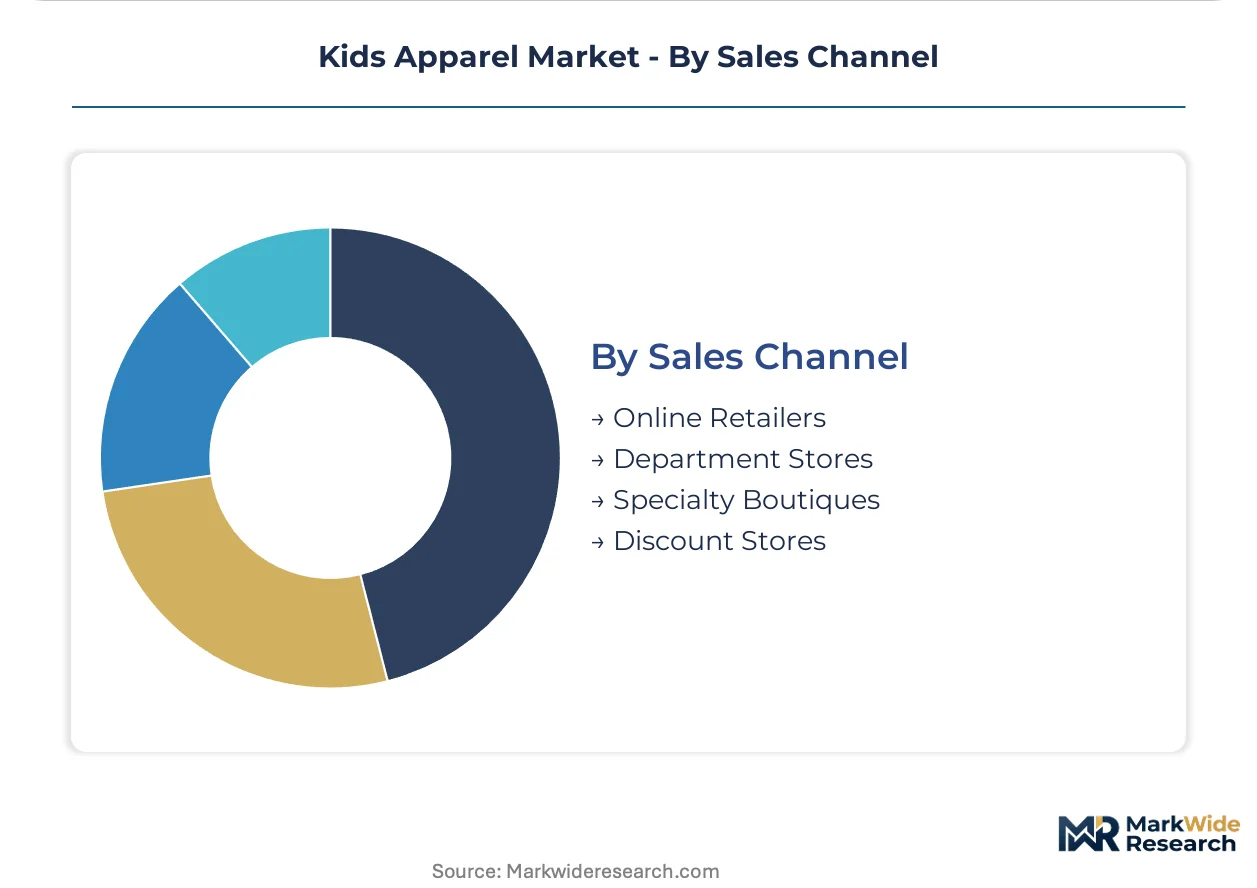
Sales Channel:
Channel selection shapes inventory risk, return rate exposure, and customer acquisition economics, with digital-native models rewriting traditional seasonal calendar structures.
- Online Retailers:Direct-to-consumer logistics and virtual try-on tools reduce return rates by eliminating fit uncertainty. Algorithm-curated subscription boxes for growing children compress traditional retail cycles, concentrating demand in urban US markets where convenience dominates tactile evaluation.
- Specialty Boutiques:Custom-design programs from contract manufacturers like AEL Apparel enable small-batch configuration with shorter lead times. Higher per-unit margins offset lower volume, though certification timeline compression from OEKO-TEX audits reduces trend responsiveness.
- Department Stores:Legacy inventory commitments face working capital pressure from faster digital competitors.
- Discount Stores:Price-driven positioning limits compliance investment capacity, creating regulatory vulnerability.
Climbing the fastest: Online Retailers. Highest margin structure: Specialty Boutiques.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Vietnamese export-processing zones while consumption clusters in North American and European markets with stringent safety frameworks. This geographic separation creates compliance-driven supply chain configurations.
United States
Parents of toddlers drive subscription service adoption as two-income households prioritize convenience over store visits. The US Consumer Product Safety Commission enforces flammability standards for children's sleepwear and mechanical hazard rules for drawstrings. New York and California state legislatures are advancing extended producer responsibility proposals that would mandate textile recycling infrastructure investments.
Vietnam
European retailers are consolidating orders with contract manufacturers around Ho Chi Minh City to secure REACH-compliant cut-and-sew capacity. The country's Ministry of Industry and Trade oversees export-processing zone operations where Thygesen Textile Vietnam anchors production for EU-bound shipments. In-house testing laboratories at major facilities reduce certification timeline compression for seasonal collection launches.
Germany
Organic cotton certification under GOTS commands 15-30% price premiums as safety-conscious purchasing intensifies among parents. The European Chemicals Agency administers REACH authorization list expansions covering azo dyes and nickel-releasing fasteners. Testing rejection rates for non-compliant textile shipments have risen, forcing suppliers to maintain dual inventory streams for German import eligibility.
China
Performance polyester blend applications for ages 8-14 activewear remain underdeveloped, presenting white space for technical fabric development. The Ministry of Ecology and Environment implements dual carbon goals that accelerate recycled content mandates in synthetic fiber production. Yangtze River Delta manufacturing clusters are investing in material science for inherent flame-resistant polymer variants.
India
Cotton price volatility in Maharashtra growing regions inflates raw material costs unpredictably for mid-tier private-label producers. The Bureau of Indian Standards oversees textile quality certifications while state-level industrial policies support apparel manufacturing clusters. Gujarat and Tamil Nadu production hubs are expanding GOTS-certified organic cotton processing capacity for European export markets.
Kids Apparel Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered market positions. Vertically integrated manufacturers with captive testing laboratories capture REACH-compliant orders from European retailers, while asset-light brands focus on direct-to-consumer subscription models and algorithm-curated sizing services. Three archetypes dominate: scale-driven contract manufacturers serving private-label clients, boutique specialists in custom-design programs, and vertically integrated exporters with in-house compliance infrastructure. Competitive moves center on geographic consolidation around Vietnamese production zones and technology licensing for virtual try-on tools.
Within the scale-driven contract manufacturing tier, MMS Clothing and Fruit of the Loom occupy positions serving high-volume private-label clients across North American retail channels. AEL Apparel exemplifies the boutique specialist archetype, anchoring custom-design capabilities for smaller buyers configuring small-batch collections. Thygesen Textile Vietnam represents vertically integrated export capacity, anchoring REACH-compliant production for European retailers from Ho Chi Minh City corridor facilities.
| Leading Market Players |
|---|
| MMS Clothing |
| AEL Apparel |
| LVMH |
| Steve Apparel |
| Thygesen Textile Vietnam |
| Fruit of the Loom |
| Hongyu Apparel |
| Penguin Kids Wear |
| Appareify |
| Others |
Value Chain & Pricing Dynamics
Cut-and-sew labor concentration in Vietnam's Ho Chi Minh City export-processing zones drives tiered pricing spreads across REACH-compliant and non-certified production tiers, with European retailers absorbing 15-30% premiums for captive laboratory testing while mid-tier private-label buyers face margin compression from cotton volatility in Maharashtra and Texas.
Pricing Analysis
Margin tightening in mid-tier private-label production reflects cotton price volatility from weather-driven supply fluctuations across Texas and Maharashtra growing regions. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic cotton from OEKO-TEX baseline compliance and uncertified commodity grades. Pricing pressure intensifies in toddler sleepwear categories as CPSC flammability testing costs concentrate with vertically integrated manufacturers. Boutique buyers show least price sensitivity for custom-design small-batch programs, while discount retailers face regulatory vulnerability from limited compliance investment capacity.
Supply Chain Analysis
Dual-sourcing requirements from European retailers mandate REACH-qualified capacity in Vietnam alongside backup qualification in India and Bangladesh. Raw material flows draw from Maharashtra cotton regions, Yangtze River Delta polyester synthesis clusters, and Gujarat GOTS-certified organic processing. Single-country production concentration in Vietnamese cut-and-sew creates vulnerability to port congestion or preferential trade agreement renegotiation. Distribution runs through direct-to-consumer subscription logistics, specialty boutique wholesale, and legacy department store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer vision sizing systems and AI growth prediction algorithms are displacing traditional trial-and-error purchase cycles, compressing return rates and rewriting inventory risk allocation between brands and contract manufacturers.
For Market Incumbents: Lock in REACH-compliant production capacity through exclusive arrangements with Vietnamese contract manufacturers possessing in-house testing laboratories. Deepen backward integration into GOTS-certified organic cotton processing in Gujarat to secure raw material cost stability against Maharashtra weather volatility. Defend against direct-to-consumer subscription entrants by deploying virtual try-on tools with algorithm-curated replenishment for toddler segments. For New Entrants and Emerging Players: The price-point gap between premium GOTS-certified positioning and economy-tier discount retail creates white space for mid-market REACH-compliant direct-to-consumer brands. Target performance polyester blend applications for ages 8-14 activewear sub-categories, where moisture-wicking specifications remain underdeveloped. Enter through subscription-based sizing services with automated replenishment models that reduce customer acquisition costs. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated Vietnamese manufacturers given EU Green Deal recycled content mandates and REACH authorization list expansions. Long-term viability centers on 5-10 year contracts with European retailers consolidating orders for compliant cut-and-sew capacity. Watch ECHA testing rejection rates for non-compliant shipments as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Infrastructure Investment | In-house testing laboratories at Vietnamese facilities reduce certification timeline compression for EU-bound collections. |
| Subscription Sizing Service Launch | Algorithm-curated replenishment models lock recurring revenue from parents of toddlers in urban US markets. |
| GOTS-Certified Organic Cotton Backward Integration | Captive processing capacity in Gujarat secures 15-30% price premiums in German import markets. |
| Performance Polyester Blend Development | Moisture-wicking synthetic applications for ages 8-14 activewear capture premium positioning from AEL Apparel. |
| Extended Producer Responsibility Infrastructure | Reverse logistics buildout in California and New York creates first-mover advantage before federal harmonization. |
Study Parameters
Multi-period observation of REACH authorization list expansions, CPSC flammability enforcement patterns, and subscription service adoption rates anchored the trend analysis, supplemented by interviews with brand managers at direct-to-consumer operators, category buyers at specialty boutiques, supply planners at contract manufacturers, and regulatory affairs leads at testing laboratories. Secondary validation drew from ECHA compliance databases, CPSC recall filings, customs records for Vietnam-EU textile shipments, and OEKO-TEX certification registries. Bottom-up order aggregation from Ho Chi Minh City export-processing zones and top-down consumption modeling across US, German, and Chinese markets enabled triangulation.
Segment-weighting across product type, age group, material composition, and sales channel dimensions structured the analytical framework across the analysis window. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated cotton futures volatility indices from Texas and Maharashtra exchanges, plus ECHA testing rejection rate trends for azo dye and nickel-releasing fastener violations.
Inputs from ECHA compliance disclosures, CPSC enforcement releases, and Vietnamese Ministry of Industry and Trade export statistics were available through the study window; gaps in real-time subscription churn metrics and proprietary algorithm performance data from virtual try-on providers introduce uncertainty bands around direct-to-consumer growth assumptions. Forecasts reflect documented assumptions regarding REACH authorization timeline acceleration and state-level extended producer responsibility implementation sequencing. A model refresh is warranted upon material change in EU Green Deal recycled content mandate enforcement or CPSC mechanical hazard standard revisions for drawstring limitations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO