
 China Culinary Tourism Market | 2026-2036
China Culinary Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
China Culinary Tourism Market Outlook
Mobile-first reservation infrastructure is reshaping how culinary experiences are discovered, booked, and delivered across Chinese destinations. Lost Plate Food Tours leverages hyperlocal vendor networks to sustain authentic street-food access in tier-two cities. China Culture Tour anchors its portfolio around UNESCO-recognized gastronomy heritage sites. Intrepid Travel competes through small-group formats that navigate seasonal ingredient availability.
China culinary tourism encompasses structured travel activities centered on regional food preparation, consumption, and cultural narrative, typically involving guided market visits, hands-on cooking instruction, and chef-hosted banquet experiences that transmit intangible cultural heritage. Food tours command the largest experience-type share due to low operational overhead and scalable logistics, while cooking classes capture premium pricing through limited group sizes and specialized equipment requirements. Online booking platforms within the service-type dimension are expanding fastest, reflecting consumer preference for real-time availability verification and peer-review integration.
SAMR enforces consumer protection standards for experience bookings, while MIIT governs data localization requirements for platform operators processing domestic traveler information. MEE environmental compliance shapes sustainable sourcing certifications that operators increasingly display to attract environmentally conscious visitors. Stakeholders must monitor evolving GB standards for food safety in experiential settings, as these will determine which vendors qualify for platform inclusion.
Market Dynamics
MIIT's digital infrastructure mandates are compressing booking friction to near-zero, while provincial heritage designation programs concentrate vendor eligibility in Sichuan and Guangdong. This dual pressure is restructuring how culinary experiences are curated, priced, and delivered across domestic and inbound channels.
Growth Catalysts
- Dual Carbon Goals:China's national decarbonization framework incentivizes low-carbon culinary tourism infrastructure, driving electric vehicle adoption for inter-provincial food tours and renewable energy integration in heritage kitchen restoration projects.
- UNESCO Gastronomy Recognition:Designation of Chengdu as a UNESCO City of Gastronomy anchors destination marketing, creating certified vendor pipelines that platform operators leverage for quality-assured inventory.
- Mobile Payment Infrastructure:Ubiquitous WeChat Pay and Alipay penetration eliminates foreign exchange friction for inbound food tourists, reducing booking abandonment rates on experience platforms.
Market Restraints
- Ingredient Cost Volatility:Sichuan peppercorn and aged Shaoxing wine prices fluctuate with climate-induced harvest variability, compressing margin buffers for cooking class operators dependent on authentic sourcing.
- Vendor Concentration Risk:Tier-one cities dominate certified heritage chef availability, forcing platform operators into exclusive contracting disputes for Guangdong dim sum masters and Sichuan hotpot specialists.
- GB Standards Compliance:Evolving national food safety standards for experiential settings create certification lag, disqualifying traditional market vendors from platform inclusion despite tourist demand.
Strategic Opportunities
- Tier-Two City Penetration:Xi'an and Changsha exhibit underdeveloped culinary tourism infrastructure relative to visitor growth, creating first-mover advantages for operators establishing hyperlocal vendor networks.
- Cross-Border E-Commerce Integration:Hainan Free Trade Port policies enable duty-free culinary product export post-experience, extending revenue capture beyond tour completion through packaged ingredient sales.
- AI-Enabled Personalization:Convergence of dietary preference algorithms and real-time inventory systems allows dynamic itinerary assembly, matching spice tolerance profiles with available chef-hosted experiences.
Industry Challenges
- Heritage Chef Talent Pipeline:Transmission of intangible culinary knowledge requires apprenticeship durations incompatible with platform scaling timelines, constraining authentic experience supply.
- Legacy System Integration:Family-run restaurants and market vendors operate on cash-based, offline reservation systems, creating data synchronization friction with platform booking engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Culinary Tourism Market |
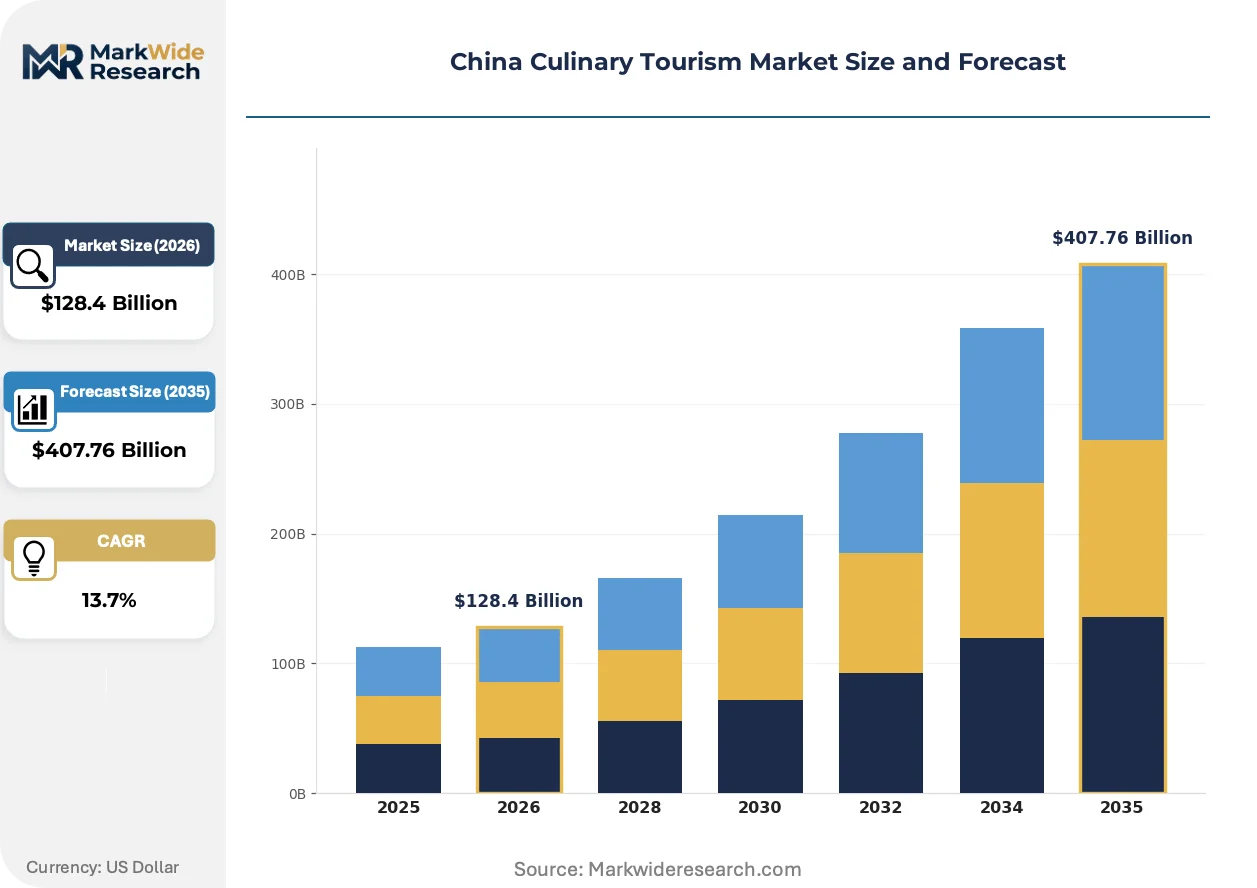
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $407.76 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Experience Type: Food Tours, Cooking Classes, Dining Experiences, Culinary Festivals Service Type: Guided Tours, Online Classes, Accommodation Packages, Local Experience Customer Type: Adventure Seekers, Food Enthusiasts, Cultural Travelers, Families Booking Channel: Travel Agencies, Online Platforms, Direct Booking, Social Media |
| Companies Covered | Intrepid Travel, Lost Plate Food Tours, China Culture Tour, On The Go Tours, Travel China Guide, China Highlights, China Odyssey Tours, China Discovery, UnTour Food Tours, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Culinary Tourism Market Strategic Shifts
Digital curation tools are displacing traditional travel agency intermediation in culinary experience discovery. Three convergent developments are restructuring how food tourists research, book, and consume gastronomic itineraries across Chinese destinations.
Immersive augmented reality is hybridizing pre-booking discovery with physical venue preview. Smartphone-based AR overlays display ingredient provenance and preparation techniques when users scan restaurant exteriors or market stalls. Young domestic tourists adopt these tools at accelerating rates, compressing decision cycles from days to hours and shifting discovery power from aggregators to direct venue engagement.
MEE environmental compliance protocols are reshaping sustainable sourcing certifications for platform-listed vendors. Operators must now display carbon footprint metrics and waste reduction credentials to maintain visibility in algorithmic rankings. Guangdong seafood experience providers face the steepest adaptation requirements, retrofitting supply chains to meet traceability standards that inbound European and North American tourists increasingly filter for.
Subscription-based culinary passport models are fragmenting traditional per-tour purchasing. Domestic travelers pre-commit to multi-destination food experiences through annual memberships, receiving priority access to limited-capacity chef-hosted events. This shift concentrates demand forecasting power with platform operators and compresses vendor negotiation leverage in Sichuan and Jiangsu provinces where membership penetration runs highest.
China Culinary Tourism Market Segmentation
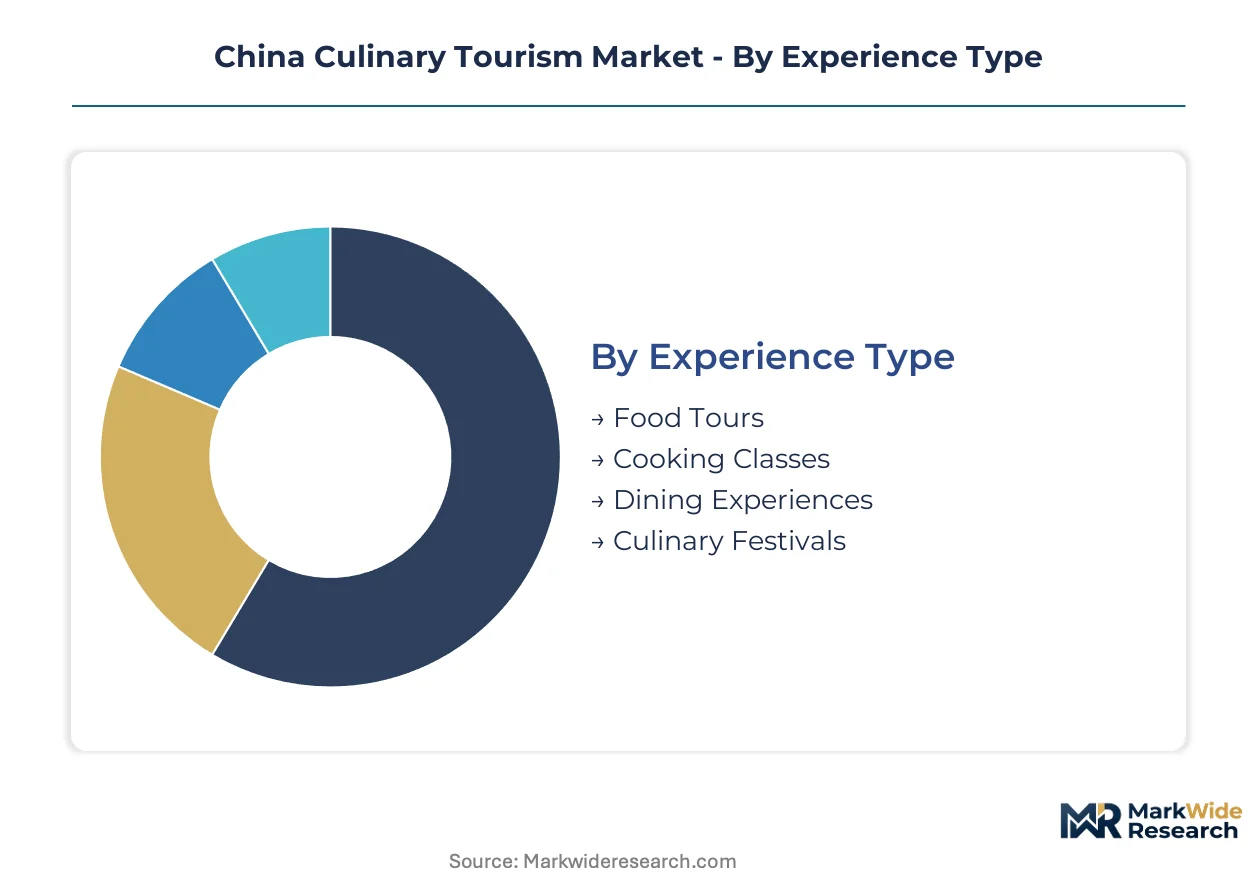
Experience formats and booking pathways in China culinary tourism exhibit divergent margin profiles and capital requirements. Understanding how demand fragments across these dimensions enables operators to align inventory investment with profitability targets.
Experience Type:
Application format determines operational complexity, asset intensity, and scalability ceiling for culinary tourism providers across Chinese destinations.
- Food Tours:Structured itineraries combining multiple vendor stops with narrative guidance from local experts. Demand concentrates in Chengdu and Guangzhou where UNESCO heritage designation validates vendor quality, though street-food access permits face tightening GB standards compliance windows.
- Cooking Classes:Hands-on instruction in specialized kitchen facilities requiring equipment investment and limited group capacity. Sichuan peppercorn sourcing volatility compresses margin buffers for operators dependent on authentic ingredient procurement.
- Dining Experiences:Chef-hosted banquets transmitting intangible cultural heritage through curated multi-course presentations.
- Culinary Festivals:Seasonal events aggregating regional vendors and competitive demonstrations around harvest calendars.
Food tours command the established base. The steepest expansion trajectory runs through cooking classes.
Service Type:
Delivery mechanism shapes customer acquisition cost, repeat purchase potential, and regulatory exposure for platform operators.
- Guided Tours:In-person facilitation requiring trained personnel and real-time logistics coordination. Tier-one cities dominate certified heritage chef availability, forcing exclusive contracting disputes for Guangdong dim sum masters.
- Online Classes:Virtual instruction eliminating geographic constraints and enabling ingredient kit distribution. Domestic travelers in Jiangsu province show accelerating adoption for pre-trip skill preparation.
- Accommodation Packages:Bundled lodging with integrated dining experiences and market access privileges.
- Local Experience:Unscripted vendor interactions with minimal platform intermediation and cash-based settlement.
Guided tours anchor current revenue. Online classes are gaining share fastest.
Customer Type:
Traveler motivation profiles dictate itinerary complexity, price sensitivity, and seasonal booking patterns across domestic and inbound channels.
- Adventure Seekers:Risk-tolerant travelers prioritizing novel sensory experiences and off-menu discoveries. Xi'an and Changsha exhibit underdeveloped infrastructure relative to this segment's visitor growth.
- Food Enthusiasts:Disciplined gastronomes researching provenance and technique with advance planning horizons. European and North American inbound tourists increasingly filter platform listings for MEE-compliant sustainable sourcing credentials.
- Cultural Travelers:Heritage-motivated visitors seeking narrative depth beyond consumption.
- Families:Multi-generational groups requiring safety assurances and dietary accommodation flexibility.
Food enthusiasts represent the established core. Adventure seekers show the steepest booking volume climb.
Booking Channel:
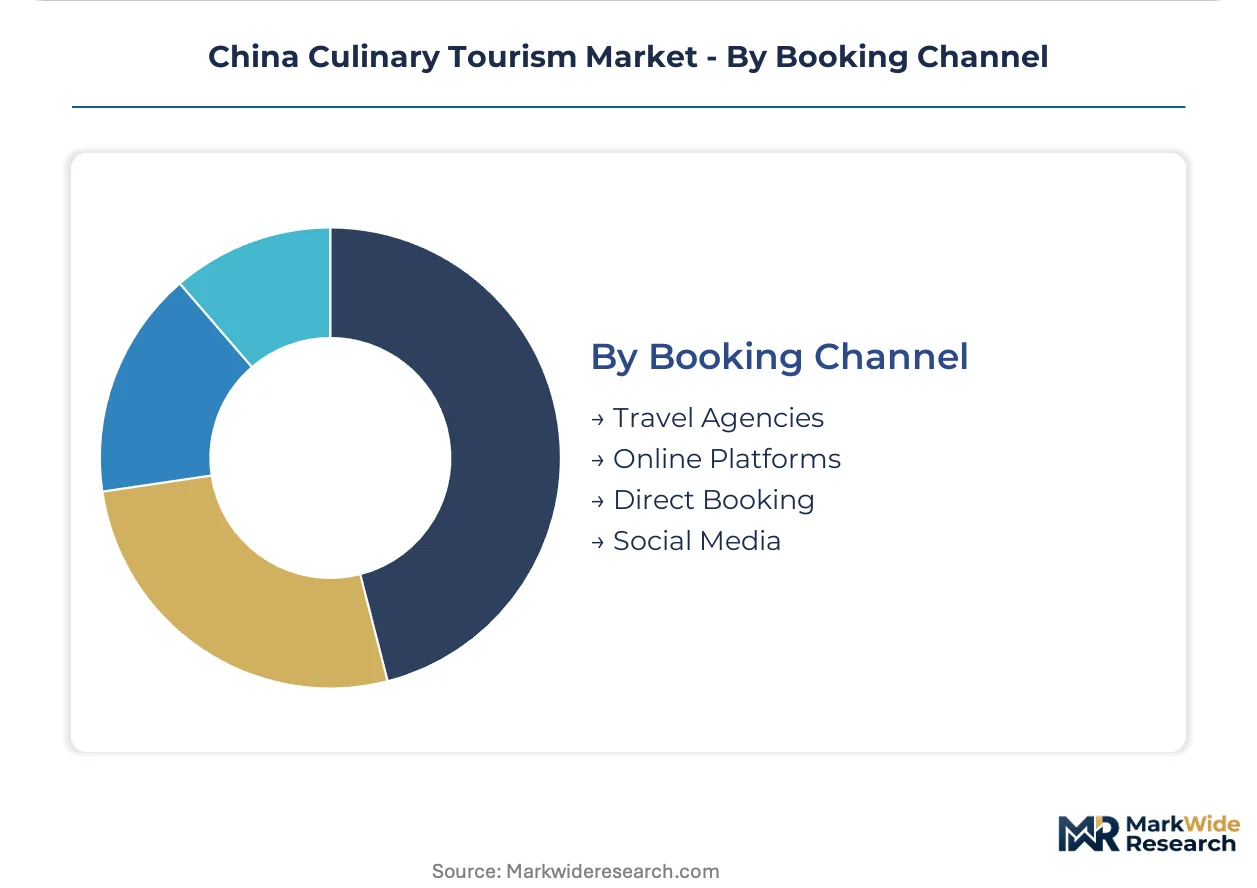
Customer acquisition pathway determines data sovereignty obligations, commission structures, and cancellation exposure under SAMR consumer protection standards.
- Travel Agencies:Traditional intermediation with established corporate relationships and package bundling capability. Legacy system integration friction persists with family-run restaurant cash-based reservation workflows.
- Online Platforms:Mobile-first booking engines with real-time availability verification and peer-review integration. MIIT data localization mandates govern domestic traveler information processing infrastructure.
- Direct Booking:Venue-controlled reservations bypassing platform commission but requiring independent marketing investment.
- Social Media:Discovery-to-transaction pathways through short-video content and influencer endorsement.
Travel agencies retain the established base. Online platforms show the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inbound culinary tourism flows concentrate along three domestic corridors: Sichuan and Guangdong provinces anchor heritage gastronomy demand, while Yangtze River Delta cities process the highest volume of mobile-first bookings. Provincial heritage designation programs create divergent vendor eligibility standards across these corridors.
Sichuan Province
Chengdu's UNESCO City of Gastronomy status drives certified vendor pipeline development for platform operators. MIIT digital infrastructure mandates accelerate mobile payment penetration in second-tier cities like Mianyang and Deyang. Sichuan peppercorn harvest volatility compresses margin buffers for cooking class operators dependent on authentic sourcing.
Guangdong Province
Guangzhou and Shenzhen dominate dim sum heritage chef availability, forcing exclusive contracting disputes among platform operators. MEE environmental compliance protocols reshape sustainable seafood sourcing certifications for experience providers. The Pearl River Delta cluster exhibits the steepest vendor concentration risk for certified Cantonese culinary masters.
Shaanxi Province
Xi'an exhibits underdeveloped culinary tourism infrastructure relative to adventure-seeker visitor growth. SAMR consumer protection standards govern experience booking platforms processing domestic traveler information. The ancient capital's street-food vendor networks face tightening GB standards compliance windows for platform inclusion.
Hunan Province
Changsha's influencer-driven food culture attracts domestic tourists seeking novel sensory experiences. Provincial heritage designation programs lag Sichuan and Guangdong in certified vendor pipeline development. The Xiang River corridor shows accelerating demand for spice-tolerance-matched chef-hosted experiences.
Hainan Province
Free Trade Port policies enable duty-free culinary product export post-experience, extending revenue capture beyond tour completion. SAMR data localization requirements govern platform operators processing domestic traveler information. Sanya and Haikou concentrate inbound resort-based dining experience demand.
China Culinary Tourism Market Competitive Environment
On the supply side, the industry is fragmented across hyperlocal vendor networks, heritage chef aggregators, and mobile-first platform operators. Strategic archetypes include UNESCO heritage site specialists, tier-two city penetration specialists, and AI-enabled personalization platforms. Dominant competitive moves encompass exclusive chef contracting and cross-border e-commerce integration for ingredient sales.
Within the heritage-specialist tier, China Culture Tour exemplifies UNESCO gastronomy site anchoring, while Lost Plate Food Tours occupies a position representing hyperlocal vendor network development in underserved cities. Intrepid Travel sits within the small-group format archetype navigating seasonal ingredient availability. These three players represent divergent approaches to authentic experience supply constraints.
| Leading Market Players |
|---|
| Intrepid Travel |
| Lost Plate Food Tours |
| China Culture Tour |
| On The Go Tours |
| Travel China Guide |
| China Highlights |
| China Odyssey Tours |
| China Discovery |
| UnTour Food Tours |
| Others |
Value Chain & Pricing Dynamics
Undercapacity among certified heritage chefs in Guangdong and Sichuan provinces drives premium pricing for authentic dim sum and hotpot experiences while forcing platform operators into exclusive contracting races that compress margin buffers for mid-tier competitors.
Pricing Analysis
Legacy guided-tour pricing faces compression from AI-enabled dynamic pricing systems that match spice-tolerance profiles with real-time chef availability. Three-tier pricing structure across premium, standard, and economy levels separates UNESCO-certified heritage banquets from street-food circuits and unscripted local experiences. Price differentiation hinges on GB standards compliance certification and exclusive vendor access rights. Pricing pressure stems from ingredient cost volatility in Sichuan peppercorn and aged Shaoxing wine markets. Adventure seekers exhibit highest price sensitivity, while food enthusiasts accept premium positioning for provenance-verified sourcing.
Supply Chain Analysis
Vendor concentration risk between Chengdu and Guangzhou dominates supply chain vulnerability for platform operators seeking certified heritage chef coverage. Geographic supply concentration centers on Sichuan, Guangdong, and Jiangsu provinces for authentic ingredient sourcing and master chef availability. Raw material dependencies rest on seasonal harvest calendars for Sichuan peppercorn, Yangtze River Delta freshwater produce, and South China Sea seafood traceability systems. Tariff exposure through Hainan Free Trade Port duty-free channels creates regulatory complexity for cross-border ingredient export post-experience. Distribution runs through mobile-first booking engines with MIIT-mandated data localization for domestic traveler information processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SAMR consumer protection standards and evolving GB food safety certifications create vendor eligibility barriers that incumbent platforms exploit to lock out unqualified competitors.
For Market Incumbents: Build exclusive chef contracting moats through multi-year apprenticeship pipeline investments that outpace platform scaling timelines. Secure backward integration into heritage kitchen restoration projects eligible for dual carbon goal subsidies. Defend against AI-enabled personalization entrants by controlling real-time inventory data flows from legacy vendor networks. Prioritize MEE environmental compliance certification as a vendor exclusion mechanism. For New Entrants and Emerging Players: Establish beachhead positions in Xi'an and Changsha where culinary tourism infrastructure lags visitor growth and certified vendor pipelines remain underdeveloped. Target adventure seeker segments with spice-tolerance-matched experience curation that incumbent platforms address poorly. Penetrate through subscription-based culinary passport models that concentrate demand forecasting power and compress vendor negotiation leverage for established competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform operators with membership-based culinary passport penetration in Sichuan and Jiangsu provinces. Long-term viability favors acquirers of hyperlocal vendor network specialists with exclusive tier-two city coverage rather than heritage site generalists facing chef talent pipeline constraints. Watch for MIIT digital infrastructure mandate acceleration as signal for mobile-first booking platform consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Heritage Chef Contracting | Locks in scarce UNESCO-certified talent pipelines against platform competitors in Chengdu and Guangzhou. |
| AI-Enabled Personalization Investment | Matches dietary preference algorithms with real-time inventory for dynamic itinerary assembly. |
| Cross-Border E-Commerce Integration | Leverages Hainan Free Trade Port policies for duty-free ingredient export revenue extension. |
| MEE Compliance Certification Program | Displays carbon footprint credentials that European and North American tourists filter for. |
| Tier-Two City Vendor Network Expansion | Captures first-mover advantage in Xi'an and Changsha before infrastructure catches visitor growth. |
Study Parameters
A standing panel of culinary tour operators, heritage chef aggregators, platform product managers, and SAMR regulatory specialists provided ongoing calibration against operating reality throughout the analysis window. Primary interviews with these stakeholders combined with secondary validation against MIIT policy filings, GB standards documentation, UNESCO gastronomy designation records, and provincial tourism bureau statistics. Bottom-up vendor network sizing and top-down mobile booking transaction estimates were triangulated for convergence.
Scenario-bracketing framed low, base, and high cases around MIIT digital infrastructure penetration speed, heritage chef apprenticeship graduation rates, and cross-border e-commerce policy expansion. Segmentation dimensions modeled encompass experience type, service delivery mechanism, customer motivation profile, and booking channel preference across the projection horizon. CAGRs were derived from trend extrapolation of mobile-first adoption curves and membership-based culinary passport penetration patterns.
Sensitivities concentrate around GB standards enforcement intensity, Sichuan peppercorn harvest variability, and Hainan Free Trade Port duty-free category expansion decisions. Forecasts reflect documented assumptions regarding regulatory implementation timelines and consumer preference evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Japan Faith-Based Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
Industrial Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Europe Theme Park Market
Destination Management and Attractions
Geotourism Market
Destination Management and Attractions
Desert Island Tourism Market