
 Film Tourism Market | 2026-2036
Film Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Film Tourism Market Foresight
Solo travelers is bifurcating from group package tourists as the primary growth archetype in film tourism, with individual booking platforms capturing disproportionate itinerary spend. Warner Bros. Studio Tour leverages its controlled backlot environments to sustain premium pricing in Los Angeles and London. Universal Studios Hollywood anchors its competitive position through integrated production facility access, while Viator competes by aggregating third-party location experiences across fragmented supplier markets. Netflix differentiates through direct destination marketing embedded in original content release cycles.
Film tourism encompasses travel motivated by on-screen location exposure, encompassing guided site visits, production facility access, and narrative-themed hospitality services typically structured around audiovisual intellectual property. The experience type dimension spans location tours, themed attractions, film festivals, and guided experiences, with location tours occupying the deepest margin pools due to low fixed-asset requirements and high repeat visitation potential. The tourist type segmentation captures families, couples, solo travelers, and fan groups, where fan groups register the highest per-trip spend intensity through premium access purchases and merchandise attachment.
The U.S. Office of Travel and Tourism Industries coordinates with state film commissions to standardize location promotion protocols, while the EU's Audiovisual Media Services Directive shapes cross-border content tourism marketing disclosures. New Zealand's Screen Production Grant framework directly links fiscal production incentives to post-release destination marketing obligations. Stakeholders must monitor how streaming platform content licensing terms increasingly encode location promotion responsibilities that reshape destination marketing organization revenue models.
Market Dynamics
Streaming platform content licensing agreements now encode location promotion obligations that restructure how destinations monetize screen exposure, forcing tourism boards to renegotiate revenue-sharing models with production entities.
Growth Catalysts
- Production Incentive Frameworks:New Zealand's Screen Production Grant mandates post-release destination marketing, creating self-funding tourism pipelines that reduce public marketing expenditure.
- Self-Directed Itinerary Tools:Mobile booking platforms enable solo travelers to construct personalized location tours without intermediary markup, expanding addressable market depth.
- EU Audiovisual Media Services Directive:Cross-border content tourism disclosure requirements standardize location promotion protocols across member states, reducing regulatory fragmentation for multi-territory releases.
Market Restraints
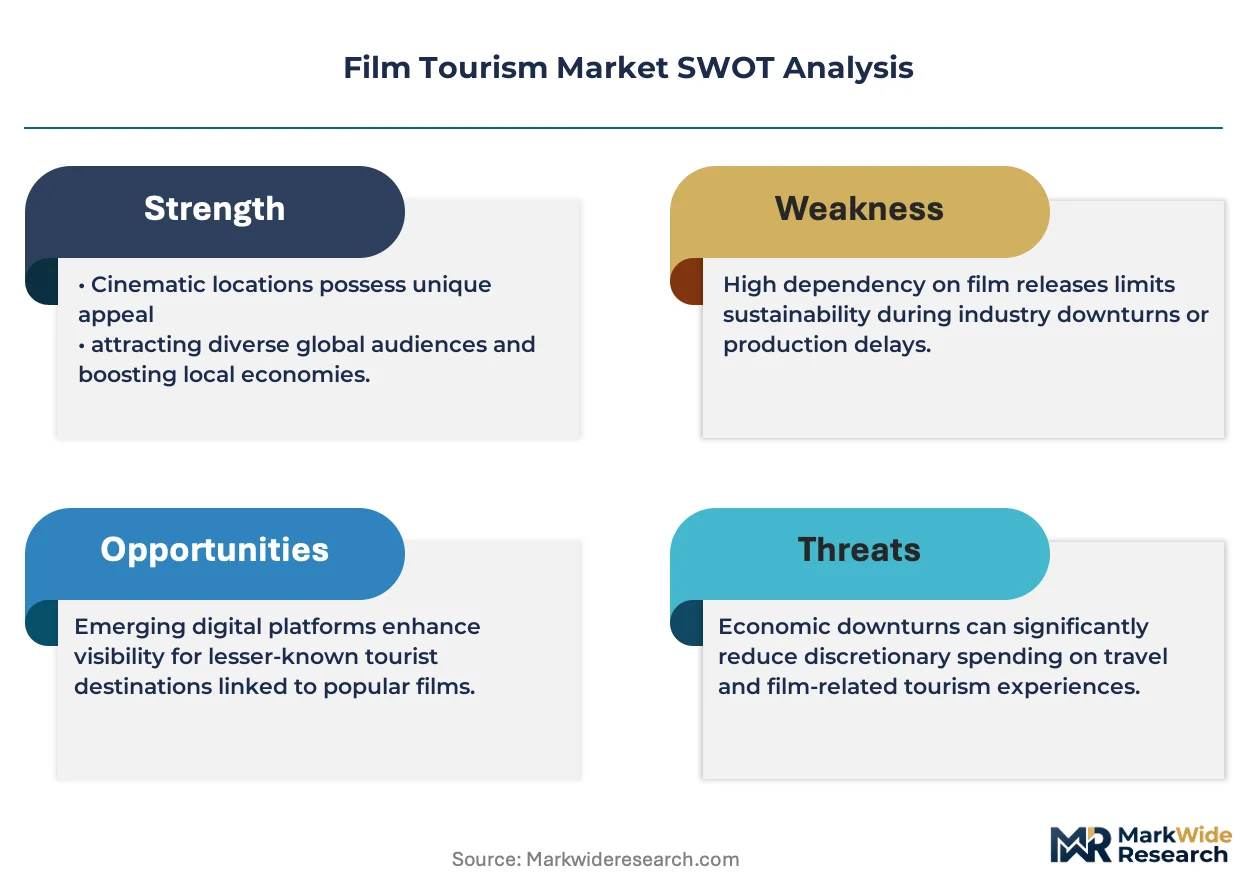
- Location Access Volatility:Private landowners in high-demand filming regions impose unpredictable access fees that compress operator margins during peak visitation windows.
- Seasonal Concentration Risk:Northern hemisphere destinations face demand collapse during winter months when outdoor location accessibility deteriorates.
- Substitution by Virtual Production:LED volume stage technology enables in-studio location replication, reducing authentic site dependency for future productions.
Strategic Opportunities
- Secondary Location Exploitation:Eastern European filming clusters in Croatia and Hungary remain underdeveloped for tourism conversion despite established production infrastructure.
- Extended Reality Convergence:Augmented reality layering onto physical locations creates premium experience tiers that command higher per-visitor yield.
- Fan Group Service Unbundling:Dedicated premium access packages for narrative-committed visitors capture merchandise and repeat visitation revenue streams separate from general tourism.
Industry Challenges
- Location Stewardship Skill Gap:Site managers lack training in simultaneous production and public access coordination, generating visitor safety incidents.
- IP Licensing Complexity:Studio property rights fragmentation across multiple holding entities delays experience authorization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Film Tourism Market |
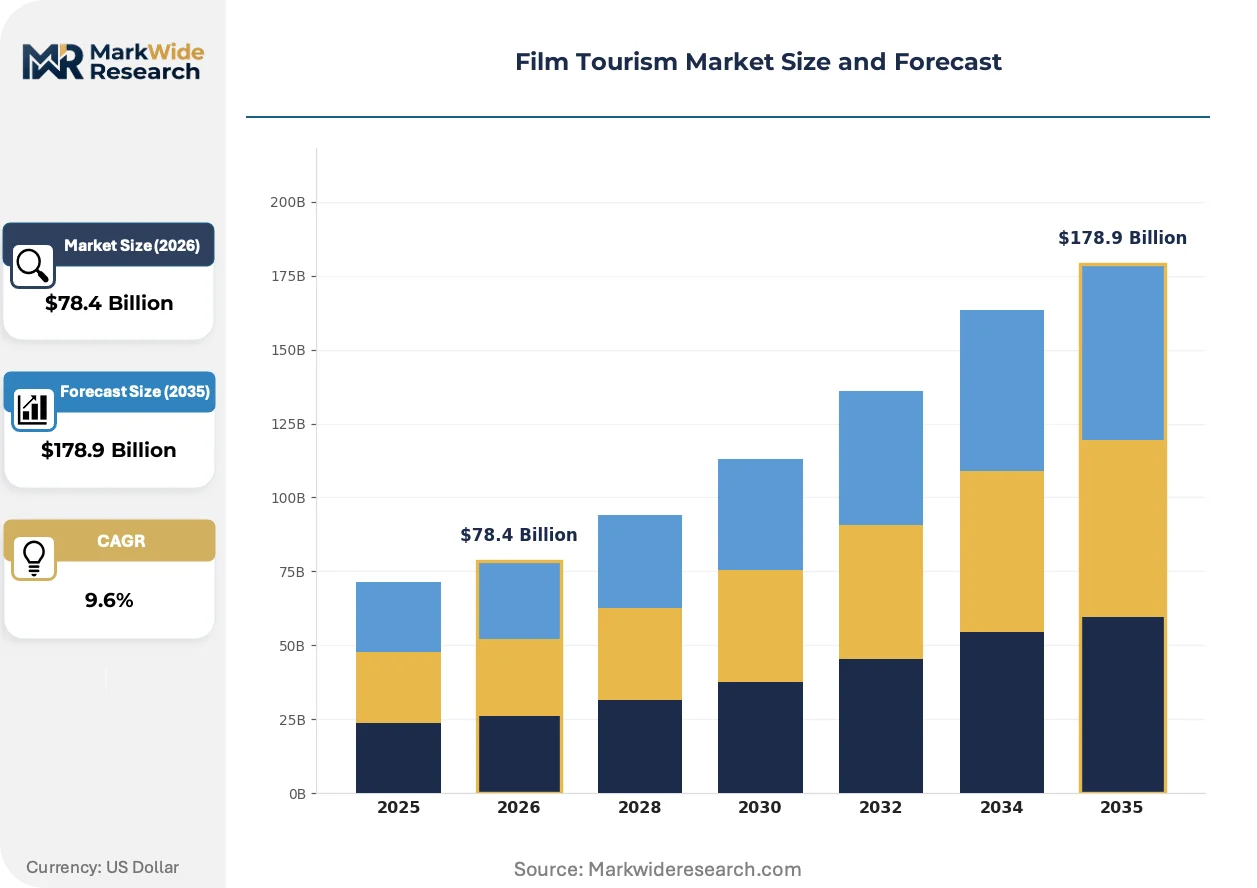
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Market Type: International, Domestic, Regional, Local Tourist Type: Families, Couples, Solo Travelers, Fan Groups Film Genre: Action, Drama, Comedy, Documentary Experience Type: Location Tours, Themed Attractions, Film Festivals, Guided Experiences |
| Companies Covered | Warner Bros. Studio Tour, Universal Studios Hollywood, Viator, GetYourGuide, New Zealand Film Tours, Netflix, Disney, Klook, TUI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Film Tourism Market Shifts & Advancements
Location-based experience design is pivoting from passive site visitation toward interactive narrative immersion, with technology and regulatory frameworks converging to enable new monetization architectures.
Augmented reality location layering is miniaturizing hardware requirements for on-site deployment, enabling independent operators to overlay digital narrative elements without studio infrastructure investment. Regional tourism boards in Scotland and Iceland are piloting smartphone-native AR layers at Outlander and Game of Thrones locations. This capability is compressing the capital barrier between third-party tour operators and studio-controlled premium experiences.
EU Audiovisual Media Services Directive disclosure mandates are requiring streaming platforms to flag filming locations in end credits, creating standardized discovery mechanisms that reduce destination marketing expenditure. National regulators in France and Germany are enforcing compliance through national media authorities. Location data standardization is forcing tourism organizations to restructure digital asset management systems.
Visitor purchasing patterns are fragmenting across direct studio channel and third-party aggregator platforms, with solo travelers prioritizing instantaneous mobile booking over packaged itinerary construction. Fan groups maintain preference for direct studio access purchases. This bifurcation is most visible in New Zealand and the United Kingdom where platform penetration diverges sharply by visitor archetype.
Film Tourism Market Segmentation
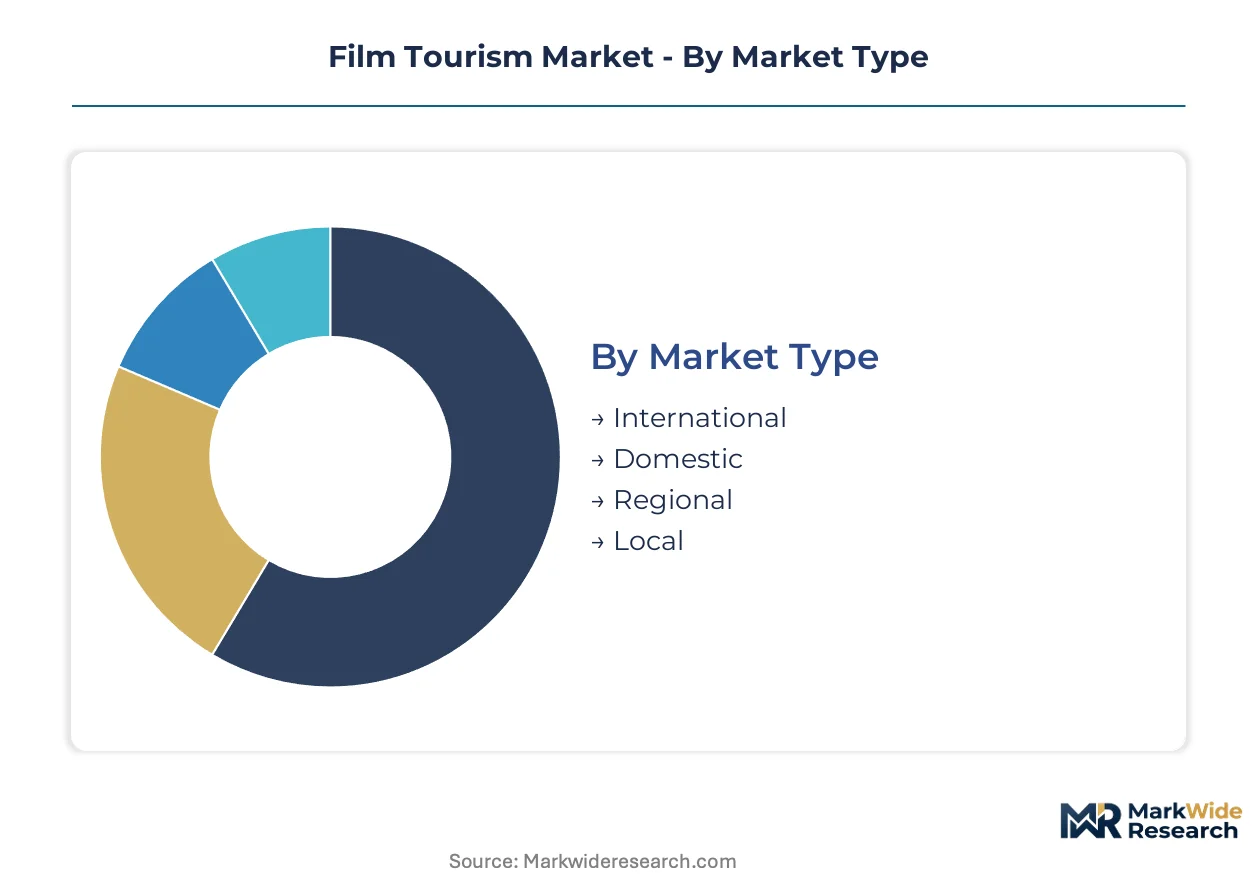
Film tourism operators structure inventory and pricing around distinct visitor archetypes and experience formats. Segment boundaries determine margin capture potential, repeat visitation rates, and partnership requirements with production entities.
Market Type:
International itineraries dominate revenue concentration while domestic circuits sustain volume foundations across production-heavy territories.
- International:Cross-border visitors motivated by flagship productions command premium accommodation spend and extended length of stay. New Zealand's Screen Production Grant-linked marketing funnels inbound visitors from North American and Asian source markets through coordinated airline and hospitality partnerships.
- Domestic:Residents visiting nearby filming locations generate higher frequency but lower per-trip yield, with repeat visitation concentrated around episodic content releases. United States domestic circuits leverage regional film commission coordination to sustain year-round occupancy.
- Regional:Neighboring country visitors within customs unions or visa-free zones reduce booking friction and currency conversion costs. European regional circuits benefit from EU Audiovisual Media Services Directive location disclosure standardization.
- Local:Same-city or same-state visitors seeking day-trip experiences without overnight stays. Local demand concentrates around studio backlot tours and metropolitan production facilities.
International visitors command the established base. The steepest expansion runs through domestic circuits as streaming content normalizes location awareness.
Tourist Type:
Group composition dictates experience packaging requirements, with solitary and affinity-based travelers diverging sharply on booking channel preferences.
- Families:Multi-generational units prioritize safety-certified attractions with educational components and reduced physical intensity. Studio-controlled environments in Los Angeles and London capture disproportionate family spend through controlled backlot access.
- Couples:Paired visitors seeking romantic narrative associations drive boutique hospitality demand at countryside filming locations. Couple-oriented packages in Scotland and Iceland leverage dramatic landscape backdrops from fantasy and historical productions.
- Solo Travelers:Self-directed individuals utilizing mobile itinerary tools to construct personalized location sequences without intermediary markup. Solo archetypes are expanding most quickly as booking platform personalization matures.
- Fan Groups:Narrative-committed collectives purchasing premium access, merchandise bundles, and repeat visitation packages. Fan groups register the highest per-trip spend intensity through direct studio channel purchases.
Fan groups anchor premium revenue extraction. Solo travelers are gaining share fastest as platform infrastructure reduces package dependency.
Film Genre:
Genre classification shapes location durability and seasonal visitation patterns, with spectacle-driven categories sustaining longer tourism lifecycles.
- Action:High-production-value spectacles featuring recognizable set pieces and stunt sequences. Action locations in New Zealand and Croatia benefit from extended marketing windows through franchise continuity.
- Drama:Character-driven narratives generating intimate location associations and repeat viewing motivation. Drama filming sites in the United Kingdom sustain visitation through period authenticity and literary adaptation heritage.
- Comedy:Lighter tonal content with location recognition decaying faster post-release. Comedy locations concentrate in urban clusters with existing tourism infrastructure.
- Documentary:Factual productions generating educational tourism demand with lower merchandise attachment. Documentary circuits in Iceland and Norway leverage environmental and wildlife narratives.
Action productions deliver the most durable location equity. Documentary formats are climbing the fastest as environmental awareness reshapes travel motivation.
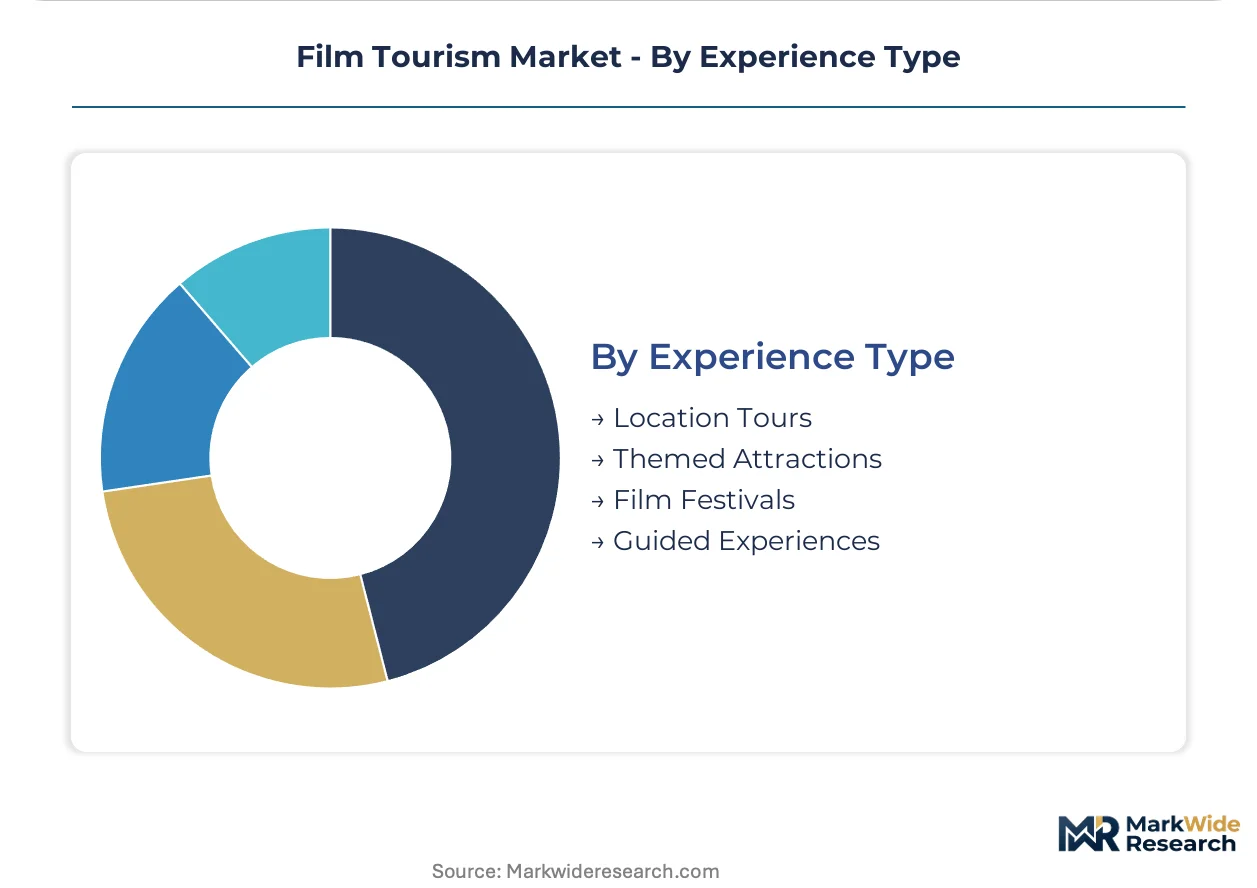
Experience Type:
Format selection determines fixed asset requirements and margin structure, with low-inventory models outperforming capital-intensive alternatives.
- Location Tours:Third-party operators guiding visitors to exterior filming sites without studio infrastructure investment. Location tours occupy the deepest margin pools due to minimal fixed-asset requirements and scalable group sizing.
- Themed Attractions:Purpose-built environments replicating narrative settings with full IP licensing and controlled experience design. Warner Bros. Studio Tour and Universal Studios Hollywood anchor this segment through integrated production facility access.
- Film Festivals:Time-concentrated events generating accommodation and hospitality surge demand. Cannes and Toronto festivals sustain destination marketing through media coverage amplification.
- Guided Experiences:Narrative-layered itineraries combining multiple location types with expert interpretation. Viator aggregates third-party guided offerings across fragmented supplier markets.
Location tours define volume leadership. Themed attractions are expanding most quickly as studios deepen direct-to-visitor channel investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand exports film tourism experiences primarily to North American and Asian source markets through coordinated airline and hospitality partnerships. The United Kingdom channels inbound visitors from European neighboring countries and long-haul markets into Scotland and England filming circuits. Croatia and Hungary attract production activity but lag in tourism infrastructure conversion despite established studio facilities.
United States
Studio backlot tours in Los Angeles and Orlando drive premium revenue through controlled production facility access. The U.S. Office of Travel and Tourism Industries coordinates with state film commissions to standardize location promotion protocols. California's Los Angeles County anchors studio-controlled experience design through integrated production and visitor access infrastructure.
United Kingdom
Period drama filming locations in Scotland and England sustain visitation through literary adaptation heritage and fantasy franchise associations. The EU Audiovisual Media Services Directive shapes cross-border content tourism marketing disclosures applicable to UK-EU content flows. Scotland's Highlands cluster captures couple-oriented boutique hospitality demand at countryside filming sites.
New Zealand
Franchise continuity from flagship productions generates extended marketing windows for action and fantasy location tours. The Screen Production Grant framework mandates post-release destination marketing obligations linked to fiscal production incentives. Wellington and Auckland metropolitan areas concentrate production infrastructure with direct tourism conversion pipelines.
Croatia
Established production infrastructure in Dubrovnik and Split generates location recognition without corresponding tourism yield capture. The country's national tourism board coordinates with regional film offices to develop secondary location exploitation strategies. Dalmatian coastal clusters remain underdeveloped for tourism conversion despite Game of Thrones production heritage.
Iceland
Environmental and wildlife documentary narratives drive educational tourism demand with lower merchandise attachment than studio-controlled alternatives. The country's national media regulator enforces location disclosure requirements aligned with EU Audiovisual Media Services Directive standards. Reykjavik and southern region filming sites concentrate augmented reality pilot programs for narrative layering.
Film Tourism Market Competitive Landscape
Listed entertainment conglomerates compete with private tour operators across experience format control and pricing power. The vendor base structures around studio-controlled environments, third-party aggregators, and destination-specialized providers. Three archetypes dominate: integrated production-entertainment entities, digital booking platforms, and regional tour specialists. Consolidation pressures concentrate on aggregator-platform partnerships and exclusive location access agreements.
Within the integrated production-entertainment tier, Warner Bros. Studio Tour and Universal Studios Hollywood exemplify controlled backlot environment models that sustain premium pricing through exclusive facility access. Among digital booking platforms, Viator occupies a position representing third-party aggregation across fragmented supplier markets. These three entities anchor competitive positioning through divergent asset-light versus asset-heavy strategies.
| Leading Market Players |
|---|
| Warner Bros. Studio Tour |
| Universal Studios Hollywood |
| Viator |
| GetYourGuide |
| New Zealand Film Tours |
| Netflix |
| Disney |
| Klook |
| TUI Group |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements between streaming platforms and destination marketing organizations lock in multi-year location promotion commitments while fixing per-visitor yield benchmarks across New Zealand, the United Kingdom, and Iceland. These contractual structures tether production incentive disbursements to post-release tourism conversion obligations, creating visibility into revenue-sharing terms that standardize third-party operator margins.
Pricing Analysis
Next-generation augmented reality layering commands premium positioning over legacy guided tour formats, with hardware miniaturization compressing deployment costs for independent operators. Three-tier pricing structure across premium, standard, and economy levels separates studio-controlled backlot access from third-party location tours and self-directed mobile itineraries. Cost compression in the economy tier stems from platform aggregation reducing intermediary markups for solo travelers. Fan groups exhibit lowest price sensitivity through direct studio channel purchases, while domestic day-trippers drive volume at compressed yields.
Supply Chain Analysis
Private landowner access negotiations in Dubrovnik, Split, and the Scottish Highlands constitute the primary chokepoint constraining third-party tour operator inventory expansion. Production infrastructure concentrates in New Zealand, the United Kingdom, and Croatia, with location recognition assets drawing from studio IP licensing, government film office coordination, and streaming platform disclosure mandates. Single-source vulnerability runs through exclusive facility access agreements held by Warner Bros. Studio Tour and Universal Studios Hollywood. Distribution runs through direct studio channels, mobile booking platforms, and regional tourism board partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among streaming platforms as licensing agreements consolidate location promotion obligations, fragmenting revenue capture for destination marketing organizations and third-party operators.
For Market Incumbents: Compound exclusive facility access through backward integration into production infrastructure, securing multi-year location lock-ups in New Zealand and the United Kingdom before LED volume stage technology displaces authentic site dependency. Expand direct-to-visitor channel investment to capture fan group premium spend that platform aggregators cannot replicate. Defend margin position by embedding augmented reality capabilities in-house rather than licensing from third-party technology vendors. For New Entrants and Emerging Players: Anchor in secondary location exploitation across Croatia and Hungary, where established production infrastructure lacks corresponding tourism yield capture. Target underdeveloped Dalmatian coastal clusters and Budapest metropolitan filming sites with smartphone-native AR overlay services that bypass studio infrastructure requirements. Pursue white-label partnerships with regional tourism boards seeking location disclosure compliance under EU Audiovisual Media Services Directive mandates. For Investors and Strategic Acquirers: Regional tour specialists with exclusive landowner agreements in high-recognition filming territories present acquisition targets with defensible inventory positions. Long-term viability hinges on conversion rate durability as streaming content release cycles compress location awareness half-lives. Monitor LED volume stage adoption rates in Los Angeles and London studio complexes as the inflection signal for authentic site dependency erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Location Access Agreement | Multi-year landowner contracts in New Zealand and Scotland lock in inventory ahead of competitor entry. |
| Augmented Reality Capability Buildout | Smartphone-native AR layers at Outlander and Game of Thrones sites compress capital barriers for independent operators. |
| Streaming Platform Partnership | Direct destination marketing embedded in Netflix original content release cycles bypasses traditional tourism board channels. |
| Production Infrastructure Integration | Controlled backlot environments in Los Angeles and London sustain premium pricing through integrated facility access. |
| Fan Group Service Unbundling | Premium access packages for narrative-committed visitors capture merchandise revenue separate from general tourism. |
Research Methodology
Cross-validation between location tour operator booking data and streaming platform content licensing disclosures anchors the qualitative findings on visitor conversion patterns. Primary interviews with destination marketing executives, regional film office directors, third-party tour operators, and hospitality procurement managers combine with secondary validation against Screen Production Grant disbursement records, EU Audiovisual Media Services Directive compliance filings, and national tourism board visitor statistics. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across international, domestic, regional, and local market types.
Sensitivity analysis on production incentive framework durability and LED volume stage substitution rates frames the forecast uncertainty bounds across the projection horizon. Segmentation dimensions modeled include tourist archetype, experience format, film genre, and geographic source market, with CAGRs derived from trend extrapolation adjusted for regulatory mandate timing and technology adoption curves. Location disclosure enforcement patterns and solo traveler platform penetration rates constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained production incentive funding and streaming platform location promotion compliance; material deviation in either assumption would warrant model refresh. Practitioners should keep alternative scenarios live as virtual production technology economics and landowner access fee structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
UAE Faith Based Tourism Market
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Italy Casino Tourism Market
Destination Management and Attractions
Wildlife Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Europe Amusement Parks Market
Destination Management and Attractions
UK Family/ Indoor Entertainment Centers Market
Destination Management and Attractions
Music Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Ornithology Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
India MICE Tourism Market
Destination Management and Attractions
Opportunities in South East Asia Travel and Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market