
 Marine Retinol Market | 2026-2036
Marine Retinol Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Retinol Market Analytics
East Asian biotech fermentation capacity is reshaping raw material availability for marine retinol suppliers. Mara leverages integrated algae cultivation in coastal zones to secure consistent precursor supply. Age Stop Switzerland anchors European premium positioning through pharmaceutical-grade extraction protocols. Josie Maran competes in the North American clean beauty channel with argan-marine hybrid positioning.
Marine retinol denotes vitamin A-active compounds biosynthesized from microalgae, macroalgae, or marine microorganisms, typically delivered as retinyl palmitate analogues or proprietary retinoid-like esters with demonstrated collagen synthesis modulation at concentrations between 0.1% and 1.0%. These compounds serve cosmetic and dermatological formulators seeking retinoid efficacy without the erythema and photosensitivity associated with synthetic tretinoin. Serum formulations command the deepest margin pools due to concentration flexibility and premium positioning, while cream applications dominate volume through mass-market accessibility. Online stores represent the fastest-expanding distribution vector as direct-to-consumer brands bypass traditional retail gatekeepers.
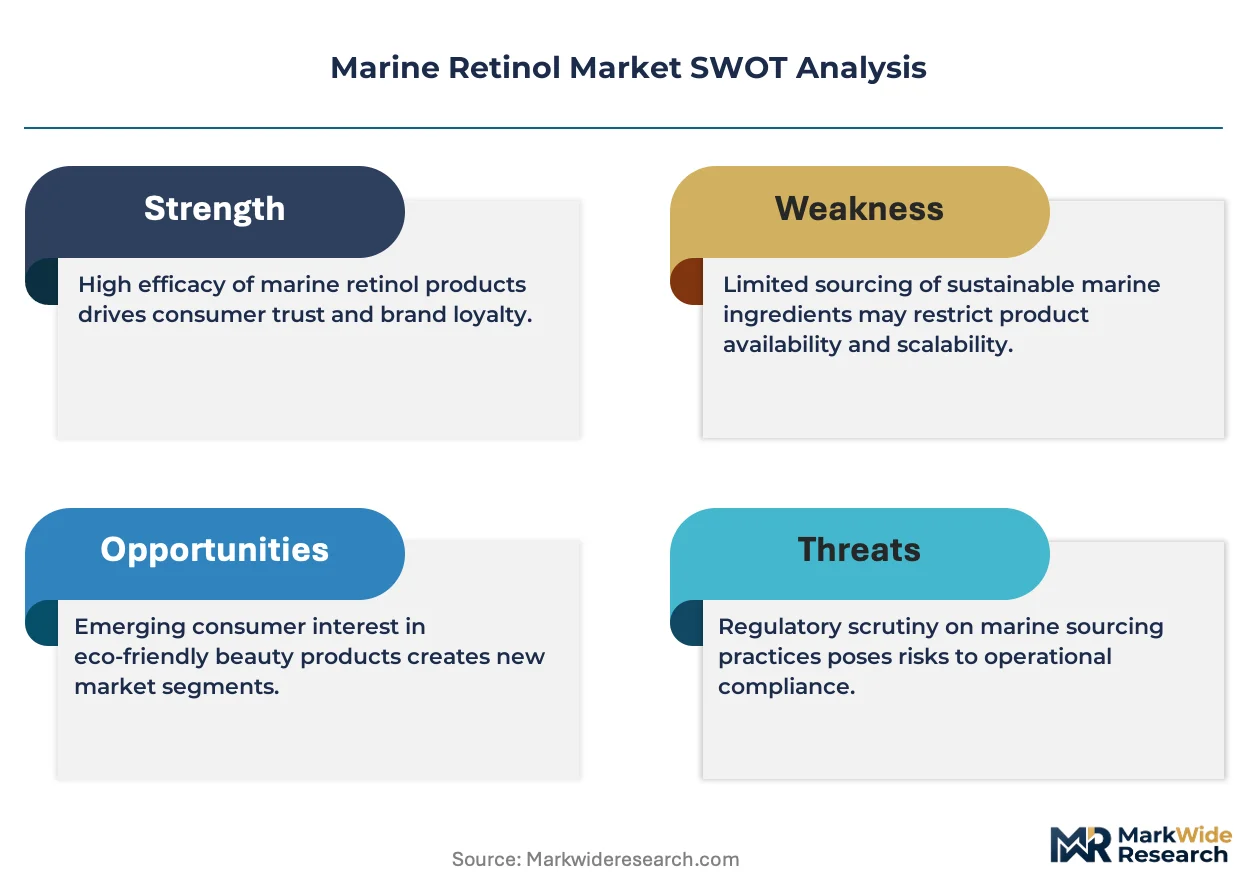
FDA cosmetic ingredient safety guidance and the EU Cosmetics Regulation (EC) No 1223/2009 jointly constrain permissible retinoid concentrations and labeling claims, compelling formulators toward marine-derived alternatives with more favorable tolerability profiles. REACH compliance in Europe and MoCRA implementation in the United States add testing and documentation burdens that favor established suppliers with regulatory affairs infrastructure. Stakeholders must monitor evolving photostability standards and biodegradability mandates as marine ingredient sourcing faces intensifying ecological scrutiny.
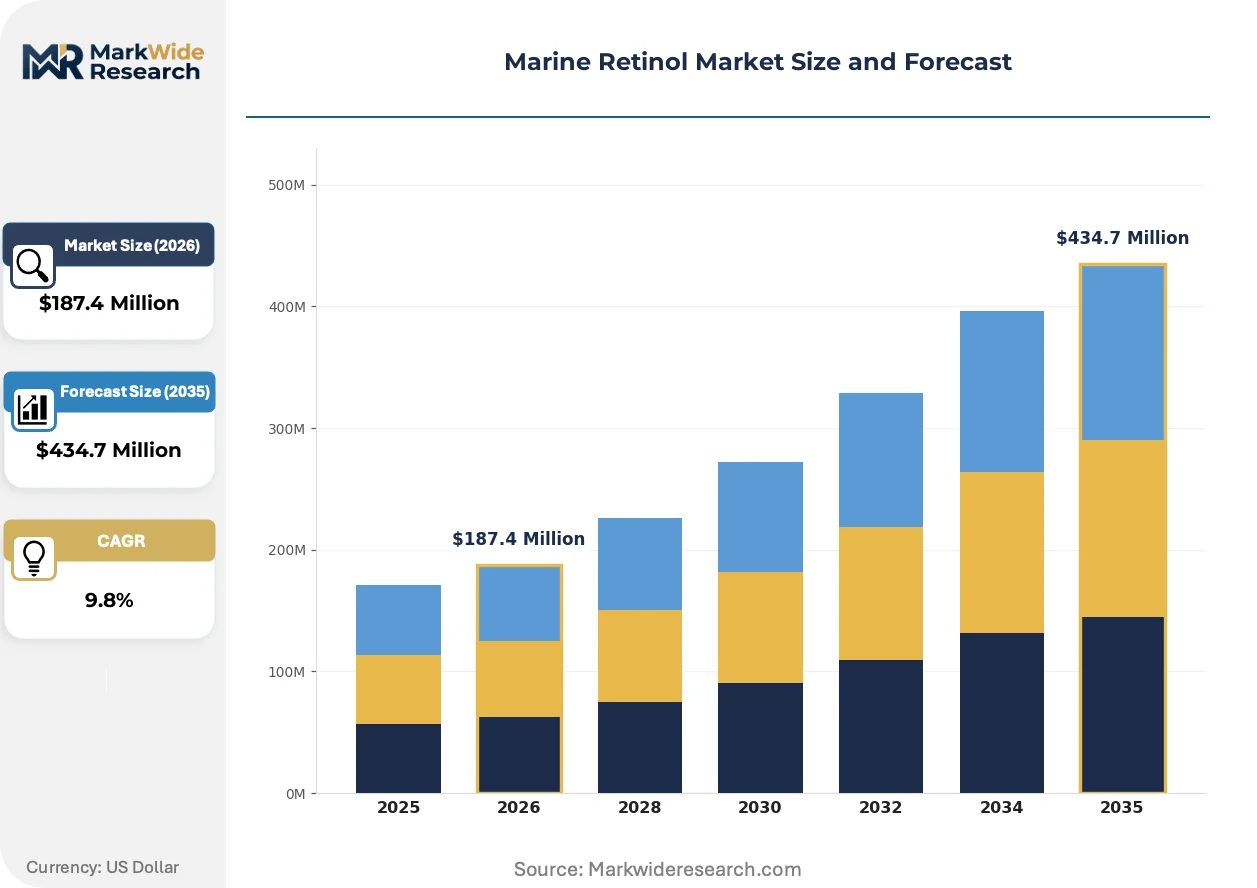
Market Dynamics
East Asian biotech fermentation capacity is concentrating raw material supply for marine retinol precursors, while FDA and EU Cosmetics Regulation compliance costs are accelerating supplier consolidation among established regulatory affairs infrastructure holders.
Growth Catalysts
- MoCRA implementation:The FDA's Modernization of Cosmetics Regulation Act tightens tolerability thresholds for synthetic retinoids, pushing formulators toward marine-derived alternatives with superior safety profiles.
- K-beauty multi-step routines:South Korean skincare protocols now integrate ocean-sourced vitamin A analogues as standard layering steps, creating sustained procurement pull from Seoul-based formulators.
- Algae cultivation automation:Closed photobioreactor systems for microalgae propagation are collapsing production cycle variability and securing year-round retinoid precursor yields.
Market Restraints
- Coastal zone access constraints:Macroalgae harvesting permits face tightening ecological scrutiny from marine protected area designations, constraining wild-source supply expansion.
- Pharmaceutical-grade extraction capex:Supercritical CO2 and chromatographic purification equipment requires seven-figure capital deployment, gating mid-tier supplier scale-up.
- Synthetic retinoid price anchoring:Bulk tretinoin and retinol remain cost-competitive reference points, compressing marine alternative pricing power in mass-market channels.
Strategic Opportunities
- India dermocosmetic channel:CDSCO's streamlined cosmetic ingredient notification pathway and expanding middle-class skincare expenditure create first-mover positioning for marine retinol entrants.
- Biodegradability mandate alignment:EU Green Deal marine ingredient sourcing standards favor suppliers with certified sustainable cultivation, rewarding compliant players with preferential procurement status.
- Direct-to-consumer serum subscriptions:Recurring revenue models for concentrated marine retinol formulations bypass traditional retail margin extraction and capture lifetime value data.
Industry Challenges
- Photostability formulation expertise:Marine retinoid esters degrade under UV exposure faster than synthetic alternatives, requiring specialized encapsulation chemistries that talent pools in cosmetic R&D centers struggle to supply.
- REACH dossier compilation timelines:Full substance registration under ECHA protocols demands 18-24 month documentation cycles, delaying European market entry for novel marine-derived actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Retinol Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Creams, Capsules, Oils Application: Cosmetics, Dermatology, Anti-aging, Sun Care End User: Individuals, Dermatologists, Salons, Clinics Distribution Channel: Online Stores, Retail Pharmacies, Specialty Stores, Supermarkets |
| Companies Covered | Age Stop Switzerland, MoonStar Essentials, Mara, Deconstruct, BeautyPro, Sheeba London, Serumology, Selfless by Hyram, Josie Maran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Retinol Market Evolving Landscape
Fermentation-derived retinoid precursors and regulatory compliance automation are compressing traditional extraction economics, while demand-side purchasing patterns fragment across clinical, prestige, and clean beauty positioning tiers.
Bioreactor-cultivated microalgae strains engineered for elevated retinyl palmitate yields are collapsing cost differentials against petroleum-derived synthetic retinoids. Contract manufacturers in coastal South Korea and eastern China are adopting these systems at commercial scale. The technology is collapsing the historical premium attached to marine-sourced claims by standardizing potency and reducing batch-to-batch variation below 3%.
REACH authorization requirements for novel cosmetic actives are forcing suppliers to front-load toxicological testing budgets before revenue generation. ECHA's 2024 updated guidance on endocrine disruption screening adds specific assay requirements for vitamin A analogues. European prestige brands are responding by consolidating supplier relationships with dossier-complete incumbents rather than qualifying novel entrants.
Subscription-based serum replenishment models are displacing traditional retail replenishment cycles for marine retinol products. Direct-to-consumer brands bypass Sephora and Ulta margin structures, capturing 40-60 point gross margin improvements. This pattern concentrates in North American urban markets where same-day delivery infrastructure supports just-in-time skincare replenishment habits.
Marine Retinol Market Segmentation
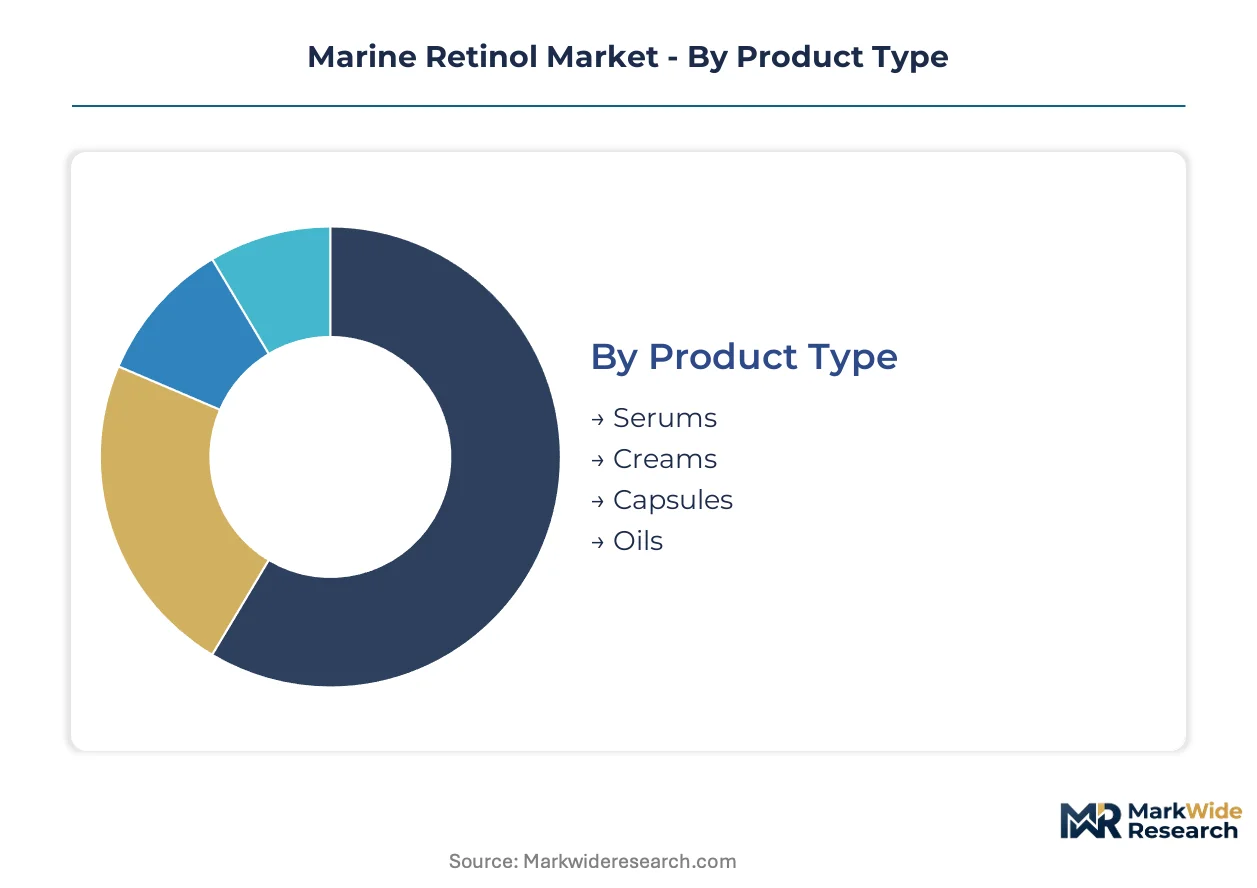
Marine retinol segmentation reflects divergent tolerability thresholds and procurement patterns across clinical and consumer channels. Formulators must match retinoid concentration, delivery vehicle, and distribution strategy to distinct end-user risk profiles and purchasing behaviors.
Product Type:
Mature serum formats coexist with emerging encapsulation technologies in this category, spanning liquid concentrates to solid-dose delivery systems.
- Serums:Water-based concentrates with 0.1% to 1.0% marine retinoid analogues enable precise dosing flexibility and rapid percutaneous absorption. Seoul-based formulators and US prestige brands concentrate procurement here, drawn by premium positioning latitude and the MoCRA-mandated shift away from synthetic retinoid tolerability concerns.
- Creams:Emulsion-based vehicles incorporating retinyl palmitate analogues at lower concentrations (0.05% to 0.3%) serve mass-market accessibility and first-time retinoid users. Volume concentrates in European pharmacy channels and Asian supermarket retail, where price anchoring against synthetic retinol constrains margin expansion.
- Capsules:Single-unit dose encapsulation protects marine retinoid esters from oxidative degradation and enables travel-format portability.
- Oils:Lipid-soluble delivery systems combine marine retinoids with complementary omega fatty acids from algal sources.
Creams retain volume leadership; serums hold the steepest expansion curve.
Application:
Cost tier stratification separates pharmaceutical-grade dermatological deployment from cosmetic wellness positioning.
- Cosmetics:General skincare formulations emphasizing texture refinement and radiance enhancement at sub-clinical retinoid concentrations. K-beauty multi-step routines in South Korea and clean beauty positioning in North America drive procurement, with CDSCO notification pathways opening comparable opportunities in India.
- Dermatology:Clinically validated protocols for acne management, post-inflammatory hyperpigmentation, and photoaging reversal requiring documented tolerability profiles. European REACH dossier completeness and FDA cosmetic ingredient safety guidance compliance determine supplier qualification, consolidating procurement among established regulatory affairs infrastructure holders.
- Anti-aging:Positioning focused on collagen synthesis modulation and wrinkle depth reduction for demographic segments over 35.
- Sun Care:Photostabilized formulations addressing UV-induced retinoid degradation through specialized encapsulation chemistries.
Cosmetics commands the broadest addressable base; dermatology delivers the highest per-unit value realization.
End User:
Customer type fragmentation separates self-directed consumption from professionally supervised application protocols.
- Individuals:Direct-to-consumer purchasers conducting independent product selection through online research and social media validation. Subscription replenishment models in North American urban markets bypass traditional retail margin extraction, capturing lifetime value data and 40-60 point gross margin improvements.
- Dermatologists:Licensed practitioners prescribing or recommending marine retinol within supervised treatment protocols. European consolidation toward dossier-complete suppliers and US prestige brand procurement acceleration shape this channel's supply requirements.
- Salons:Aesthetic service providers incorporating marine retinol into facial treatment protocols.
- Clinics:Medical aesthetic practices combining marine retinol with procedural interventions.
Individuals generate the highest transaction frequency; dermatologists anchor professional credibility transfer.
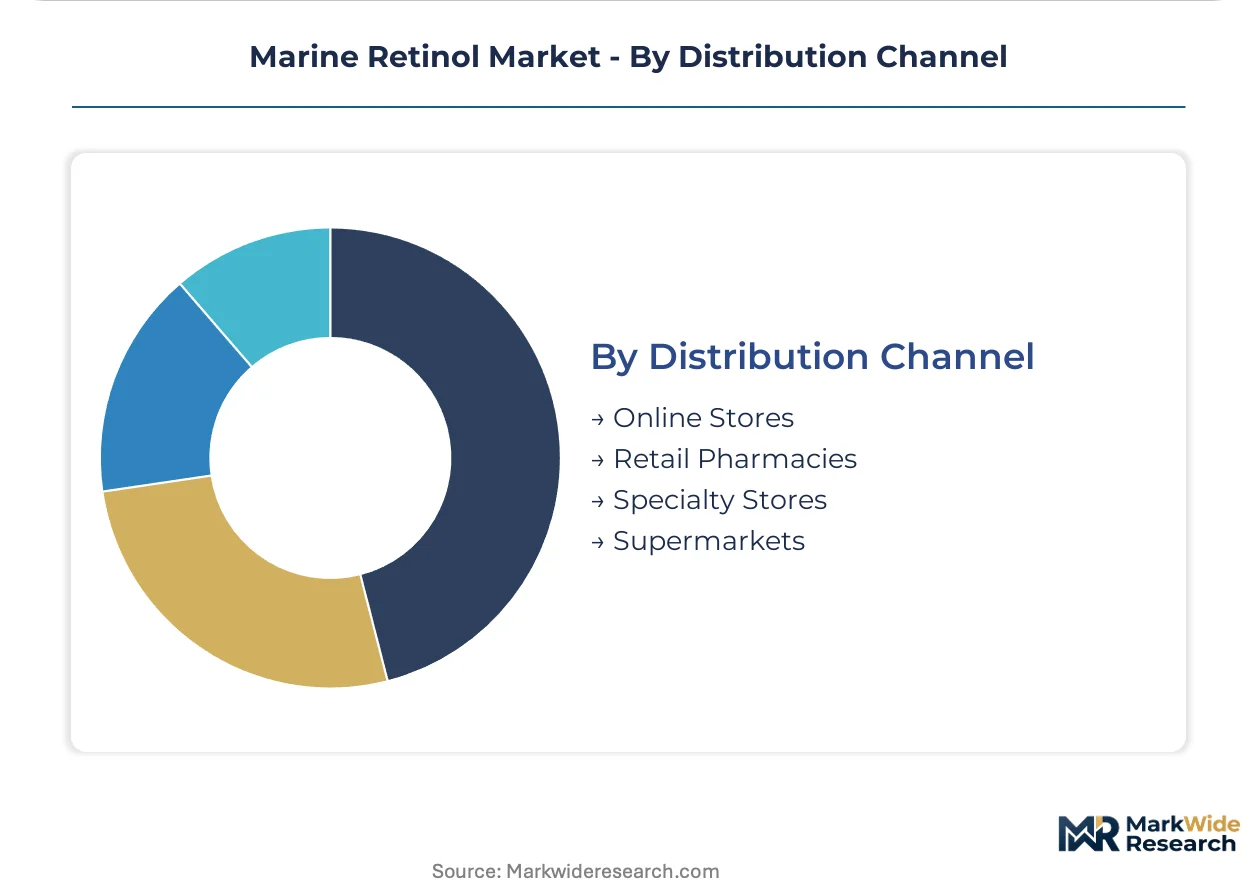
Distribution Channel:
Supply concentration in digital infrastructure is displacing traditional retail gatekeeper relationships.
- Online Stores:Direct-to-consumer platforms and marketplace aggregators enabling same-day delivery infrastructure and subscription replenishment. North American urban markets and Seoul's digital-native consumer base concentrate here, with just-in-time skincare habits reinforcing channel stickiness.
- Retail Pharmacies:Licensed dispensaries providing pharmacist consultation and regulatory compliance assurance. European pharmacy channels dominate, with REACH and EU Cosmetics Regulation documentation requirements favoring established supplier relationships.
- Specialty Stores:Sephora, Ulta, and comparable beauty retailers offering curated assortment and sampling access.
- Supermarkets:Mass-market retail formats emphasizing price accessibility and impulse purchase convenience.
Retail pharmacies retain trust-based positioning; online stores are climbing the fastest as direct brands capture margin and data advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan container throughput anchors East Asian marine retinol logistics, while Rotterdam's cold-chain infrastructure underwrites European distribution. Algae cultivation clusters in South Korea's coastal zones and China's Shandong Peninsula feed bioreactor networks supplying Seoul and Shanghai formulators.
United States
Prestige skincare procurement concentrates in New York and Los Angeles metro areas as FDA MoCRA implementation tightens synthetic retinoid tolerability thresholds. The Modernization of Cosmetics Regulation Act compliance costs favor established suppliers with regulatory affairs infrastructure. Boston's dermatology research corridor validates marine-derived alternatives for clinical positioning.
South Korea
K-beauty multi-step routines in Seoul drive sustained procurement pull for ocean-sourced vitamin A analogues. MFDS cosmetic ingredient notification pathways align with CDSCO's streamlined approach, creating export protocol synergies. Busan-Ulsan coastal bioreactor clusters supply standardized retinoid precursors to Gangnam-based formulators.
Switzerland
Pharmaceutical-grade extraction protocols in Basel and Zurich anchor European premium positioning. Swissmedic documentation requirements and REACH dossier completeness favor suppliers with toxicological testing infrastructure. Geneva's regulatory consulting ecosystem supports ECHA compliance for marine-derived actives entering EU markets.
India
Expanding middle-class skincare expenditure in Mumbai and Delhi-NCR creates first-mover positioning for marine retinol entrants. CDSCO's streamlined cosmetic ingredient notification pathway reduces entry timelines versus European protocols. Maharashtra's contract manufacturing base adapts fermentation-derived precursors for dermocosmetic channel distribution.
China
NMPA cosmetic registration requirements and dual carbon goals reshape algae cultivation economics in Shandong and Fujian provinces. Yangtze River Delta formulators integrate bioreactor-cultivated microalgae strains into domestic prestige brands. Shanghai's cross-border e-commerce infrastructure exports marine retinol serums to Southeast Asian markets.
Marine Retinol Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The marine retinol market structures around three tiers: fermentation-scale suppliers controlling precursor yields, formulation brands commanding consumer positioning, and regulatory-compliance service providers enabling market access. Competitive moves concentrate on algae cultivation automation partnerships and REACH dossier acquisition strategies.
Within the fermentation-scale supplier tier, Mara anchors integrated algae cultivation positioning, while Age Stop Switzerland exemplifies pharmaceutical-grade extraction protocol differentiation. Josie Maran occupies the North American clean beauty channel with hybrid natural positioning. These three entities represent divergent strategic archetypes: coastal bioreactor integration, European regulatory premium, and mass-market accessibility.
| Leading Market Players |
|---|
| Age Stop Switzerland |
| MoonStar Essentials |
| Mara |
| Deconstruct |
| BeautyPro |
| Sheeba London |
| Serumology |
| Selfless by Hyram |
| Josie Maran |
| Others |
Value Network & Pricing Analysis
Bioreactor utilization rates above 85% in South Korea's coastal zones are compressing precursor yields and forcing suppliers toward longer-term offtake contracts to stabilize input costs. FDA MoCRA compliance investments and EU REACH dossier requirements are simultaneously elevating fixed-cost thresholds, concentrating pricing power among established regulatory infrastructure holders while squeezing mid-tier formulators.
Pricing Analysis
EU Cosmetics Regulation and FDA MoCRA jointly dictate the pricing tier structure across marine retinol procurement channels. Certification-grade differentiation separates pharmaceutical-extraction protocols from cosmetic-grade fermentation outputs, with REACH dossier completeness commanding substantial premiums over pending-registration alternatives. Price erosion runs through mass-market cream formulations as synthetic retinol price anchoring constrains marine alternative positioning, while subscription serum models in North America exhibit the lowest buyer price sensitivity due to captured lifetime value economics.
Supply Chain Analysis
Dual-use biotechnology export controls limiting microalgae strain transfers are reshaping supplier geography toward domestic cultivation clusters. Raw material flows center on South Korea, China's Shandong Peninsula, and Switzerland's pharmaceutical extraction hubs, with retinyl palmitate precursors and supercritical CO2 purification equipment constituting critical dependencies. Single-source vulnerability concentrates in photobioreactor automation systems sourced from East Asian equipment fabricators. Distribution runs through direct-to-consumer platforms and retail pharmacy channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine retinol procurement is fragmenting across clinical validation tiers and clean beauty positioning, creating specialized supplier niches as K-beauty formulators, US prestige brands, and Indian dermocosmetic channels pursue divergent tolerability and sourcing specifications.
For Market Incumbents: Pre-empt synthetic retinoid price anchoring by locking multi-year algae cultivation contracts before bioreactor capacity expansion in China's coastal zones saturates precursor supply. Secure ECHA REACH dossier completeness for retinoid analogues ahead of updated endocrine disruption screening requirements, consolidating procurement relationships with European prestige brands seeking regulatory risk mitigation. For New Entrants and Emerging Players: Pursue CDSCO notification pathway advantages in India's dermocosmetic channel before established suppliers complete regulatory documentation. Target subscription-based serum formulations for North American urban markets with same-day delivery infrastructure, bypassing Sephora and Ulta margin extraction through direct-to-consumer positioning anchored on marine-derived tolerability claims. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade extraction equipment as supercritical CO2 and chromatographic purification systems require seven-figure deployment. Fermentation-scale suppliers with integrated coastal bioreactor networks and complete REACH dossiers represent the most defensible acquisition profile through the next decade. Monitor ECHA authorization timelines for novel vitamin A analogues as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Bioreactor Capacity Expansion | Secures year-round retinoid precursor yields against macroalgae harvesting permit constraints. |
| REACH Dossier Acquisition Strategy | Accelerates European market entry ahead of ECHA's updated endocrine disruption screening requirements. |
| Direct-to-Consumer Serum Launch | Captures 40-60 point gross margin improvements by bypassing Sephora and Ulta retail structures. |
| CDSCO Notification Pathway Investment | Opens first-mover positioning in India's expanding dermocosmetic channel ahead of competitor filings. |
| Photostability Encapsulation Partnership | Addresses marine retinoid ester UV degradation faster than synthetic alternatives through specialized chemistries. |
Research Methodology
Desk research of ECHA REACH registration databases, FDA cosmetic ingredient safety guidance documents, and MFDS notification filings preceded structured interviews with marine biotechnology R&D directors, K-beauty formulators, European regulatory affairs consultants, and Indian dermocosmetic brand managers. Secondary validation drew from customs trade data on algae-derived cosmetic ingredient flows, SEC filings of listed skincare companies, and EU Cosmetics Regulation enforcement reports. Bottom-up procurement modeling triangulated against top-down market sizing across serum, cream, capsule, and oil delivery formats.
Assumptions held fixed include MoCRA implementation timelines and EU Green Deal marine ingredient sourcing standards, while algae cultivation automation adoption rates and CDSCO notification processing speeds were varied across sensitivity scenarios. Segmentation modeling spanned product type, application tier, end-user channel, and distribution format, with CAGRs derived from rolling average growth rate analysis across the projection horizon. Forecast inputs incorporated bioreactor yield standardization trends and photostability formulation expertise scarcity.
Sensitivities concentrate around ECHA authorization timeline delays for novel marine-derived actives and coastal zone ecological designation expansions constraining wild-source macroalgae supply. Forecasts reflect documented assumptions on regulatory compliance cost trajectories and fermentation-derived precursor cost convergence. Material shifts in FDA tolerability threshold enforcement or EU biodegradability mandate stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Ultrasound Skin Cleaners Market
Skincare
Rice Water Skincare Market
Skincare
Skin Care Supplements Market
Skincare
Biological Skin Substitutes Market
Skincare
Global Scar Removal Treatment Market
Skincare
Herbal Skincare Products Market
Skincare
India Skin Care Products Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Skin Boosters Market
Skincare
Germany Skincare Product Market
Skincare
Cystic Acne Market
Skincare
Dermocosmetics Skin Care Products Market
Skincare
Fragrance-Free Skin Care Products Market
Skincare
Hand Eczema (HE) Treatment Market
Skincare
Anti-Aging Services Market