
 Travel Retail Market | 2026-2036
Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Retail Market Intelligence
Dubai's terminal expansion and new luxury retail zones is reconfiguring capacity benchmarks for competing hubs. Lotte Duty Free leverages its dominance in Seoul Incheon to anchor Asian passenger spend. DFS Group competes through curated brand portfolios in Greater China gateways. China Duty Free Group extends its Hainan island retail network to capture domestic outbound demand.
Travel retail denotes commercial transactions conducted in duty-exempt zones at airports, seaports, and border crossings, typically requiring proof of imminent international departure and operating under bonded warehouse protocols with real-time inventory tracking. Fragrance and confectionery categories sustain the highest margin pools due to compact logistics and impulse-driven purchase behavior. Airport duty-free channels dominate volume, while cruise ship and onboard retail segments specialize in captive-audience monetization with extended dwell times. Personal shopping assistance and loyalty programs increasingly differentiate operator performance as passenger expectations rise.
FDA oversees alcohol and tobacco labeling standards affecting inbound US passenger allowances, while EU Green Deal carbon reporting requirements under CSRD reshape airport retail energy and waste protocols. REACH and RoHS frameworks govern cosmetics and electronics composition sold across European duty-free zones. China's SAMR enforces product authenticity verification for cross-border retail, tightening supply chain documentation. Stakeholders must monitor regulatory divergence between origin and destination jurisdictions to preempt compliance costs and access restrictions.
Market Dynamics
China's dual carbon goals are forcing airport infrastructure redesigns that shrink retail footprints while mandating green building certifications, compressing available selling space per passenger at major hubs.
Growth Catalysts
- Green building mandates:China's SAMR enforcement of carbon-neutral airport construction is accelerating duty-free zone redevelopment with energy-efficient fixtures and bonded warehouse protocols.
- Personal shopping assistance:Airport operators in Dubai and Doha are deploying concierge services that extend dwell time and lift conversion rates in fragrance and confectionery categories.
- REACH compliance:European cosmetics sold in duty-free zones must meet ECHA chemical composition standards, creating premium positioning for verified clean-label products.
Market Restraints
- Input cost volatility:Luxury packaging materials face petroleum-based resin price swings that squeeze margin pools in compact logistics-dependent categories.
- Supply concentration risk:Middle Eastern hub operators depend on a narrow corridor of Dubai and Doha for premium fragrance inventory, exposing them to regional disruption.
- Regulatory friction:FDA alcohol and tobacco labeling requirements for inbound US passengers create documentation bottlenecks that slow real-time inventory tracking systems.
Strategic Opportunities
- Hainan island expansion:China Duty Free Group's domestic outbound capture model offers a template for replicating captive-audience monetization outside traditional airport zones.
- EU Green Deal tailwind:CSRD carbon reporting requirements are pressuring airport retail energy and waste protocols, rewarding early adopters with preferential lease terms.
- Cruise ship channel innovation:Extended dwell times on vessels enable curated brand portfolios and loyalty program integration unavailable in high-velocity airport environments.
Industry Challenges
- Certification timeline compression:RoHS electronics verification and SAMR product authenticity documentation must synchronize with bonded warehouse restocking cycles.
- Legacy system integration:Real-time inventory tracking protocols often conflict with established ERP architectures at older hub facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Retail Market |
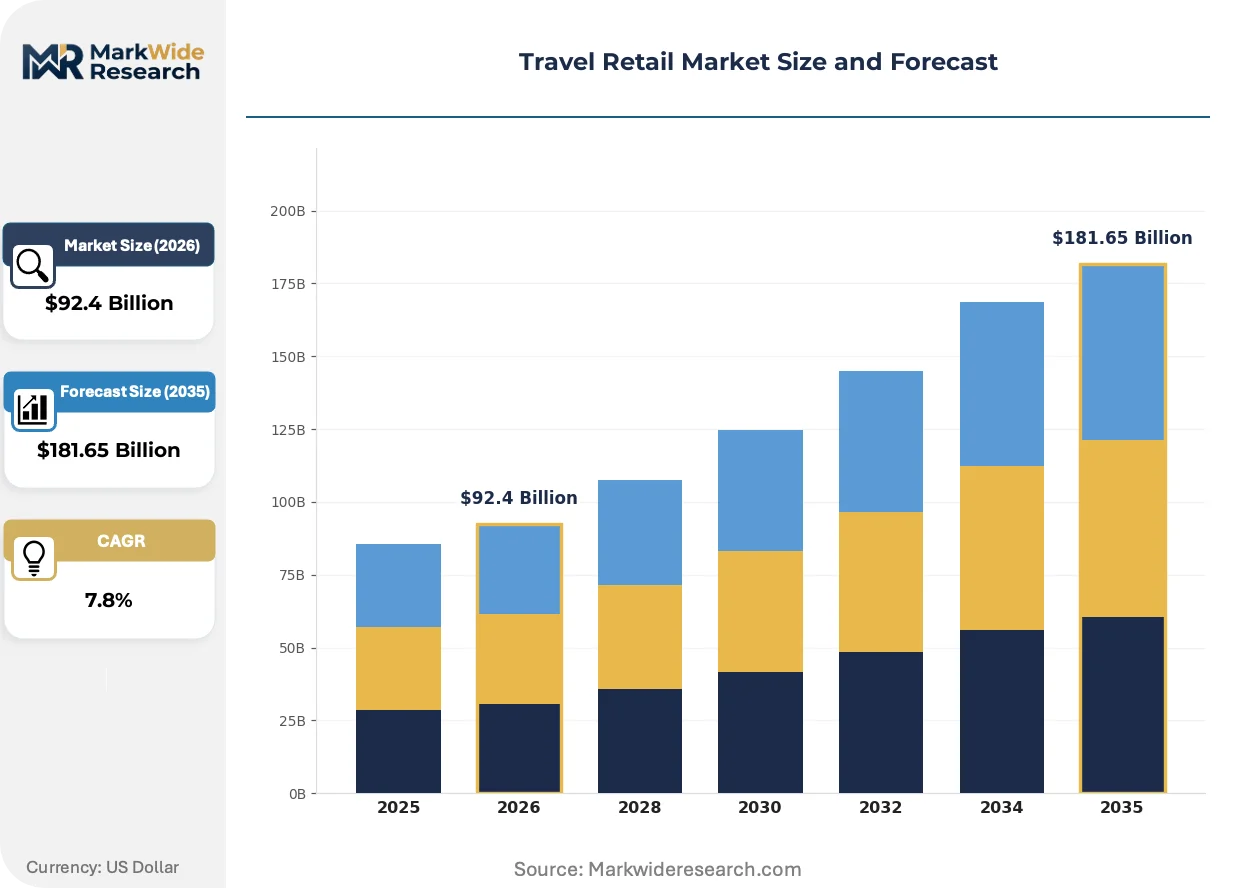
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $181.65 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrances, Confectionery, Electronics, Souvenirs, Apparel, Accessories Distribution Channel: Airport Duty-Free, Onboard Retail, Travel Venues, Online Travel Portals, Cruise Ships Customer Type: Frequent Flyers, Business Travelers, Leisure Travelers, Transit Passengers, VIP Clients Service Type: Personal Shopping Assistance, Package Delivery, Currency Exchange, Gift Wrapping, Loyalty Programs |
| Companies Covered | DFS Group, Duty Free Americas, Avolta, WHSmith North America, Paradies Lagardère, Lagardère Travel Retail, Lotte Duty Free, HMSHost, China Duty Free Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Retail Market Strategic Shifts & Innovations
Digital infrastructure is hybridizing with physical retail operations, creating frictionless purchase pathways that reshape how duty-free operators capture impulse-driven spend.
Biometric payment authentication is hybridizing passenger verification with transaction completion. Seoul Incheon and Dubai International are deploying facial recognition at point-of-sale terminals. This technology is hybridizing security clearance with commercial checkout, collapsing two previously separate passenger processing stages into one seamless interaction.
EU Green Deal carbon reporting requirements under CSRD are mandating granular energy and waste disclosure from airport retail tenants. Operators must now submit verified emissions data to secure lease renewals. Fragrance and cosmetics categories face the steepest compliance costs due to packaging material traceability demands.
Leisure travelers are consolidating purchase decisions into pre-departure mobile browsing sessions. Personal shopping assistance services now originate in airport apps rather than at physical concierge desks. This behavioral pivot is most pronounced among outbound Chinese passengers who research Hainan island pricing benchmarks before reaching duty-free zones.
Travel Retail Market Segmentation
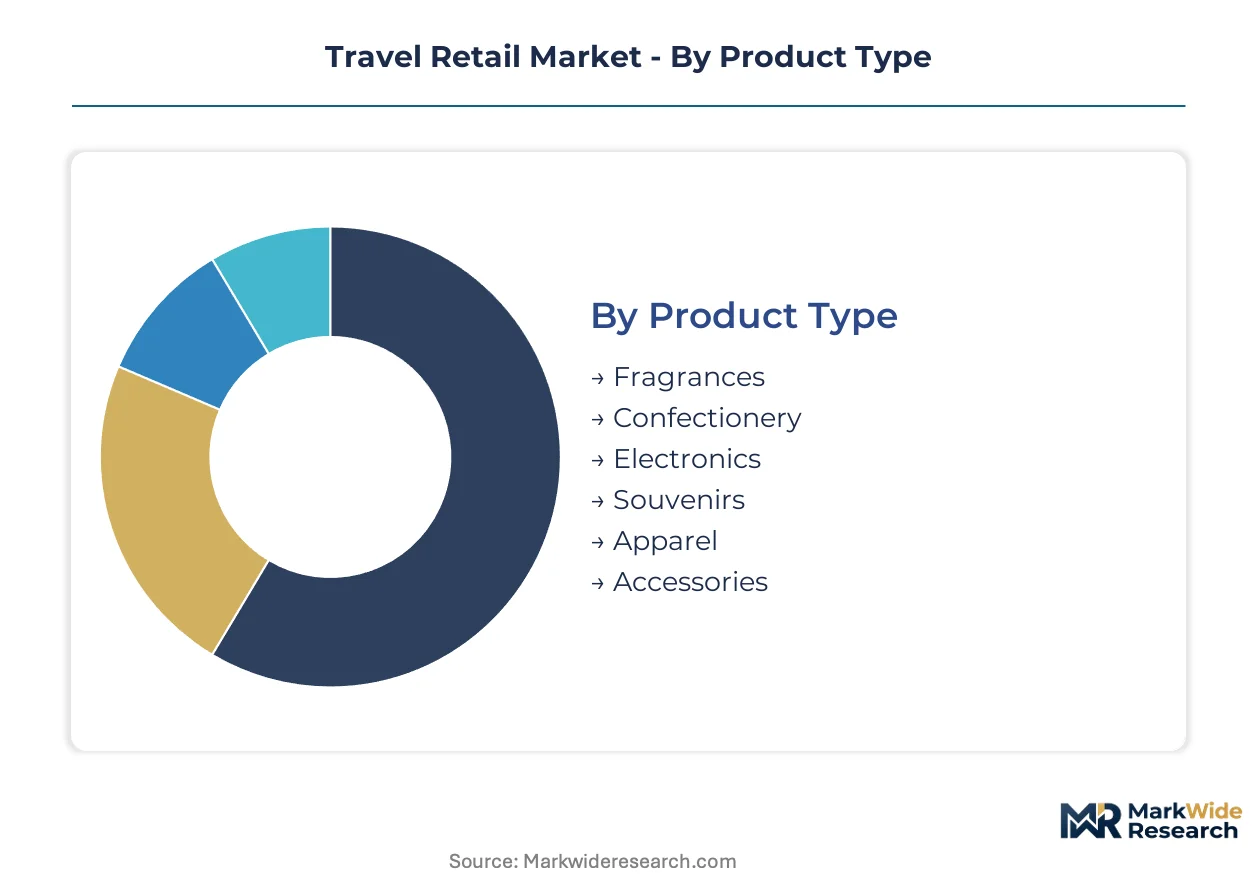
Travel retail segmentation reveals how duty-free operators align inventory, service models, and channel strategies with distinct passenger profiles and purchase occasions. Category-specific margin structures and dwell-time economics drive resource allocation across airport, cruise, and digital touchpoints.
Product Type:
Cost tier stratification separates compact logistics categories with impulse velocity from bulky, lower-velocity merchandise requiring extended consideration cycles.
- Fragrances:Compact SKU formats maximize shelf density per square meter in constrained airport retail footprints. Dubai and Doha hubs anchor premium fragrance demand, with China's SAMR authenticity verification tightening documentation requirements for cross-border inventory.
- Confectionery:High-rotation packaged goods exploit impulse thresholds at security-adjacent retail zones. Middle Eastern hub operators concentrate procurement on European heritage brands to satisfy outbound Asian passenger preferences.
- Electronics:RoHS compliance verification governs composition standards for devices sold across European duty-free zones.
- Souvenirs:Location-branded merchandise captures terminal-exit purchase behavior with minimal dwell-time requirements.
- Apparel:Size complexity and return friction limit airport penetration compared to downtown flagship formats.
- Accessories:Leather goods and timepieces require secured display infrastructure with bonded warehouse tracking protocols.
Fragrances hold installed capacity. Confectionery is rotating up the share rankings.
Distribution Channel:
Application context determines whether operators optimize for transaction velocity, captive-audience monetization, or pre-departure convenience.
- Airport Duty-Free:Dominant volume channel operating under bonded warehouse protocols with real-time inventory tracking synchronized to flight departure data. China's dual carbon goals are compressing available retail square footage per passenger at major hubs undergoing green building retrofits.
- Cruise Ships:Extended voyage durations enable curated brand portfolios and loyalty program integration unavailable in high-velocity environments. Onboard retail segments specialize in captive-audience monetization with dwell times measured in days rather than minutes.
- Onboard Retail:In-flight sales operations face weight restrictions and payment friction that limit category breadth.
- Travel Venues:Border crossings and seaports operate under divergent customs protocols that fragment operational standardization.
- Online Travel Portals:Pre-departure browsing behavior among Chinese passengers is consolidating purchase research into mobile sessions before physical zone arrival.
Airport Duty-Free retains dominant throughput. Cruise Ships are gaining share fastest among experiential spend categories.
Customer Type:
Volume concentration patterns separate high-frequency low-yield segments from episodic high-yield occasions requiring differentiated service intensity.
- Leisure Travelers:Episodic high-yield segment driving fragrance and confectionery impulse velocity with extended dwell windows. Personal shopping assistance services now originate in airport apps rather than physical concierge desks for this cohort.
- Business Travelers:Compressed dwell times favor grab-and-go formats with minimal friction. Seoul Incheon and Dubai International deploy biometric payment authentication to collapse security clearance with commercial checkout for time-constrained passengers.
- Frequent Flyers:Loyalty program integration enables predictive inventory positioning based on historical purchase patterns.
- Transit Passengers:Extended connection windows create captive retail exposure at hub airports with deliberate terminal design.
- VIP Clients:Dedicated concierge services extend conversion rates in premium categories through appointment-based access.
Leisure Travelers hold installed capacity. Business Travelers are climbing the fastest as biometric infrastructure reduces transaction friction.
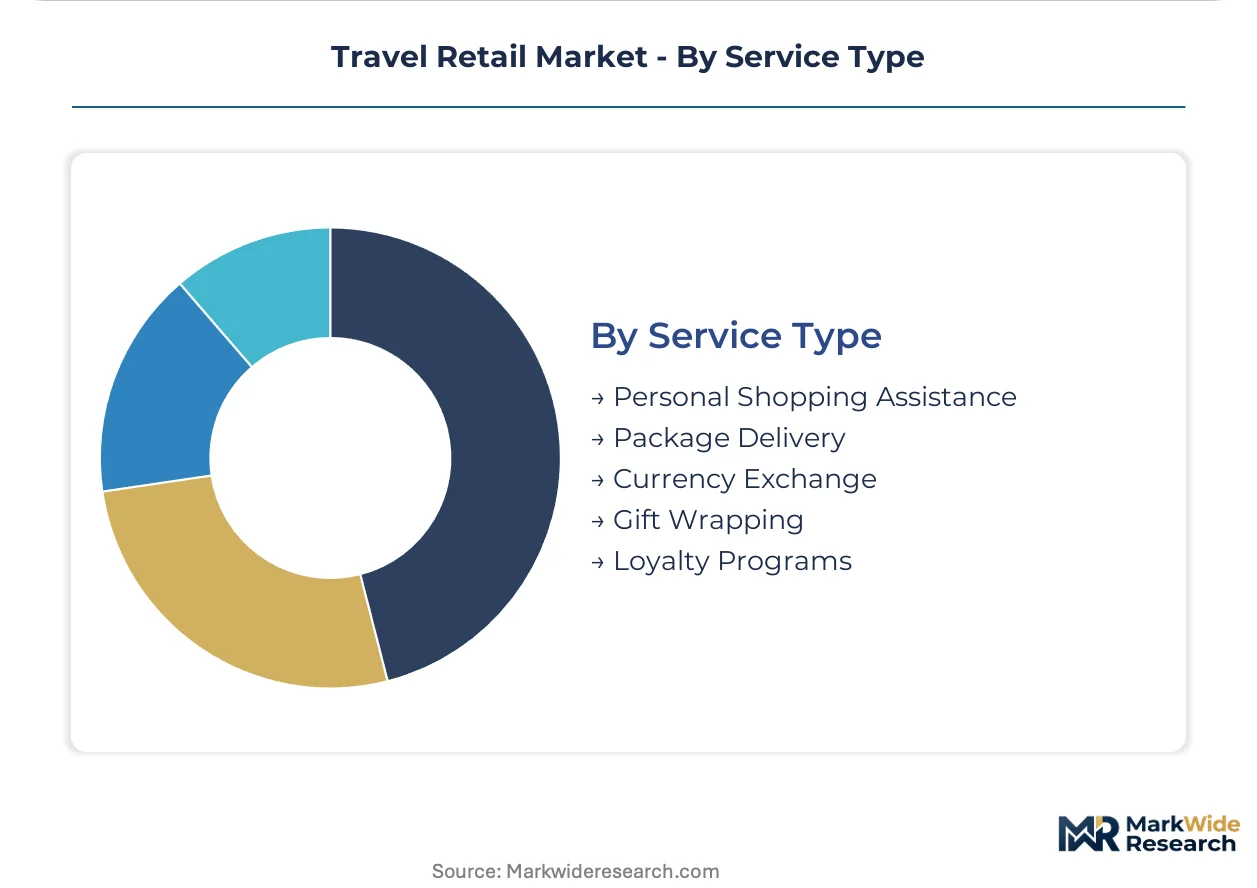
Service Type:
Margin contribution separates scalable digital services from labor-intensive experiential offerings that extend dwell time and conversion depth.
- Personal Shopping Assistance:Concierge services deployed in Dubai and Doha extend dwell time and lift conversion rates in high-margin categories. EU Green Deal carbon reporting requirements under CSRD are mandating energy-efficient fixture standards for service-dense retail zones.
- Loyalty Programs:Data capture infrastructure enables predictive inventory positioning and personalized promotion delivery across multi-hub networks.
- Package Delivery:Post-purchase logistics integration addresses inbound allowance constraints for US passengers under FDA alcohol and tobacco labeling standards.
- Currency Exchange:Regulatory fragmentation across origin and destination jurisdictions creates compliance overhead for real-time rate synchronization.
- Gift Wrapping:Labor-intensive service with limited scalability in high-velocity terminal environments.
Personal Shopping Assistance holds installed capacity. Loyalty Programs are expanding most quickly as operators digitize passenger data capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's carbon-neutral construction mandates in China are compressing retail footprints at major hubs while EU Green Deal CSRD disclosure rules reshape European airport energy protocols.
China
Dual carbon goals are forcing green building retrofits at Beijing Capital and Shanghai Pudong that shrink duty-free square footage per passenger. SAMR enforces product authenticity verification with bonded warehouse documentation requirements. Hainan island's offshore duty-free network captures domestic outbound demand through China Duty Free Group's expansion.
United Arab Emirates
Dubai International's terminal expansion and new luxury retail zones reconfigure capacity benchmarks for competing Middle Eastern hubs. MOHAP oversees product safety standards for cosmetics and fragrances sold across Emirates duty-free zones. Dubai and Doha anchor premium fragrance and confectionery demand concentration.
South Korea
Seoul Incheon deploys biometric payment authentication that collapses security clearance with commercial checkout for time-constrained passengers. MFDS regulates cosmetics composition sold in duty-free zones under national pharmaceutical standards. Lotte Duty Free leverages hub dominance to anchor Asian passenger spend patterns.
United States
FDA alcohol and tobacco labeling standards create documentation bottlenecks for inbound passenger allowances that slow real-time inventory tracking systems. EPA energy efficiency guidelines influence airport retail fixture specifications at major hubs. Miami and JFK terminals concentrate Latin American and transatlantic passenger flows.
Germany
REACH and RoHS frameworks govern cosmetics and electronics composition across European duty-free zones with ECHA chemical verification requirements. KBA transport safety regulations affect bonded warehouse logistics protocols at Frankfurt and Munich airports. Bavaria's hub infrastructure maintains premium brand portfolio curation.
Travel Retail Market Key Industry Players
Capability concentration sits with hub-specific operators commanding passenger flow access; scale advantage sits with multi-territory portfolios spanning airport, cruise, and digital channels. The vendor base organizes around three strategic archetypes: incumbent airport concessionaires with bonded warehouse expertise, luxury brand aggregators curating premium portfolios, and domestic market specialists capturing outbound demand. Dominant competitive moves include strategic partnerships with biometric technology providers and portfolio diversification into personal shopping assistance services.
Within the hub-dominant tier, Lotte Duty Free and China Duty Free Group exemplify geographic specialization strategies. DFS Group occupies a position representing the luxury brand aggregator archetype across Greater China gateways. Duty Free Americas sits within the North American concessionaire segment with operational scale across multiple US airport terminals.
| Leading Market Players |
|---|
| DFS Group |
| Duty Free Americas |
| Avolta |
| WHSmith North America |
| Paradies Lagardère |
| Lagardère Travel Retail |
| Lotte Duty Free |
| HMSHost |
| China Duty Free Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in Middle Eastern fragrance inventory is compressing margin pools for competing hub operators while elevating pricing power for Dubai and Doha concessionaires. This utilization dynamic feeds directly into supplier selection criteria and procurement urgency across bonded warehouse networks.
Pricing Analysis
Dubai and Doha command a 15-25% price premium over European duty-free zones for identical fragrance SKUs, reflecting captive-audience monetization and limited alternative sourcing. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand heritage and packaging complexity. Pricing pressure stems from petroleum-based resin volatility in luxury packaging materials, squeezing compact logistics-dependent categories. Leisure travelers exhibit lowest price sensitivity due to impulse-driven purchase behavior, while transit passengers show highest elasticity.
Supply Chain Analysis
Contract manufacturing for duty-free exclusive SKUs concentrates with LVMH Beauty, Coty, and Interparfums facilities in France and Spain. Fragrance and confectionery production draws from European heritage brand clusters, while electronics sourcing rests on Chinese and South Korean component suppliers. Single-source vulnerability pervades premium fragrance procurement, where Middle Eastern hubs depend on narrow European supply corridors. Distribution runs through bonded warehouse protocols synchronized to flight departure data, with real-time inventory tracking mandating ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from Hainan island's domestic duty-free model, which captures outbound Chinese demand without airport infrastructure constraints. Defense requires structural adaptation.
For Market Incumbents: Harden biometric payment infrastructure to collapse security clearance with commercial checkout, reducing dwell-time friction that Hainan cannot replicate. Deepen backward integration into personal shopping assistance services through airport app ecosystems, creating switching costs. Vertical control over loyalty program data capture anchors predictive inventory positioning against domestic retail alternatives.
For New Entrants and Emerging Players: Secondary-tier Chinese airports undergoing green building retrofits present underpenetration opportunity, as incumbent operators vacate compressed retail footprints. Cruise ship channels offer captive-audience monetization with extended dwell times absent from high-velocity environments. Go-to-market angle should emphasize curated brand portfolios unavailable through Hainan's mass-market positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biometric infrastructure deployment and CSRD-compliant fixture retrofits, favoring scaled operators with lease renewal leverage. Acquisition targets should display hub-specific passenger flow access combined with multi-channel portfolios spanning airport, cruise, and digital touchpoints. Monitor SAMR enforcement intensity as inflection signal for cross-border inventory documentation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Payment Deployment | Seoul Incheon and Dubai International facial recognition collapses security clearance with commercial checkout. |
| Green Building Retrofit | CSRD carbon reporting mandates energy-efficient fixtures to secure lease renewals at EU hubs. |
| Hainan Network Expansion | China Duty Free Group's domestic outbound capture model replicates captive-audience monetization outside airports. |
| Cruise Ship Channel Entry | Extended voyage durations enable loyalty program integration unavailable in terminal environments. |
| Personal Shopping Digitization | Airport app-originated concierge services extend dwell time and lift conversion in fragrance categories. |
Research Approach
Initial hypotheses were tested against primary input from airport concession directors, duty-free procurement managers, airline retail operations heads, and bonded warehouse logistics coordinators, then refined through secondary validation. Sources included customs and trade data from major hub jurisdictions, SAMR and FDA regulatory filings, airport authority capex disclosures, and fragrance industry shipment records. Bottom-up passenger spend modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with segmentation across product type, distribution channel, customer archetype, and service tier throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including CSRD implementation and China's dual carbon mandates. Industry-specific inputs incorporated green building certification timelines and biometric infrastructure deployment schedules at named hub airports.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic offshore duty-free operators would shift outcomes beyond modeled ranges. Quarterly review of SAMR enforcement actions, CSRD compliance deadlines, and Middle Eastern hub expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Greece Tourism Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Sports Tourism Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
South Korea Travel Retail Market