
 Travel Intermediaries Business Market | 2026-2036
Travel Intermediaries Business Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Intermediaries Business Market Analytics
The direct-to-supplier channel is narrowing as corporate travel programs reinstate intermediary relationships for duty-of-care compliance and negotiated rate access. Booking Holdings leverages its massive accommodation inventory to sustain pricing leverage across enterprise accounts. American Express Global Business Travel anchors its position through integrated expense management and traveler safety protocols. SAP Concur competes by embedding travel booking within broader financial workflow automation.
Travel intermediaries business encompasses entities that facilitate, arrange, and manage transportation, lodging, and ancillary services between suppliers and end travelers, operating through proprietary booking platforms that integrate global distribution systems, payment processing, and real-time inventory management. The primary commercial purpose centers on aggregating fragmented supplier inventory while adding value through negotiated rates, policy enforcement, and traveler support services. Online travel agents occupy the fastest-expanding margin pool as mobile-first booking behavior shifts volume away from traditional call-center operations. Corporate travel services command premium pricing through contract complexity and ongoing account management requirements. Data analytics technology underpins competitive differentiation, enabling intermediaries to predict demand patterns and optimize supplier negotiations.
The EU Package Travel Directive imposes strict liability and information disclosure requirements on European intermediaries, elevating compliance costs while protecting traveler rights. The US Department of Transportation enforces transparency rules on airline fee disclosure, directly affecting how American intermediaries display and price flight options. China's SAMR monitors platform pricing algorithms under anti-monopoly frameworks, constraining how intermediaries operating there can leverage data for personalized pricing. Stakeholders must monitor evolving AI governance frameworks as automated decision-making in travel recommendations triggers new accountability standards across multiple jurisdictions.
Market Dynamics
Corporate travel programs are consolidating intermediary relationships to secure duty-of-care compliance and negotiated rate access, reversing the pandemic-era shift toward direct supplier booking. This structural pivot elevates intermediaries with integrated safety protocols and expense management capabilities.
Growth Catalysts
- EU Package Travel Directive:Strict liability and disclosure requirements drive intermediaries to upgrade platform transparency, creating competitive differentiation for compliant operators.
- AI-driven personalization engines:Machine learning recommendation systems enable intermediaries to match traveler preferences against policy constraints in real-time booking flows.
- Multinational enterprise reinvestment:Fortune 500 companies are reinstating managed travel programs with centralized booking mandates and integrated expense controls.
Market Restraints
- Global distribution system fees:Legacy GDS transaction costs compress margins for traditional intermediaries serving price-sensitive leisure segments.
- Supplier direct channel expansion:Major hotel chains and airlines are investing in proprietary loyalty programs that bypass intermediary commissions.
- China SAMR algorithm oversight:Anti-monopoly monitoring of platform pricing constrains how intermediaries leverage data for dynamic personalization.
Strategic Opportunities
- India corporate travel formalization:Small and medium enterprises in India are adopting managed travel programs for the first time, creating greenfield account acquisition potential.
- EU AI Act compliance services:Automated travel recommendation systems trigger new accountability standards, opening advisory and audit revenue streams.
- Embedded finance convergence:Integration of travel booking with corporate card issuance and expense reconciliation creates stickier platform relationships.
Industry Challenges
- Legacy system integration:Corporate clients demand API connectivity with entrenched ERP platforms like SAP and Oracle, extending implementation timelines.
- Traveler data privacy engineering:Cross-border data transfer restrictions under GDPR and emerging national frameworks complicate cloud infrastructure architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Intermediaries Business Market |
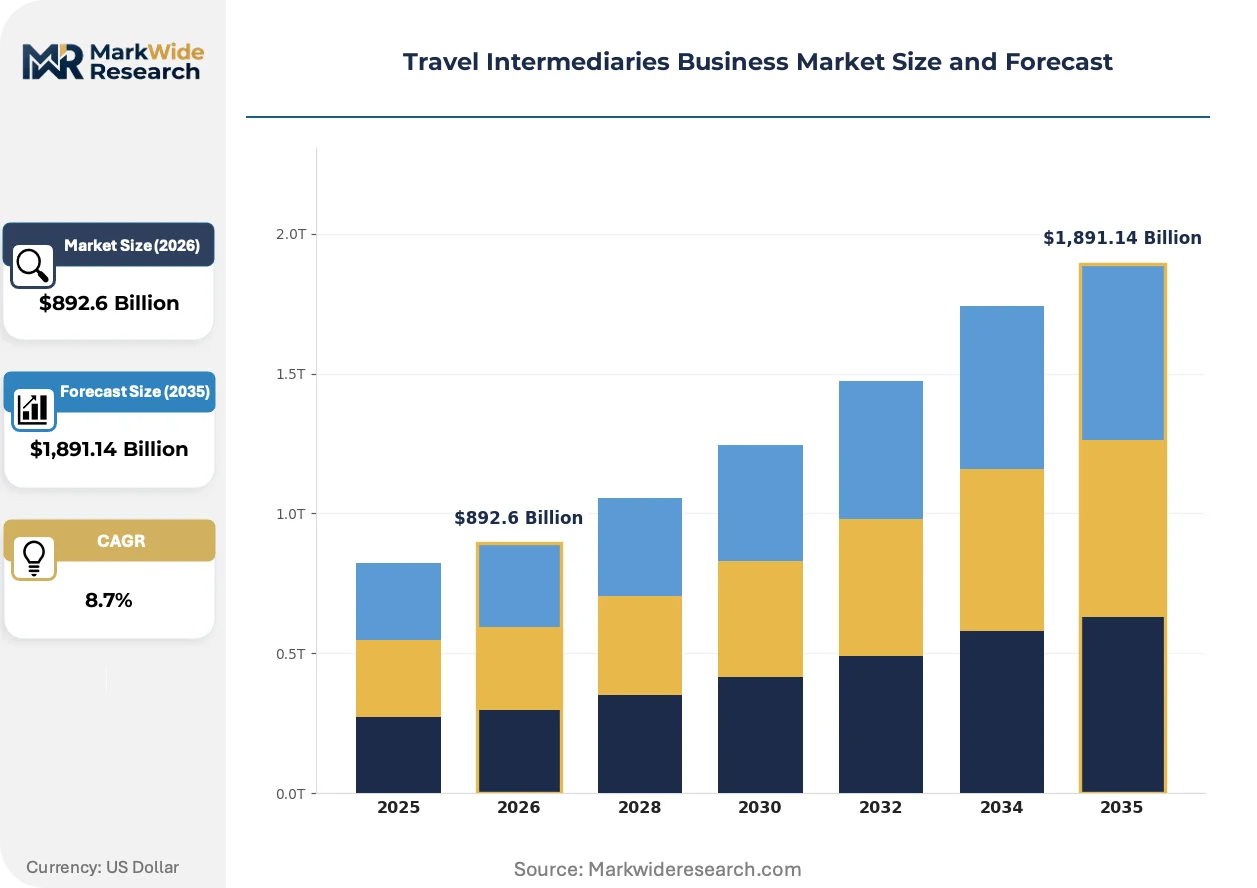
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,891.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Travel Agencies, Online Travel Agents, Tour Operators, Corporate Travel Services Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Government Travelers Distribution Channel: Direct Booking, Third-Party Booking, Mobile Apps, Booking Engines Technology: Booking Software, CRM Systems, Payment Gateways, Data Analytics |
| Companies Covered | Trip.com Group, Internova Travel Group, Booking Holdings, FCM Travel, Spotnana, Expedia Group, Navan, SAP Concur, American Express Global Business Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Intermediaries Business Market Evolving Landscape
Artificial intelligence is compressing the gap between traveler intent and booking completion, while regulatory frameworks reshape intermediary liability and platform accountability across major economies.
Generative AI itinerary builders are rendering obsolete the traditional call-center consultation model for complex multi-destination corporate trips. Multinational enterprises with distributed workforces are adopting these tools at accelerating pace, compressing the role of human agents to exception handling and policy escalation. The technology is rendering obsolete the tiered service model that separated self-service from assisted booking.
The US Department of Transportation enforces expanded airline fee disclosure rules that mandate itemized pricing transparency across all booking channels. This regulatory pressure forces intermediaries to reengineer display algorithms and supplier data feeds. American corporate travel platforms face the steepest compliance costs as they reconcile DOT requirements with client-specific negotiated rate confidentiality.
Mobile-first booking behavior has shifted volume decisively away from desktop interfaces and call-center operations toward native applications with one-tap confirmation. The leisure segment leads this migration, but corporate travelers increasingly expect consumer-grade mobile experiences within policy-controlled environments. This pattern is most visible in the United States, where business traveler smartphone penetration and employer BYOD policies enable seamless platform adoption.
Travel Intermediaries Business Market Segmentation
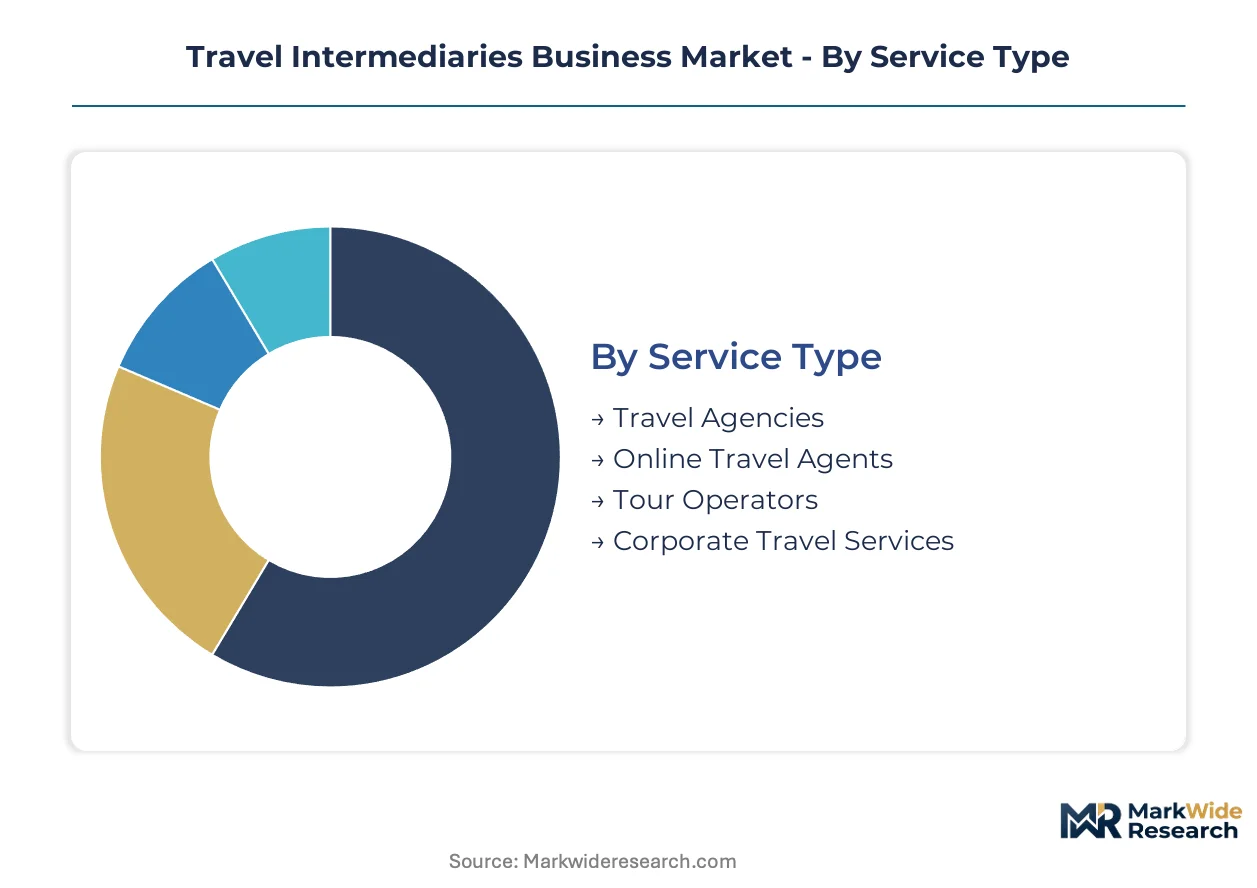
Segmentation in travel intermediaries reveals distinct operational models, each demanding specialized platform architecture and supplier negotiation strategies. Service type and customer dynamics determine margin structure, while distribution channel and technology investments shape competitive defensibility.
Service Type:
Mature segments dominate revenue concentration, though emerging formats are capturing disproportionate technology investment and user migration.
- Travel Agencies:Traditional storefront and call-center operations persist through complex itinerary construction and high-touch corporate account management. Demand concentrates among leisure travelers in Germany and Japan seeking multi-destination packages with human oversight.
- Online Travel Agents:Digital-native platforms aggregate fragmented inventory through API-connected supplier networks, capturing mobile-first booking behavior. Volume concentrates in the United States where consumer-grade app experiences drive leisure segment conversion.
- Tour Operators:Curated package providers bundle transportation, lodging, and experiences through contracted supplier blocks.
- Corporate Travel Services:Managed programs integrate policy enforcement, duty-of-care protocols, and expense reconciliation for enterprise accounts.
Travel Agencies retain volume leadership; Online Travel Agents hold the steepest expansion curve.
Customer Type:
Margin profiles diverge sharply across customer categories, with procurement complexity and booking frequency determining platform stickiness.
- Leisure Travelers:Price-sensitive individual bookers drive volume through comparison shopping and promotional responsiveness. Demand concentrates in mobile app channels where one-tap confirmation reduces abandonment.
- Business Travelers:Policy-constrained road warriors require real-time policy enforcement and integrated expense submission. Fortune 500 reinvestment in managed programs drives premium pricing capture in the United States.
- Group Travelers:Coordinated multi-passenger bookings demand block inventory holds and customized payment splitting.
- Government Travelers:Federally mandated compliance requirements and contracted rate access create specialized procurement workflows.
Leisure Travelers anchor transaction volume; Business Travelers command the highest revenue per booking.
Distribution Channel:
Channel economics reflect shifting infrastructure investments, with platform-native interfaces displacing intermediary-dependent discovery.
- Direct Booking:Supplier-proprietary websites and apps bypass intermediary commissions through loyalty program incentives. Hotel chains in the United States leverage member-only rates to shift share from third-party platforms.
- Third-Party Booking:Aggregator and affiliate channels capture comparison-driven demand through metasearch and referral partnerships.
- Mobile Apps:Native smartphone applications enable geolocation, push notification, and biometric payment integration.
- Booking Engines:White-label reservation systems embed within corporate intranets and partner websites.
Third-Party Booking maintains broadest reach; Mobile Apps demonstrate the sharpest adoption acceleration.
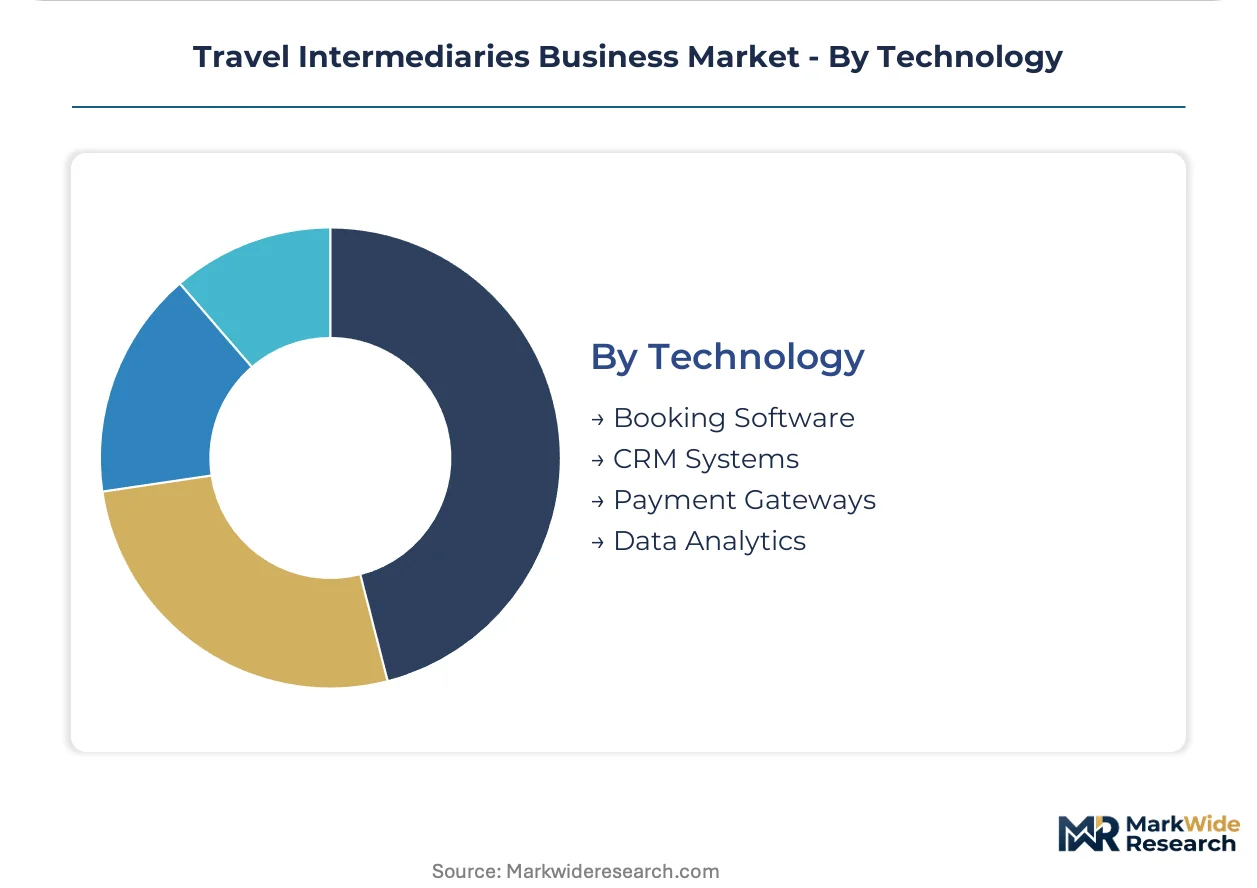
Technology:
Technology stack differentiation determines operational scalability and personalization depth across intermediary operations.
- Booking Software:Core reservation engines integrate global distribution systems, real-time inventory, and dynamic pricing algorithms. Corporate platforms in the United States prioritize API connectivity with SAP and Oracle ERP systems.
- CRM Systems:Customer data platforms enable preference tracking, campaign orchestration, and lifetime value optimization.
- Payment Gateways:Multi-currency transaction processing with fraud detection and corporate card integration.
- Data Analytics:Demand forecasting and supplier negotiation intelligence derived from booking pattern analysis.
Booking Software constitutes the foundational layer; Data Analytics offers the most differentiated competitive leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates asymmetrically between the United States and Germany, where corporate travel program reinvestment outpaces rate negotiation leverage in emerging markets. Intermediary margins compress in price-sensitive leisure corridors while duty-of-care compliance commands premium positioning in enterprise-heavy economies.
United States
Fortune 500 reinvestment in managed travel programs and BYOD-enabled mobile booking adoption drive intermediary demand. The Department of Transportation enforces expanded airline fee disclosure rules that reengineer platform display algorithms. Corporate travel volume concentrates in New York Metro and Chicago, where centralized booking mandates integrate with SAP and Oracle ERP systems.
Germany
Leisure travelers seeking multi-destination packages with human oversight sustain traditional agency storefronts alongside digital migration. The EU Package Travel Directive imposes strict liability requirements that elevate compliance costs for cross-border itinerary construction. Munich and Frankfurt host dense clusters of corporate travel management platforms serving Mittelstand export enterprises.
China
Domestic business travel recovery and platform algorithm oversight reshape intermediary operational constraints. SAMR monitors pricing algorithms under anti-monopoly frameworks, constraining dynamic personalization capabilities. Beijing and Shanghai concentrate online travel agent headquarters integrating payment processing with super-app ecosystems.
India
Small and medium enterprises adopt managed travel programs for the first time, creating greenfield account acquisition potential. DGFT frameworks and emerging data localization requirements complicate cross-border platform architecture. Bengaluru and Mumbai anchor technology development centers for corporate booking engine deployment.
United Kingdom
Post-pandemic corporate travel normalization and GDPR-compliant data infrastructure investments determine platform competitiveness. The Information Commissioner's Office enforces cross-border data transfer restrictions affecting cloud-based itinerary management. London dominates regional headquarters placement for multinational travel management companies serving European enterprise accounts.
Travel Intermediaries Business Market Competitive Landscape
Global-scale aggregators and integrated corporate service providers split the market between volume-driven leisure conversion and policy-enforced enterprise retention. The vendor base concentrates around three strategic archetypes: digital-native online travel agents with mobile-first architectures, legacy travel management companies with duty-of-care protocols, and embedded finance platforms merging booking with expense automation. Competitive positioning hardens through API ecosystem partnerships and vertical consolidation into ancillary travel services.
Within the integrated corporate services tier, American Express Global Business Travel and SAP Concur exemplify divergent approaches to enterprise account stickiness, while Booking Holdings occupies a position spanning both leisure aggregation and negotiated rate access for managed programs. Trip.com Group anchors the Asia-Pacific digital-native archetype with super-app convergence strategies.
| Leading Market Players |
|---|
| Trip.com Group |
| Internova Travel Group |
| Booking Holdings |
| FCM Travel |
| Spotnana |
| Expedia Group |
| Navan |
| SAP Concur |
| American Express Global Business Travel |
| Others |
Value Network & Pricing Analysis
Global distribution system providers in the United States and Europe anchor upstream technology costs, concentrating margin capture among intermediaries with direct airline and hotel chain partnerships that bypass legacy transaction fees.
Pricing Analysis
The customization-premium spread between configured corporate travel programs and standard leisure bookings defines intermediary margin architecture. Three-tier pricing structure across premium managed services, mid-market self-service platforms, and economy leisure aggregation captures divergent buyer willingness-to-pay. Price differentiation hinges on duty-of-care protocol depth and ERP integration complexity. Cost compression in the leisure tier intensifies as supplier direct channels erode commission structures, while Fortune 500 accounts exhibit lowest price sensitivity due to bundled compliance requirements.
Supply Chain Analysis
Supplier-financing facilities extended by major hotel chains and global airlines reshape working capital demands for intermediary platforms operating on thin transaction margins. Technology development concentrates in the United States, India, and China, with booking engine architecture drawing from cloud infrastructure providers and payment gateway specialists. Raw material dependencies include GDS connectivity licenses, biometric authentication modules, and multi-currency settlement rails. Single-source vulnerability around legacy GDS providers threatens margin stability. Distribution runs through API-connected supplier networks, white-label corporate portals, and native mobile applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network effects from accumulated traveler preference data and entrenched corporate procurement relationships create defensive moats that compound with each additional enterprise account integration.
For Market Incumbents: Entrench platform stickiness through deeper ERP connectivity with SAP and Oracle systems, while expanding duty-of-care protocol suites to counter emerging AI-native competitors. Capacity addition in India and Southeast Asia addresses the formalization wave among small and medium enterprises. Certification investment in EU AI Act compliance frameworks creates advisory revenue streams that offset transaction margin pressure.
For New Entrants and Emerging Players: Pursue greenfield corporate travel management adoption among Indian SMEs and mid-market European enterprises underserved by legacy travel management company infrastructure. Embedded finance convergence—integrating corporate card issuance with real-time expense reconciliation—offers the most penetrable wedge against established platforms. A mobile-first, API-native architecture with consumer-grade user experience accelerates land-and-expand adoption cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platforms combining booking technology with captive expense management workflows, as these exhibit superior account retention and data monetization potential. Long-term viability favors intermediaries with demonstrated AI governance compliance and cross-border data infrastructure resilient to GDPR and emerging national localization mandates. The signal to watch is Fortune 500 procurement committee consolidation toward fewer, deeper platform relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration Deepening | API connectivity with SAP and Oracle systems locks in enterprise procurement workflows. |
| AI Governance Compliance | EU AI Act advisory services create differentiated revenue streams beyond transaction fees. |
| Embedded Finance Convergence | Corporate card issuance integration with booking platforms extends platform stickiness. |
| Mobile-First Architecture | Native application deployment captures BYOD-enabled business traveler booking behavior. |
| Duty-of-Care Protocol Expansion | Integrated traveler safety services command premium pricing in enterprise accounts. |
Research Methodology
A standing panel of corporate travel managers, expense platform procurement officers, airline distribution executives, and hotel chain revenue management directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings from publicly traded intermediaries, IATA airline distribution reports, and EU regulatory transparency databases. Bottom-up triangulation across booking volume estimates and top-down reconciliation against industry association aggregates anchored market sizing.
Scenario-bracketing around corporate travel recovery trajectories and AI adoption curves framed the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, customer category, distribution channel, and technology stack tier. CAGRs were derived from fitted growth curves against historical booking pattern analysis, with inputs from global distribution system transaction disclosures and corporate managed program reinvestment surveys.
Sensitivities concentrate around airline fee disclosure rule evolution, AI governance framework implementation timing, and corporate travel policy normalization rates. Forecasts reflect assumptions on intermediary commission structures and supplier direct channel investment levels. Macroeconomic contraction, regulatory deviation, or generative AI disruption of traditional booking workflows would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Sports Tourism Market
Travel and Tourism
B2B Travel Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
India Outbound Tourism Market