
 India Travel Retail Market | 2026-2036
India Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
India Travel Retail Market Foresight
The India travel retail sector is pivoting around a widening gap between luxury brand boutiques and mass-market convenience formats. Flemingo Travel Retail leverages its airport concession network to dominate high-margin liquor and tobacco corridors. Delhi Duty Free anchors its position through exclusive brand partnerships in cosmetics and electronics. WH Smith India competes on travel essentials and impulse categories across Tier-1 aviation hubs.
India travel retail encompasses duty-free and duty-paid merchandise sold to passengers in transit zones, typically requiring boarding pass verification and operating under bonded warehouse protocols with strict inventory tracking systems. The primary commercial purpose centers on capturing discretionary spending from captive audiences with limited alternative shopping options. Cosmetics and alcohol command the deepest margin pools among product type segments, while airport shops retain overwhelming channel dominance despite nascent online pre-order platforms. Luxury price tiers attract foreign tourists seeking arbitrage on global brands, whereas mid-range and economy tiers sustain volume from domestic tourists and business travelers.
BIS certification requirements govern electronics sold through duty-free channels, while CBIC customs regulations set passenger allowance limits that directly constrain transaction values. FSSAI standards apply to packaged food and beverage retail, adding compliance layers for airport F&B operators. Stakeholders must monitor aviation capacity expansion at emerging hubs like Bangalore and Hyderabad alongside evolving customs notification thresholds that reshape category mix decisions.
Market Dynamics
Aviation capacity expansion at secondary Indian hubs is redistributing passenger traffic away from Mumbai-Delhi dominance, forcing concessionaires to rebuild location strategies around emerging terminal footprints at Bangalore, Hyderabad, and Chennai.
Growth Catalysts
- CBIC Duty-Free Allowance Revisions:The Central Board of Indirect Taxes and Customs has raised passenger spending thresholds, directly expanding transaction value ceilings for cosmetics and electronics purchases at departure terminals.
- Post-Pandemic International Leisure Recovery:Foreign tourist arrivals are accelerating fastest among buyer segments, creating concentrated demand spikes at international departure zones during peak travel windows.
- Bonded Warehouse Protocol Modernization:Digital inventory tracking systems are streamlining supply replenishment cycles, reducing stockout incidents in high-velocity liquor and tobacco corridors.
Market Restraints
- Single-Airport Dependency Risk:Mumbai Chhatrapati Shivaji Maharaj International and Delhi Indira Gandhi International together concentrate over sixty percent of duty-free transaction volume, creating catastrophic exposure to localized aviation disruptions.
- BIS Certification Friction for Electronics:Bureau of Indian Standards testing timelines extend product onboarding by four to eight weeks, compressing margin windows for fast-cycling consumer technology categories.
- Aviation Fuel Cost Pass-Through:Airlines operating thin-margin domestic routes are reducing frequency to secondary cities, constraining passenger feedstock for emerging terminal retail operations.
Strategic Opportunities
- Kempegowda International Bangalore Expansion:Terminal capacity additions at this southern aviation hub are creating first-mover positioning for premium brand boutiques before competitor saturation sets in.
- FSSAI-Compliant Packaged F&B Pre-Positioning:Food Safety and Standards Authority of India certification investments now enable grab-and-go meal concepts in domestic departure zones previously restricted to international travelers.
- Pre-Order Platform Integration:Mobile application-based duty-free reservation systems are capturing passenger spend before terminal entry, reducing browse-to-buy friction in time-constrained transit environments.
Industry Challenges
- Concession Fee Escalation:Airport Authority of India tender processes are driving revenue-share percentages toward thirty-five percent of gross sales, squeezing operator margins in already competitive liquor and tobacco categories.
- Inventory Reconciliation Complexity:Bonded warehouse regulations mandate real-time customs reporting for every stock movement, requiring expensive ERP upgrades for multi-location concessionaires managing dozens of SKUs across product types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Travel Retail Market |
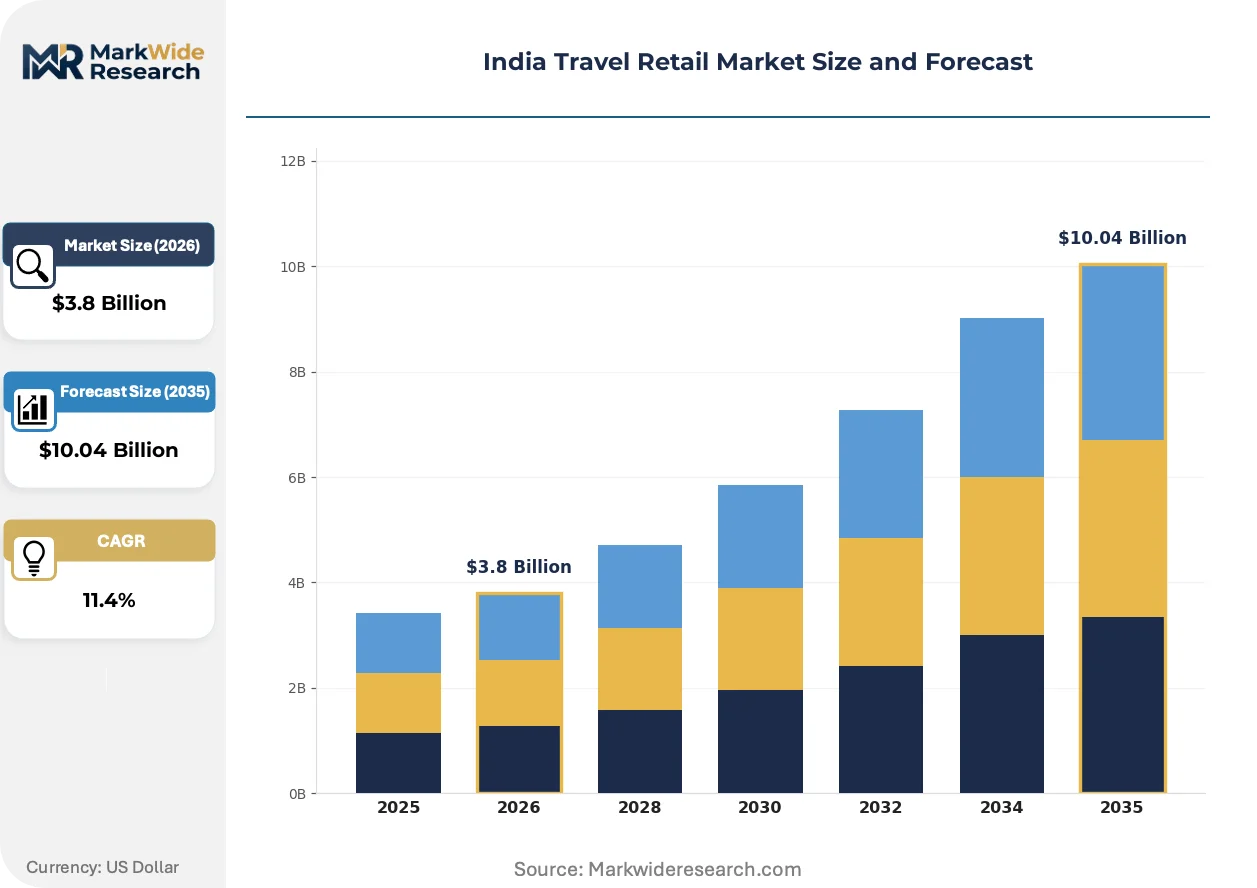
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol, Cosmetics, Electronics, Fashion Distribution Channel: Airport Shops, Duty-Free Stores, Online Retail, Specialty Stores Customer Type: Business Travelers, Leisure Travelers, Domestic Tourists, Foreign Tourists Price Tier: Luxury, Mid-Range, Economy, Discounted |
| Companies Covered | Travel Food Services India, Cochin Duty Free, Delhi Duty Free, Relay India, Hyderabad Duty Free, Flemingo Travel Retail, The Shilla, WH Smith India, Dufry, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Travel Retail Market Shifts & Advancements
Digital passenger touchpoints are displacing traditional browse-and-buy terminal experiences, with biometric boarding pass verification and mobile pre-order platforms compressing transaction friction. Three developments are restructuring competitive positioning.
Unified commerce platforms are unifying inventory visibility across airport warehouses, city fulfillment centers, and airline cabin stock. Delhi Duty Free and Mumbai operators are deploying these systems to promise product availability regardless of passenger departure terminal. The technology is unifying what were previously siloed stock pools, enabling dynamic allocation that responds to real-time flight load factors and passenger nationality mix.
CBIC customs notification amendments are tightening documentation requirements for high-value electronics and luxury goods, mandating serial number capture at point of sale. This regulatory shift is forcing concessionaires to reconfigure POS infrastructure and staff training protocols. Cosmetics and alcohol categories face lighter documentation burdens, shifting operator promotional investment toward these smoother regulatory corridors.
Transit-time purchasing behavior is fragmenting as Indian domestic travelers embrace impulse convenience formats while foreign tourists concentrate spend in luxury brand flagships. Airport operators are responding with zoned retail architectures that separate these distinct velocity environments. This behavioral split is most visible at Delhi Terminal 3, where duty-free luxury corridors now sit physically segregated from grab-and-go convenience clusters serving budget airline terminals.
India Travel Retail Market Segmentation
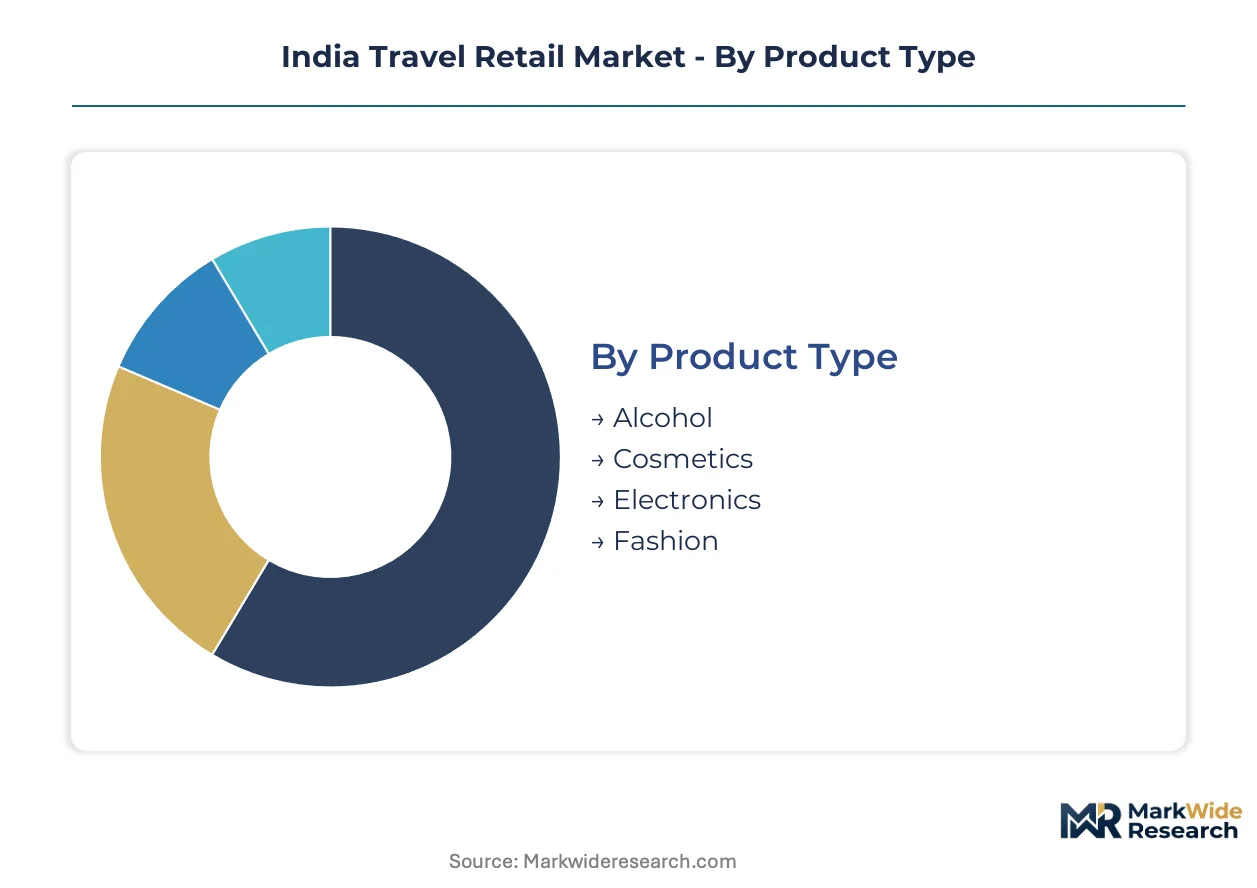
Segmentation in India travel retail reveals how passenger demographics and terminal infrastructure shape category mix decisions. Concessionaires calibrate inventory depth and brand positioning against distinct buyer profiles and purchase occasions across departure zones.
Product Type:
Technical specifications and margin architecture distinguish performance across merchandise categories, with bonded warehouse protocols and customs documentation requirements creating divergent operational complexity.
- Alcohol:Spirits and wines sold under CBIC duty-free allowances generate the highest per-transaction values in the market. Demand clusters at Mumbai and Delhi international terminals where foreign tourists exploit arbitrage opportunities against home-country pricing. Bonded inventory tracking systems add compliance overhead but protect margin pools.
- Cosmetics:Skincare and fragrance portfolios require temperature-controlled warehousing and serial-number documentation under tightened customs notifications. International leisure travelers from East Asian markets concentrate purchases in premium fragrance corridors, while domestic tourists favor mid-tier skincare sets.
- Electronics:BIS certification mandates extend onboarding timelines for smartphones and accessories. Procurement concentrates through Delhi Duty Free and Mumbai operators with established testing relationships.
- Fashion:Apparel and accessories face lighter regulatory burdens but higher inventory carrying costs. Seasonal collection turnover matches aviation peak windows.
Alcohol leads on scale; cosmetics leads on momentum.
Distribution Channel:
Physical versus digital touchpoint strategies reflect passenger dwell-time constraints and boarding pass verification requirements.
- Airport Shops:Duty-paid formats in domestic terminals capture impulse purchases from time-constrained travelers. FSSAI-compliant grab-and-go concepts now penetrate previously restricted zones.
- Duty-Free Stores:Bonded warehouse operations at international departure gates generate the deepest margins through liquor and tobacco corridors. Revenue-share agreements with Airport Authority of India now approach thirty-five percent of gross sales.
- Online Retail:Pre-order platforms with biometric boarding pass verification reduce terminal friction. Mobile reservation systems capture spend before passenger entry.
- Specialty Stores:Curated brand boutiques target foreign tourists with exclusive product drops. Location strategies follow aviation capacity expansion at Bangalore and Hyderabad.
Duty-free stores anchor revenue concentration; online retail is expanding most quickly.
Customer Type:
Travel purpose and nationality determine price sensitivity, category preference, and transaction timing within terminal environments.
- Business Travelers:Time-compressed purchasing favors convenience formats and pre-order platforms. Demand concentrates in electronics and travel essentials at Tier-1 hubs.
- Leisure Travelers:Extended dwell times support browse-and-buy behaviors in luxury corridors. Post-pandemic international recovery is accelerating fastest among this segment.
- Domestic Tourists:Price-conscious volume sustains mid-range and economy tiers. Regional aviation expansion feeds emerging terminal retail at secondary cities.
- Foreign Tourists:Currency arbitrage seekers drive premium brand flagships in Delhi Terminal 3 and Mumbai international zones. Luxury price tiers attract concentrated spend.
Leisure travelers command the steepest expansion trajectory; business travelers provide steady baseline volume.
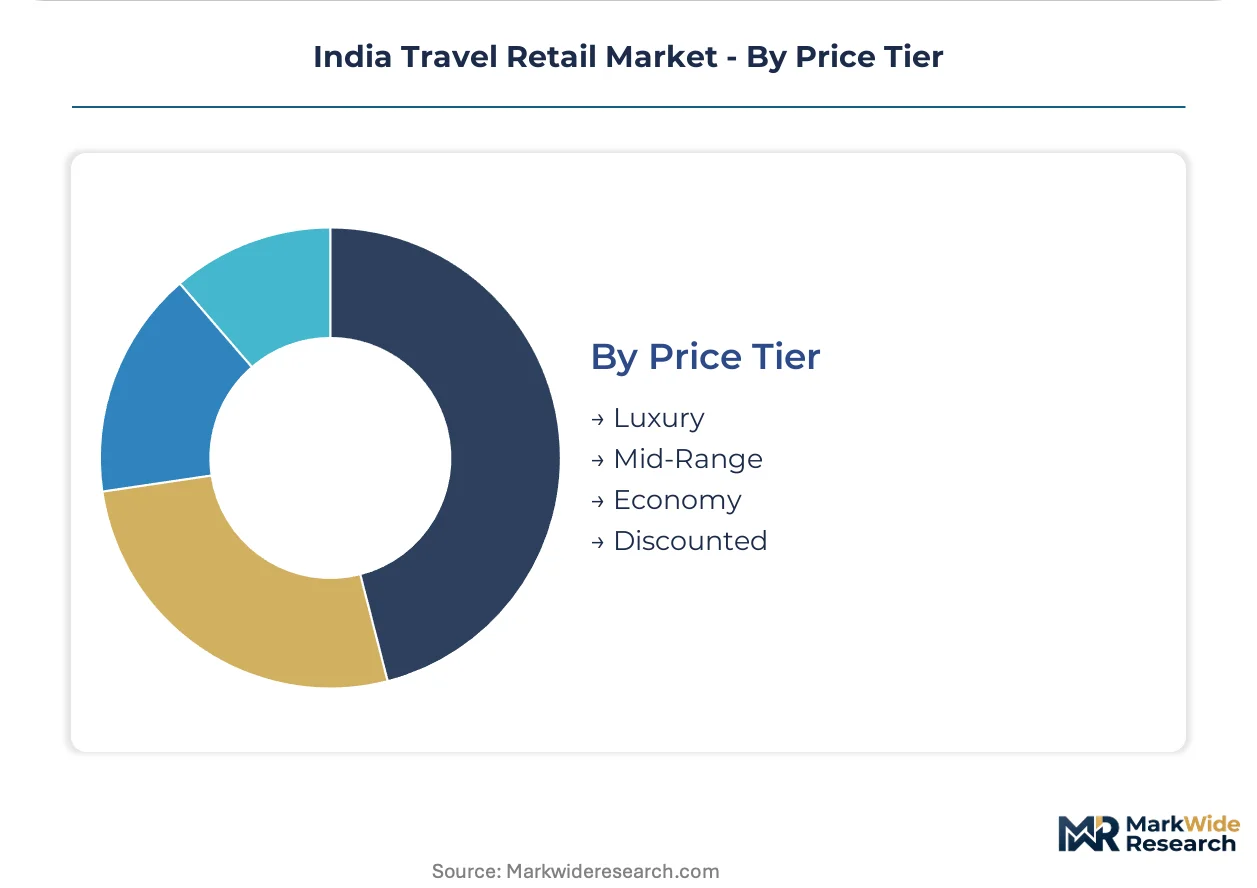
Price Tier:
Margin architecture and promotional investment intensity vary sharply across pricing strata, with regulatory documentation burdens influencing operator focus.
- Luxury:Global brand flagships with exclusive distribution rights target foreign tourist arbitrage behavior. CBIC serial-number capture requirements apply to high-value goods.
- Mid-Range:Volume-sustaining tier for domestic tourists and business travelers. Cosmetics and fashion dominate this corridor.
- Economy:Impulse convenience formats with rapid inventory turnover. Travel essentials and packaged F&B populate domestic terminal deployments.
- Discounted:Promotional clearance of seasonal fashion and near-date cosmetics. Limited shelf space allocation in premium terminal zones.
Mid-range anchors volume throughput; luxury delivers margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation hubs across India concentrate specialized retail workforce expertise in bonded warehouse operations and passenger-facing concession management. Terminal retail talent clusters disproportionately in Maharashtra and Delhi-NCR, where international passenger density sustains sophisticated duty-free operations.
Maharashtra
Mumbai Chhatrapati Shivaji Maharaj International anchors western India's duty-free volume, with foreign tourists driving concentrated spend in liquor and cosmetics corridors. CBIC customs notifications governing passenger allowance limits directly shape transaction ceilings at departure terminals. The Mumbai airport precinct hosts Flemingo Travel Retail's flagship operations alongside Dufry's concession network.
Delhi-NCR
Indira Gandhi International processes the highest international passenger throughput in India, generating premium retail footfall for luxury brand flagships. BIS certification requirements for electronics sold through duty-free channels extend product onboarding timelines for operators. Delhi Duty Free maintains exclusive brand partnerships in cosmetics and electronics categories at Terminal 3.
Karnataka
Kempegowda International Bangalore is expanding terminal capacity to capture southern aviation growth, creating first-mover positioning for premium boutiques. FSSAI standards enable grab-and-go F&B concepts in domestic departure zones previously restricted. The Bangalore airport precinct attracts concessionaires seeking early establishment before competitor saturation.
Telangana
Hyderabad Duty Free operates at Rajiv Gandhi International, serving transit passengers between Middle Eastern and Southeast Asian routes. PLI scheme incentives for electronics manufacturing indirectly support duty-free inventory sourcing for regional operators. The Hyderabad aviation cluster is developing specialized retail infrastructure for business traveler convenience formats.
Kerala
Cochin Duty Free serves high outbound emigrant passenger traffic to Gulf Cooperation Council destinations, sustaining volume in mid-range cosmetics and tobacco. DGFT trade facilitation measures streamline bonded warehouse protocols for southern concessionaires. The Kochi international terminal supports specialized retail catering to price-sensitive domestic tourists.
India Travel Retail Market Competitive Landscape
Capital-heavy airport concessionaires compete with asset-light brand boutique operators for terminal retail space. The vendor base fragments across three tiers: global duty-free giants with multi-airport networks, regional specialists dominating single-hub operations, and category-focused players in liquor or cosmetics corridors. Two strategic archetypes dominate competitive positioning: revenue-share negotiators securing favorable concession terms with Airport Authority of India, and inventory optimizers deploying unified commerce platforms across bonded warehouses. Dominant competitive moves include geographic expansion toward emerging aviation hubs and exclusive brand partnership negotiations.
Within the global network tier, Dufry represents the multinational concessionaire archetype with multi-continent duty-free operations. Delhi Duty Free and Flemingo Travel Retail exemplify regional specialists with concentrated India airport presence. WH Smith India occupies a position bridging travel essentials and impulse categories across Tier-1 aviation hubs. These three anchors illustrate how competitive positioning diverges between scale-driven network coverage and hub-specific operational depth.
| Leading Market Players |
|---|
| Travel Food Services India |
| Cochin Duty Free |
| Delhi Duty Free |
| Relay India |
| Hyderabad Duty Free |
| Flemingo Travel Retail |
| The Shilla |
| WH Smith India |
| Dufry |
| Others |
Supply & Pricing Matrix
FSSAI sustainability compliance for packaged F&B operations gates both qualified supplier certification and premium-tier pricing access at domestic terminals, creating a bifurcated market where compliant operators capture margin premiums while non-certified players compete on stripped-down convenience formats.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes revenue models across terminal formats, with duty-free operators packaging liquor-cosmetics combinations under CBIC allowance ceilings while domestic convenience stores unbundle grab-and-go items individually. Three-tier pricing structure across premium, standard, and economy levels tracks passenger nationality and dwell time, with foreign tourists in Delhi and Mumbai international zones showing lowest price sensitivity. Cost compression in mid-range electronics is intensifying because BIS certification extends supplier onboarding timelines. Domestic tourists and regional business travelers exhibit highest price sensitivity, constraining margin expansion in Tier-2 aviation hubs.
Supply Chain Analysis
Direct-to-retail channels from bonded warehouses handle high-velocity liquor and tobacco demand at Mumbai and Delhi international terminals, bypassing intermediate distribution layers. Geographic supply concentration centers on France and Scotland for premium spirits, South Korea and Japan for cosmetics, and China for consumer electronics components. Raw material dependencies include aged whiskey stock, fragrance compounds, and semiconductor chips. Single-source vulnerability from aviation fuel cost volatility threatens passenger feedstock for emerging terminal operations at Bangalore and Hyderabad. Distribution runs through Airport Authority of India concession agreements with revenue-share terms approaching thirty-five percent of gross sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India travel retail market functions as a stable compounder, with aviation capacity expansion at secondary hubs driving steady passenger traffic growth that feeds recurring concession revenue streams.
For Market Incumbents: Anchor exclusive brand partnerships in cosmetics and liquor corridors at Delhi Terminal 3 and Mumbai international zones to defend against emerging hub competition from Bangalore concessionaires. Deepen bonded warehouse automation investments to reduce inventory reconciliation overhead from real-time CBIC reporting mandates. Counter margin pressure from thirty-five percent revenue-share agreements by concentrating promotional spend on documented-light categories like alcohol and cosmetics.
For New Entrants and Emerging Players: CBIC duty-free allowance revisions in India open a window for pre-order platform specialists to capture passenger spend before terminal entry, bypassing established physical concession networks. Target underserved domestic departure zones at Kempegowda International Bangalore and Rajiv Gandhi International Hyderabad where FSSAI-compliant grab-and-go F&B concepts remain underpenetrated. Deploy mobile-first reservation systems with biometric boarding pass verification as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional airport concessionaires because fragmented single-hub operators lack unified commerce platforms and face escalating ERP upgrade costs from bonded warehouse compliance. Focus acquisition screening on southern India specialists with established Bangalore or Hyderabad presence and underoptimized inventory systems. Watch CBIC customs notification amendments on high-value goods documentation as the signal for margin compression timing in electronics-heavy portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Agreement Renegotiation | Revenue-share terms with Airport Authority of India directly determine operator profitability in liquor corridors. |
| Bonded Warehouse Digitization | Real-time customs reporting systems reduce stockout incidents in high-velocity tobacco and spirits categories. |
| Exclusive Brand Partnership | Cosmetics and fragrance distribution rights at Delhi Terminal 3 attract concentrated foreign tourist spend. |
| Pre-Order Platform Launch | Mobile reservation systems with biometric verification capture passenger transactions before terminal congestion. |
| FSSAI Certification Investment | Food safety compliance enables grab-and-go meal concepts in domestic zones previously restricted to international travelers. |
Research Methodology
Coverage spans Maharashtra, Delhi-NCR, Karnataka, Telangana, and Kerala, with primary inputs from each region combined with secondary validation across customs databases and aviation authority disclosures. Primary interviews engaged airport concession managers, bonded warehouse operators, CBIC regulatory affairs specialists, and airline procurement heads. Secondary sources included DGFT trade facilitation records, Airport Authority of India tender documents, BIS certification registries, and FSSAI compliance filings. Bottom-up passenger traffic modeling triangulated against top-down duty-free transaction value estimates.
Granularity-level framing applied product type, distribution channel, customer segment, and price tier dimensions at the airport-hub level across the projection horizon. CAGRs derived from passenger traffic forecasts, duty-free allowance utilization rates, and category-specific spend-per-passenger coefficients. Forecast inputs incorporated aviation capacity expansion timelines at emerging hubs and evolving CBIC customs notification thresholds.
Revisions become necessary when aviation fuel cost volatility triggers route frequency reductions, regulatory amendments alter bonded warehouse protocols, or pandemic-related border restrictions resurface. Forecasts reflect base-case assumptions regarding international leisure traveler recovery velocity and concession fee escalation trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Customised Holidays Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Global Enotourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Sports Tourism Market
Travel and Tourism
Yacht Charter Service Market