
 Russia Outbound Tourism Market | 2026-2036
Russia Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Outbound Tourism Market Analytics
Federal Law No. 132-FZ on the Fundamentals of Tourist Activity is rebalancing compliance burdens for operators serving Russian travelers. Pegas Touristik leverages its integrated charter-flight networks to sustain price competitiveness on mass-market routes to Antalya and Sharm el-Sheikh. Tez Tour anchors its position through direct contracts with Mediterranean and Red Sea hoteliers, bypassing intermediary markups. Sletat.ru competes as a meta-search platform, aggregating inventory from multiple suppliers to control comparison-shopping traffic.
Russia outbound tourism encompasses all temporary departures by Russian residents for leisure, business, education, or medical purposes, typically involving stays of up to one year and requiring cross-border documentation, currency exchange, and transport logistics coordination. The sector functions as a foreign-exchange outflow channel, a services-trade deficit contributor, and a demand generator for international hospitality, aviation, and insurance industries. Leisure travel dominates volume flows to Turkey and Egypt, while business travel commands premium pricing through shorter booking windows and flexible cancellation terms. Medical travel to South Korea and Israel represents the fastest-growing margin pool, driven by aging demographics and domestic capacity constraints in specialized care. Online travel agencies capture growing share among urban millennials, though travel agents retain loyalty among family segments seeking package-trip security.
Russia's Federal Agency for Tourism (Rostourism) enforces operator licensing and financial guarantee requirements, while the Central Bank of Russia monitors foreign-currency transaction reporting for cross-border payments. Turkey's Ministry of Culture and Tourism coordinates with Russian regulators on bilateral safety protocols and charter-flight permissions. The UAE's Federal Authority for Identity and Citizenship manages visa-on-arrival eligibility that shapes last-minute booking patterns. Stakeholders must track shifts in bilateral aviation agreements and payment-system interoperability as sanctions-era financial fragmentation continues to alter how Russian travelers fund and document foreign trips.
Market Dynamics
Visa facilitation agreements between Russia and destination states are compressing booking friction for middle-class families, while payment-system fragmentation forces operators to maintain multi-channel foreign-currency settlement infrastructure.
Growth Catalysts
- Digital Booking Platforms:Meta-search engines aggregate inventory from fragmented suppliers, reducing search costs for urban millennials planning independent trips.
- Federal Law No. 132-FZ:Russia's tourism law streamlines operator licensing while mandating financial guarantees that stabilize consumer trust in package purchases.
- Turkey:Simplified entry protocols and bilateral aviation agreements sustain charter-flight volumes to Antalya and coastal resort zones.
Market Restraints
- Payment Infrastructure:Sanctions-era exclusion from SWIFT forces reliance on Mir card networks and cash-based settlement, elevating transaction costs for cross-border bookings.
- Aviation Capacity Concentration:Dependence on Russian and Turkish carriers for mass-market routes creates vulnerability to bilateral diplomatic friction or airspace restrictions.
- Domestic Medical Capacity:Shortfalls in specialized oncology and cardiology care accelerate outflow of high-margin medical travelers, constraining domestic healthcare retention.
Strategic Opportunities
- Medical Travel to South Korea:Aging demographics and domestic capacity gaps position oncology and cosmetic surgery segments for sustained margin expansion.
- Visa-on-Arrival Protocols:UAE Federal Authority for Identity and Citizenship eligibility rules enable last-minute booking patterns that capture impulse-driven leisure demand.
- Direct Hotelier Contracts:Bypassing intermediary markups through exclusive property agreements protects margin compression on Egyptian Red Sea packages.
Industry Challenges
- Foreign-Currency Transaction Reporting:Central Bank of Russia monitoring requirements complicate real-time payment reconciliation for operators managing multi-destination itineraries.
- Charter-Flight Permission Coordination:Bilateral aviation negotiations with Turkish and Egyptian regulators introduce scheduling uncertainty during peak seasonal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Outbound Tourism Market |
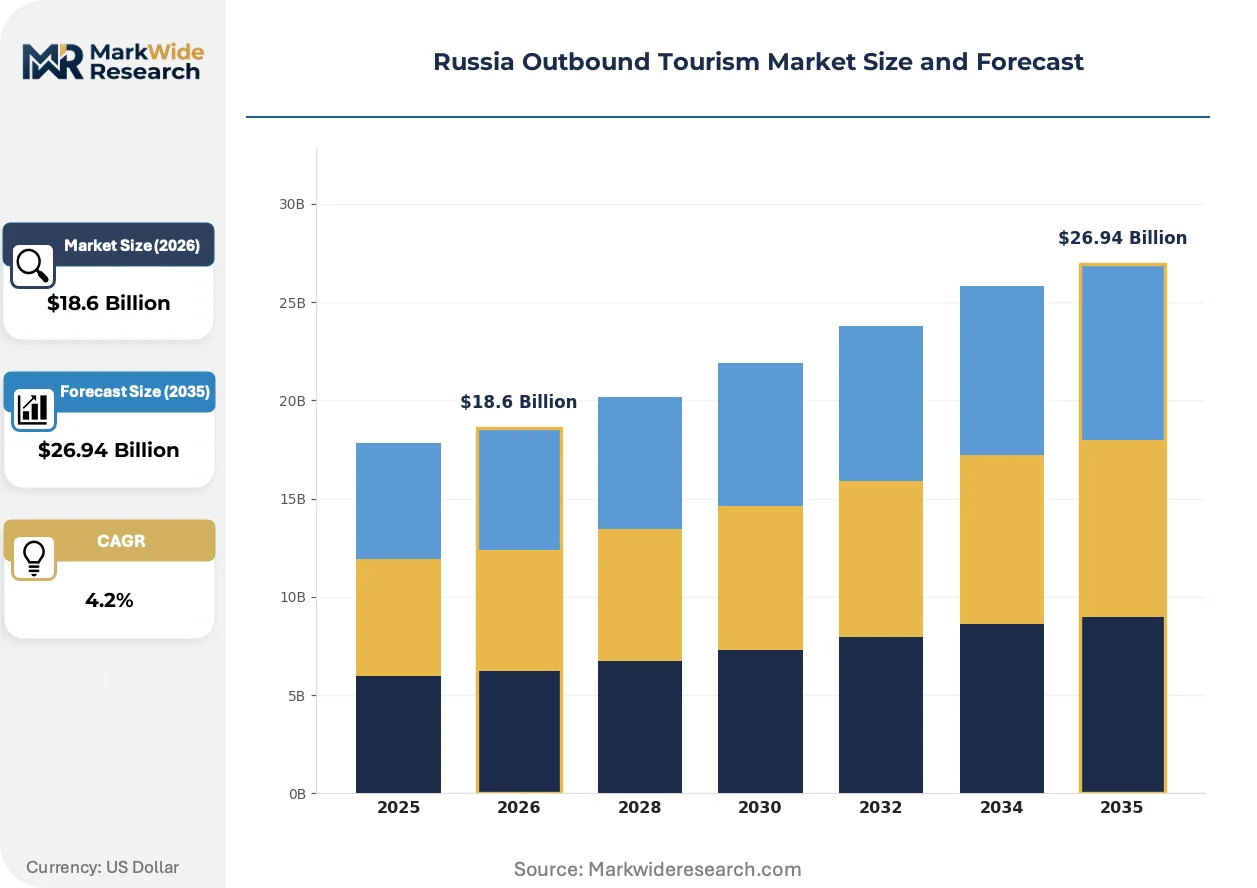
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Leisure Travel, Business Travel, Educational Travel, Medical Travel Preferred Destination: Europe, Asia, North America, Middle East Booking Channel: Online Travel Agencies, Direct Airline Booking, Travel Agents, Mobile Apps Customer Segment: Families, Solo Travelers, Couples, Group Travelers |
| Companies Covered | ReConnect Russia, Russian Association of Tour Operators (ATOR), VolnaTrack, Pegas Touristik, Sletat.ru, ZovStep, EdenRoute, Tez Tour, MIRCraft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Outbound Tourism Market Evolving Landscape
Booking behavior is fragmenting across platform types as legacy package security competes with algorithmic price transparency, while regulatory adaptation in destination states reshapes entry logistics.
Dynamic packaging engines are absorbing manual itinerary assembly tasks previously handled by travel agents. Urban millennials adopt these tools for multi-city Mediterranean routes, compressing commission-dependent distribution structures. The technology is absorbing price comparison functions that once required human intermediation.
Federal Law No. 132-FZ financial guarantee mandates are elevating capital requirements for tour operators. Rostourism enforcement tightens market entry, pushing smaller intermediaries toward consolidation or meta-search platform affiliation. Family segments respond by gravitating toward licensed operators with visible guarantee backing.
Last-minute booking patterns are intensifying around visa-on-arrival eligibility windows. UAE and Turkish entry protocols enable spontaneous departure decisions that bypass traditional advance-purchase package structures. This behavioral shift concentrates demand volatility on inventory-heavy hoteliers in Sharm el-Sheikh and Dubai.
Russia Outbound Tourism Market Segmentation
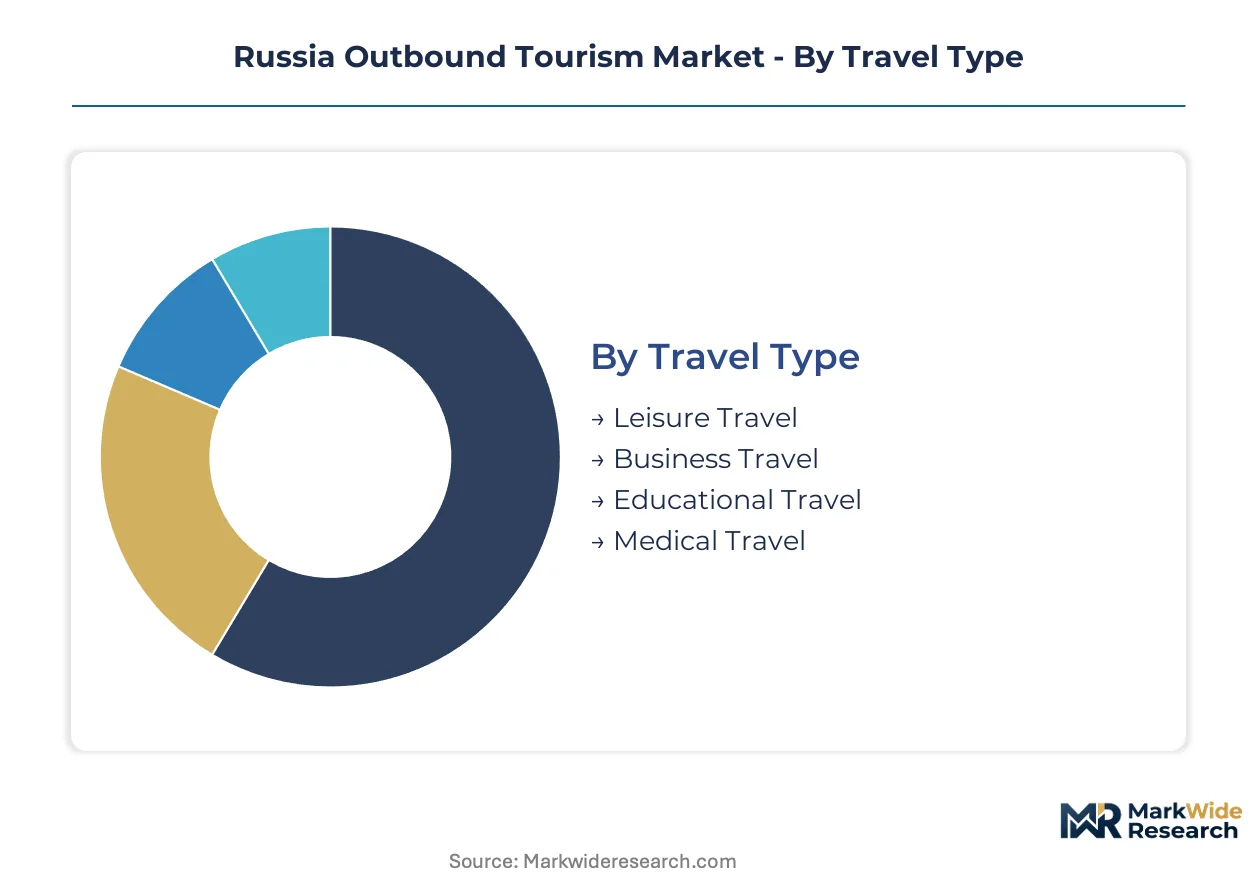
Segmentation in Russia's outbound tourism market reveals how capital deployment, regulatory exposure, and booking behavior diverge across traveler profiles. Operators calibrate inventory, payment infrastructure, and destination mix to these distinct demand pools.
Travel Type:
Capital intensity escalates sharply from leisure packages to medical travel infrastructure, with specialized care coordination requiring the heaviest upfront investment in foreign hospital networks and visa facilitation.
- Leisure Travel:Mass-market packages to Turkish and Egyptian resorts dominate volume flows. Demand concentrates in Antalya and Sharm el-Sheikh where charter-flight networks and all-inclusive hotel contracts compress per-unit acquisition costs for tour operators.
- Medical Travel:Oncology and cosmetic surgery segments in South Korea and Israel command premium pricing through dedicated patient coordinators and treatment pre-qualification. Aging demographics and domestic capacity constraints in specialized Russian care accelerate outflow of high-margin travelers.
- Business Travel:Shorter booking windows and flexible cancellation terms sustain yield premiums. Corporate accounts prioritize direct airline relationships over packaged intermediation.
- Educational Travel:Language immersion and university placement services require sustained counseling infrastructure. Demand clusters in UK and German destination markets with established Russian student pipelines.
Most installed capacity flows through Leisure Travel. Expansion is steepest in Medical Travel.
Preferred Destination:
Destination selection maps directly to payment-system interoperability and bilateral aviation access, with Middle East and Asian corridors absorbing the bulk of redirected demand from restricted Western markets.
- Middle East:UAE visa-on-arrival protocols and Dubai's hospitality infrastructure capture impulse-driven demand. Turkish coastal resorts sustain charter-flight density through Rostourism-coordinated bilateral permissions.
- Asia:South Korean medical facilities and Southeast Asian beach destinations attract aging family segments. Mir card network acceptance varies sharply across national banking systems.
- Europe:Schengen visa friction compresses volumes to premium independent travelers with established documentation capacity. Baltic and Balkan peripheries retain residual package demand.
- North America:Visa interview backlogs and payment-system exclusion constrain flows to essential business and educational segments with dedicated compliance resources.
Most installed capacity flows through Middle East. Expansion is steepest in Asia.
Booking Channel:
Channel economics split between commission-heavy human intermediation and technology-driven self-service, with mobile penetration reshaping last-minute purchase patterns among urban millennials.
- Online Travel Agencies:Meta-search aggregation reduces search costs for independent trip planners. Sletat.ru and comparable platforms capture comparison-shopping traffic through multi-supplier inventory display.
- Travel Agents:Family segments seeking package-trip security retain loyalty to licensed operators with visible Federal Law No. 132-FZ financial guarantees. Commission structures persist where cancellation protection carries premium value.
- Direct Airline Booking:Business travelers and frequent flyers bypass intermediary markups through carrier loyalty programs and corporate account direct billing.
- Mobile Apps:Spontaneous departure decisions concentrate demand volatility on inventory-heavy hoteliers in visa-on-arrival destinations like Dubai.
Most installed capacity flows through Online Travel Agencies. Expansion is steepest in Mobile Apps.
Customer Segment:
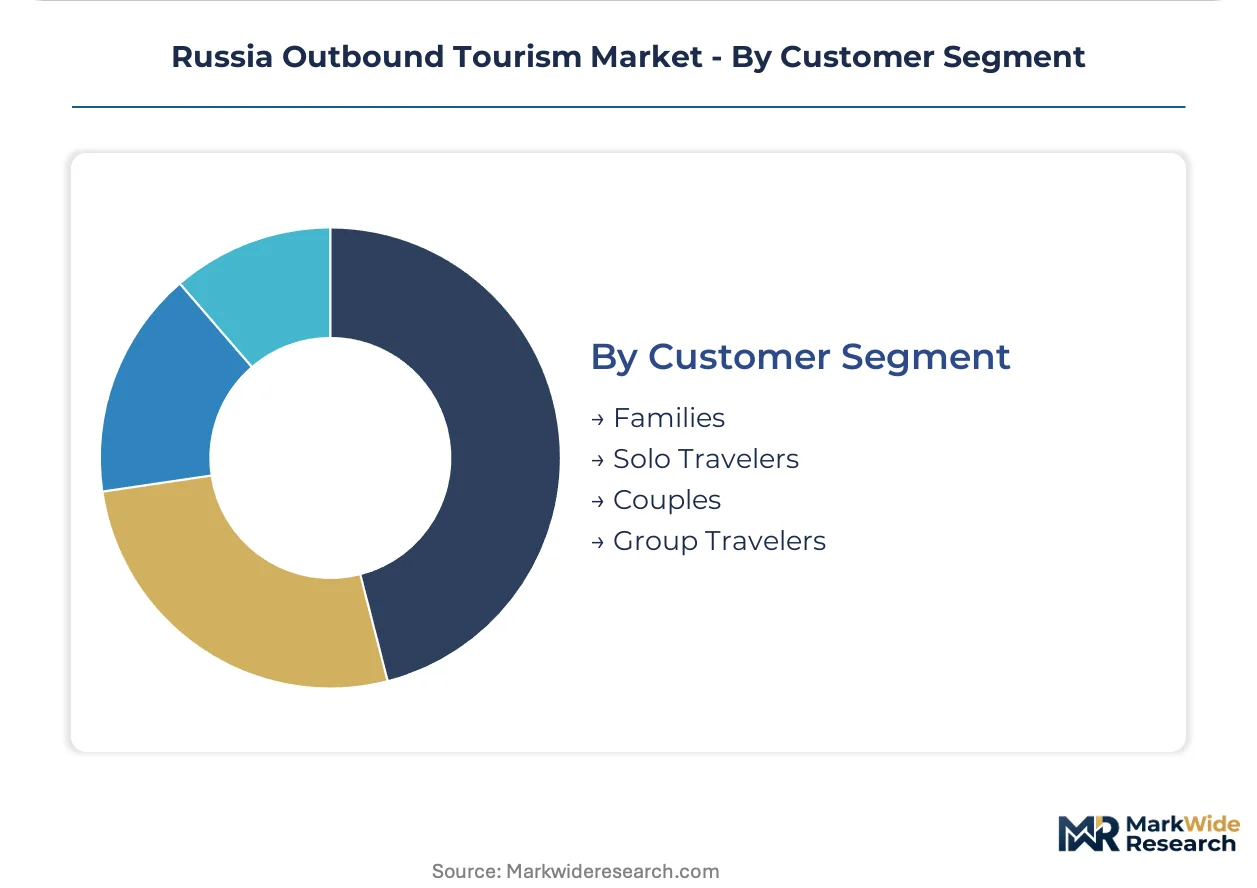
Customer archetypes diverge in risk tolerance, trip duration, and sensitivity to financial guarantee backing, with family units representing the fastest-expanding buyer pool for packaged intermediation.
- Families:Multi-generational groups prioritize all-inclusive security and child-friendly resort amenities. Rostourism licensing requirements elevate trust in established operators for high-stakes vacation expenditure.
- Solo Travelers:Independent itinerary assembly through dynamic packaging engines absorbs demand from traditional agent relationships. Urban millennials dominate this segment.
- Couples:Romantic and honeymoon travel concentrates in premium Turkish and UAE properties with direct hotelier contract pricing.
- Group Travelers:Corporate incentive and affinity group coordination requires dedicated block-booking negotiation with Egyptian Red Sea and Mediterranean hoteliers.
Most installed capacity flows through Families. Expansion is steepest in Solo Travelers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's outbound tourism infrastructure crystallized during the post-Soviet period when charter-flight networks to Mediterranean and Red Sea destinations established the operational template for mass-market leisure travel. Bilateral aviation agreements with Turkey and Egypt created the foundational corridors that still channel the majority of Russian vacation demand today.
Turkey
Antalya's coastal resort zone absorbs the highest volume of Russian leisure travelers through dense charter-flight scheduling coordinated by Rostourism and Turkey's Ministry of Culture and Tourism. Simplified entry protocols eliminate visa friction for tourist passport holders. The Alanya-Kemer corridor concentrates all-inclusive hotel capacity where direct operator contracts compress distribution costs.
United Arab Emirates
Dubai's hospitality infrastructure captures impulse-driven demand through visa-on-arrival eligibility managed by the Federal Authority for Identity and Citizenship. Last-minute booking patterns concentrate volatility on inventory-heavy hoteliers in the emirate's beach and entertainment districts. Mir card network acceptance varies across UAE banking terminals, forcing cash backup protocols.
Egypt
Sharm el-Sheikh and Hurghada sustain Red Sea resort demand through bilateral aviation permissions that govern seasonal charter frequency. Egyptian hoteliers negotiate direct contracts with Russian operators to bypass intermediary markups on package pricing. The Central Bank of Russia's foreign-currency transaction reporting requirements complicate real-time payment reconciliation for multi-destination itineraries including Egyptian segments.
South Korea
Seoul's oncology and cosmetic surgery clusters attract aging Russian medical travelers facing domestic capacity constraints in specialized care. The Korea Tourism Organization coordinates with Russian patient coordinators on treatment pre-qualification and extended-stay visa facilitation. Gangnam-gu's hospital district concentrates the highest density of Russian-speaking medical concierge services.
Israel
Tel Aviv and Jerusalem medical facilities command premium pricing for cardiology and fertility treatments unavailable through Russian domestic providers. Israel's Ministry of Health maintains bilateral protocols with Russian regulators on medical visa issuance and treatment outcome documentation. The city's private hospital clusters invest in Russian-language patient liaison infrastructure.
Russia Outbound Tourism Market Competitive Landscape
The competitive structure tilts toward vertically integrated tour operators controlling charter-flight capacity and direct hotelier contracts. Three distinct archetypes populate the landscape: mass-market package operators with captive aviation assets, meta-search platforms aggregating fragmented supplier inventory, and specialized medical travel coordinators managing foreign hospital networks. Consolidation pressure intensifies as Federal Law No. 132-FZ financial guarantee mandates elevate capital requirements. Strategic moves concentrate on direct property contracting to protect margins and multi-channel payment infrastructure to circumvent sanctions-era transaction friction.
Among integrated charter-flight operators, Pegas Touristik and Tez Tour exemplify the scale-driven archetype through Antalya and Red Sea route dominance. Sletat.ru occupies a distinct position within the meta-search tier, aggregating inventory across multiple suppliers to capture comparison-shopping traffic from independent trip planners. These three entities represent the structural fault lines between packaged security and algorithmic price transparency that define current competitive dynamics.
| Leading Market Players |
|---|
| ReConnect Russia |
| Russian Association of Tour Operators (ATOR) |
| VolnaTrack |
| Pegas Touristik |
| Sletat.ru |
| ZovStep |
| EdenRoute |
| Tez Tour |
| MIRCraft |
| Others |
Value Network & Pricing Analysis
Charter-flight network integration anchors both supply positioning and pricing power for Russian outbound tour operators. Pegas Touristik and Tez Tour leverage captive aviation assets to compress per-seat acquisition costs on Antalya and Sharm el-Sheikh routes, translating operational control into margin protection against intermediary-heavy competitors.
Pricing Analysis
All-inclusive package pricing dominates leisure segments while unbundled medical travel commands premium markups through treatment coordination fees. Three-tier pricing structure across premium, standard, and economy levels segments Turkish resort inventory by star rating and meal-plan inclusivity. Cost compression in economy tiers is intensifying because Egyptian hoteliers negotiate direct contracts bypassing operator markups. Family segments exhibit highest price sensitivity, while aging medical travelers prioritize outcome certainty over cost minimization.
Supply Chain Analysis
Reverse-logistics flows remain minimal in tourism services, though charter-flight repositioning and seasonal crew rotation create operational complexity for Russian carriers. Supply concentrates in Turkey, Egypt, and the United Arab Emirates for mass-market leisure capacity. Raw material dependencies center on aviation fuel procurement, hotel room blocks, and foreign-currency liquidity. Single-source vulnerability in bilateral aviation permissions with Turkish regulators introduces scheduling uncertainty. Distribution runs through Rostourism-licensed operators with Federal Law No. 132-FZ financial guarantee backing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's outbound tourism market functions as a regulatory compounder where Federal Law No. 132-FZ financial guarantee mandates continuously elevate capital barriers and consolidate operator tiers.
For Market Incumbents: Anticipate margin compression from meta-search platform aggregation by deepening direct hotelier contracts in Egyptian Red Sea zones. Rostourism licensing enforcement presents consolidation leverage against undercapitalized intermediaries lacking guarantee backing. Priority rests on multi-channel payment infrastructure circumventing sanctions-era transaction friction. For New Entrants and Emerging Players: Solo travelers seeking dynamic packaging tools represent the most penetrable buyer archetype underserved by legacy agent networks. White-space concentrates in medical travel coordination for South Korean oncology segments and mobile-first booking interfaces for visa-on-arrival destinations. Go-to-market positioning should emphasize algorithmic price transparency against commission-heavy intermediation. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier licensed operators because Federal Law No. 132-FZ capital requirements force fragmentation into acquisition-ready targets. Long-term viability hinges on platform scale advantages in payment-system interoperability and bilateral aviation access. Monitor shifts in Turkey-Russia diplomatic protocols as inflection indicator for charter-flight capacity valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Hotelier Contracting | Bypasses intermediary markups on Egyptian Red Sea packages, protecting margin compression. |
| Multi-Channel Payment Infrastructure | Mir card network integration and cash settlement protocols circumvent SWIFT exclusion friction. |
| Medical Travel Coordination Investment | Seoul oncology and Gangnam cosmetic surgery clusters capture aging demographic outflows. |
| Mobile App Development | Visa-on-arrival eligibility in Dubai enables spontaneous booking capture from urban millennials. |
| Bilateral Aviation Permission Expansion | Rostourism-coordinated agreements with Turkish Ministry of Culture and Tourism secure charter density. |
Research Methodology
Bottom-up traveler segment modeling reconciled against top-down aviation capacity tracking forms the analytical core of this study. Primary interviews with tour operator executives, Rostourism licensing officials, Turkish hotelier procurement managers, and medical travel patient coordinators combined with secondary validation from customs departure records, Central Bank of Russia foreign-currency transaction reports, and bilateral aviation agreement filings. Top-down and bottom-up triangulation cross-validates volume estimates against charter-flight scheduling data and destination entry statistics.
Historical trendline analysis of departure volumes, booking channel migration, and destination mix shifts established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include travel type, preferred destination, booking channel, and customer archetype. CAGRs derive from regression analysis of correlated macroeconomic indicators and traveler propensity indices. Forecast inputs incorporate Federal Law No. 132-FZ enforcement intensity and payment-system interoperability evolution.
Underlying measurement precision varies by segment; leisure travel departure volumes carry tighter precision than medical travel expenditure estimates due to informal payment channels. Forecasts reflect assumptions on bilateral diplomatic stability and aviation permission continuity. Practitioners should monitor Turkey-Russia diplomatic friction, Mir card network expansion, and Rostourism licensing enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Airline Retailing Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
Indonesia Sustainable Tourism Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
United Kingdom Casino Tourism Market