
 Finance and Accounting Outsourcing (FAO) Market | 2026-2036
Finance and Accounting Outsourcing (FAO) Market Size, Share, and Industry Trends Forecast 2026-2036
Finance and Accounting Outsourcing (FAO) Market Insights
Enterprise-grade service tiering is collapsing as mid-market clients demand the same SOC 2 Type II controls and real-time dashboards historically reserved for Fortune 500 engagements. Deloitte leverages its audit heritage to anchor complex regulatory reporting mandates across multinational clients. Genpact sustains competitive differentiation through domain-specific AI accelerators embedded in accounts payable and receivable workflows. Auxis specializes in nearshore delivery from Latin America, occupying a cost-arbitrage niche between onshore premium pricing and offshore scale.
Finance and Accounting Outsourcing encompasses the delegation of transactional, analytical, and compliance-oriented financial functions to third-party providers operating under defined service level agreements with measurable accuracy thresholds and turnaround parameters. Providers deploy robotic process automation alongside cloud-native general ledger platforms to execute high-volume reconciliations, payroll disbursements, and statutory tax filings with reduced error rates and accelerated close cycles. Accounts payable and financial reporting services dominate current revenue pools, while payroll management and tax preparation segments exhibit the fastest structural expansion as regulatory complexity intensifies across multiple jurisdictions. Small and medium enterprises represent an underpenetrated client type where bundled service packages and subscription pricing models are displacing traditional hourly engagement structures.
ISO 27001 certification requirements, SOC 2 attestation standards, and GDPR data residency rules collectively shape provider qualification criteria and client procurement thresholds in cross-border engagements. The US SEC, UK Financial Conduct Authority, and India's RBI impose evolving disclosure timelines and audit trail mandates that directly expand outsourced compliance workload volumes. Stakeholders must monitor how generative AI governance frameworks and emerging algorithmic accountability standards will redefine liability allocation between enterprises and their outsourcing partners.
Market Dynamics
Cloud-native ERP platforms and AI-driven process automation are collapsing traditional service tier boundaries as mid-market enterprises demand Fortune 500-grade controls and real-time visibility without premium pricing structures.
Growth Catalysts
- SEC disclosure mandates:The US Securities and Exchange Commission has compressed financial reporting timelines for public companies, expanding outsourced compliance workload volumes and accelerating client migration to specialized FAO providers.
- Healthcare vertical expansion:Hospital systems and physician practice groups are delegating revenue cycle management and tax preparation to external specialists as reimbursement complexity intensifies under evolving Medicare billing codes.
- AI workflow acceleration:Machine learning models embedded in accounts payable and receivable processes are reducing error rates and accelerating close cycles, creating measurable ROI that drives contract renewals and scope expansions.
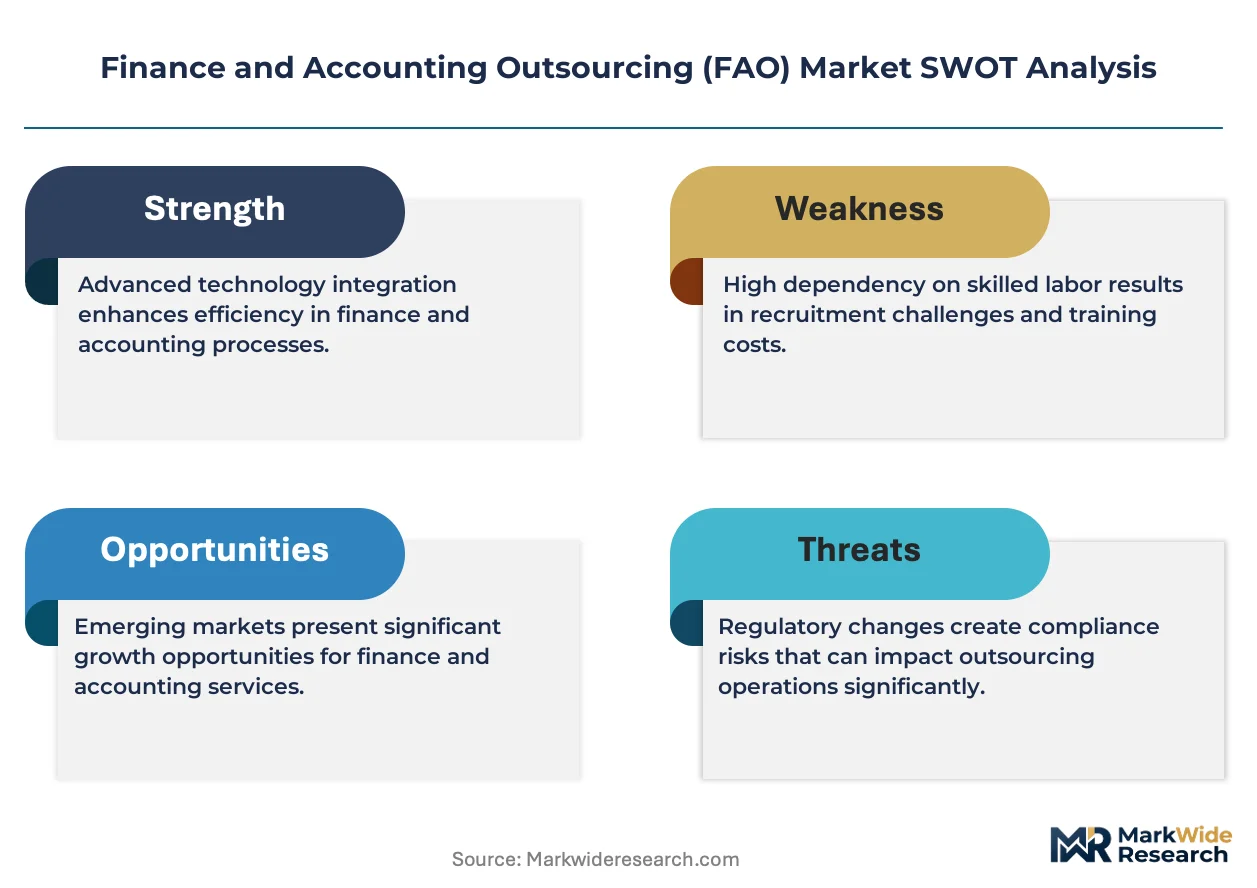
Market Restraints
- Data residency compliance costs:GDPR requirements in the United Kingdom and European Union member states impose strict cross-border data transfer limitations, forcing providers to maintain redundant infrastructure across jurisdictions.
- Talent concentration risk:Skilled accounting professionals with SOC 2 attestation expertise cluster in urban India and metro United States markets, creating wage inflation and attrition vulnerability in these delivery hubs.
- Legacy system integration friction:Enterprises running on-premise general ledger platforms face extended migration timelines and data mapping complexity when connecting to cloud-native FAO architectures.
Strategic Opportunities
- Latin American nearshore expansion:Costa Rica and Colombia offer time-zone alignment with United States clients at labor rates below domestic onshore premiums, creating a viable middle tier between offshore scale and premium pricing.
- Generative AI governance services:Emerging algorithmic accountability standards are creating demand for outsourced risk assessment and documentation services that bridge enterprise liability gaps.
- Subscription model penetration:Small and medium enterprises remain underpenetrated by bundled service packages with predictable monthly pricing, displacing traditional hourly engagement structures in this segment.
Industry Challenges
- SOC 2 Type II certification timelines:Attestation processes require 6-12 month observation periods, constraining provider scalability and delaying market entry for new entrants.
- Multi-jurisdictional tax expertise scarcity:Professionals capable of navigating simultaneous United States, United Kingdom, and Indian regulatory frameworks command premium compensation and exhibit high mobility between competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finance and Accounting Outsourcing (FAO) Market |
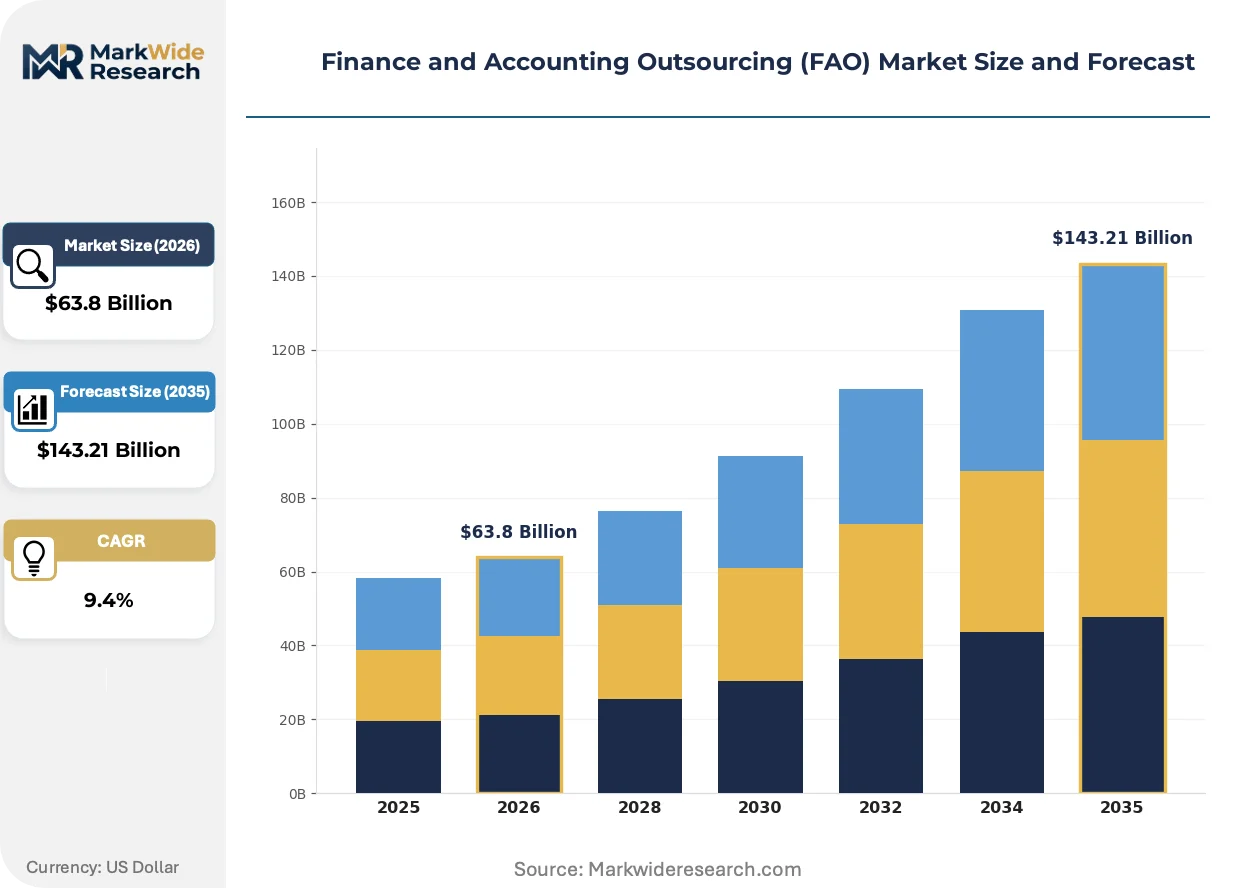
| Market Size in 2026 | $63.8 Billion |
| Market Size in 2035 | $143.21 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accounts Payable, Accounts Receivable, Financial Reporting, Payroll Management, Tax Preparation, Expense Management Industry Vertical: BFSI, Telecommunications, Manufacturing, Healthcare Providers, Hospitality, Education Client Type: Small & Medium Enterprises, Large Enterprises, Startups, Non-Profit Organizations, Government Agencies Engagement Model: Project-Based, Dedicated Team, Build-Operate-Transfer, Risk-Reward, Managed Services |
| Companies Covered | Deloitte, KPMG, EY (Ernst & Young), PwC, Genpact, Capgemini, Infosys BPM, BDO, Auxis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finance and Accounting Outsourcing (FAO) Market Trends and Innovations
Service delivery models are fragmenting as automation capabilities democratize access to sophisticated financial controls while regulatory complexity simultaneously expands compliance workload scope.
Robotic process automation combined with machine learning inference engines is displacing manual reconciliation and exception-handling workflows in high-volume transaction processing. Mid-market enterprises with annual revenue between $50 million and $500 million are adopting these tools at the fastest pace as subscription pricing eliminates upfront capital barriers. The structural consequence is compressing margins for providers unable to demonstrate measurable efficiency gains versus legacy manual processing.
The EU AI Act's risk-based classification system for automated decision-making tools is reshaping provider liability frameworks across European engagements. FAO contracts now explicitly allocate accountability for algorithmic errors in credit decisions and fraud detection workflows. United Kingdom-based financial services firms are most affected, requiring enhanced documentation and human-in-the-loop protocols that extend service delivery timelines.
Enterprise buyers are consolidating vendor relationships from multiple point-solution providers to integrated platform contracts spanning accounting, tax, and treasury functions. This behavior shift is compressing the competitive set for mid-tier specialists while favoring providers with end-to-end cloud-native architectures. The United States exhibits the most visible concentration, with healthcare and technology verticals leading the migration toward single-source FAO arrangements.
Finance and Accounting Outsourcing (FAO) Market Segmentation
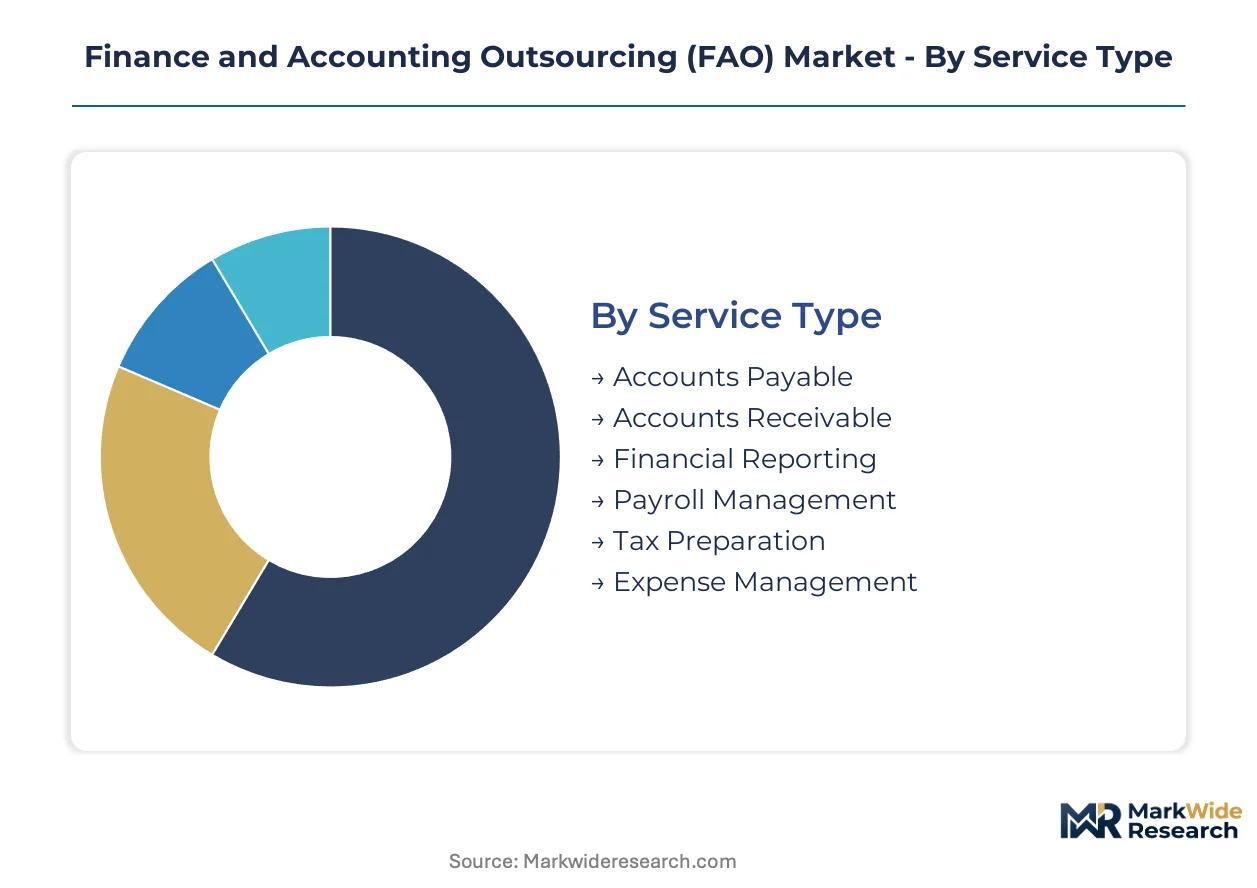
FAO procurement patterns fragment across four distinct dimensions: service type determines technical capability requirements, industry vertical shapes compliance complexity, client type governs pricing elasticity, and engagement model defines risk allocation. Understanding these intersections reveals where automation substitutes labor versus where human expertise retains pricing power.
Service Type:
Substitution pressure from robotic process automation varies dramatically across service types, with high-volume transactional workflows facing the most severe margin compression while judgment-intensive compliance functions defend premium pricing.
- Accounts Payable:Invoice matching, three-way verification, and vendor payment execution constitute the most automated FAO function. Manufacturing enterprises in the United States and Germany concentrate demand here as ERP-embedded RPA tools displace manual processing at scale.
- Tax Preparation:Multi-jurisdictional filing complexity and evolving SEC disclosure timelines sustain strong pricing power. Healthcare providers and BFSI clients in the United States and United Kingdom generate concentrated demand as regulatory burden intensifies.
- Accounts Receivable:Cash application and collections management blend automated matching with exception handling.
- Financial Reporting:Close cycle acceleration and statutory consolidation require SOC 2 attestation expertise.
- Payroll Management:Disbursement execution and tax withholding calculations face cloud-native platform substitution.
- Expense Management:Receipt capture and policy enforcement migrate rapidly to mobile-first SaaS tools.
Accounts Payable anchors the volume base while Tax Preparation gains share at the steepest rate.
Industry Vertical:
Cost tier stratification separates verticals where FAO delivers pure efficiency gains from those requiring specialized regulatory knowledge and audit trail documentation.
- BFSI:Basel III liquidity reporting, anti-money laundering documentation, and stress testing submissions demand the highest certification grades. United States and United Kingdom institutions drive premium-tier contract values.
- Healthcare Providers:Revenue cycle management, Medicare billing compliance, and HIPAA-aligned financial controls create domain-specific workflow requirements. Hospital systems across the United States delegate these functions as reimbursement complexity escalates.
- Telecommunications:Multi-currency treasury operations and interconnection settlement reconciliation require scale.
- Manufacturing:Cost accounting and inventory valuation workflows concentrate in Germany and China production hubs.
- Hospitality:Seasonal staffing payroll and tip allocation compliance create cyclical demand patterns.
- Education:Grant fund accounting and endowment reporting require restricted-use fund expertise.
Healthcare Providers command the highest contract values per seat while BFSI delivers the most stable renewal rates.
Client Type:
Application maturity diverges sharply across client types, with Large Enterprises demanding integrated platform architectures and Small & Medium Enterprises accepting standardized bundles.
- Large Enterprises:Multi-entity consolidation, intercompany eliminations, and statutory reporting across 10+ jurisdictions require bespoke service architectures. Fortune 500 companies in the United States and United Kingdom consolidate vendors toward end-to-end platform contracts.
- Small & Medium Enterprises:Subscription-priced bundles covering bookkeeping, payroll, and basic tax filing address underpenetrated demand. United States mid-market companies between $50 million and $500 million annual revenue adopt these packages fastest.
- Startups:Venture-backed companies prioritize burn rate visibility and cap table management over comprehensive outsourcing.
- Non-Profit Organizations:Fund accounting and donor restriction compliance require specialized expertise.
- Government Agencies:Appropriation accounting and audit readiness mandates impose unique procurement protocols.
Large Enterprises anchor the revenue base while Small & Medium Enterprises expand most quickly as subscription pricing eliminates capital barriers.
Engagement Model:
Volume concentration favors Managed Services and Dedicated Team structures as clients seek predictable cost structures over transaction-based arrangements.
- Managed Services:Outcome-based SLAs with guaranteed accuracy thresholds and turnaround parameters dominate strategic outsourcing. United States healthcare and technology verticals lead adoption of these comprehensive arrangements.
- Dedicated Team:Captive capacity with client-specific process documentation suits complex regulatory environments. BFSI clients in the United Kingdom and India prefer this model for audit trail continuity.
- Project-Based:System implementation and process redesign engagements deliver finite-scope deliverables.
- Build-Operate-Transfer:Captive center establishment with eventual client ownership appeals to cost-conscious multinationals.
- Risk-Reward:Gain-sharing arrangements tied to working capital improvement or cost reduction outcomes.
Managed Services anchors the contract value base while Dedicated Team structures climb the fastest as regulatory complexity demands relationship continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demand SOC 2 Type II attestation without premium pricing, while Indian procurement prioritizes scale economics over control sophistication. United Kingdom clients absorb GDPR compliance costs that deter smaller competitors.
United States
Hospital systems and technology firms drive FAO adoption as SEC disclosure timelines compress. HIPAA and SOX mandates require audit trail documentation that favors established providers. New York and San Francisco financial services clusters concentrate contract values for regulatory reporting services.
India
RBI guidelines on data localization and cross-border financial flows expand compliance workload scope. Bengaluru and Hyderabad delivery hubs face wage inflation as SOC 2 expertise concentrates in these metros. Domestic IT majors leverage scale advantages in accounts payable automation.
United Kingdom
FCA disclosure mandates and GDPR residency rules impose infrastructure redundancy costs on providers. London-based BFSI institutions consolidate vendor relationships toward integrated platform contracts. Edinburgh and Manchester secondary hubs attract mid-market engagements seeking cost optimization.
Germany
Industrial manufacturers delegate cost accounting and inventory valuation as CSRD reporting requirements intensify. Munich and Stuttgart automotive clusters demand German-language financial controls with ISO 27001 certification. Providers maintain redundant Frankfurt data centers to satisfy data sovereignty expectations.
Costa Rica
Nearshore delivery from San José and Heredia captures United States mid-market clients seeking time-zone alignment. Labor rates sit below domestic premiums while English proficiency exceeds offshore alternatives. Providers exploit this positioning to displace higher-cost onshore arrangements.
Finance and Accounting Outsourcing (FAO) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Tier-one audit-origin firms anchor premium regulatory mandates while technology-enabled specialists capture automation-driven efficiency gains. Strategic moves concentrate on geographic expansion into nearshore delivery zones and generative AI governance service development.
Among audit-heritage conglomerates, Deloitte and KPMG exemplify the premium-tier archetype through attestation credibility and multinational coverage. Genpact occupies a distinct position as a technology-native operator with embedded AI accelerators in transactional workflows. Auxis represents the nearshore specialization model, leveraging Latin American delivery to capture cost-sensitive United States mid-market demand.
| Leading Market Players |
|---|
| Deloitte |
| KPMG |
| EY (Ernst & Young) |
| PwC |
| Genpact |
| Capgemini |
| Infosys BPM |
| BDO |
| Auxis |
| Others |
Pricing and Supply Chain Analysis
Cloud-native ERP platforms displacing legacy on-premise general ledger systems simultaneously reshape delivery geography toward India and Latin America while compressing pricing premiums historically attached to SOC 2 attestation. This substitution dynamic forces providers to absorb compliance infrastructure costs while competing on subscription-based unit economics.
Pricing Analysis
Multi-year managed service contracts with embedded SLA penalties drive lifetime value more than transactional engagements. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 engagements with dedicated teams from mid-market subscription bundles and startup self-serve tiers. Pricing pressure stems from robotic process automation commoditizing accounts payable reconciliation. Small and medium enterprises exhibit highest price sensitivity while BFSI clients absorb premiums for regulatory continuity.
Supply Chain Analysis
Workforce inventory cycles of 6-12 months for SOC 2 Type II certification create capacity constraints that extend client onboarding timelines. Talent supply concentrates in India, the United States, and Costa Rica as English-proficient accounting professionals with cross-border regulatory expertise. Provider capability rests on cloud infrastructure from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Single-source vulnerability emerges from concentration of AI/ML engineering talent in Bengaluru and Hyderabad. Distribution runs through direct enterprise sales teams with industry vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against generative AI-native entrants automating judgment-intensive compliance workflows that previously required human expertise. Substitution threat from algorithmic tax preparation and autonomous close-cycle management demands proactive capability investment.
For Market Incumbents: Fortify competitive moats by embedding proprietary AI accelerators directly into client ERP environments and pursuing backward integration into cloud infrastructure to reduce third-party dependency. Vertical integration into data center operations in Costa Rica and Colombia mitigates margin compression from infrastructure markups.
For New Entrants and Emerging Players: Lead with generative AI governance services targeting United Kingdom BFSI clients grappling with EU AI Act compliance documentation requirements. White-space opportunity sits in mid-market healthcare providers seeking bundled revenue cycle management with HIPAA-aligned controls. Go-to-market angle emphasizes subscription pricing with guaranteed accuracy SLAs.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-native operators with embedded workflow automation and established SOC 2 Type II attestation rather than audit-heritage firms with legacy cost structures. Acquisition target archetype combines Latin American delivery footprint with AI-enabled process automation. Signal to watch is consolidation velocity among mid-tier providers unable to demonstrate measurable efficiency gains versus manual processing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Accelerator Embedding | Proprietary machine learning models in accounts payable defend margin against RPA commoditization. |
| Nearshore Delivery Expansion | Costa Rica and Colombia operations capture United States mid-market demand with time-zone alignment. |
| SOC 2 Type II Investment | Attestation credibility unlocks Fortune 500 and BFSI contracts with multi-year renewal visibility. |
| Generative AI Governance Services | EU AI Act compliance documentation creates new revenue pool bridging enterprise liability gaps. |
| Subscription Model Penetration | Predictable monthly pricing displaces hourly engagements in underpenetrated SME segment. |
Research Methodology
Initial hypotheses were tested against primary input from CFOs at mid-market enterprises, FAO provider delivery heads, healthcare revenue cycle directors, BFSI compliance officers, and cloud ERP implementation specialists and refined through secondary validation against SEC disclosure filings, RBI regulatory circulars, GDPR enforcement actions, healthcare GPO contract databases, and ERP vendor partnership announcements. Bottom-up service line sizing triangulated with top-down macroeconomic indicators.
Variance decomposition across service type, industry vertical, client size tier, and engagement model dimensions structured the analytical framework over the projection horizon. CAGRs derived from regression against historical adoption curves and regulatory mandate timelines. Forecast inputs incorporated cloud ERP penetration rates and AI automation deployment velocity by process category.
Forecasts assume regulatory continuity in United States SEC disclosure regimes, United Kingdom FCA mandates, and Indian RBI data localization requirements; material policy shifts would require re-modeling. Model outputs reflect scenario-weighted assumptions rather than deterministic projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
United Kingdom Accounting Software Market
Accounting and Taxation Services
UK Forensic Accounting Market
Accounting and Taxation Services
South Korea Forensic Accounting Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
China Accounting & Budgeting Software Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Tax Software Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Accounting Services Market
Accounting and Taxation Services
Tax Preparation Services Market
Accounting and Taxation Services
Crypto Tax Software Market
Accounting and Taxation Services
Canada Accounting Software Market