
 Sales Tax Software Market | 2026-2036
Sales Tax Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Tax Software Market Analysis
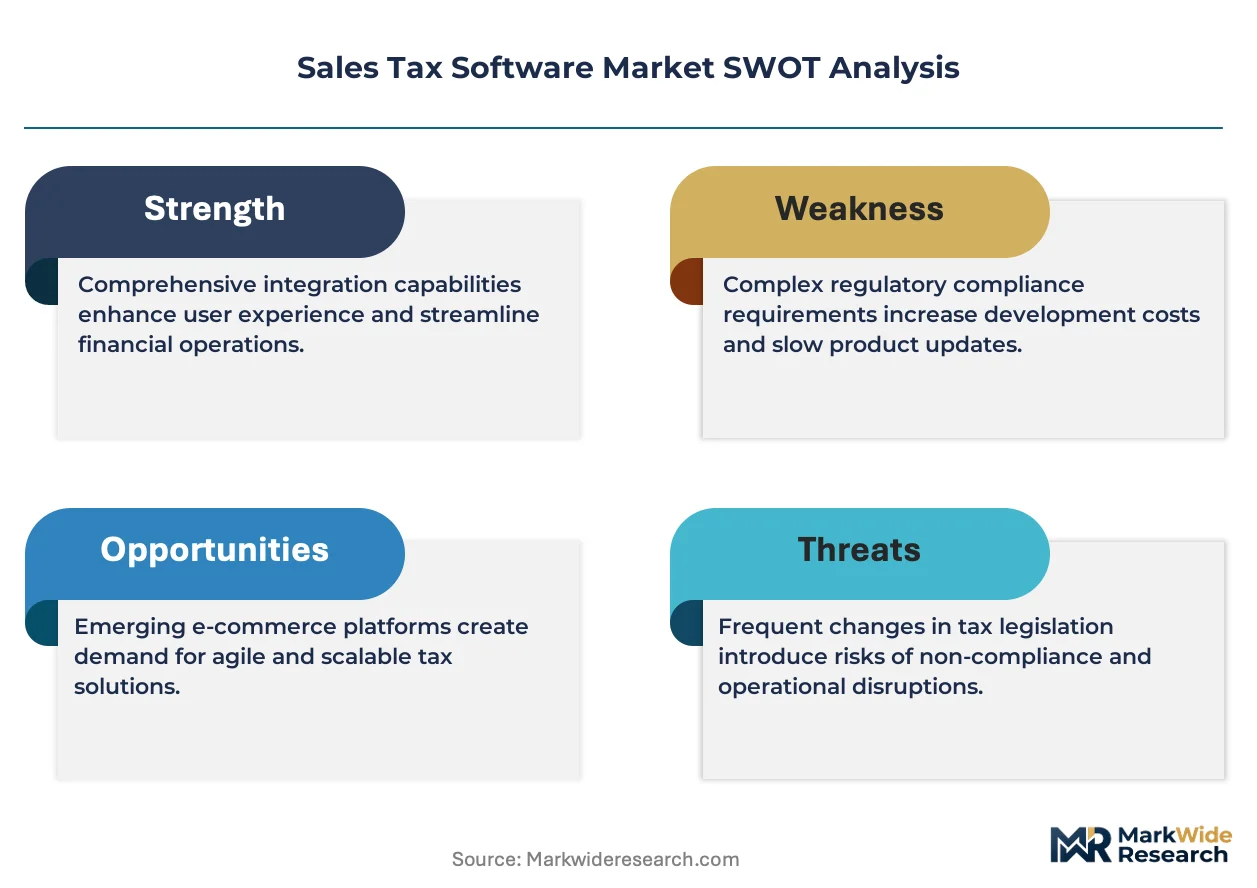
The EU Green Deal is hardening compliance expectations for cross-border digital sellers operating into European markets. Avalara, Inc. leverages extensive jurisdiction coverage to sustain its position among multinational retailers. Vertex, Inc. anchors enterprise-grade tax determination through deep ERP integration capabilities. Thomson Reuters Corporation differentiates via regulatory content depth that competes with specialized compliance databases.
Sales tax software constitutes an automated tax calculation and remittance system that applies jurisdiction-specific rates, rules, and filing schedules to commercial transactions through real-time API calls or batch processing engines. Cloud-based deployments lead current adoption curves due to faster implementation cycles and lower capital requirements, while API-based integration levels capture the fastest growth as embedded finance architectures proliferate across ERP and e-commerce platforms. On-premises solutions retain share among large enterprises with stringent data residency requirements.
The US IRS, state revenue departments, and the EU's VAT Digital Reporting Requirements collectively shape product roadmaps through escalating electronic filing mandates and real-time reporting obligations. The OECD's VAT/GST guidelines further influence cross-border functionality standards for software vendors serving multinational clients. Stakeholders must monitor evolving nexus thresholds and digital reporting timelines to align platform investments with enforcement trajectories.
Market Dynamics
The US Supreme Court's South Dakota v. Wayfair decision continues to expand nexus obligations for remote sellers, forcing transaction tax platforms to absorb fifty-state rate complexity into automated calculation engines. This structural shift multiplies addressable demand across mid-market e-commerce operators previously exempt from collection duties.
Growth Catalysts
- EU VAT Digital Reporting Requirements:Real-time invoice reporting mandates across member states compel cross-border sellers to deploy automated tax engines. European digital marketplaces now embed calculation APIs directly into checkout flows.
- Embedded finance architectures:ERP and e-commerce platforms are absorbing tax determination as a native module rather than bolt-on service. API-first vendors capture integration premiums from SaaS marketplaces.
- Marketplace facilitator laws:US states are shifting collection liability to platform operators. Amazon, Etsy, and Shopify absorb compliance costs, driving procurement of white-label tax engines.
Market Restraints
- Jurisdiction content maintenance:Real-time rate and rule updates across 12,000+ US tax jurisdictions require continuous data engineering investment. Content accuracy failures expose vendors to liability claims.
- Cloud data residency requirements:German and French enterprise buyers mandate EU-sovereign infrastructure. Vendors must replicate stack across regional data centers, compressing margins.
- Free calculation alternatives:Basic rate lookup tools from state revenue departments and open-source libraries absorb price-sensitive micro-merchant demand.
Strategic Opportunities
- India GST compliance automation:India's quarterly return filing and e-invoice mandates create whitespace for vendors with multi-lingual support and local data center presence.
- Carbon border adjustment mechanisms:The EU Green Deal's CBAM will require embedded emissions calculations tied to import VAT. Tax platforms can absorb carbon accounting into existing transaction engines.
- Real-time audit defense:Automated documentation and exemption certificate management represent underpenetrated upsell modules for enterprise accounts facing state examination activity.
Industry Challenges
- Legacy ERP integration complexity:On-premises SAP and Oracle instances require custom middleware development. Implementation timelines stretch 9-18 months, delaying revenue recognition.
- Sales tax nexus expertise scarcity:Platform vendors compete for professionals with state-specific audit defense experience. Compensation inflation in technical consulting functions compresses service margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Tax Software Market |
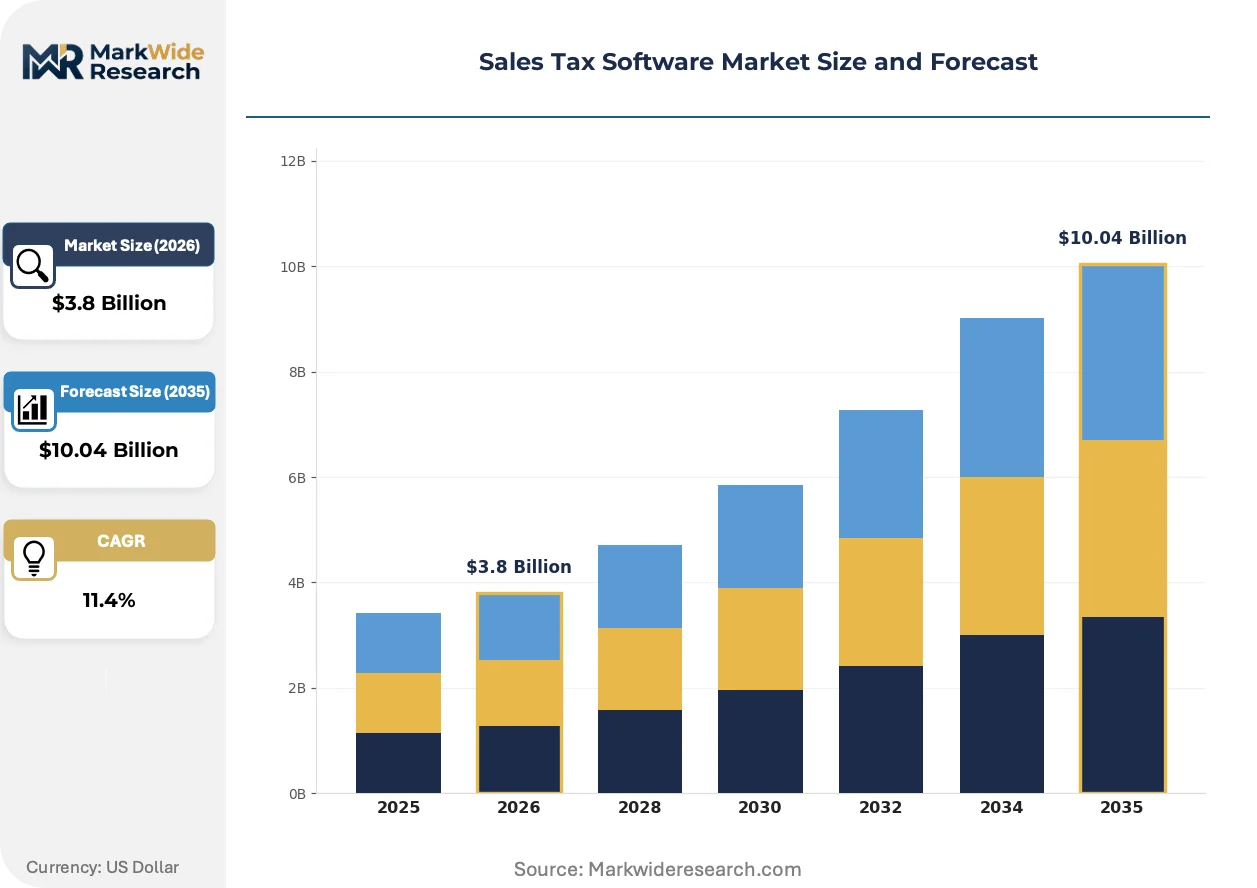
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Enterprise End User: Small Businesses, Medium-sized Enterprises, Large Enterprises, Accounting Firms Deployment Model: Single-tenant, Multi-tenant, Dedicated, Hosted Integration Level: API-based, Plug-ins, Native Integrations, Manual |
| Companies Covered | Avalara, Inc., APEX Analytix, TaxJar, Vertex, Inc., Sovos Compliance LLC, Thomson Reuters Corporation, The Sage Group plc, Ryan, LLC, TaxCloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Tax Software Market Emerging Trajectories
Transaction tax platforms are absorbing adjacent compliance functions—exemption certificate management, use tax accrual, and audit documentation—into unified data architectures. This convergence reshapes vendor competitive positioning around workflow breadth rather than calculation accuracy alone.
Machine learning models trained on historical audit outcomes are absorbing pattern recognition for nexus risk assessment. Mid-market SaaS vendors deploy these engines to flag exposure before state registration thresholds trigger. The technology compresses advisory service margins for traditional accounting firms while embedding compliance intelligence directly into transaction flows.
The OECD's VAT/GST guidelines are hardening technical standards for cross-border digital services. Software vendors serving multinational clients must absorb invoice sequencing, currency conversion, and reverse-charge logic into unified calculation engines. European tax authorities are tightening enforcement timelines, forcing platforms to compress reporting latency from monthly to real-time transmission.
Subscription billing platforms are absorbing tax determination as a native feature rather than third-party integration. Stripe Tax, Chargebee, and Recurly embed jurisdiction-aware calculation into recurring revenue workflows. This disintermediation pressures standalone vendors to defend position through vertical specialization—alcohol taxation, cannabis compliance, or telecom excise—where rate complexity exceeds generic platform capabilities.
Sales Tax Software Market Segmentation
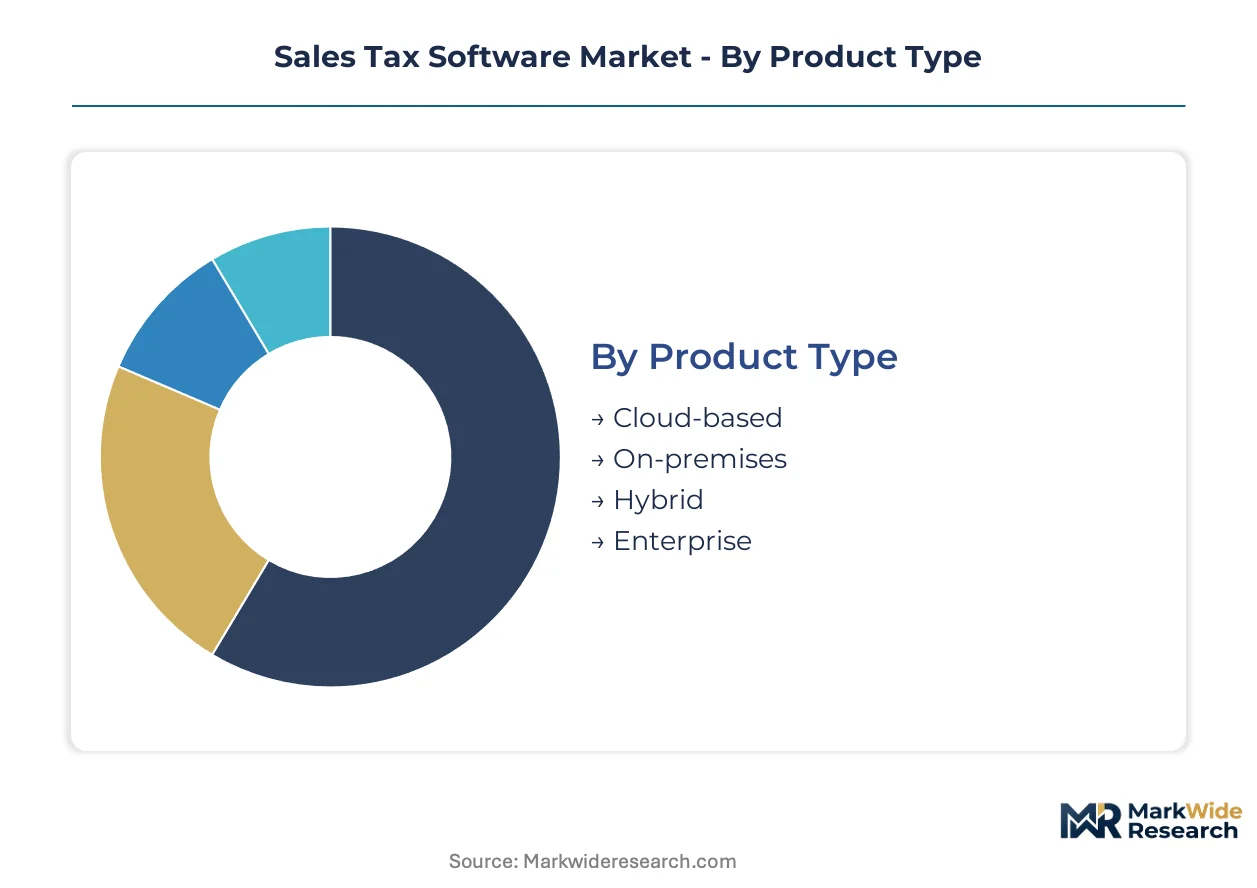
Sales tax software procurement varies sharply by organizational scale and technical architecture. Buyers prioritize either rapid deployment velocity or deep ERP customization depending on internal IT maturity and transaction complexity.
Product Type:
Cost tier determines implementation approach for most buyers, with capital constraints pushing mid-market operators toward subscription models.
- Cloud-based:SaaS delivery enables real-time rate updates and automatic compliance patches without client-side maintenance. Demand concentrates among e-commerce operators and multi-state retailers managing South Dakota v. Wayfair nexus obligations across fifty jurisdictions.
- On-premises:Localized installation satisfies data residency mandates from German and French enterprise buyers under GDPR sovereignty requirements. Large manufacturers with legacy SAP instances absorb nine-to-eighteen-month implementation timelines to retain full infrastructure control.
- Hybrid:Split architectures process sensitive transactions locally while offloading routine calculations to cloud nodes.
- Enterprise:Custom-configured stacks serve Fortune 500 tax departments with dedicated account engineering and SLA guarantees.
Cloud-based leads on scale; API-enabled cloud variants gain share fastest among embedded finance deployments.
End User:
Application complexity separates buyer tiers, with transaction volume and audit exposure driving feature requirements.
- Large Enterprises:Complex nexus footprints across multiple countries demand jurisdiction-aware engines with exemption certificate management and audit documentation modules. Procurement teams prioritize Vertex and Thomson Reuters integrations for ERP backbone compatibility.
- Accounting Firms:Multi-client aggregation requires dashboard consolidation across disparate client systems. Firms serving mid-market e-commerce clients absorb white-label tax engines to embed calculation services into advisory offerings.
- Medium-sized Enterprises:Growth-stage operators balance functionality against implementation speed, often selecting pre-built connectors for Shopify or NetSuite.
- Small Businesses:Basic rate lookup needs frequently default to free state revenue department tools or native platform calculators.
Large Enterprises anchor revenue concentration; Accounting Firms expand addressable market through service bundling.
Deployment Model:
Volume predictability shapes infrastructure commitments, with seasonal transaction spikes favoring elastic capacity.
- Multi-tenant:Shared infrastructure delivers lowest unit economics for standardized calculation workloads. Holiday retail surges and quarterly filing deadlines drive automatic scaling without capital reservation.
- Single-tenant:Isolated environments satisfy security reviews from healthcare and financial services buyers subject to HIPAA and SEC data handling protocols.
- Dedicated:Reserved hardware clusters support consistent high-throughput processing for marketplace facilitators absorbing collection liability under state marketplace laws.
- Hosted:Vendor-managed private clouds bridge compliance requirements and operational simplicity for European mid-market operators.
Multi-tenant dominates unit volume; Dedicated deployments capture premium pricing from platform operators.
Integration Level:
Customer technical sophistication determines connectivity preference, with developer resources dictating build-versus-buy calculus.
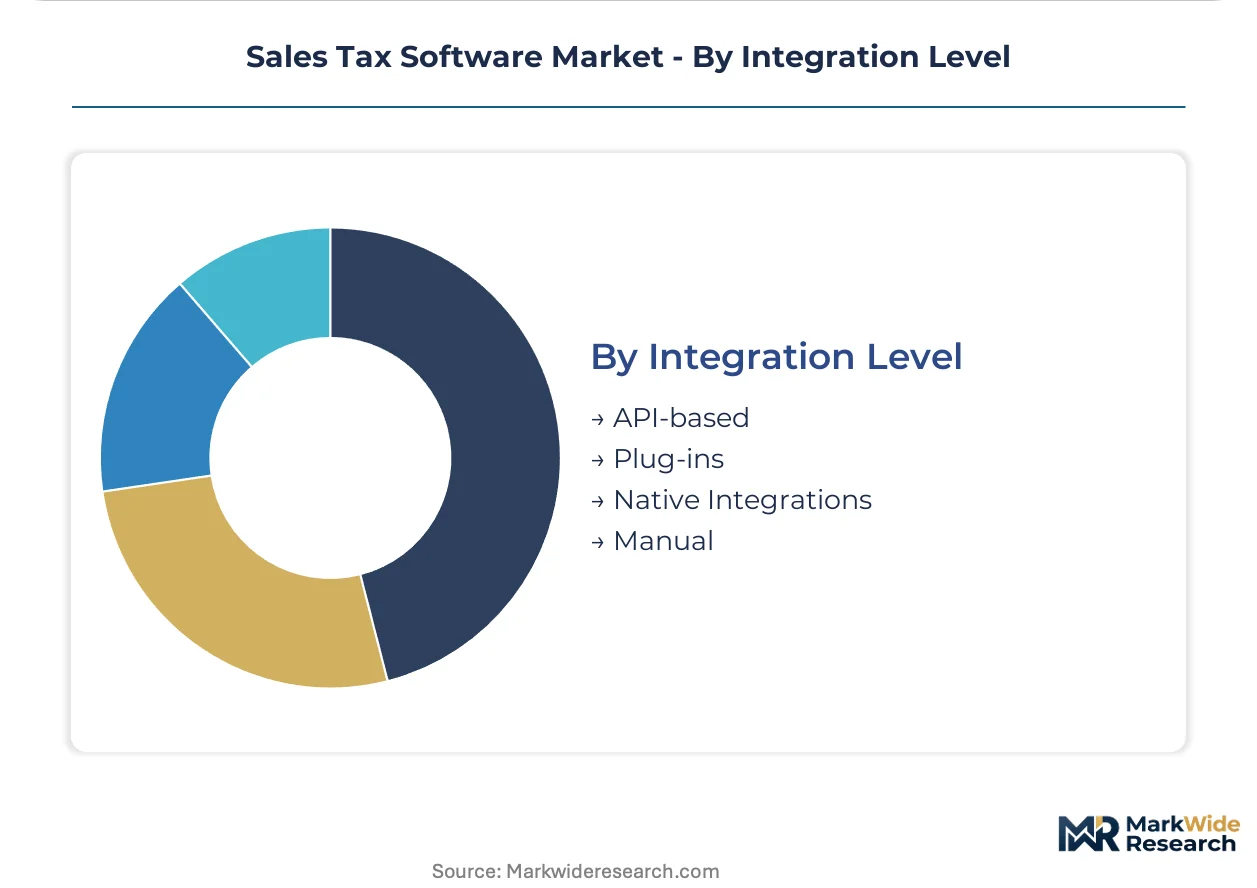
- API-based:RESTful endpoints enable embedded tax determination within checkout flows, subscription billing platforms, and procurement systems. Stripe Tax and Recurly native modules exemplify this architecture's penetration into recurring revenue workflows.
- Native Integrations:Pre-built connectors for SAP, Oracle, NetSuite, and Microsoft Dynamics compress implementation to weeks rather than months. Enterprise procurement teams prioritize these for ERP backbone compatibility.
- Plug-ins:Marketplace extensions for WooCommerce, Magento, and BigCommerce serve merchant operators without dedicated development staff.
- Manual:Spreadsheet upload and batch file processing persists among legacy operators with low transaction volumes and limited IT investment.
API-based integration climbs the fastest as embedded finance architectures proliferate; Native Integrations retain largest installed base among established enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax technology talent clusters in the United States, the United Kingdom, and Germany anchor software development pipelines. These concentrations feed engineering capacity into compliance automation platforms serving multinational enterprises.
United States
Fifty-state rate complexity and post-Wayfair nexus obligations drive procurement from mid-market e-commerce operators. State revenue departments enforce electronic filing mandates that compress implementation timelines. Austin and Seattle host engineering centers where API-first platforms embed calculation engines into checkout flows.
Germany
GDPR data sovereignty requirements and EU VAT Digital Reporting Requirements shape buyer specifications for on-premise and hosted deployments. The national financial regulator BaFin influences audit documentation standards for enterprise tax departments. Frankfurt and Munich concentrate implementation specialists serving DAX-listed manufacturers with legacy SAP integration demands.
United Kingdom
Post-Brexit VAT rule divergence from EU frameworks creates demand for dual-jurisdiction calculation engines. HMRC's Making Tax Digital program mandates quarterly digital submissions from VAT-registered businesses. London's fintech corridor houses product teams developing real-time reporting modules for cross-border digital sellers.
India
GST quarterly return filing and e-invoice mandates generate whitespace for vendors with multi-lingual platform support. The Central Board of Indirect Taxes and Customs enforces strict data localization through Goods and Services Tax Network infrastructure. Bangalore and Hyderabad development centers build compliance automation for India's fragmented state-level rate architecture.
Canada
Provincial sales tax harmonization gaps and Quebec's distinct QST regime sustain demand for multi-rate calculation engines. The Canada Revenue Agency coordinates with provincial finance ministries on electronic filing standardization. Toronto's financial district anchors advisory practices serving US-Canada cross-border retail operators.
Sales Tax Software Market Vendor Landscape
Capital-heavy enterprise software producers compete with asset-light API-first specialists across deployment architectures. The vendor base stratifies into three tiers: multinational content aggregators, embedded finance platforms, and vertical compliance specialists. Strategic differentiation centers on jurisdiction coverage breadth versus integration depth. Consolidation pressure intensifies as subscription billing platforms absorb native tax determination capabilities.
Among North American compliance technology providers, Avalara, Inc., Vertex, Inc., and Thomson Reuters Corporation occupy distinct positioning archetypes. Avalara exemplifies API-first scale through extensive jurisdiction coverage. Vertex anchors enterprise-grade ERP integration for Fortune 500 tax departments. Thomson Reuters represents content depth competition against specialized regulatory databases. Each sits within a tier defined by technical architecture rather than geographic origin alone.
| Leading Market Players |
|---|
| Avalara, Inc. |
| APEX Analytix |
| TaxJar |
| Vertex, Inc. |
| Sovos Compliance LLC |
| Thomson Reuters Corporation |
| The Sage Group plc |
| Ryan, LLC |
| TaxCloud |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up compliance specialists concentrate engineering talent in Austin and Seattle, compressing cost-to-serve curves while sustaining subscription pricing power through jurisdictional content depth. This ownership pattern feeds pricing discipline back into supply choices, favoring cloud-native architectures over capital-intensive on-premise replication.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise procurement patterns from mid-market adoption curves. SaaS subscription tiers dominate, with price differentiation anchored in jurisdiction coverage breadth and ERP integration complexity. Pricing pressure stems from embedded finance platforms absorbing tax determination as native features. Large enterprises exhibit lowest price sensitivity due to audit exposure and compliance liability, while micro-merchants gravitate toward free state revenue department tools.
Supply Chain Analysis
Workforce availability in Indian development centers—Bangalore and Hyderabad specifically—anchors content engineering and localization pipelines for GST compliance modules. The supply chain draws from US-based regulatory content curators, EU data center operators for GDPR-sovereign hosting, and Indian multilingual support engineering. Single-source vulnerability concentrates in jurisdiction rate data licensing from state revenue departments. Distribution runs through direct enterprise sales, SaaS marketplaces, and accounting firm channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sales tax software functions as a regulatory compounder, with the US Supreme Court's South Dakota v. Wayfair decision perpetually expanding nexus obligations and embedded calculation demand across remote seller ecosystems.
For Market Incumbents: Hedge platform commoditization by deepening vertical specialization in alcohol taxation, cannabis compliance, and telecom excise—segments where rate complexity exceeds generic engine capabilities. Acquire jurisdiction content libraries to defend data moats against open-source rate alternatives. Prioritize API-first architecture investment to capture integration premiums from embedded finance proliferation.
For New Entrants and Emerging Players: Accounting firm channel partners represent the most penetrable on-ramp, bundling white-label calculation engines into advisory service offerings. Target India's GST compliance whitespace through multi-lingual platform support and local data center presence. Pursue carbon border adjustment mechanism functionality as a differentiated module for EU import VAT workflows.
For Investors and Strategic Acquirers: Valuations sit cheapest among vertical compliance specialists with deep jurisdiction expertise but limited platform scale. Long-term viability hinges on absorption into embedded finance architectures or sustained independence through regulatory complexity moats. Watch for real-time audit defense module penetration rates as an inflection indicator of enterprise wallet share expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Specialization | Alcohol and cannabis tax modules capture premium pricing from compliance complexity. |
| API-First Platform Expansion | Embedded finance architectures absorb tax determination into recurring revenue workflows. |
| Geographic Data Center Replication | EU-sovereign infrastructure satisfies GDPR mandates from German and French buyers. |
| Machine Learning Audit Defense | Pattern recognition engines compress advisory margins for traditional accounting firms. |
| Carbon Border Adjustment Integration | EU Green Deal CBAM requirements tie emissions calculations to import VAT workflows. |
Methodological Framework
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and tax technology directors at multinational retailers and accounting firms combined with secondary validation from SEC filings, hyperscaler partnership disclosures, and state revenue department electronic filing mandate documentation. Triangulation across these sources anchored jurisdiction coverage assessments and integration complexity benchmarks.
Input-output matrices mapped transaction volume projections against SaaS pricing elasticity and on-premise licensing decay. Segmentation dimensions modeled include deployment architecture, organization size tier, integration complexity level, vertical industry, and regional regulatory cluster. CAGRs derived from slope analysis of historical adoption curves adjusted for enforcement timeline acceleration from real-time reporting mandates. Forecast inputs incorporated ERP migration cycles and marketplace facilitator law adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nexus threshold modifications, embedded finance platform consolidation, and open-source rate tool maturation. Forecasts reflect assumptions about regulatory enforcement continuity and cloud infrastructure cost trajectories. Material deviation in state marketplace law adoption or API-first platform acquisition activity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Spain Forensic Accounting Market
Accounting and Taxation Services
Tax Compliance Services Market
Accounting and Taxation Services
Global Financial Accounting Advisory Services Market
Accounting and Taxation Services
Europe Accounting Software Market
Accounting and Taxation Services
Europe Auditing Services Market
Accounting and Taxation Services
India Forensic Accounting Market
Accounting and Taxation Services
China Accounting Software Market
Accounting and Taxation Services
Accounting Software Market
Accounting and Taxation Services
Accounting and Budgeting Software Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Global Accounting Finance Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
Tax Management Software Market
Accounting and Taxation Services
Global Business Accounting Software Market