
 Hong Kong Tourism Market | 2026-2036
Hong Kong Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Tourism Market Outlook
The Individual Visit Scheme is decoupling mainland visitor quotas from traditional group-tour economics, raising fixed costs for independent travel packaging. Fosun Tourism Group leverages its integrated resort assets to capture extended-stay spending. EGL Holdings anchors its position through outbound-inbound tour bundling. China Links Travel specializes in bespoke heritage itineraries that bypass commodity pricing.
Hong Kong tourism encompasses destination services, visitor accommodation, experiential programming, and cross-border mobility infrastructure designed to generate foreign exchange and employment through temporary visitor consumption. The sector operates through fixed-capacity assets including 32,000+ hotel rooms and constrained heritage sites requiring timed-entry management. Leisure travelers command the largest share of bed-nights, while cultural experiences generate the highest per-visitor ancillary spend. Luxury travel styles capture disproportionate margin pools despite smaller volume, whereas budget backpacking segments drive off-peak occupancy recovery.
Hong Kong's Commerce and Economic Development Bureau coordinates with the Tourism Commission to enforce hotel licensing standards and visitor safety protocols. The National Immigration Administration of China governs cross-border permit issuance that directly gates mainland demand inflows. The Travel Industry Council of Hong Kong maintains escrow and bonding requirements that shape operator solvency thresholds. Stakeholders must weigh capacity expansion against heritage preservation mandates when allocating capital across the harborfront and outlying islands.
Market Dynamics
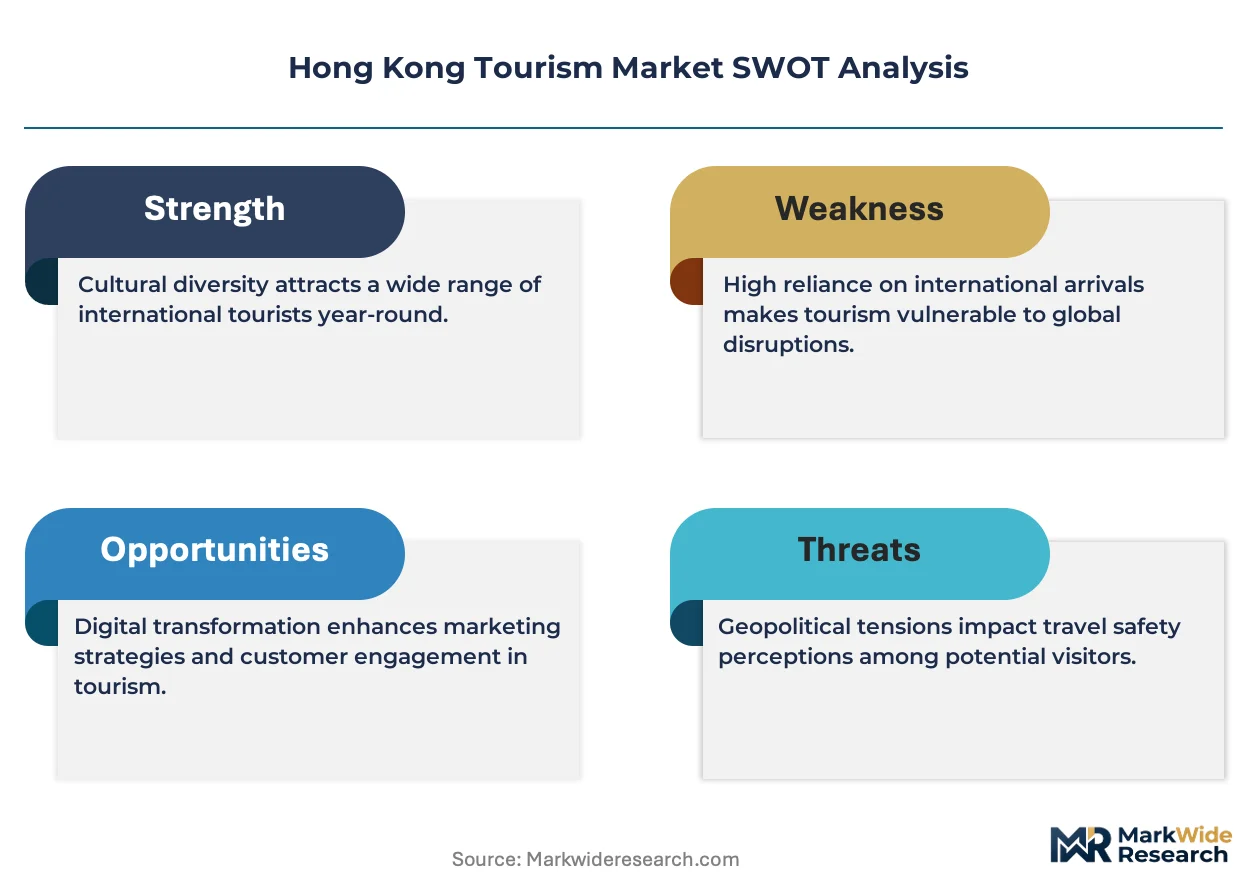
The Individual Visit Scheme's expansion is decoupling mainland Chinese arrivals from group-tour economics, forcing operators to redesign fixed-cost structures around independent travelers while heritage site capacity constraints harden entry bottlenecks.
Growth Catalysts
- Smart Destination Platforms:Real-time visitor flow systems around Victoria Harbour and Lantau Island optimize capacity utilization at constrained heritage assets.
- The Individual Visit Scheme:China's National Immigration Administration permit relaxation removes quota friction for mainland leisure travelers seeking extended-stay cultural programming.
- Heritage Tourism Demand:Bespoke cultural itineraries across Central and Kowloon districts command premium ancillary spend per bed-night.
Market Restraints
- Fixed Asset Rigidity:Hong Kong's 32,000+ hotel rooms cannot expand within harborfront preservation zones, capping peak-season inventory elasticity.
- Cross-Border Permit Volatility:China's National Immigration Administration retains unilateral authority to suspend or throttle Individual Visit Scheme issuance.
- Heritage Site Saturation:Timed-entry mandates at constrained Central and Kowloon landmarks limit revenue-per-visitor scalability.
Strategic Opportunities
- Outlying Islands Development:Lantau Island's underutilized land bank permits resort-style extended-stay product outside urban density constraints.
- Integrated Resort Convergence:Mixed-use hospitality-entertainment-retail complexes capture mainland visitor spending across multiple touchpoints.
- Outbound-Inbound Bundling:Dual-destination packaging with Greater Bay Area cities deepens per-trip yield and extends booking windows.
Industry Challenges
- Multilingual Service Talent Scarcity:Frontline hospitality roles requiring Mandarin-Cantonese-English fluency face recruitment gaps as visitor demographics shift.
- Escrow Compliance Burden:The Travel Industry Council of Hong Kong's bonding requirements strain smaller operator balance sheets during demand troughs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Tourism Market |
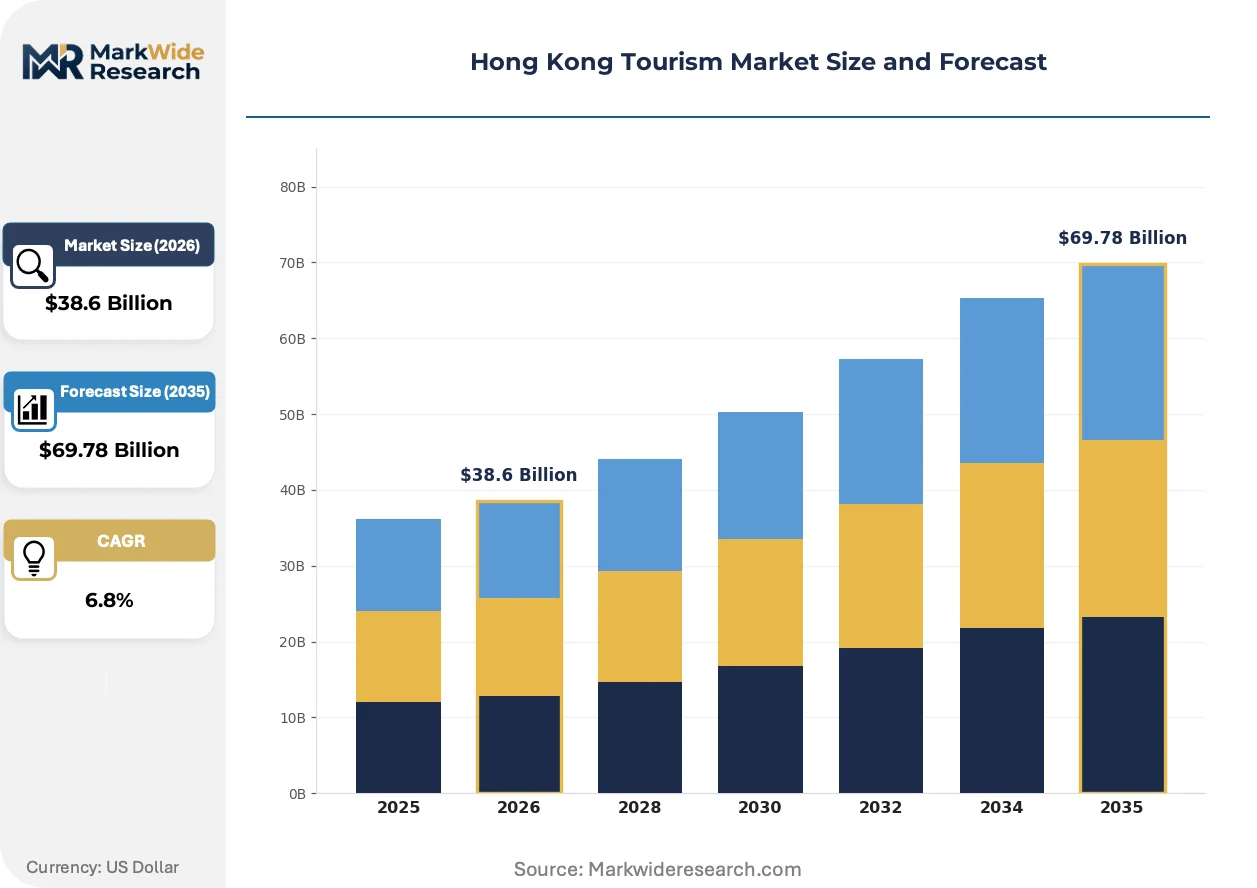
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Leisure Travelers, Business Travelers, Families, Couples Service Type: Accommodation, Outdoor Activities, Cultural Experiences, Dining Attraction Type: Museums, Nature Parks, Shopping Districts, Historical Sites Travel Style: Luxury, Budget, Backpacking, Group Tours |
| Companies Covered | Intrepid Travel, Globus, Fosun Tourism Group, Uniworld, China Links Travel, EGL Holdings, Explore!, SmarTours, WWPKG Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Tourism Market Strategic Shifts
Digital infrastructure is absorbing operational complexity across Hong Kong's constrained physical assets, while regulatory coordination between mainland and local authorities reshapes cross-border mobility architecture.
Artificial intelligence-powered visitor flow management is absorbing congestion prediction and dynamic pricing functions previously handled by static capacity allocations. The Tourism Commission and harborfront operators deploy these systems to stagger entry at Victoria Harbour viewpoints and Lantau Island attractions. Heritage site revenue models are absorbing predictive analytics that match ticket release to real-time demand signals, compressing underutilized slot wastage.
The National Immigration Administration's permit digitization and Hong Kong's Commerce and Economic Development Bureau hotel licensing convergence are streamlining cross-border compliance documentation. This regulatory alignment reduces processing friction for mainland independent travelers while tightening data-sharing protocols between jurisdictions. Smaller inbound tour operators face elevated compliance costs as escrow and bonding thresholds adjust to the new mobility framework.
Experience-based booking platforms are displacing traditional travel agency intermediation for mainland visitors researching Hong Kong itineraries. These channels aggregate heritage site timed-entry slots, harborfront dining reservations, and Lantau Island transport into unified purchase paths. The shift concentrates commission economics among platform operators while forcing legacy agencies toward specialized concierge functions.
Hong Kong Tourism Market Segmentation
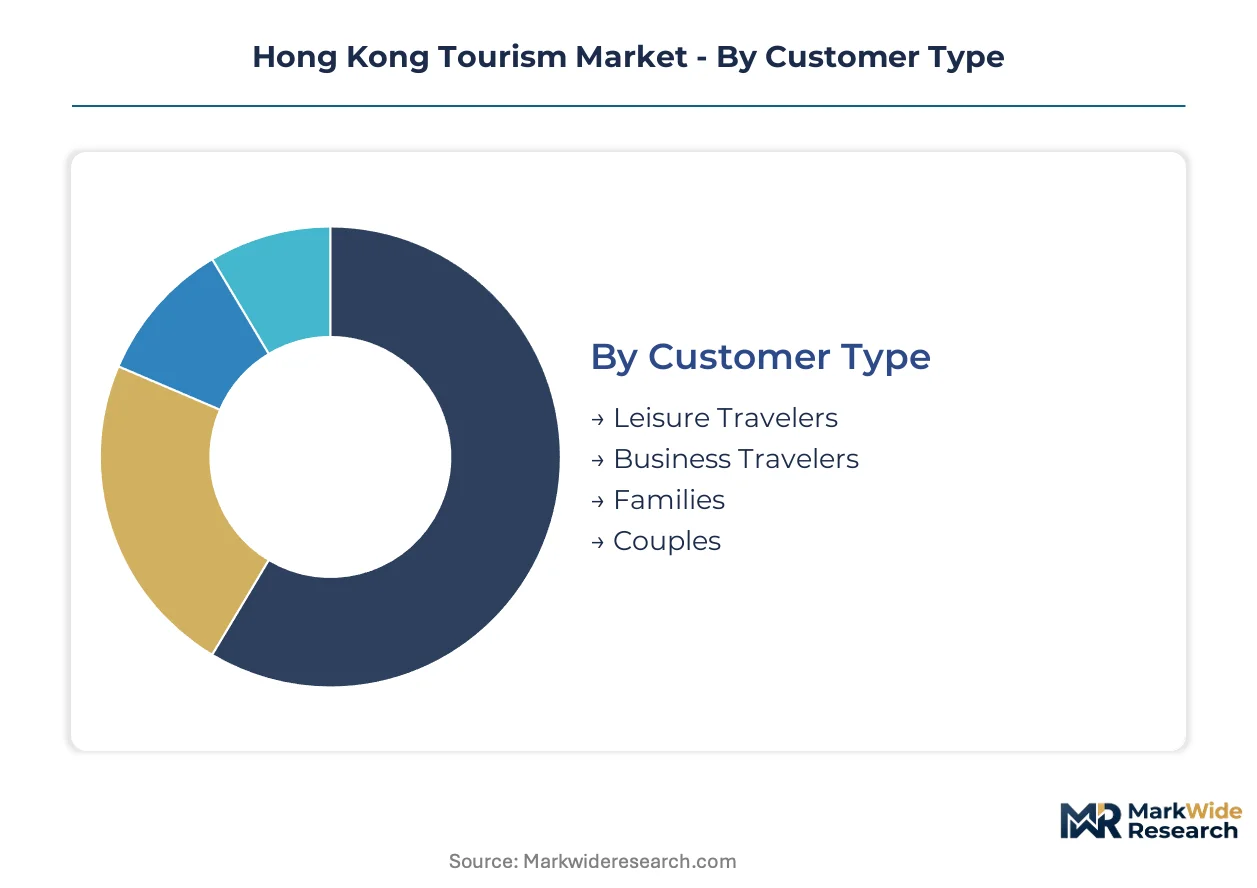
Segmentation reveals how Hong Kong's constrained physical assets and regulatory frameworks create divergent margin profiles across visitor cohorts. Operators must match service architecture to specific demand patterns rather than treating the market as homogeneous.
Customer Type:
Upgrade cycles in travel behavior are shortening as mainland visitors under the Individual Visit Scheme shift from group-tour dependency to independent itinerary planning, forcing operators to rebuild service models around self-directed research and booking patterns.
- Leisure Travelers:Independent mainland Chinese visitors seeking extended-stay cultural programming drive the highest bed-night volumes. Victoria Harbour and Lantau Island attractions absorb their concentrated demand during peak windows.
- Business Travelers:Corporate visitors command premium per-night rates at harborfront properties. Their compressed itineraries limit ancillary spend to dining and transport, though frequency sustains occupancy during off-peak periods.
- Families:Multi-generational groups from the Greater Bay Area prioritize integrated resort experiences that consolidate accommodation, entertainment, and dining. Their booking windows extend further than individual leisure segments.
- Couples:Young mainland pairs pursuing heritage photography and boutique dining generate elevated per-visitor spend across Central and Kowloon districts. Their social media documentation amplifies destination marketing reach.
Leisure travelers sit at the top of the volume ranking, with couples climbing the fastest as bespoke itinerary platforms displace traditional agency intermediation.
Service Type:
Cost tier differentiation separates mass-market commodity providers from premium experience architects, with regulatory compliance burdens falling disproportionately on smaller operators in lower-margin segments.
- Accommodation:Hong Kong's 32,000+ hotel rooms face fixed-capacity constraints within harborfront preservation zones. The Travel Industry Council of Hong Kong enforces escrow and bonding requirements that shape operator solvency thresholds.
- Outdoor Activities:Lantau Island's underutilized land bank permits resort-style product development outside urban density limits. Smart destination platforms optimize visitor flow to prevent congestion at trailheads and viewpoints.
- Cultural Experiences:Timed-entry mandates at heritage sites limit revenue scalability despite premium pricing power. Predictive analytics now match ticket release to real-time demand signals.
- Dining:Harborfront and outlying island restaurants capture mainland visitor spending through experience-based booking platforms. Commission economics concentrate among platform operators.
Accommodation commands the largest revenue pool, with outdoor activities gaining share fastest as Lantau development proceeds.
Attraction Type:
Application-based segmentation reveals how physical constraints and preservation mandates create divergent operational models across Hong Kong's visitor touchpoints.
- Museums:Heritage institutions in Central and Kowloon districts deploy AI-powered flow management to stagger entry and compress underutilized slot wastage. Their revenue models increasingly rely on predictive analytics.
- Nature Parks:Lantau Island and outlying island conservation areas balance access expansion against ecological preservation. Smart platforms absorb congestion prediction functions previously handled by static capacity allocations.
- Shopping Districts:Harborfront retail corridors capture mainland visitor spending across multiple touchpoints. Integrated resort convergence deepens per-trip yield through hospitality-entertainment-retail complexes.
- Historical Sites:Constrained landmarks require timed-entry management that caps visitor throughput. The Tourism Commission coordinates with operators to enforce safety protocols while maximizing asset utilization.
Museums anchor the cultural tourism segment by volume, with nature parks expanding most quickly as smart infrastructure extends to outlying islands.
Travel Style:
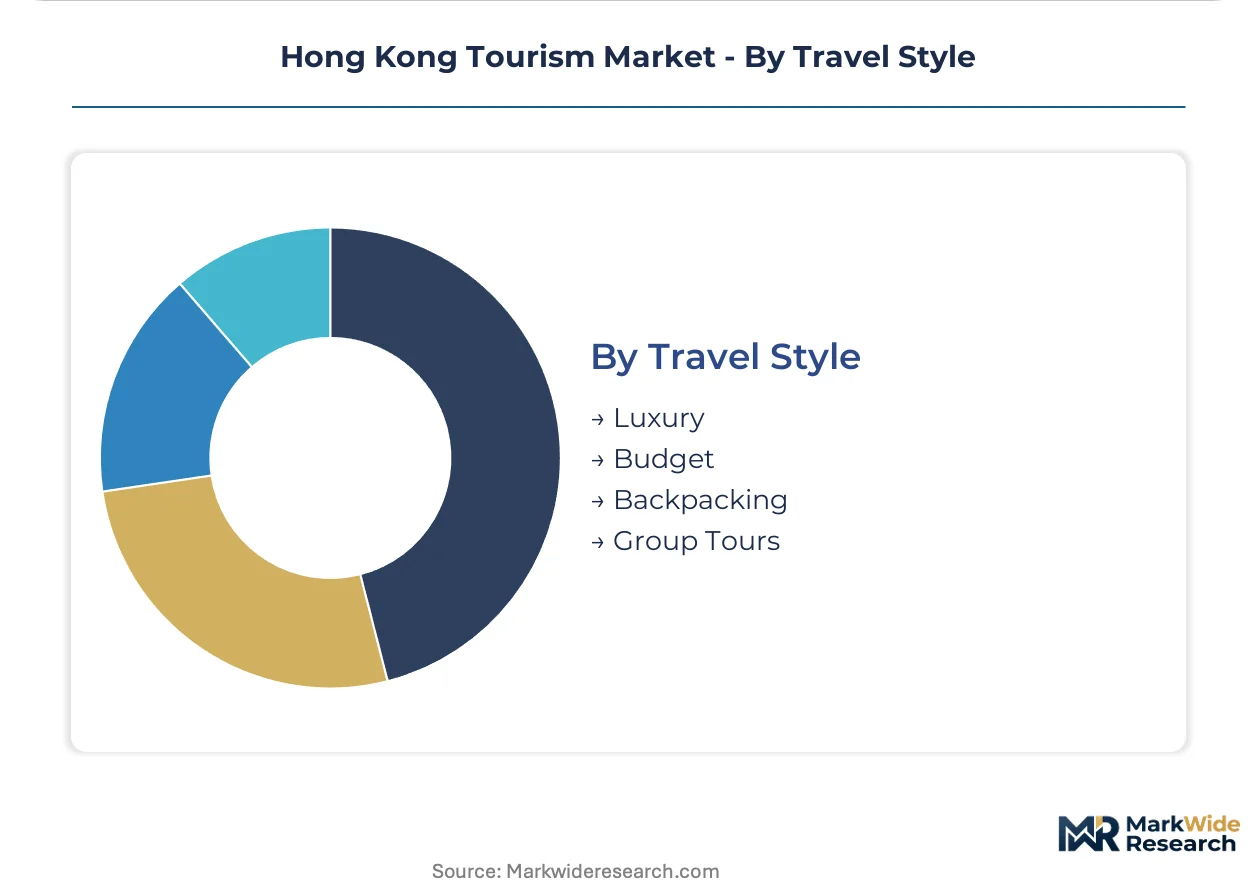
Margin concentration patterns favor luxury and premium segments despite smaller absolute volumes, while budget positioning drives off-peak occupancy recovery through price-sensitive demand.
- Luxury:High-net-worth mainland visitors and international elites command disproportionate margin pools through bespoke concierge services and exclusive heritage access. Their extended stays amortize fixed costs across more nights.
- Budget:Price-conscious travelers fill inventory troughs through dynamic pricing platforms. Their demand concentrates in off-peak periods when premium segments contract.
- Backpacking:Young independent travelers from Southeast Asia and Europe prioritize hostel accommodation and public transport. Their low ancillary spend limits operator interest despite volume contribution.
- Group Tours:Traditional packaged travel faces structural decline as the Individual Visit Scheme decouples mainland arrivals from group-tour economics. Operators redesign fixed-cost structures around shrinking cohorts.
Luxury travel sits at the top of the margin ranking, with budget segments climbing fastest as platform intermediation reduces search and booking friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality workforce clusters in Hong Kong's harborfront districts anchor visitor service capacity, while cross-border talent pipelines from Shenzhen and Guangzhou replenish frontline Mandarin-Cantonese-English fluency requirements.
Kowloon
Heritage tourism demand concentrates in Tsim Sha Tsui and Mong Kok, where boutique dining and photography circuits generate elevated per-visitor spend. The Tourism Commission enforces timed-entry coordination at constrained landmarks. Cultural experience providers cluster along the West Kowloon Cultural District, absorbing independent mainland travelers through experience-based booking platforms.
Hong Kong Island
Business travelers command premium rates at Central and Admiralty harborfront properties, sustaining occupancy during off-peak windows. The Commerce and Economic Development Bureau coordinates hotel licensing standards with visitor safety protocols. Victoria Harbour viewpoint operators deploy AI-powered flow management to stagger entry and compress underutilized slot wastage.
Lantau Island
Resort-style extended-stay product development proceeds on underutilized land banks outside urban density constraints. Smart destination platforms optimize visitor flow to trailheads and viewpoints. Integrated resort complexes capture mainland visitor spending across hospitality-entertainment-retail touchpoints.
New Territories
Greater Bay Area families prioritize multi-generational accommodation near cross-border rail termini. The National Immigration Administration's permit digitization streamlines documentation for Shenzhen and Guangzhou origin markets. Outbound-inbound tour bundling with Pearl River Delta cities deepens per-trip yield in Sha Tin and Tai Po corridors.
Outlying Islands
Ecotourism demand concentrates in conservation areas balancing access expansion against preservation mandates. The Travel Industry Council of Hong Kong maintains escrow requirements that shape operator solvency thresholds for inter-island ferry and activity providers. Nature park concessionaires absorb congestion prediction functions through smart infrastructure deployment.
Hong Kong Tourism Market Competitive Environment
The competitive structure tilts toward integrated resort operators and heritage experience specialists. Market concentration remains moderate, with tiered positioning separating premium bespoke providers from volume-driven packaged tour operators. Two strategic archetypes dominate: asset-heavy integrated resort owners capturing extended-stay spending, and niche heritage itinerary designers bypassing commodity pricing. Competitive moves center on outbound-inbound bundling partnerships and smart platform intermediation that displaces traditional agency channels.
Within the integrated resort tier, Fosun Tourism Group anchors asset-heavy positioning through hospitality-entertainment-retail convergence. EGL Holdings occupies a position straddling outbound-inbound bundling with Greater Bay Area connectivity. China Links Travel exemplifies the heritage specialization archetype, occupying a position in bespoke cultural programming that commands premium ancillary spend.
| Leading Market Players |
|---|
| Intrepid Travel |
| Globus |
| Fosun Tourism Group |
| Uniworld |
| China Links Travel |
| EGL Holdings |
| Explore! |
| SmarTours |
| WWPKG Holdings |
| Others |
Value Chain & Pricing Dynamics
AI-powered visitor flow management simultaneously compresses operational cost structures at heritage sites and concentrates pricing power among platform intermediaries that aggregate timed-entry inventory. The shift from static capacity allocations to dynamic demand-matching redraws margin distribution between asset owners and digital aggregators.
Pricing Analysis
Bundled experience packaging versus unbundled à la carte services splits pricing architecture across the Hong Kong tourism market. Three-tier pricing structure across premium, standard, and economy levels captures divergent visitor archetypes, with heritage site timed-entry slots and integrated resort convergence commanding premium positioning. Price differentiation rests on Mandarin-Cantonese-English service fluency and exclusive harborfront access rights. Cost compression in budget accommodation intensifies as platform intermediation erodes traditional agency markups. Backpacking segments from Southeast Asia exhibit highest price sensitivity, while luxury extended-stay visitors from mainland China demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Guangzhou anchor hub-and-spoke patterns for cross-border visitor services, with secondary nodes in Hong Kong's harborfront districts handling last-mile experience delivery. Geographic supply concentration centers on China's Greater Bay Area for Mandarin-speaking guide talent, Thailand and the Philippines for hospitality labor, and Japan for premium service training protocols. Raw material dependencies span hotel furnishings from mainland China, food and beverage inputs from Australia and New Zealand, and technology infrastructure from South Korea. Single-source vulnerability in cross-border permit processing by China's National Immigration Administration threatens demand pipeline stability. Distribution runs through experience-based booking platforms that displace traditional travel agency channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong tourism functions as a regulatory compounder where China's Individual Visit Scheme permit relaxation serves as the primary demand accelerator. The National Immigration Administration's unilateral authority over cross-border mobility creates both growth catalysts and structural vulnerability.
For Market Incumbents: Deepen vertical integration into Lantau Island resort assets to capture extended-stay spending outside urban density constraints. Incorporate AI-powered flow management to defend margin position against platform intermediaries that aggregate timed-entry inventory. The Travel Industry Council of Hong Kong's escalating escrow requirements threaten smaller operator solvency, creating consolidation opportunity for balance-sheet-strong incumbents. For New Entrants and Emerging Players: Launch via experience-based booking platforms that aggregate heritage site slots, harborfront dining, and outlying island transport into unified purchase paths. Target couples pursuing bespoke heritage photography and boutique dining in Central and Kowloon districts, the fastest-climbing segment as traditional agency intermediation erodes. White-space opportunity concentrates in Mandarin-Cantonese-English multilingual service talent provision. For Investors and Strategic Acquirers: Valuations sit cheapest among outbound-inbound tour bundlers with Greater Bay Area connectivity. Long-term viability hinges on regulatory alignment between China's National Immigration Administration and Hong Kong's Commerce and Economic Development Bureau across the projection horizon. Acquisition target archetype: heritage experience specialists with exclusive timed-entry relationships at constrained Central landmarks. The signal to watch is permit digitization pace and data-sharing protocol tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Destination Platform Deployment | AI-powered flow management at Victoria Harbour viewpoints compresses underutilized slot wastage and optimizes constrained asset yields. |
| Integrated Resort Convergence | Mixed-use hospitality-entertainment-retail complexes capture mainland visitor spending across multiple Lantau Island touchpoints. |
| Outbound-Inbound Bundling Partnership | Dual-destination packaging with Greater Bay Area cities deepens per-trip yield and extends booking windows for operators. |
| Multilingual Service Talent Acquisition | Frontline recruitment pipelines from Shenzhen and Guangzhou address Mandarin-Cantonese-English fluency gaps in harborfront districts. |
| Heritage Site Timed-Entry Digitization | Predictive analytics matching ticket release to real-time demand signals upgrade revenue models at constrained Central landmarks. |
Study Parameters
Direct dialogue with hotel operations directors, heritage site concessionaires, cross-border tour operators, and Travel Industry Council of Hong Kong compliance officers grounded qualitative findings. Secondary validation drew from China's National Immigration Administration permit issuance data, Hong Kong Tourism Commission visitor statistics, Commerce and Economic Development Bureau hotel licensing records, and Greater Bay Area transport authority disclosures. Bottom-up property-level capacity analysis and top-down macro demand modeling triangulated volume and value estimates.
Bottom-up segmentation by customer type, service type, attraction type, and travel style anchored the analytical framework across the modeling period. CAGRs derived from time-series regression against permit issuance velocity, hotel occupancy elasticity, and heritage site throughput constraints. Industry-specific forecast inputs included Individual Visit Scheme expansion trajectories and smart destination platform adoption curves at Victoria Harbour and Lantau Island.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unilateral permit suspension by China's National Immigration Administration or harborfront preservation zone expansion moratoria. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Luxury Travel Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
UK Outbound Travel Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
China Outbound Travel Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Japan Travel Retail Market