
 Halal Tourism Market | 2026-2036
Halal Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Tourism Market Outlook
Aftermarket service revenue from curated halal experiences is rewriting how travel platforms capture margin pools in faith-aligned hospitality. HalalBooking leverages proprietary certification verification to sustain premium positioning across Mediterranean and Southeast Asian properties. Tourism Malaysia anchors destination marketing through government-backed halal ecosystem development, while Rooh Travel Limited specializes in bespoke pilgrimage-adjacent itineraries that differentiate on spiritual authenticity rather than price.
Halal tourism encompasses travel services and destinations compliant with Islamic dietary laws, prayer requirements, and modesty standards, typically integrating halal-certified food preparation, gender-appropriate facilities, and alcohol-free environments into hospitality operations. The sector's primary commercial purpose centers on capturing expenditure from Muslim travelers who prioritize faith-compatible amenities alongside conventional leisure or business objectives. Accommodation and dining services within the Service Type dimension dominate current revenue capture due to certification infrastructure maturity, while Cultural Experiences within Package Type represent the fastest-growing margin pool as Muslim millennials seek heritage immersion beyond traditional pilgrimage. Pilgrimage Visitors within Customer Type retain the highest per-trip spend concentration, though Leisure Travelers now deliver the largest absolute volume expansion across booking platforms.
Malaysia's Islamic Tourism Centre and Indonesia's MUI halal certification framework shape product standards and market access across Southeast Asian destination markets, with Saudi Arabia's Saudi Tourism Authority adding pilgrimage capacity regulations that directly influence Umrah package economics. The EU's broader consumer protection directives intersect with member-state halal labeling requirements, creating compliance complexity for European operators serving outbound Muslim travelers. Stakeholders must monitor how Gulf state tourism privatization and competing national halal certification mutual recognition agreements reshape destination competitiveness and supplier qualification thresholds.
Market Dynamics
Muslim millennial leisure travelers are redefining demand architecture, forcing platforms to recalibrate certification infrastructure around heritage immersion and digital-native booking behaviors rather than traditional pilgrimage package economics.
Growth Catalysts
- Malaysia's ITC Certification Framework:Government-backed halal ecosystem development reduces supplier qualification friction, accelerating property onboarding across Southeast Asian destinations.
- Digital Booking Platforms:Proprietary verification algorithms collapse information asymmetry between Muslim travelers and halal-compliant accommodations, compressing search-to-booking cycles.
- Heritage Immersion Demand:Cultural experience packages now outpace traditional Umrah volume expansion as Indonesian and Malaysian millennials prioritize ancestral destination exploration.
Market Restraints
- Certification Cost Structure:Multi-jurisdictional halal audit fees from Indonesia's MUI and Malaysia's JAKIM create fixed cost barriers for small-scale hospitality operators.
- Supply Concentration Risk:Southeast Asian destination infrastructure investment clusters in Jakarta and Kuala Lumpur, leaving secondary cities with certification gaps.
- Regulatory Fragmentation:Competing national halal standards without mutual recognition agreements force redundant compliance spend across Gulf state and ASEAN markets.
Strategic Opportunities
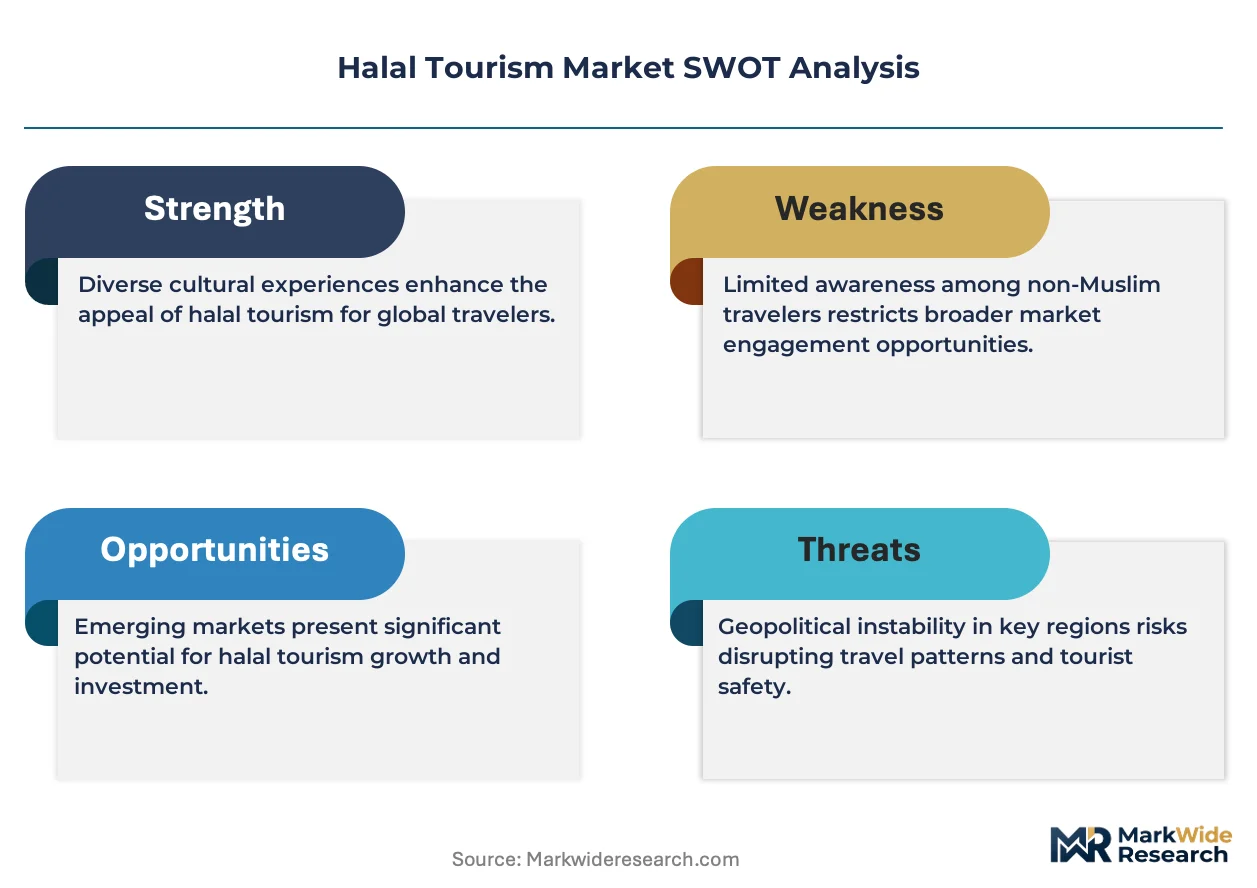
- Turkiye's Mediterranean Coastline:Underpenetrated resort infrastructure offers first-mover positioning for faith-aligned hospitality concepts targeting European Muslim outbound.
- AI-Driven Personalization:Machine learning prayer-time calculators and qibla orientation tools converge with booking engines to create stickier platform relationships.
- Saudi Vision 2030 Pilgrimage Expansion:Nusuk platform digitization and Umrah visa liberalization open adjacent leisure packaging around religious travel.
Industry Challenges
- Halal Auditor Talent Scarcity:Cross-functional expertise combining Islamic jurisprudence and hospitality operations remains concentrated in Malaysia and Indonesia.
- Legacy Property Retrofit Costs:Gender-segregated facility reconfiguration and alcohol removal impose capex burdens on established resort operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Tourism Market |
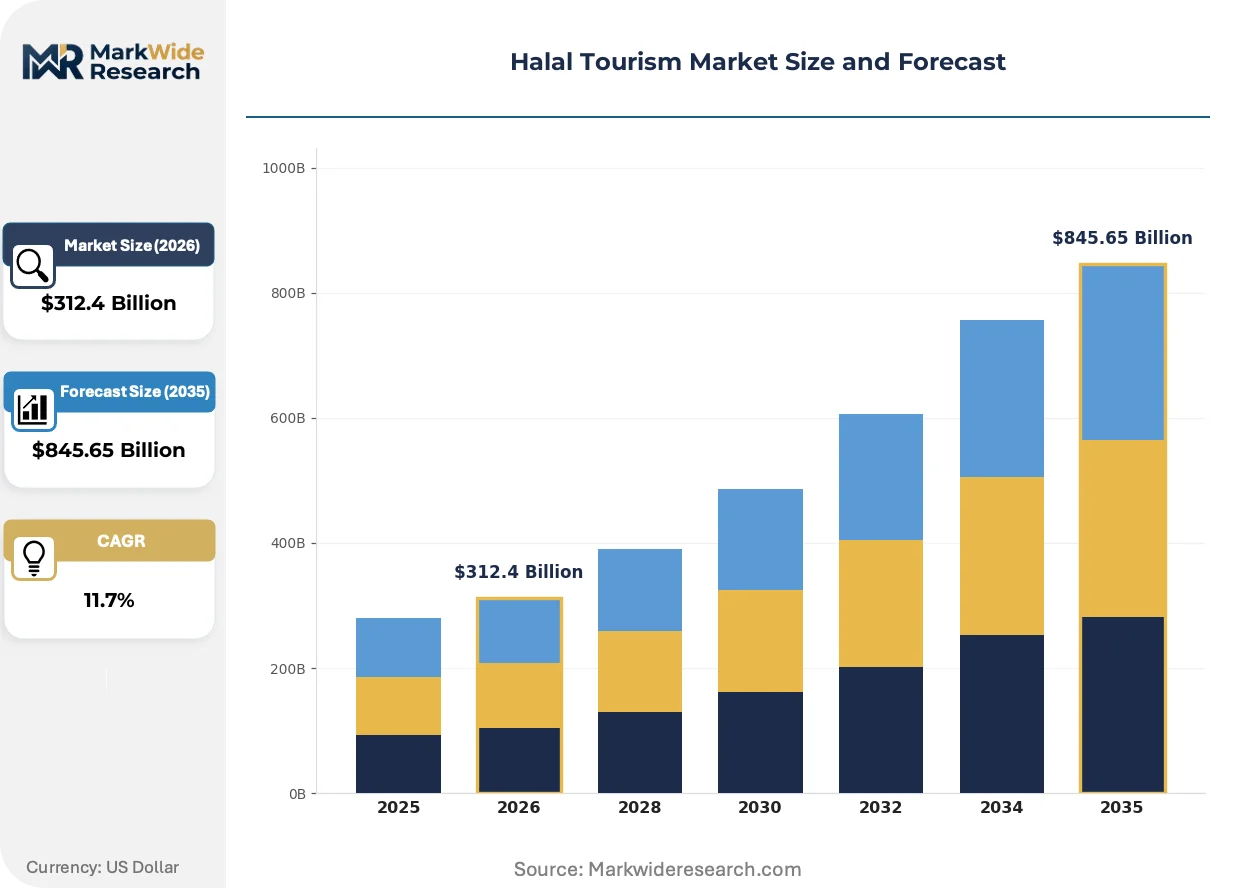
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $845.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Accommodation, Dining, Entertainment, Transportation Package Type: Family Packages, Solo Travel, Group Tours, Cultural Experiences Customer Type: Leisure Travelers, Business Travelers, Pilgrimage Visitors, Family Travelers Activity Type: Religious Tours, Cultural Excursions, Wellness Retreats, Adventure Activities |
| Companies Covered | Al Habtoor Group, Rooh Travel Limited, HalalBooking, SalamBooking, Archer & Gaher Adventures, HalalTrip, Halal Tours, The Muslim Women Travel Group, Tourism Malaysia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Tourism Market Strategic Shifts
Technology-enabled trust verification and regulatory harmonization efforts are compressing the gap between Muslim traveler expectations and mainstream hospitality capabilities, while generational demand shifts reward platforms that embed spiritual authenticity into leisure infrastructure.
Blockchain-based halal supply chain tracking is collapsing certification verification timelines from weeks to hours. Saudi Arabia's Saudi Tourism Authority and UAE hospitality groups pilot distributed ledger systems for food provenance and prayer facility compliance. This compression eliminates intermediary audit bottlenecks that previously constrained property scaling.
Indonesia's Omnibus Law harmonization streamlines MUI certification overlap with national tourism investment incentives. The regulatory consolidation reduces bureaucratic friction for foreign hospitality investors targeting the archipelago's 17,000-island destination potential. Domestic operators accelerate certification adoption to capture redirected Middle Eastern outbound.
Muslim millennial travelers now book heritage immersion experiences through direct-to-consumer platforms, bypassing traditional travel agency intermediaries. HalalBooking and regional specialists capture margin pools previously held by pilgrimage package consolidators. Turkiye and Morocco witness the sharpest channel disintermediation as digital-native travelers prioritize self-curated itineraries over group structures.
Halal Tourism Market Segmentation
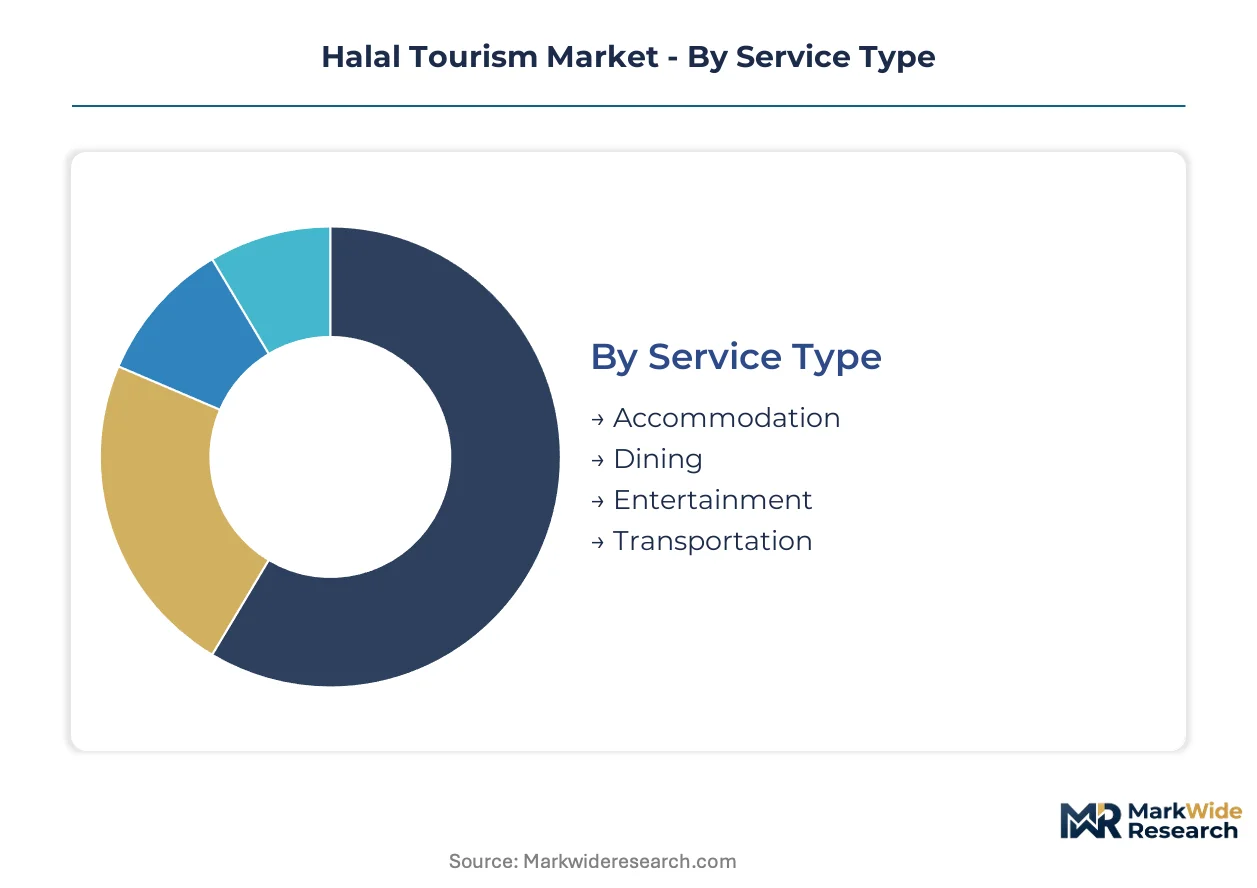
Segmentation in halal tourism reveals how certification infrastructure maturity varies dramatically across service categories, with accommodation and dining commanding established compliance frameworks while entertainment and transportation lag in standardized verification. Understanding these maturity differentials helps stakeholders allocate capital toward segments where halal authentication creates measurable pricing power.
Service Type:
Mature certification ecosystems dominate accommodation and dining, while entertainment and transportation remain fragmented with emerging halal compliance protocols.
- Accommodation:Properties integrate gender-appropriate facilities, alcohol-free environments, and prayer room infrastructure. Demand concentrates in Southeast Asian urban clusters where Malaysia's JAKIM and Indonesia's MUI certification reduce booking friction for Muslim travelers seeking verified compliance.
- Dining:Halal-certified kitchen operations and supply chain verification form the core value proposition. Saudi Arabia and UAE hospitality groups deploy blockchain tracking to collapse certification timelines, capturing premium positioning in Gulf state markets where dietary compliance is non-negotiable.
- Entertainment:Alcohol-free venues and gender-segregated programming serve faith-aligned leisure seekers. Indonesian operators retrofit existing attractions to capture domestic millennial demand.
- Transportation:Prayer-friendly scheduling and halal meal provisioning differentiate carriers. Malaysian airlines anchor regional connectivity with certified cabin services.
Accommodation retains volume leadership; entertainment holds the steepest expansion curve as heritage immersion experiences reshape demand architecture.
Package Type:
Margin concentration shifts from traditional group structures toward self-curated itineraries as digital-native travelers bypass legacy intermediaries.
- Family Packages:Multi-generational accommodations with child-friendly halal amenities and supervised gender-appropriate activities. Demand clusters in Turkish Mediterranean resorts serving European Muslim outbound.
- Solo Travel:Safety-verified properties and female-friendly hospitality concepts targeting Muslim women travelers. Platforms like HalalBooking capture this segment through proprietary certification filters.
- Group Tours:Pilgrimage-adjacent logistics and fixed-itinerary heritage circuits. Moroccan operators maintain share through spiritual authenticity positioning.
- Cultural Experiences:Ancestral destination exploration and heritage immersion programming. Indonesian and Malaysian millennials drive fastest expansion through direct-to-consumer booking channels.
Group tours retain volume leadership; cultural experiences gain share fastest as generational preferences disintermediate traditional package economics.
Customer Type:
Per-trip spend concentration varies sharply across traveler motivations, with pilgrimage visitors maintaining premium outlays while leisure volumes scale through platform digitization.
- Leisure Travelers:Heritage-focused itineraries and wellness-oriented halal hospitality. Southeast Asian millennials anchor volume expansion through smartphone-native booking behaviors.
- Business Travelers:Prayer-friendly meeting facilities and halal-certified corporate dining. UAE and Saudi Arabia infrastructure investment captures MICE segment migration.
- Pilgrimage Visitors:Umrah and Hajj-adjacent packaging with highest per-trip expenditure concentration. Saudi Vision 2030 digitization through Nusuk platform reshapes adjacent leisure capture.
- Family Travelers:Multi-room accommodations and child-centric halal amenities. Turkish operators target European diaspora through summer season concentration.
Pilgrimage visitors retain spend leadership; leisure travelers climb the fastest on absolute volume as certification infrastructure democratizes access.
Activity Type:
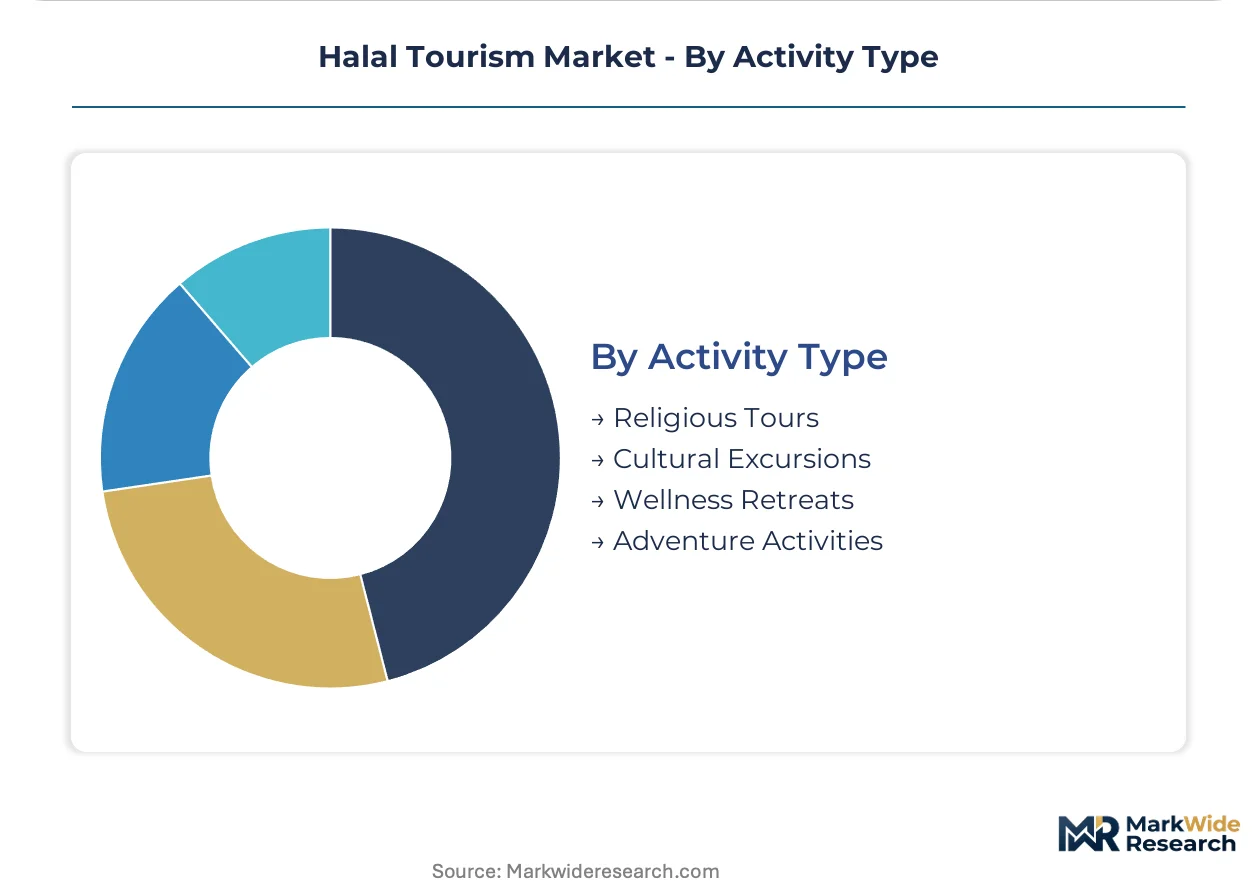
Experience design now differentiates on spiritual authenticity integration rather than binary halal compliance alone.
- Religious Tours:Mosque visits, Islamic heritage site programming, and scholar-led educational itineraries. Saudi Arabia and Morocco anchor supply through endowment-controlled site access.
- Cultural Excursions:Ancestral homeland exploration and artisan craft immersion. Indonesian demand concentrates on Middle Eastern and North African destinations.
- Wellness Retreats:Gender-segregated spa services and Islamic mindfulness programming. Malaysian operators pioneer halal wellness certification standards.
- Adventure Activities:Alcohol-free expedition logistics and prayer-time accommodating schedules. Turkish Mediterranean coastline offers underpenetrated positioning.
Religious tours retain volume leadership; cultural excursions expand most quickly as heritage identity drives destination selection beyond traditional pilgrimage circuits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Halal tourism infrastructure investment clusters disproportionately in Southeast Asian and Middle Eastern jurisdictions where government-backed certification frameworks reduce supplier qualification friction. Malaysia and Indonesia anchor capacity expansion through national halal ecosystem development, while Saudi Arabia's pilgrimage digitization and Turkiye's Mediterranean positioning reshape destination competitiveness.
Malaysia
Domestic millennial leisure demand and Middle Eastern inbound traffic drive property certification adoption across the Klang Valley and Penang Island clusters. The Islamic Tourism Centre's JAKIM-aligned standards reduce audit redundancy for hospitality operators seeking multi-territory compliance. Kuala Lumpur's integrated halal ecosystem concentrates platform headquarters and auditor training capacity.
Indonesia
Archipelago-wide heritage immersion itineraries and domestic pilgrimage-adjacent travel expand booking platform penetration beyond Java-centric infrastructure. MUI certification harmonization under Omnibus Law streamlines foreign investor qualification for resort development in Bali and Lombok. Jakarta anchors certification authority concentration while Yogyakarta specializes in cultural experience programming.
Saudi Arabia
Umrah visa liberalization and Nusuk platform digitization open adjacent leisure packaging around religious travel in Makkah and Madinah corridors. The Saudi Tourism Authority's capacity regulations directly influence package economics for adjacent hospitality operators. Riyadh concentrates government-backed ecosystem investment while Jeddah anchors Red Sea coastal resort development.
Turkiye
European Muslim outbound demand and underpenetrated Mediterranean coastline position Antalya and Bodrum for faith-aligned resort concepts. The country's national tourism investment incentives reduce capex barriers for alcohol-free property retrofits. Istanbul anchors platform technology development while coastal provinces specialize in family-package hospitality infrastructure.
United Arab Emirates
Dubai and Abu Dhabi hospitality groups deploy blockchain verification pilots for food provenance tracking across integrated resort properties. MOHAP-aligned regulatory frameworks intersect with federal tourism privatization to reshape supplier qualification thresholds. Ras Al Khaimah emerges as secondary destination for heritage immersion programming targeting South Asian outbound segments.
Halal Tourism Market Competitive Environment
Digital-native booking platforms and government-backed destination marketers split the market between proprietary verification algorithms and certification ecosystem development. The competitive structure rewards first-mover positioning in underpenetrated Mediterranean and Southeast Asian corridors where halal-compliant property supply lags demand expansion. Two dominant strategic archetypes emerge: technology-enabled aggregators leveraging machine-learning personalization, and destination authorities anchoring supply-side certification infrastructure. Primary competitive moves center on M&A targeting regional specialist platforms and vertical integration into proprietary audit capabilities.
Within the technology-aggregator tier, HalalBooking and Rooh Travel Limited exemplify contrasting positioning approaches. HalalBooking anchors European and Southeast Asian property networks through proprietary certification verification filters. Rooh Travel Limited occupies a specialist position in bespoke pilgrimage-adjacent itinerary design. Tourism Malaysia represents the destination-authority archetype, embedding government-backed ecosystem development into competitive positioning.
| Leading Market Players |
|---|
| Al Habtoor Group |
| Rooh Travel Limited |
| HalalBooking |
| SalamBooking |
| Archer & Gaher Adventures |
| HalalTrip |
| Halal Tours |
| The Muslim Women Travel Group |
| Tourism Malaysia |
| Others |
Value Chain & Pricing Dynamics
Malaysia's JAKIM auditor training capacity concentrates upstream certification expertise, directing margin pools toward platforms that collapse verification timelines rather than properties bearing redundant audit costs.
Pricing Analysis
Malaysia's ITC certification framework dictates the pricing tier structure across Southeast Asian hospitality markets. Three-tier pricing structure across premium, standard, and economy levels separates JAKIM-verified resorts from self-certified properties and uncertified alternatives. Price differentiation rests on audit depth, with blockchain-tracked supply chains commanding premium positioning. Pricing pressure stems from Indonesia's MUI harmonization reducing cross-border certification premiums. Leisure travelers show highest price sensitivity; pilgrimage visitors absorb premium tiers for verified compliance.
Supply Chain Analysis
Tariff exposure between Indonesia and Middle Eastern source markets dominates supply chain risk architecture for halal food provisioning in tourism properties. Geographic supply concentration clusters in Malaysia, Indonesia, and Saudi Arabia for certification authority and auditor talent. Raw material dependencies include halal-slaughtered protein, prayer facility construction materials, and gender-segregation retrofit components. Single-source vulnerability sits with Malaysia's concentrated auditor training capacity. Distribution runs through platform-mediated direct booking channels disintermediating legacy pilgrimage consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as Muslim millennial demand splinters across heritage immersion niches, rewarding specialized positioning over generalized halal compliance.
For Market Incumbents: Entrench certification infrastructure moats through proprietary blockchain verification development and captive auditor training academies in Kuala Lumpur. Incumbents must absorb Indonesia's MUI harmonization threat by securing multi-jurisdiction audit reciprocity before competitors achieve scale. Backward integration into halal supply chain tracking technology anchors pricing power against platform disintermediation. For New Entrants and Emerging Players: Turkish Mediterranean coastline resorts represent the most penetrable entry point, with undercertified capacity and European Muslim outbound demand convergence. Secondary Indonesian cities outside Jakarta-Yogyakarta corridors offer whitespace for MUI-certified boutique properties. Direct-to-consumer heritage immersion packaging bypasses incumbent platform commission structures. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform-auditor combinations with multi-territory certification coverage. Long-term viability favors assets capturing both Southeast Asian domestic millennial leisure and Middle Eastern pilgrimage-adjacent packaging. Monitor Saudi Vision 2030 Nusuk platform API access policies as inflection signal for adjacent leisure capture economics.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Verification Deployment | Saudi Arabia's Saudi Tourism Authority pilots collapse certification timelines from weeks to hours. |
| Auditor Training Academy Buildout | Malaysia's JAKIM-aligned programs address talent scarcity constraining property scaling. |
| Heritage Immersion Content Development | Indonesian operators capture redirected Middle Eastern outbound through ancestral destination programming. |
| Multi-Jurisdiction Certification Reciprocity | ASEAN mutual recognition agreements reduce redundant compliance spend for regional chains. |
| Direct-to-Consumer Platform Launch | HalalBooking's proprietary filters demonstrate margin capture from disintermediated pilgrimage consolidators. |
Study Parameters
The analysis maps accommodation certification tiers, package type economics, and customer segment spending patterns, each validated through hospitality operations directors, platform technology leads, and certification authority officials. Primary interviews with Islamic Tourism Centre program managers, JAKIM auditors, and MUI compliance officers combine with secondary validation against tourism investment databases, national halal certification registries, and booking platform transaction disclosures. Bottom-up property-level revenue modeling and top-down national tourism expenditure data achieve triangulation.
Assumptions hold fixed current certification mutual recognition status while varying pilgrimage visa liberalization pace and millennial leisure preference evolution across the projection horizon. Segmentation dimensions include service type maturity, package type margin structure, customer type spend concentration, and activity type experience design complexity. CAGRs derive from property onboarding velocity, platform penetration curves, and certification infrastructure investment flows. Blockchain verification adoption rates and auditor training pipeline capacity serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Middle Eastern outbound travel expenditure and Indonesian domestic consumption trajectories would shift the trajectory. Forecasts reflect documented assumptions on certification harmonization timelines and platform technology diffusion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
South Africa Sports Tourism Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Russia Outbound Tourism Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Solo Ecotourism Market