
 Eyeliner Pen Market | 2026-2036
Eyeliner Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Eyeliner Pen Market Foresight
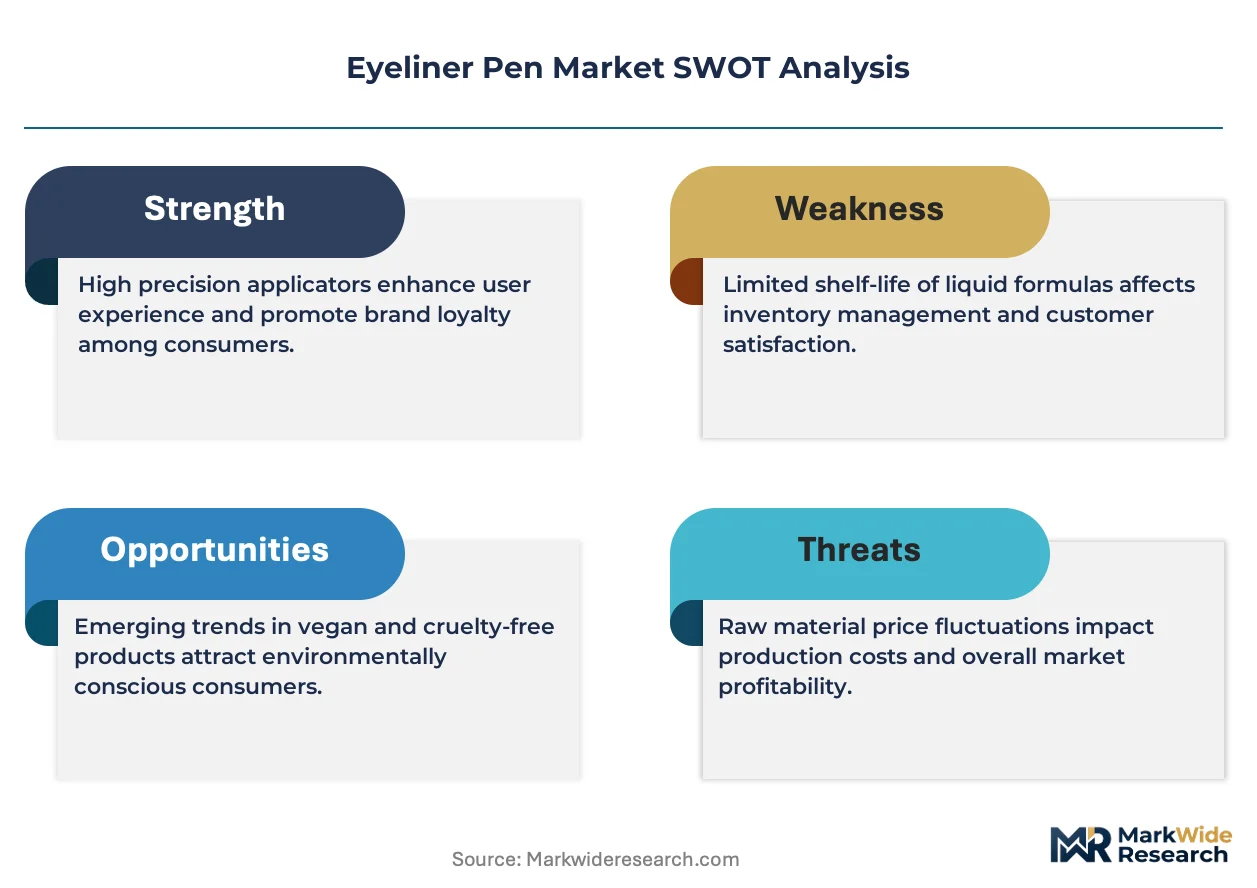
Dual-ended and modular applicator configurations is restructuring how consumers evaluate value in the Eyeliner Pen Market. L'Oreal S.A. leverages its integrated R&D pipeline to dominate liquid and felt-tip innovation across European retail channels. The Estee Lauder Companies Inc. anchors premium positioning through controlled specialty store distribution. Shiseido Company, Limited competes with precision manufacturing scale in gel formulations for East Asian markets.
An eyeliner pen is a cosmetic applicator delivering pigment via a reservoir-fed tip, typically formulated with film-forming polymers, waxes, and colorants suspended in solvent or water bases, engineered to deposit consistent lines along the lash line for aesthetic definition. Liquid formulations sustain the largest revenue pool due to their dominance in professional and dramatic wear applications, while vegan and hypoallergenic segments capture expanding margin pools as clean beauty claims harden into purchase criteria. Waterproof formulations occupy the most technically demanding tier, requiring specialized polymer chemistry that differentiates specialist suppliers from commodity blenders.
REACH in Europe and FDA color additive regulations in the United States constrain permissible pigment chemistries, pushing manufacturers toward reformulation investments that raise compliance costs but lock out unqualified entrants. China's SAMR cosmetic registration rules and GB standards for eye-area products add parallel testing burdens for brands sourcing from or selling into that production base. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid fragmented certification costs that erode cross-border economics.
Market Dynamics
Dual-ended applicator configurations are compressing traditional single-format value propositions, while REACH and RoHS compliance in Europe forces reformulation investments that lock out unqualified pigment suppliers.
Growth Catalysts
- Professional makeup artist segment:This end-use vertical sustains premium demand for precision liquid formulations and modular tip systems across theatrical, bridal, and editorial applications.
- REACH compliance:European regulatory pressure on film-forming polymers and colorant chemistries accelerates R&D investment by qualified manufacturers, creating certification moats against commodity competitors.
- South Korea beauty innovation cluster:Concentrated formulation expertise in Seoul and Gyeonggi-do drives rapid prototyping cycles for waterproof polymer systems that diffuse into global product pipelines.
Market Restraints
- Specialized polymer input costs:Acrylates copolymer and polyurethane film formers face petrochemical feedstock volatility, compressing margin pools for waterproof tier manufacturers.
- China SAMR registration burden:Parallel testing requirements for GB-compliant eye-area safety assessments add certification timelines that delay new formulation launches by qualified entrants.
- Gel formulation substitution:Pot-applied gel eyeliners retain cost advantages in mass-market segments, constraining pen-format penetration in price-sensitive demographics.
Strategic Opportunities
- Vegan certification white space:Unmet demand for plant-derived film formers and synthetic-free colorants creates margin expansion potential in clean beauty positioning.
- Hypoallergenic tier development:Fragrance-free and ophthalmologist-tested formulations address underserved sensitive-eye consumer segments with limited current supply.
- Direct-to-consumer channel innovation:Subscription-based replenishment models bypass traditional retail markup structures, capturing recurring revenue from high-frequency users.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in eye-safe polymer rheology and pigment dispersion commands premium compensation, constraining mid-tier manufacturer scale-up.
- Cross-jurisdiction certification complexity:Divergent FDA, REACH, and SAMR color additive lists force parallel stability testing programs that fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eyeliner Pen Market |
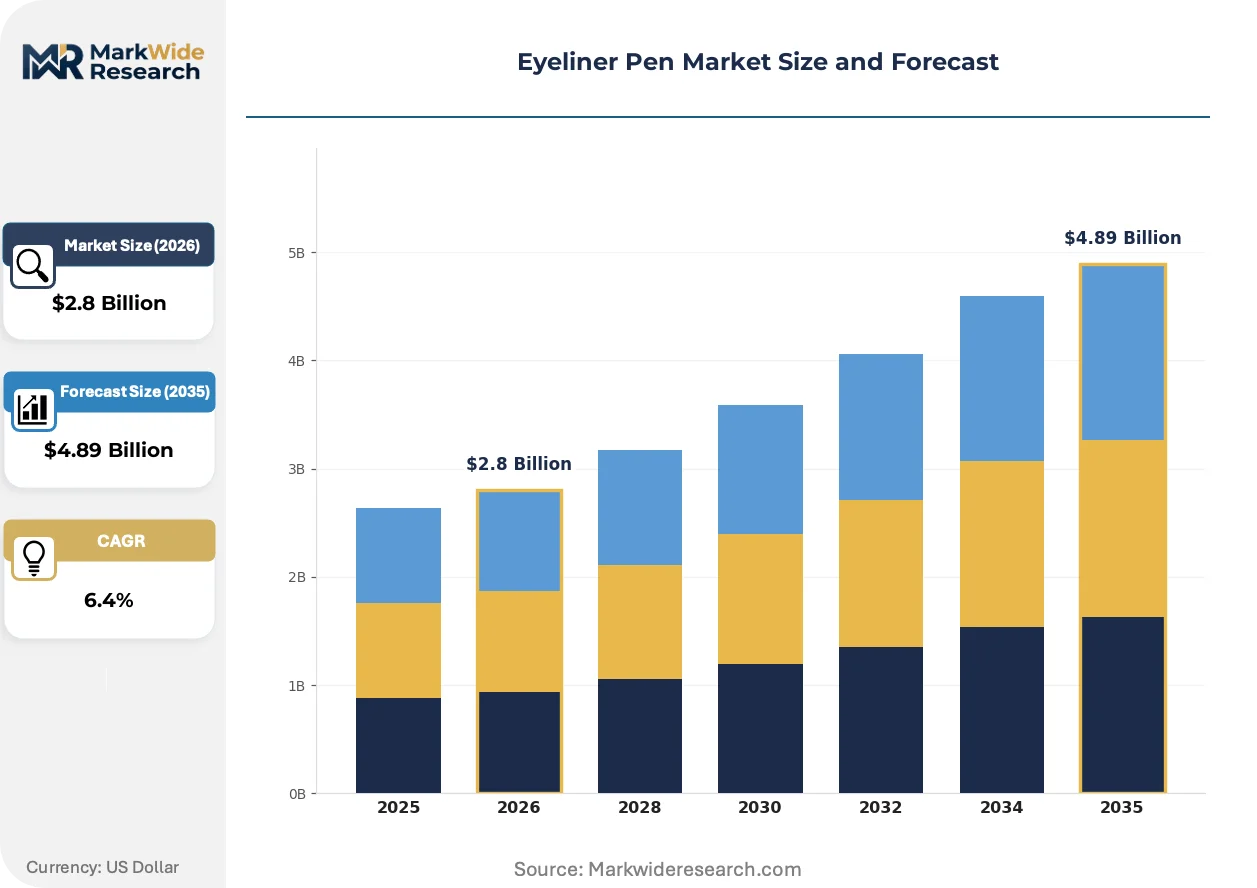
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Felt-tip, Pencil Formulation: Waterproof, Smudge-proof, Vegan, Hypoallergenic End User: Professional Makeup Artists, Consumers, Salons, Studios Distribution Channel: Online, Supermarkets, Specialty Stores, Beauty Salons |
| Companies Covered | L'Oreal S.A., The Estee Lauder Companies Inc., Shiseido Company, Limited, Chanel S.A., Christian Dior SE, Kao Corporation, LG Household & Healthcare Limited, Amorepacific Corporation, Markwins International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eyeliner Pen Market Shifts & Advancements
Modular applicator architectures and clean chemistry claims are restructuring competitive differentiation, with regulatory compliance becoming a technical capability rather than a checkbox exercise.
Micro-fiber brush tip technology is absorbing market share from traditional felt-tip configurations by enabling variable line weight control through pressure modulation. Professional makeup artists in editorial and special-effects applications are adopting this format fastest, with South Korean manufacturers leading production scale. The technology is absorbing R&D investment that previously flowed into incremental felt-tip density improvements, compressing innovation cycles for legacy formats.
REACH authorization requirements for synthetic organic pigments are forcing substitution toward mineral and iron oxide alternatives in European formulations. This industrial consequence raises raw material costs but creates supply relationships with qualified pigment houses that smaller competitors cannot replicate. Waterproof and long-wear product categories face the steepest reformulation burden, with German and French manufacturers accelerating in-house toxicology screening capabilities.
Ingredient transparency scanning via mobile applications is altering purchase validation behavior among millennial and Gen-Z demographics. Specialty beauty retailers and direct-to-consumer channels are integrating QR-linked supply chain disclosures that mass-market drugstore formats struggle to match. This shift concentrates premium demand in channels with verified clean beauty credentials, most visible in urban coastal markets across the United States and Western Europe.
Eyeliner Pen Market Segmentation
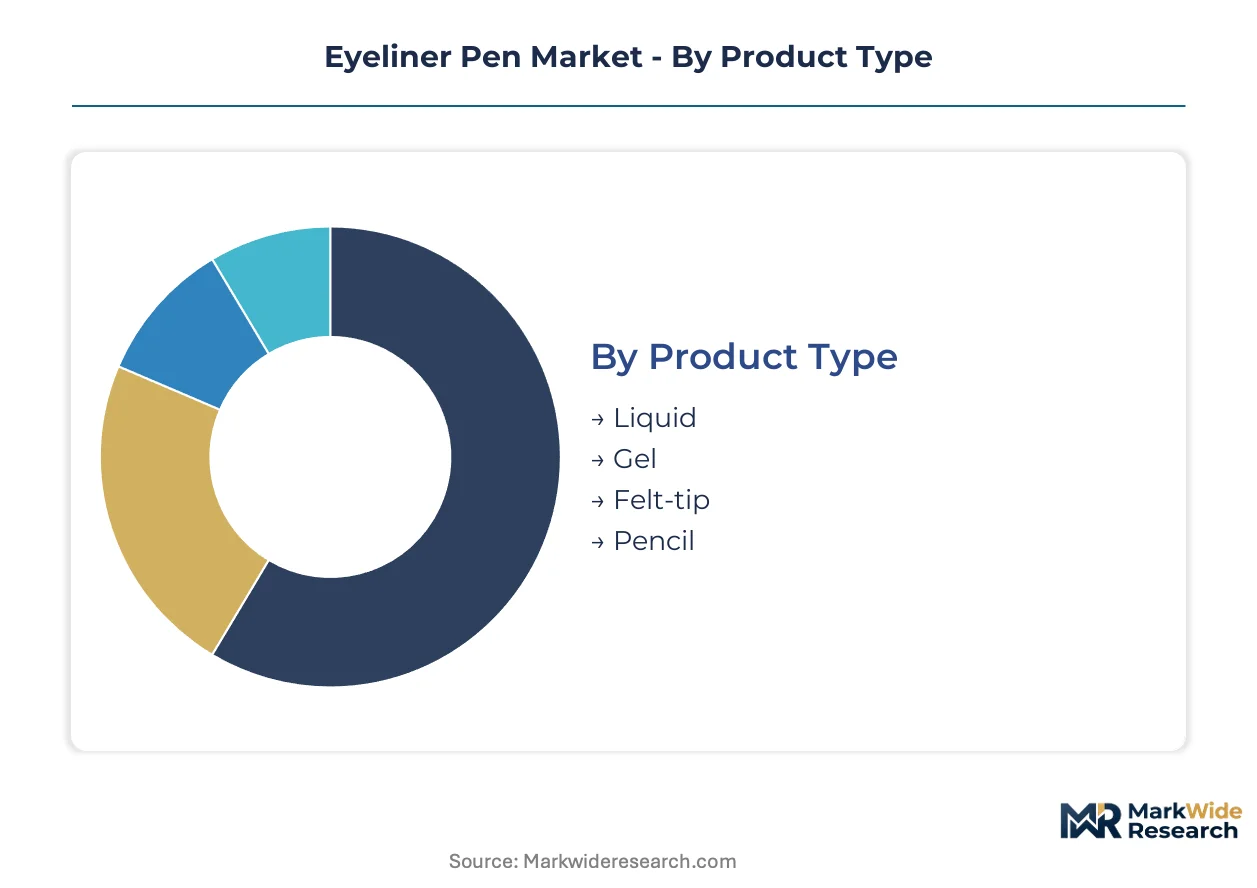
Segmentation in the Eyeliner Pen Market reveals how formulation chemistry and professional-grade specifications create distinct margin tiers. Supply-side capabilities cluster around waterproof polymer expertise and clean beauty certification, fragmenting competitive positioning across end-use verticals.
Product Type:
Manufacturing scale concentrates in liquid and felt-tip formats where precision tip engineering requires dedicated production lines.
- Liquid:Reservoir-fed systems deposit pigment through synthetic fiber or felt applicators, with film-forming polymers enabling 12-hour wear. Professional makeup artists in editorial and bridal applications sustain premium demand for precision line control and saturated color payoff.
- Felt-tip:Tapered fiber bundles allow variable line weight through pressure modulation, with South Korean manufacturers leading micro-fiber brush innovation. The format is displacing traditional felt configurations in theatrical and special-effects use cases where precision outweighs cost sensitivity.
- Gel:Thixotropic formulations require shear-thinning rheology for smooth deposition, with pot-applied alternatives retaining cost advantages in mass-market segments.
- Pencil:Wax-based cores with lower pigment load serve quick-application consumers, though tip sharpening infrastructure constrains format innovation.
Liquid absorbs the bulk of installed capacity; felt-tip is expanding most quickly.
Formulation:
Cost tier differentiation separates commodity waterproof blends from certified clean alternatives commanding formulation premiums.
- Waterproof:Acrylates copolymer and polyurethane film formers create occlusive barriers resistant to sebum and moisture. REACH authorization requirements for synthetic organic pigments force German and French manufacturers toward accelerated in-house toxicology screening.
- Vegan:Plant-derived film formers and synthetic-free colorants replace animal-derived glycerin and carmine, with unmet demand in millennial and Gen-Z demographics driving margin expansion.
- Smudge-proof:Hybrid polymer systems balance flexibility with adhesion, occupying mid-tier positioning between waterproof performance and removal ease.
- Hypoallergenic:Fragrance-free and ophthalmologist-tested formulations address sensitive-eye segments with limited current supply, creating white space for specialty positioning.
Waterproof formulations anchor volume production; vegan certification is climbing the fastest.
End User:
Application intensity varies dramatically between high-frequency professional use and occasional consumer purchase patterns.
- Professional Makeup Artists:Daily tool replacement and modular tip system adoption sustain premium demand across theatrical, bridal, and editorial verticals.
- Consumers:Mass-market purchase cycles concentrate in drugstore and online channels, with price sensitivity favoring multi-use pencil formats.
- Salons:Backbar inventory requirements favor bulk liquid refills and disposable applicator hygiene protocols.
- Studios:Film and television production demands extreme wear performance, with specialized effects applications requiring custom color matching services.
Professional makeup artists absorb the bulk of precision-format capacity; studio applications are gaining share fastest.
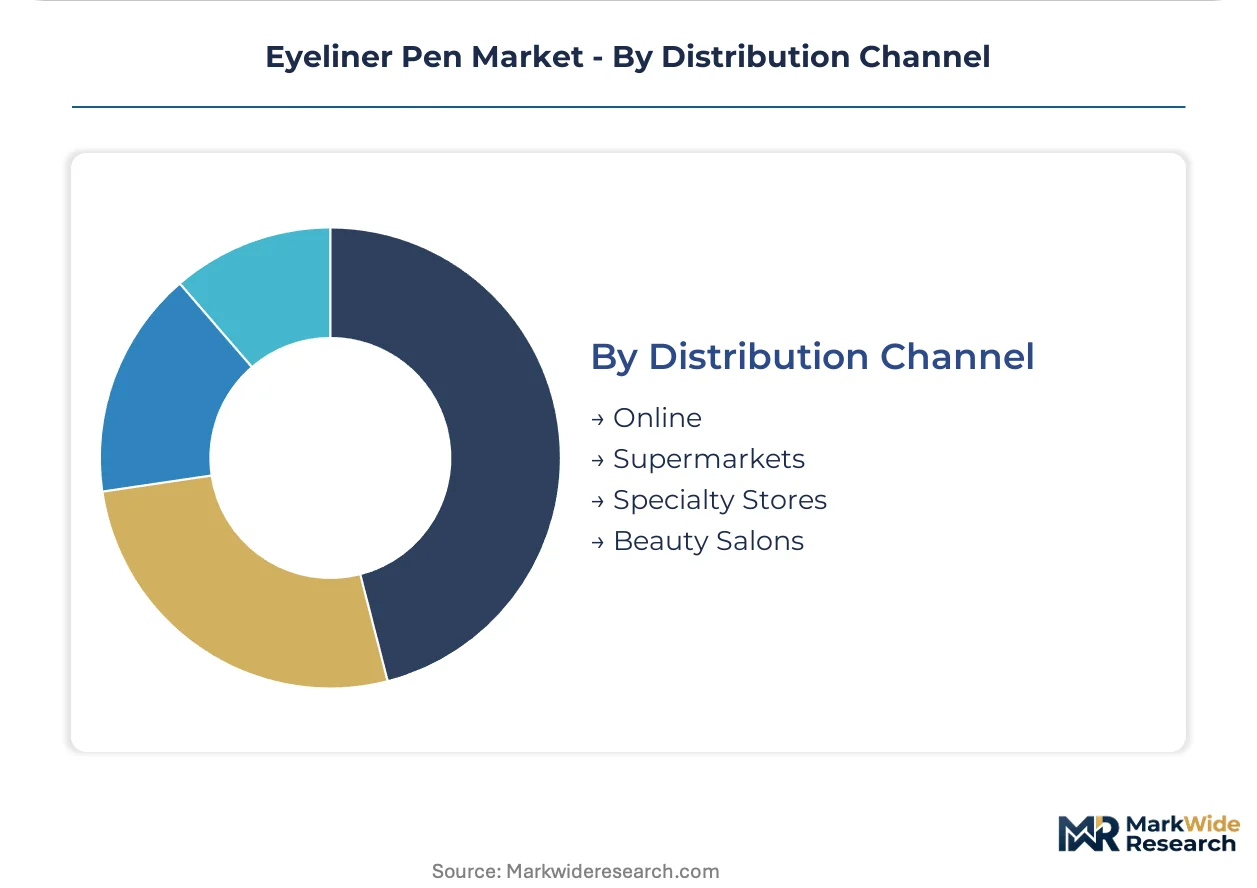
Distribution Channel:
Customer type determines channel preference, with transparency requirements fragmenting retail formats.
- Specialty Stores:Controlled environments enable ingredient consultation and shade matching, with QR-linked supply chain disclosures verifying clean beauty credentials.
- Online:Direct-to-consumer subscription models capture recurring revenue from high-frequency users, bypassing traditional retail markup structures.
- Supermarkets:Mass-market velocity favors recognizable brands and promotional pricing, constraining niche format penetration.
- Beauty Salons:Professional-only SKUs and backbar sizing create channel-specific product lines with distinct margin profiles.
Specialty stores retain the bulk of premium positioning; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Incheon Free Economic Zone concentrates formulation R&D for waterproof polymer systems, with Seoul-Gyeonggi corridor manufacturers supplying precision micro-fiber brush technology to global beauty brands.
United States
FDA color additive regulations constrain permissible pigment chemistries for eye-area products, pushing Los Angeles and New York-based formulators toward accelerated stability testing programs. California's clean beauty legislative momentum creates parallel certification requirements that fragment cross-state distribution economics.
Germany
REACH authorization requirements for synthetic organic pigments force Hamburg and Düsseldorf manufacturers toward mineral and iron oxide alternatives. Bavarian chemical clusters develop in-house toxicology screening capabilities that lock out unqualified pigment suppliers from premium waterproof tier supply.
France
ANSM oversight of cosmetic safety assessments combines with ECHA enforcement to raise reformulation costs for Paris-based luxury houses. Île-de-France formulation laboratories concentrate expertise in film-forming polymer rheology for long-wear professional applications.
China
SAMR cosmetic registration rules and GB standards for eye-area products impose parallel testing timelines that delay new formulation launches. Shanghai and Guangzhou manufacturing bases absorb the bulk of domestic volume production while navigating dual carbon goals that constrain petrochemical feedstock access.
South Korea
MFDS cosmetic safety regulations intersect with concentrated formulation expertise in Seoul and Incheon to drive rapid prototyping cycles for modular applicator systems. Gyeonggi-do manufacturing clusters supply micro-fiber brush innovation that diffuses into global professional makeup artist channels.
Eyeliner Pen Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning strata. The vendor base organizes around three strategic archetypes: multinational beauty houses with integrated R&D pipelines, regional champions leveraging manufacturing scale, and specialist suppliers concentrated in polymer chemistry or precision applicator engineering. Dominant competitive moves include backward integration into captive film-former production and geographic expansion through controlled specialty retail distribution.
Within the multinational beauty house tier, L'Oreal S.A., The Estee Lauder Companies Inc., and Shiseido Company, Limited exemplify divergent strategic positioning. The Paris-based conglomerate anchors European liquid formulation innovation through retail channel density. The New York-headquartered corporation occupies premium positioning via controlled specialty store distribution. The Tokyo-based manufacturer represents precision manufacturing scale in gel systems for East Asian market penetration.
| Leading Market Players |
|---|
| L'Oreal S.A. |
| The Estee Lauder Companies Inc. |
| Shiseido Company, Limited |
| Chanel S.A. |
| Christian Dior SE |
| Kao Corporation |
| LG Household & Healthcare Limited |
| Amorepacific Corporation |
| Markwins International Corporation |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock indices for acrylates copolymer and polyurethane film formers cascade through formulation tiers, compressing waterproof segment margins while elevating vegan-certified alternatives that command formulation premiums from clean beauty buyers.
Pricing Analysis
Margin tightening in waterproof formulations reflects acrylates copolymer feedstock volatility and REACH-driven reformulation costs. Three-tier pricing structure across premium professional-grade, standard retail, and economy mass-market levels separates precision micro-fiber brush systems from commodity felt-tip alternatives. Price differentiation hinges on ophthalmologist-tested certification and South Korean manufacturing origin. Cost-down pressure on mass-market tiers accelerates because gel pot substitutes retain unit economics advantages. Professional makeup artists exhibit lowest price sensitivity; drugstore consumers show highest elasticity.
Supply Chain Analysis
Film-forming polymer supply rests on German and French specialty chemical producers, with South Korean precision brush manufacturing feeding global assembly. Raw material dependencies center on petrochemical-derived acrylates, iron oxide pigments from Bavarian qualified suppliers, and micro-fiber bundles from Gyeonggi-do clusters. Single-source vulnerability concentrates in REACH-authorized pigment houses that lock out unqualified competitors. Distribution runs through controlled specialty retail and direct-to-consumer subscription channels that bypass traditional markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified formulation chemist scarcity props pricing across waterproof and vegan-certified tiers, constraining mid-tier manufacturer scale-up regardless of capital availability.
For Market Incumbents: Lock in backward integration into captive film-former production to defend against petrochemical feedstock volatility and REACH compliance cost escalation. Secure exclusive supply relationships with German and French qualified pigment houses before certification moats harden further. Prioritize in-house toxicology screening capabilities to accelerate European reformulation cycles. For New Entrants and Emerging Players: Modular applicator system innovation offers entry leverage into professional makeup artist channels underserved by legacy felt-tip configurations. Target hypoallergenic formulation white space where fragrance-free and ophthalmologist-tested supply remains limited. Pursue direct-to-consumer subscription models to bypass entrenched retail gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision manufacturing specialists in South Korea's Incheon corridor facing temporary export headwinds. Long-term viability hinges on clean beauty certification infrastructure and modular tip patent portfolios. Watch REACH authorization timelines for synthetic organic pigments as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film-Former Production | Captive acrylates copolymer supply insulates waterproof tier margins from petrochemical volatility. |
| REACH-Authorized Pigment House Acquisition | Qualified supplier relationships create certification moats against commodity formulation competitors. |
| Modular Applicator Patent Portfolio Buildout | Micro-fiber brush innovation captures professional makeup artist channel loyalty. |
| Direct-to-Consumer Subscription Launch | Recurring revenue models bypass traditional retail markup structures for high-frequency users. |
| In-House Toxicology Screening Investment | Accelerated European reformulation cycles reduce time-to-market for clean beauty claims. |
Research Methodology
Document review covered regulatory filings from ECHA, FDA, and SAMR, complemented by interviews with formulation chemists, professional makeup artists, specialty beauty retail buyers, and polymer supply specialists. Secondary validation drew from REACH authorization databases, GB standards documentation, customs trade records, and beauty industry procurement disclosures. Bottom-up demand modeling triangulated against top-down market sizing.
Historical volume trajectories cross-referenced against expert panel inputs on reformulation timelines and channel shift velocities. Segmentation dimensions included formulation chemistry, applicator technology, end-use intensity, and regional regulatory cluster. CAGRs derived from curve-fitting across disclosed revenue ranges and production capacity announcements. Forecast inputs incorporated REACH authorization backlogs and SAMR registration queue lengths.
Several conditions sit outside the modeled scope, including abrupt petrochemical price spikes, trade restriction escalations, and breakthrough biodegradable polymer substitutions. Forecasts reflect assumptions on regulatory stability and professional channel growth continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
Indonesia Skin Care Products Market
Cosmetics & Skincare
Epigenetic Cosmetic Products Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
Organic Bar Soap Market
Cosmetics & Skincare
France Lip Care Products Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Period Balm Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Makeup Setting Powder Market