
 Hand Cream Market | 2026-2036
Hand Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Cream Market Intelligence
Aftermarket service revenue from subscription-based replenishment programs is reconfiguring how hand cream brands capture lifetime value. Beiersdorf AG leverages its Nivea brand heritage to sustain pharmacy channel dominance across European markets. L'Oréal competes through dedicated dermocosmetic hand care lines that extend its professional skincare expertise into at-home routines.
Hand cream is a viscous emulsion typically formulated with humectants such as glycerin at 3-10% concentration, emollients, and occlusive agents designed to restore epidermal barrier function and transepidermal water loss in the stratum corneum. Moisturizing formulations occupy the largest volume share due to universal daily-use positioning, while anti-aging variants command premium pricing through retinol and peptide inclusion. Tube packaging leads mass-market distribution for portability and hygiene, though jar formats dominate prestige segments where tactile application rituals support brand positioning.
The EU REACH regulation and FDA cosmetic labeling requirements in the United States constrain permissible preservative systems and mandate ingredient transparency, directly elevating R&D costs for reformulation cycles. ECHA's ongoing substance evaluation of endocrine-disrupting candidates threatens several conventional emulsifier chemistries, forcing suppliers toward bio-based alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented compliance architectures that fragment supply chains.
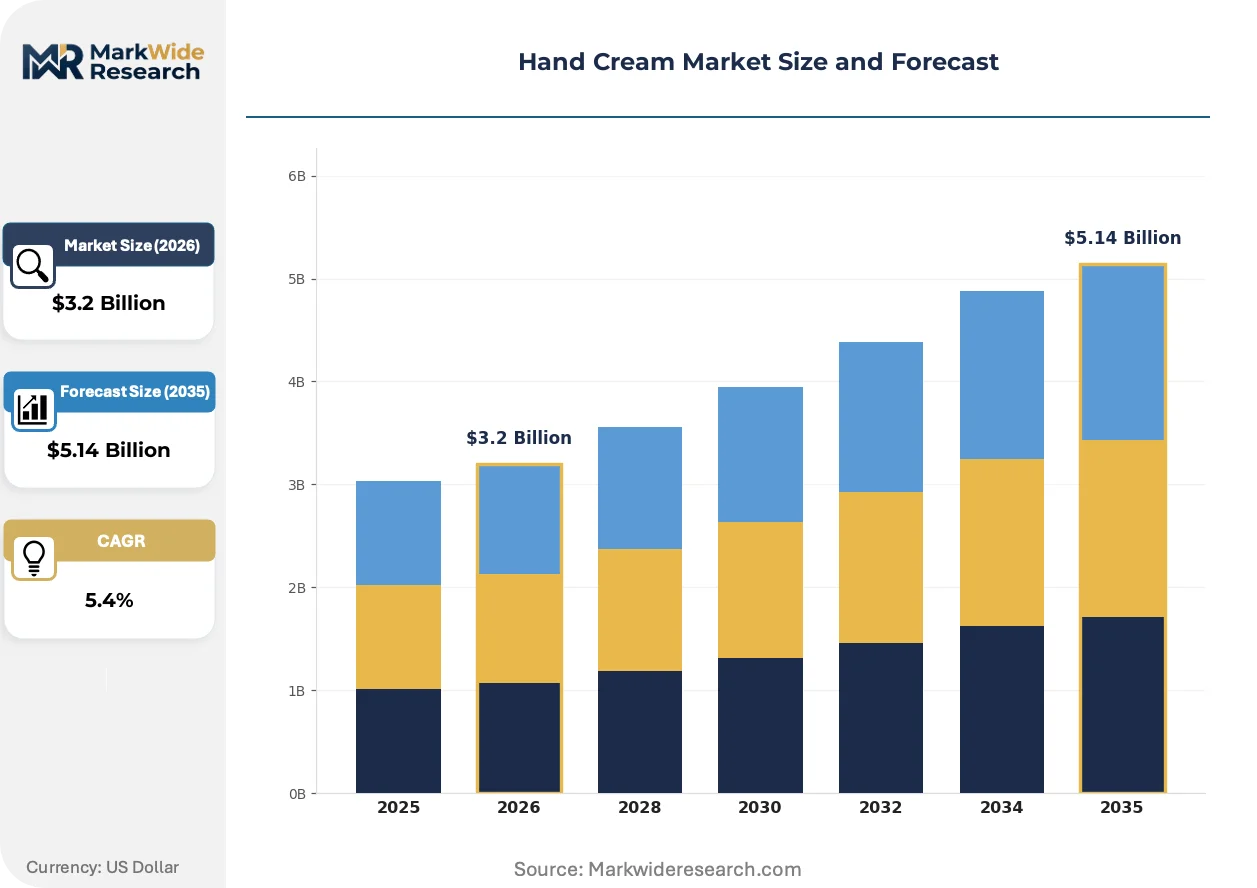
Market Dynamics
EU REACH substance evaluation is virtualizing emulsifier supply chains by forcing rapid substitution of endocrine-disrupting chemistries with bio-based alternatives, fragmenting procurement architectures and elevating R&D burn rates across formulation houses.
Growth Catalysts
- Professional salon channel expansion:Premium hand cream volumes accelerate as spa and nail service providers standardize post-treatment retail protocols, embedding product recommendation into service workflows.
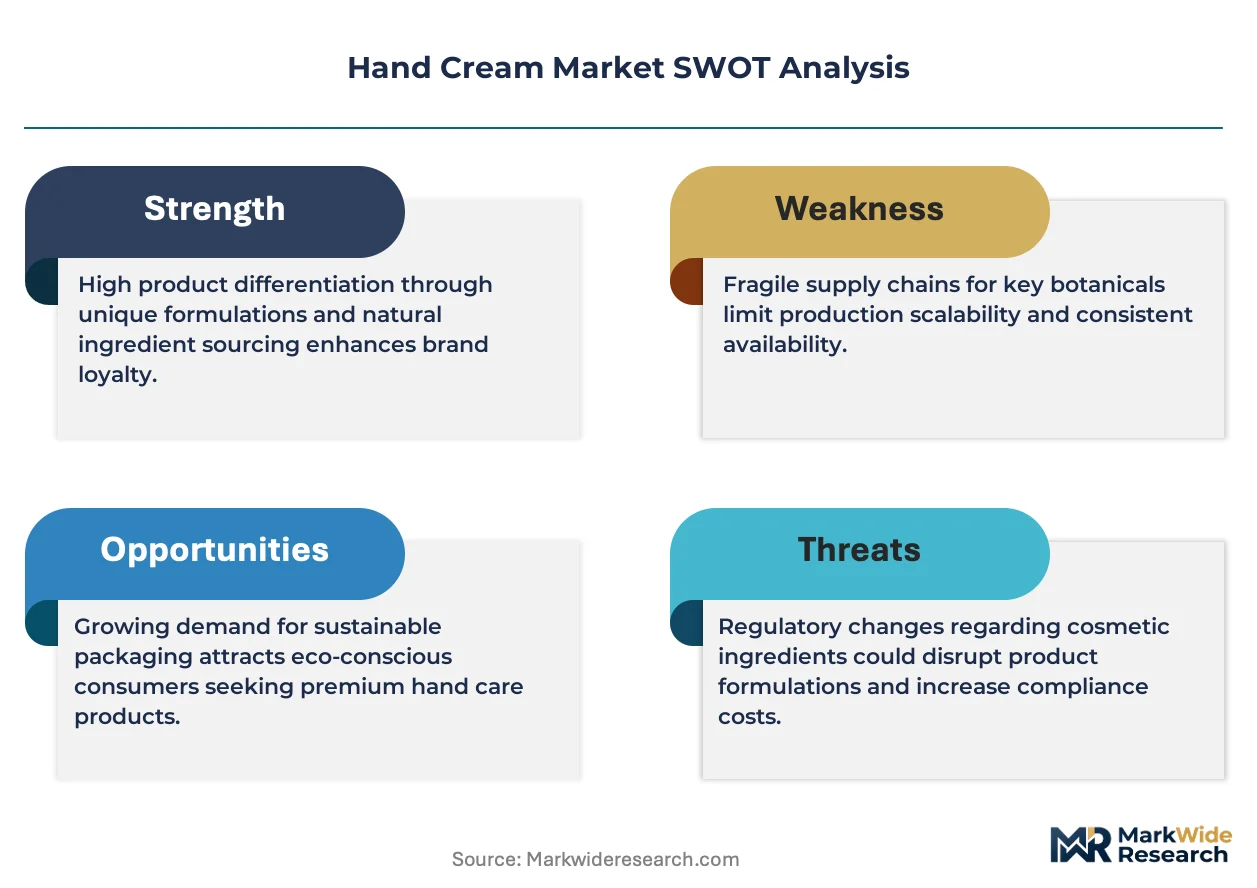
- REACH ingredient disclosure mandates:Transparency requirements under ECHA evaluation protocols create competitive differentiation for brands with clean-label positioning, rewarding early compliance investments.
- Barrier restoration science:Ceramide and niacinamide inclusion at therapeutic concentrations drives pharmacy channel migration, capturing consumers with compromised epidermal conditions.
Market Restraints
- Petrochemical feedstock volatility:Occlusive agents including petrolatum and mineral oil face price instability tied to crude oil benchmarks, compressing margin predictability for mass-market producers.
- Preservative system constraints:FDA cosmetic labeling requirements and EU paraben restrictions eliminate conventional antimicrobial chemistries, forcing costly reformulation cycles and stability retesting.
- Water-free formulation competition:Anhydrous balm substitutes positioned as concentrated alternatives threaten standard emulsion volumes in sustainability-conscious consumer segments.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer auto-delivery programs capture lifetime value through predictable reorder cycles, reducing customer acquisition cost burdens.
- Dermocosmetic hand care extension:Professional skincare expertise migrates into at-home routines through peptide and retinol positioning, commanding price premiums above basic moisturizers.
- India personal care penetration:Rising disposable incomes in urban centers expand addressable market for functional hand care beyond basic cold cream substitutes.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based emulsifier compatibility and natural preservation systems commands premium compensation, constraining R&D team scaling.
- Multi-jurisdiction compliance fragmentation:Divergent preservative approvals between FDA, ECHA, and Health Canada force parallel product architectures, elevating inventory complexity and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Cream Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Anti-aging, Nourishing, Scented Ingredient Type: Organic, Synthetic, Botanical, Mineral Packaging Type: Tube, Jar, Pump, Sachet Distribution Channel: Online, Supermarket, Specialty Store, Pharmacy |
| Companies Covered | Beiersdorf AG, Procter & Gamble, L'Oréal, Estée Lauder Companies, Natura & Co, Unilever, L'Occitane Groupe, Coty Inc., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Cream Market Strategic Shifts & Innovations
Digital skin diagnostics and microbiome science are reconfiguring how hand cream efficacy is demonstrated, shifting competitive advantage from fragrance marketing toward measurable barrier function claims verified through instrumental analysis.
Biotechnology-derived ceramide complexes is virtualizing traditional petrolatum-based occlusion by delivering identical barrier repair through fermentation-sourced lipids. Prestige and pharmacy brands accelerate adoption as consumer skepticism toward fossil-derived ingredients intensifies. This technology is virtualizing supply chain relationships between cosmetic houses and agricultural commodity traders, replacing them with bioreactor capacity contracts.
ECHA's ongoing endocrine disruptor candidate list expansion tightens permissible emulsifier chemistries under REACH Article 57 scrutiny. Industrial consequence forces suppliers toward sucrose ester and lecithin-derived alternatives with inferior stability profiles. Prestige segments absorb reformulation costs fastest, while mass-market players face compressed margins or portfolio rationalization.
Professional recommendation influence now dominates high-value hand cream selection, displacing traditional advertising and retail placement. Dermatologists and aestheticians increasingly function as gatekeepers for therapeutic-positioned products, particularly in Germany and France where pharmacy channel authority remains concentrated. This shift is most visible in European markets with established dermocosmetic distribution infrastructure.
Hand Cream Market Segmentation
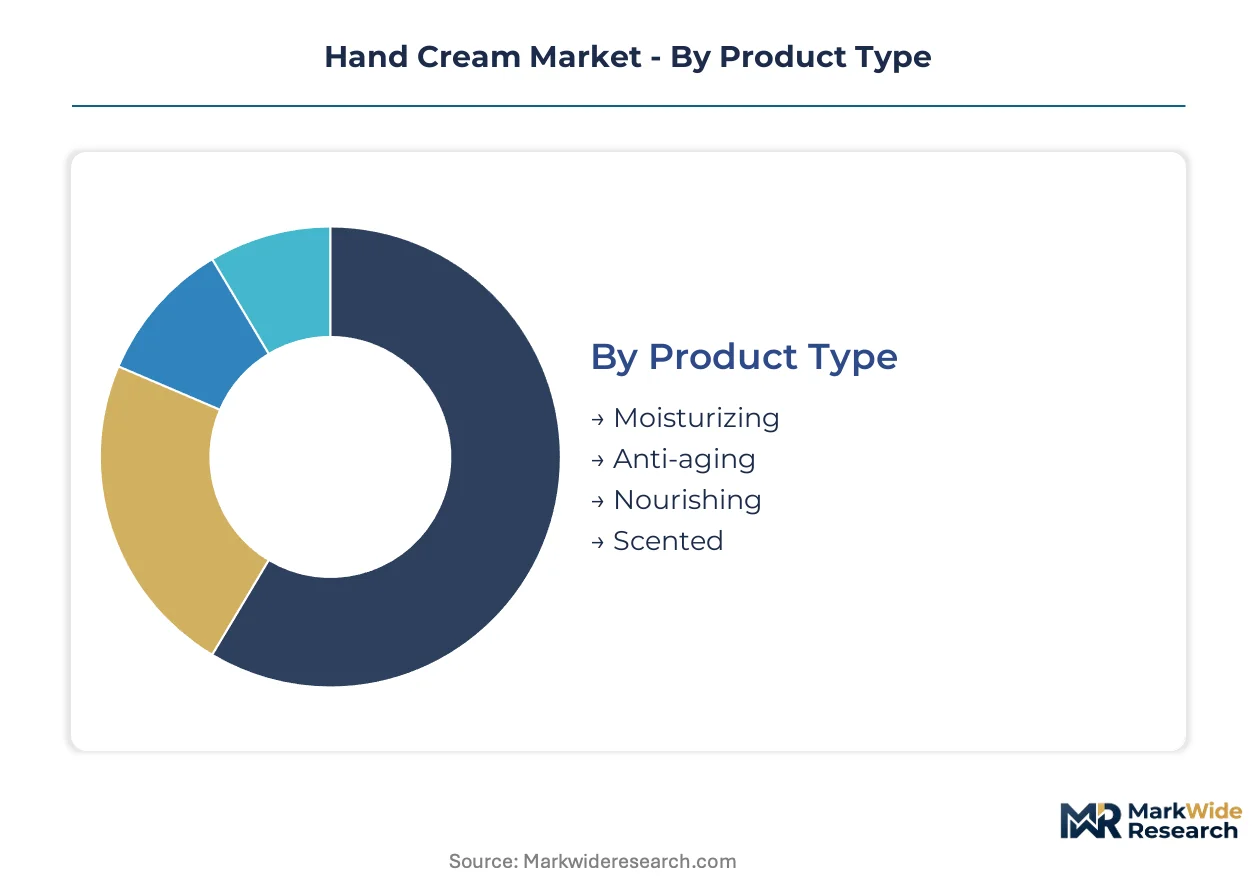
Hand cream purchasing cycles vary dramatically across formulation types, with daily-use moisturizing products turning over inventory fastest while premium anti-aging variants sit longer on shelves but deliver superior margins per unit. Understanding these velocity patterns across product, ingredient, packaging, and channel dimensions enables targeted portfolio management and working capital optimization.
Product Type:
Moisturizing formulations rotate through retail channels fastest due to universal daily-use positioning, while anti-aging SKUs experience extended purchase consideration cycles that compress inventory turns but expand gross margin per transaction.
- Moisturizing:Glycerin-based emulsions at 3-10% humectant concentration dominate pharmacy and supermarket volumes through barrier restoration claims. Germany's dermocosmetic distribution infrastructure concentrates demand for therapeutic-positioned variants among consumers with compromised epidermal conditions.
- Anti-aging:Retinol and peptide inclusion at therapeutic concentrations commands premium pricing through dermatologist recommendation channels. Professional spa and nail service providers in France standardize post-treatment retail protocols that embed these SKUs into service workflows.
- Nourishing:Ceramide-rich formulations target compromised skin barriers with occlusive-heavy compositions.
- Scented:Fragrance-forward variants rely on impulse purchase triggers in travel retail and gift segments.
Moisturizing hand creams anchor the volume base while anti-aging formulations gain share at the steepest rate through professional channel expansion.
Ingredient Type:
Cost tier stratification separates premium-positioned organic and botanical inputs from mass-market synthetic alternatives, with mineral ingredients occupying a narrowing mid-market position squeezed by clean-label migration.
- Organic:Certified cultivation chains and EU REACH-compliant extraction methods elevate R&D burn rates for compliance documentation. ECHA substance evaluation protocols reward early investment in transparent supply chains with competitive differentiation in German pharmacy channels.
- Synthetic:Petrochemical-derived emollients face margin compression from crude oil price volatility and consumer skepticism toward fossil-sourced inputs. FDA cosmetic labeling requirements constrain permissible preservative systems, forcing costly reformulation cycles.
- Botanical:Plant-derived active positioning captures sustainability-conscious segments through fermentation-sourced lipid alternatives.
- Mineral:Petrolatum and mineral oil occlusion faces displacement from biotechnology-derived ceramide complexes.
Synthetic ingredients still dominate unit volumes while organic certification climbs the fastest through subscription replenishment model adoption.
Packaging Type:
Application ritual preferences split convenience-driven portable formats against prestige-positioned tactile experiences, with hygiene concerns post-pandemic accelerating tube and pump adoption over communal jar access.
- Tube:Aluminum-laminate and plastic squeeze formats lead mass-market distribution through portability and single-user hygiene protection. Supermarket and pharmacy channels in urban India favor this format for rising disposable income penetration beyond basic cold cream substitutes.
- Jar:Wide-mouth glass and heavy-wall plastic containers dominate prestige segments where finger-dip application rituals support brand positioning. European dermocosmetic houses leverage this format to signal concentrated formula value.
- Pump:Airless dispenser systems capture institutional and professional salon volumes through controlled dosing.
- Sachet:Single-use foil pouches concentrate in travel retail and emerging market trial-size distribution.
Tube packaging sustains the volume foundation while pump formats expand most quickly through professional channel standardization.
Distribution Channel:
Customer acquisition economics diverge sharply between high-friction physical retail and direct-to-consumer digital platforms, with subscription auto-delivery programs reconfiguring lifetime value capture away from transactional shelf sales.
- Online:Direct-to-consumer platforms and marketplace aggregators enable auto-replenishment programs that reduce customer acquisition costs through predictable reorder cycles. Digital skin diagnostics integration supports measurable barrier function claims that shift competitive advantage from fragrance marketing.
- Supermarket:Mass-market gondola placement depends on price-point accessibility and promotional velocity programs. Petrochemical feedstock volatility compresses margin predictability for producers competing on shelf-turn metrics.
- Specialty Store:Curated beauty retailers concentrate premium and niche positioning through experiential merchandising.
- Pharmacy:Germany's dermocosmetic infrastructure and French para-pharmacy networks concentrate professional recommendation influence.
Supermarket channels anchor current volume distribution while online direct-to-consumer routes gain share at the steepest rate through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across hand cream markets. German pharmacy channels absorb premium dermocosmetic pricing through professional recommendation authority, while Indian mass-market segments remain acutely sensitive to unit cost thresholds.
Germany
Pharmacy channel dominance concentrates demand for therapeutic-positioned hand creams with ceramide and niacinamide formulations. ECHA REACH Article 57 substance evaluation protocols tighten permissible emulsifier chemistries, rewarding early compliance investments. Berlin-Brandenburg and North Rhine-Westphalia host formulation houses accelerating bio-based preservative system adoption.
United States
Direct-to-consumer subscription models capture lifetime value through auto-replenishment programs reducing customer acquisition costs. FDA cosmetic labeling requirements constrain permissible preservative systems, elevating R&D burn rates for reformulation cycles. Greater Boston and Pacific Northwest clusters concentrate digital skin diagnostics integration with barrier function claims.
France
Professional spa and nail service providers standardize post-treatment retail protocols embedding premium hand cream recommendations into service workflows. ANSM oversight of cosmetic safety maintains stringent ingredient disclosure standards. Paris and Provence-Alpes-Côte d'Azur anchor prestige brand positioning through tactile application ritual marketing.
India
Rising disposable incomes in urban centers expand addressable market for functional hand care beyond basic cold cream substitutes. BIS certification requirements for imported cosmetics create compliance barriers for unstandardized suppliers. Maharashtra and Delhi-NCR concentrate modern trade penetration and pharmacy channel expansion.
Japan
Water-free anhydrous balm substitutes challenge standard emulsion volumes in sustainability-conscious consumer segments. METI guidelines on sustainable packaging drive innovation in refillable and reduced-plastic formats. Kanto and Kansai regions host biotechnology firms developing fermentation-sourced ceramide complexes.
Hand Cream Market Key Industry Players
Capability concentration sits with dermocosmetic specialists commanding pharmacy channel authority; scale advantage sits with mass-market conglomerates dominating supermarket and online distribution. The market structures around three tiers: heritage European houses with professional recommendation networks, multinational FMCG players with replenishment platform infrastructure, and emerging clean-label challengers with direct-to-consumer velocity. Dominant competitive moves include subscription auto-delivery program scaling and biotechnology-derived ingredient pipeline acquisition.
Within the heritage dermocosmetic tier, Beiersdorf AG and L'Oréal occupy positions leveraging professional skincare expertise extension into at-home hand care routines. Among mass-market scale players, Unilever and Procter & Gamble exemplify replenishment platform economics through predictable reorder cycle capture. L'Occitane Groupe represents the prestige tactile-ritual positioning archetype with concentrated jar-format market presence.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Procter & Gamble |
| L'Oréal |
| Estée Lauder Companies |
| Natura & Co |
| Unilever |
| L'Occitane Groupe |
| Coty Inc. |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Berlin-Brandenburg formulation houses anchor European supply capacity for bio-based emulsifier systems, and their R&D investment cycles directly transmit into downstream pricing power for pharmacy-channel dermocosmetic brands. REACH Article 57 compliance costs concentrate in this cluster, elevating barrier-to-entry economics that sustain premium pricing tiers.
Pricing Analysis
Subscription replenishment revenue streams anchor lifetime value capture for direct-to-consumer hand cream brands. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient certification tier and professional recommendation authority. Cost compression in mass-market synthetic segments intensifies due to petrochemical feedstock volatility. Price-sensitive consumers cluster in Indian urban centers seeking functional alternatives to basic cold cream substitutes, while German pharmacy channels show lowest elasticity.
Supply Chain Analysis
Supplier-financing instruments including extended payment terms and supply-chain finance facilities are restructuring procurement relationships between formulation houses and agricultural commodity traders. Germany, France, and Japan concentrate biotechnology-derived ceramide production capacity. Raw material dependencies center on fermentation-sourced lipids, sucrose ester emulsifiers, and lecithin-derived alternatives. Single-source vulnerability runs through bioreactor capacity contracts for novel bio-based inputs. Distribution runs through pharmacy networks in Europe and professional salon channels in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-free anhydrous balm substitutes represent the substitution threat requiring active defense, as sustainability-conscious segments in Japan and Europe migrate toward concentrated non-emulsion formats.
For Market Incumbents: Harden pharmacy channel control through accelerated bio-based preservative system certification under ECHA evaluation protocols. Deepen backward integration into fermentation-sourced lipid supply through captive bioreactor capacity contracts. This defensive posture neutralizes clean-label challenger velocity while securing margin protection against REACH-driven reformulation cost spirals. For New Entrants and Emerging Players: Establish a beachhead in India's functional hand care segment beyond basic cold cream substitutes, targeting rising disposable income clusters in Maharashtra and Delhi-NCR. Leverage BIS certification gaps to capture modern trade shelf space before standardized compliance barriers harden. Direct-to-consumer digital platforms with auto-replenishment mechanics offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dermocosmetic specialists with pharmacy channel authority and biotechnology-derived ingredient pipelines. Long-term viability rests on professional recommendation network depth rather than mass-market scale. Acquisition targets should demonstrate ECHA REACH early-compliance investment and dermatologist endorsement density. The signal to watch is bio-based emulsifier stability profile advancement in prestige brand adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Auto-Replenishment Scaling | Captures predictable lifetime value through direct-to-consumer reorder cycles reducing acquisition costs. |
| Bio-Based Preservative System Certification | ECHA REACH Article 57 compliance creates competitive differentiation in German pharmacy channels. |
| Biotechnology-Derived Ceramide Pipeline Acquisition | Fermentation-sourced lipids displace petrolatum occlusion in prestige and therapeutic segments. |
| Professional Salon Channel Standardization | Post-treatment retail protocol embedding captures premium hand cream volumes in French spa networks. |
| Digital Skin Diagnostics Integration | Instrumental barrier function verification shifts competitive advantage from fragrance toward measurable efficacy claims. |
Research Approach
Initial hypotheses were tested against primary input from formulation chemists, pharmacy category managers, professional aestheticians, and dermocosmetic brand directors and refined through secondary validation. FDA cosmetic labeling filings, ECHA REACH substance evaluation protocols, EU customs trade data, and Nielsen retail audit records anchored quantitative triangulation. Bottom-up SKU velocity analysis and top-down channel revenue estimation were cross-referenced for coherence.
Demand-supply-balance framing structured the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation type, ingredient certification tier, packaging format, and distribution channel cluster. CAGRs were derived from trend-line extrapolation of historical velocity patterns adjusted for regulatory inflection points. Forecast inputs incorporated ECHA endocrine disruptor candidate list expansion timelines and biotechnology capacity buildout curves.
Sensitivities concentrate around REACH Article 57 substance evaluation scope expansion, bioreactor capacity commissioning delays, and professional recommendation channel consolidation rates. Forecasts embed assumptions regarding regulatory trajectory stability and clean-label consumer preference persistence. Macroeconomic contraction, accelerated ECHA restriction timelines, or breakthrough anhydrous formulation efficacy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Private Label Cosmetics Manufacturing Service Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market