
 Group Travel Market | 2026-2036
Group Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Group Travel Market Analysis
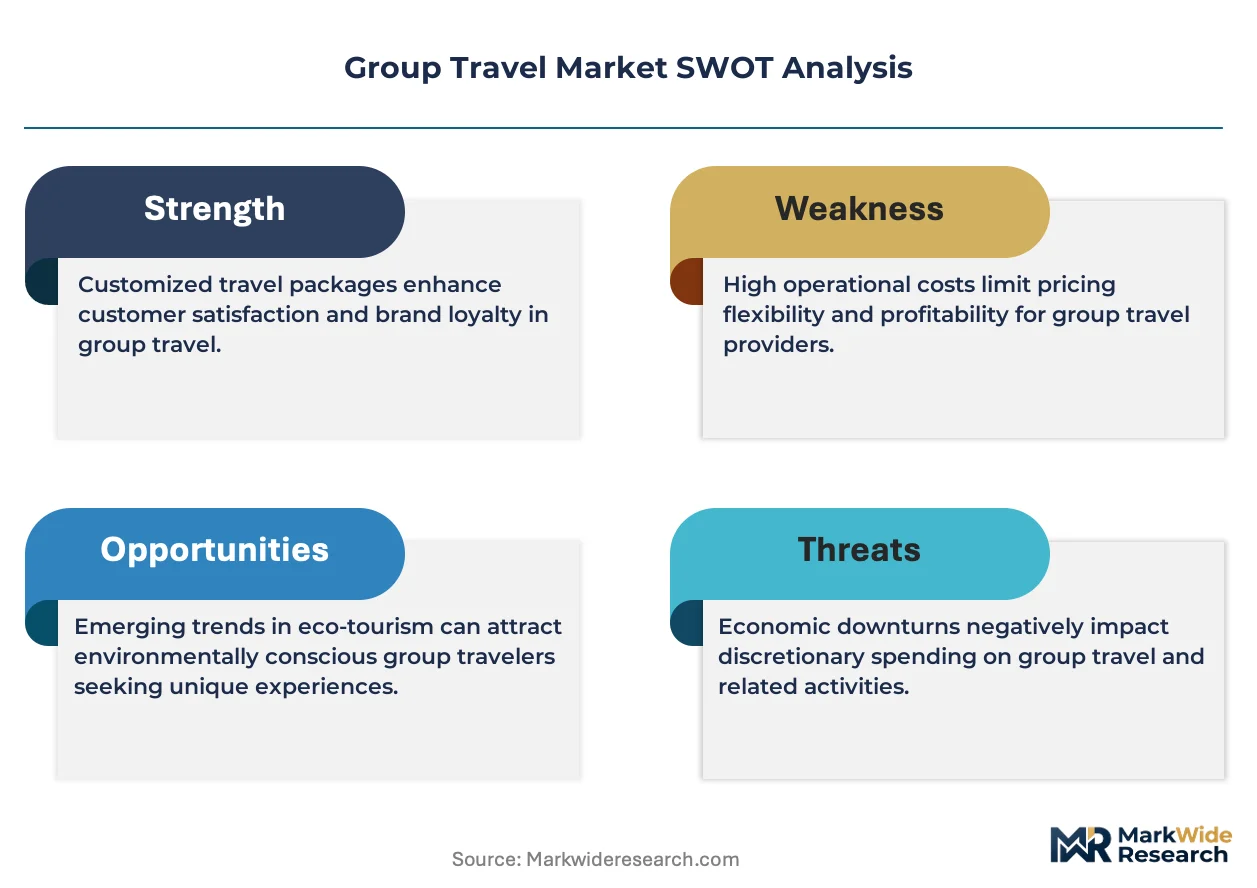
Premium experiential tiers are rotating toward the center of group travel value creation. TUI AG leverages its integrated hotel-airline network to control end-to-end margin capture across European charter routes. G Adventures differentiates through community-based tourism partnerships that anchor its position in the adventure segment. Booking Holdings extends its platform architecture to aggregate fragmented group inventory at scale.
Group travel denotes coordinated movement of ten or more individuals under unified booking, itinerary, and payment structures, typically requiring block inventory commitments, dedicated ground logistics, and negotiated group rates with hospitality suppliers. Its commercial purpose centers on cost arbitrage through volume purchasing and operational simplification for organizers managing complex multi-party arrangements. Adventure tours command the highest per-passenger margins due to specialized guide ratios and equipment logistics, while corporate retreats represent the fastest-expanding customer type as enterprises formalize offsite budgets. Educational institutions sustain predictable annual demand cycles tied to academic calendars, creating counter-seasonal booking patterns that operators navigate through capacity allocation.
The EU Green Deal and CSRD reporting mandates shape operator disclosure obligations across European itineraries, while the FAA's Part 135 charter regulations govern air brokerage compliance for US-based group aviation packages. ISO 14001 environmental management certifications increasingly function as market access prerequisites for institutional RFP participation. Stakeholders must monitor how carbon accounting standardization alters supplier qualification criteria and route viability assessments.
Market Dynamics
The EU Green Deal's carbon disclosure mandates are forcing tour operators to restructure supplier qualification protocols and route economics around verified emissions accounting.
Growth Catalysts
- CSRD Reporting Mandates:Corporate sustainability disclosure rules in Europe require institutional buyers to document supply chain emissions, creating procurement preference for certified group operators.
- Corporate Retreat Formalization:Enterprise human resource departments now maintain dedicated offsite budgets with defined per-employee spending thresholds, generating predictable demand cycles.
- Adventure Tourism Infrastructure:Specialized equipment logistics and guide certification programs in alpine and marine destinations unlock premium per-passenger yield structures.
Market Restraints
- Jet Fuel Price Volatility:Aviation kerosene cost swings compress margin on air-inclusive group packages, particularly for charter-dependent European routes.
- Ground Handler Concentration:Destination management company networks in Mediterranean markets exhibit supplier consolidation, limiting negotiation leverage for mid-size operators.
- ISO 14001 Certification Burden:Environmental management system audits impose fixed compliance costs that disproportionately burden operators below ten-thousand annual passenger volume.
Strategic Opportunities
- Community-Based Tourism Partnerships:Direct contracts with indigenous cooperatives in Costa Rica and Peru enable margin capture previously lost to intermediary layers.
- Educational Institution Counter-Seasonal Booking:Academic calendar-driven demand creates fill-rate opportunities during traditional leisure low seasons.
- Digital Payment Integration:Unified group payment platforms that consolidate individual contributions into single master accounts reduce booking abandonment.
Industry Challenges
- Specialized Guide Talent Scarcity:Certified adventure tourism leaders with dual language and technical safety credentials face supply shortages across alpine and marine segments.
- Legacy Reservation System Integration:Property management system interfaces between group booking engines and individual hotel inventory platforms require expensive middleware development.
- Carbon Accounting Standard Fragmentation:Competing emissions calculation methodologies create audit complexity when institutional buyers mandate specific frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Group Travel Market |
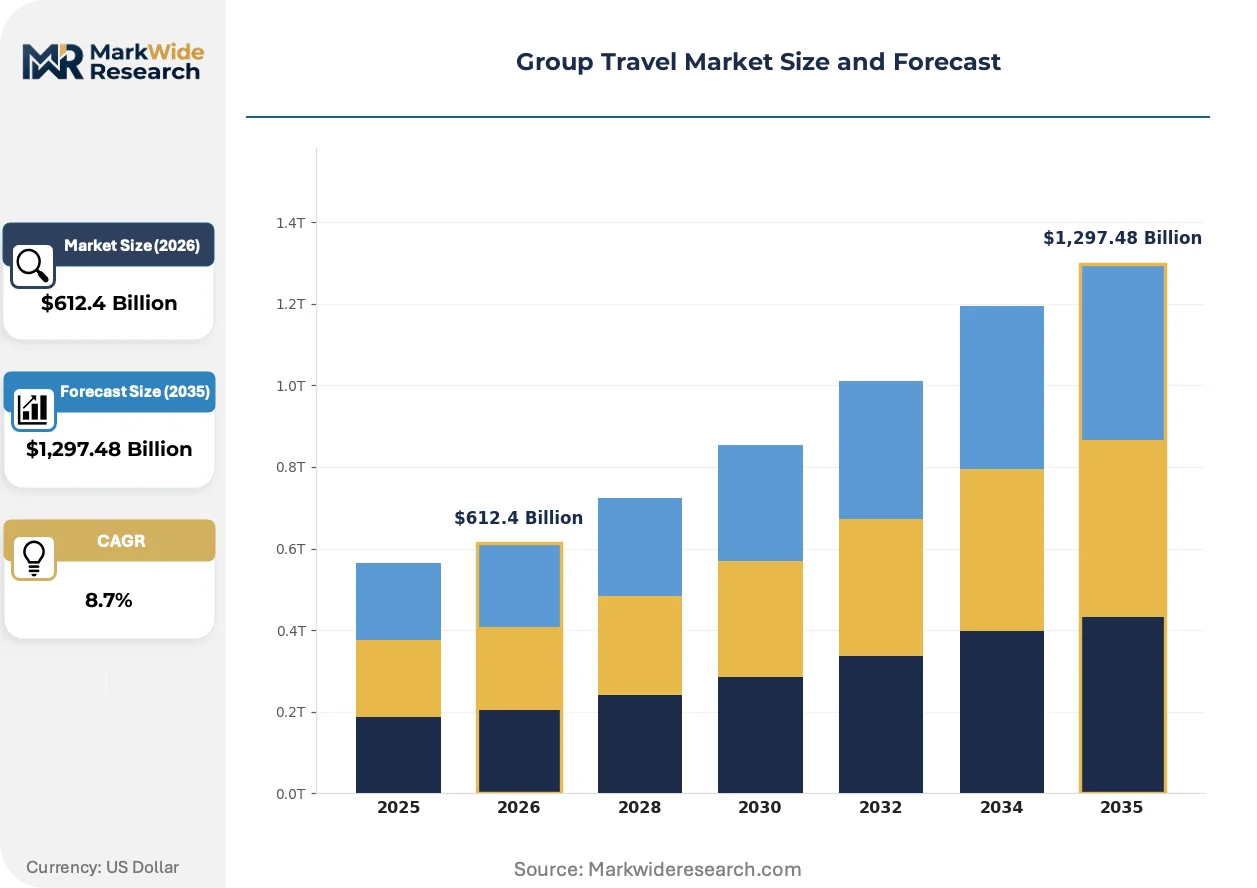
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Adventure Tours, Corporate Retreats, Educational Trips, Family Gatherings Customer Type: Corporate Clients, Social Groups, Educational Institutions, Nonprofits Distribution Channel: Online Travel Agencies, Direct Booking, Travel Management Companies, Traditional Travel Agents End User: Leisure Travelers, Business Travelers, Students, Community Organizations |
| Companies Covered | Booking Holdings, Expedia Group, TUI AG, G Adventures, Contiki, Flight Centre Travel Group, Butterfield & Robinson, Geographic Expeditions, ROW Adventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Group Travel Market Emerging Trajectories
Digital infrastructure is compressing coordination costs for multi-party bookings while regulatory pressure restructures supplier certification hierarchies across European itineraries.
Dynamic group pricing algorithms is supplanting static block-rate contracts as the dominant revenue management approach. Mid-size operators deploy machine learning models that adjust per-passenger rates based on real-time inventory fill rates and competitor positioning. This capability is compressing the yield advantage previously held by integrated carriers with captive distribution.
CSRD disclosure requirements in Europe now extend to scope-three emissions reporting for corporate travel procurement. Tour operators must provide verified carbon intensity data per passenger-kilometer to maintain institutional contract eligibility. German and French enterprise buyers have moved fastest in mandating ISO-compliant documentation as a contract precondition.
Unified payment orchestration platforms now consolidate fragmented individual contributions into master accounts with automated reconciliation. Corporate retreat planners and educational trip organizers have abandoned manual collection processes in favor of these tools. North American institutional buyers exhibit the highest adoption velocity, driven by procurement department demands for spend visibility and audit trails.
Group Travel Market Segmentation
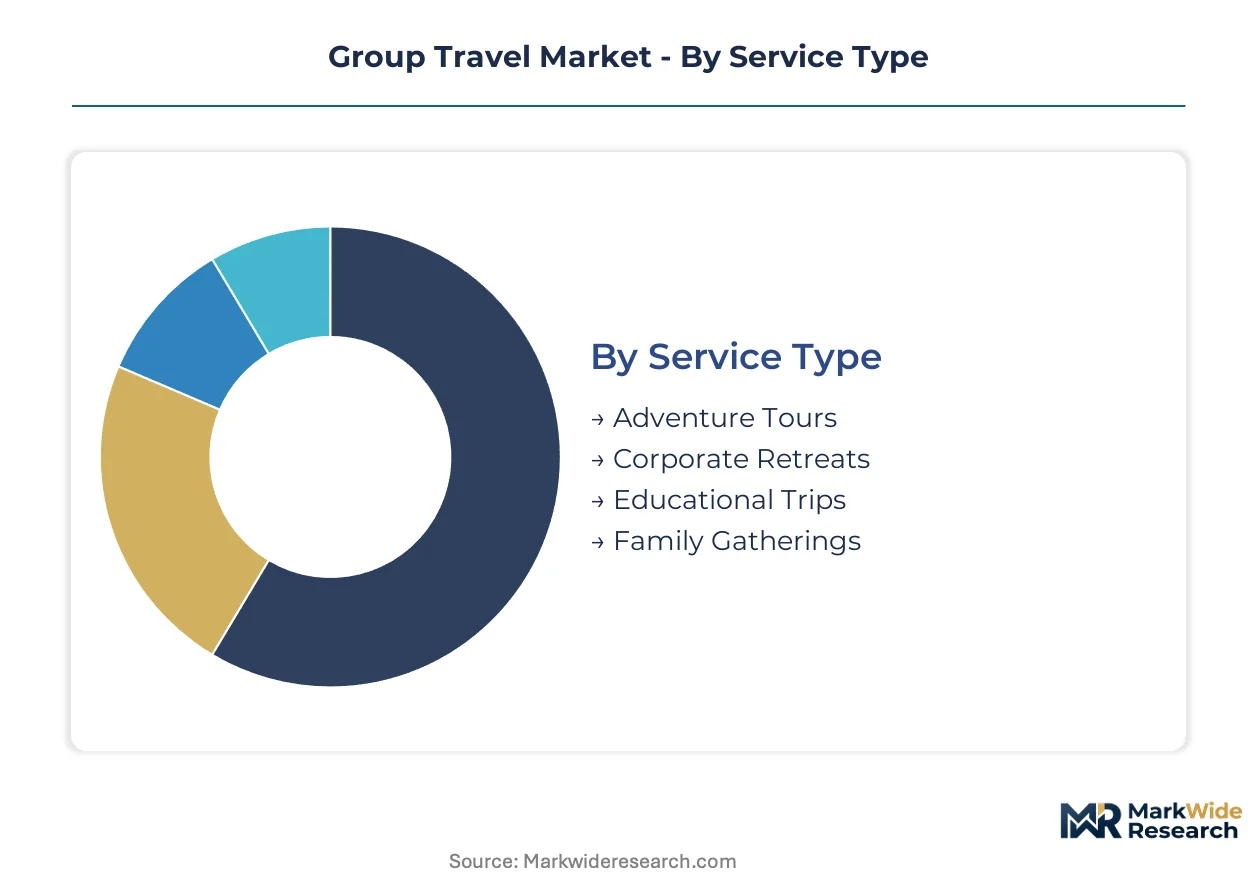
Group travel operators structure product portfolios around distinct service configurations, customer procurement patterns, and channel economics. Each segmentation dimension reveals divergent margin profiles and operational complexity thresholds that determine competitive positioning.
Service Type:
Domestic demand concentrates in corporate retreats and family gatherings, while adventure tours and educational trips draw heavily from international source markets with extended booking horizons.
- Adventure Tours:Specialized itineraries requiring certified guides, technical equipment logistics, and small-group ratios. Demand clusters in alpine and marine destinations where German and Austrian operators capture premium yield through exclusive access permits.
- Corporate Retreats:Structured offsite programming with unified billing, dedicated ground transport, and venue exclusivity requirements. Procurement through human resource departments in France and the Netherlands generates predictable annual contracting cycles.
- Educational Trips:Curriculum-aligned itineraries with risk management protocols and academic credit integration.
- Family Gatherings:Multi-generational reunions with flexible cancellation terms and accessibility accommodations.
Corporate retreats hold the largest share; momentum sits with adventure tours.
Customer Type:
Volume distribution splits between institutional procurement with formalized budgets and informal social coordination with fragmented decision-making.
- Corporate Clients:Enterprise buyers with defined per-employee spending thresholds and sustainability disclosure obligations under CSRD mandates. Contracting concentrates in Germany and Belgium where procurement departments mandate ISO 14001-certified operators.
- Educational Institutions:Schools and universities with academic calendar constraints and duty-of-care liability frameworks. Italian and Spanish institutions drive Mediterranean destination demand during shoulder seasons.
- Social Groups:Informal associations with rotating leadership and pooled payment collection.
- Nonprofits:Mission-driven organizations with grant-funded travel and volunteer service components.
Corporate clients dominate contract value; educational institutions are climbing the fastest.
Distribution Channel:
Channel mix reflects customer digital maturity and complexity tolerance, with institutional buyers favoring intermediaries that consolidate compliance documentation.
- Travel Management Companies:B2B intermediaries providing consolidated billing, policy enforcement, and emissions reporting for enterprise accounts. Adoption accelerates in France where CSRD disclosure requirements favor outsourced procurement.
- Online Travel Agencies:Platform-based aggregation with dynamic pricing and self-service configuration tools.
- Direct Booking:Operator-controlled channels capturing full margin but requiring internal sales capacity.
- Traditional Travel Agents:Commission-based intermediaries serving legacy customer segments with high service expectations.
Travel management companies command institutional volume; online travel agencies gain share fastest.
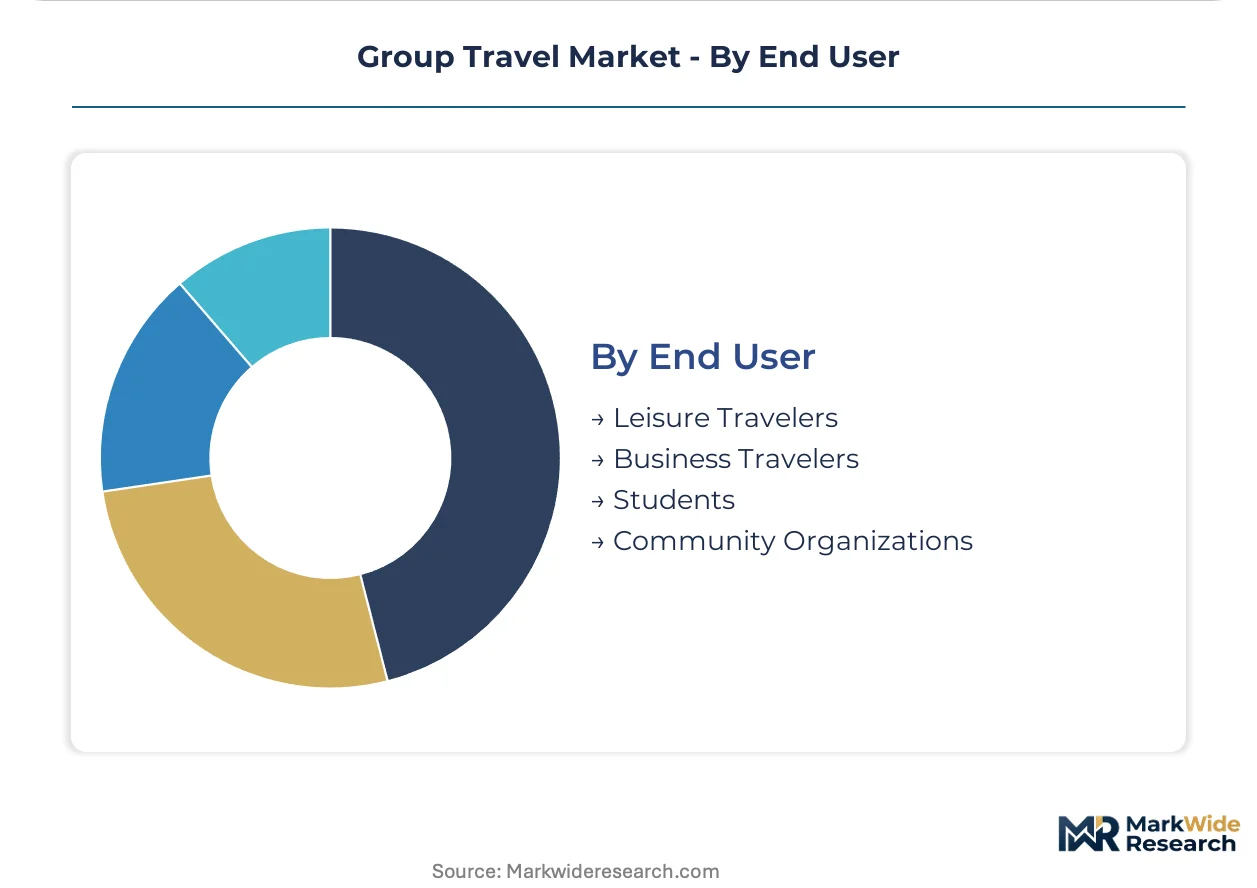
End User:
User categories map to distinct trip purpose hierarchies, with business travelers prioritizing efficiency and leisure travelers emphasizing experiential depth.
- Business Travelers:Time-constrained participants requiring seamless logistics and productivity infrastructure. German enterprise segments sustain highest per-trip expenditure through premium ground transport and executive accommodation tiers.
- Leisure Travelers:Experience-seeking groups with flexible dates and destination substitution willingness.
- Students:Price-sensitive cohorts with chaperone requirements and educational outcome accountability.
- Community Organizations:Membership-based groups with democratic decision processes and shared cost structures.
Business travelers generate highest yield per departure; students represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial group travel services surplus, exporting packaged itineraries across European charter routes while importing specialized adventure infrastructure from alpine destinations. Trade flows concentrate in corporate retreat procurement and educational mobility programs.
United States
Corporate retreat demand from technology and financial services sectors drives institutional booking volume. FAA Part 135 regulations govern air brokerage compliance for charter aviation packages. Greater Boston and San Francisco Bay Area clusters anchor premium corporate offsite procurement with defined per-employee spending thresholds.
Germany
Enterprise buyers in manufacturing and automotive sectors sustain predictable annual contracting cycles for team cohesion investments. EU Green Deal carbon disclosure mandates reshape supplier qualification protocols for tour operators. Berlin and Munich metropolitan areas concentrate procurement departments mandating ISO 14001-certified operators.
United Kingdom
Educational institution demand from universities and independent schools creates counter-seasonal booking patterns during shoulder seasons. CSRD reporting requirements extend to scope-three emissions for corporate travel procurement. London and Southeast England clusters dominate travel management company intermediation for institutional accounts.
France
Human resource departments in luxury goods and pharmaceuticals formalize offsite budgets with sustainability disclosure obligations. ANSM and CNIL frameworks intersect with EU-wide procurement transparency rules. Paris and Île-de-France anchor enterprise contracting concentration with fastest adoption of outsourced procurement through travel management companies.
Canada
Adventure tourism demand concentrates in alpine and marine destinations requiring specialized guide certification. Health Canada and PMRA regulations govern risk management protocols for educational trips. British Columbia and Alberta clusters capture premium yield through exclusive access permits for wilderness itineraries.
Group Travel Market Vendor Landscape
Concentration sits with integrated tour operators controlling captive airline and hotel inventory. The vendor base distributes across three tiers: multinational conglomerates with end-to-end network control, mid-size specialists with regional destination expertise, and niche adventure operators with community-based partnerships. Strategic moves center on sustainability certification acquisition and dynamic pricing algorithm deployment.
Among integrated European operators, TUI AG exemplifies network-scale archetype with German corporate origins. Booking Holdings occupies platform-aggregation position with technology-driven inventory consolidation. G Adventures represents community-based tourism specialization with adventure segment focus. These three anchors illustrate divergent margin capture strategies across charter routes, digital distribution, and experiential differentiation.
| Leading Market Players |
|---|
| Booking Holdings |
| Expedia Group |
| TUI AG |
| G Adventures |
| Contiki |
| Flight Centre Travel Group |
| Butterfield & Robinson |
| Geographic Expeditions |
| ROW Adventures |
| Others |
Supply Flow & Price Mechanics
Unified payment platform adoption replacing fragmented manual collection systems simultaneously reshapes distribution geography toward North American institutional buyers and compresses coordination cost premiums previously captured by traditional intermediaries. CSRD disclosure requirements in Europe feed back into supplier certification investments, elevating compliance costs that operators pass through to corporate procurement departments or absorb through margin compression.
Pricing Analysis
Corporate retreat planners anchor three-tier pricing structure across premium, standard, and economy levels, with ISO 14001 certification and dedicated ground transport bundling as primary differentiation drivers. Pricing pressure stems from jet fuel volatility on air-inclusive packages, particularly for charter-dependent European routes. Educational institutions exhibit highest price sensitivity due to grant-funded budgets, while German enterprise buyers with formalized offsite thresholds demonstrate lowest sensitivity to per-passenger rate adjustments.
Supply Chain Analysis
Strategic block inventory commitments predominate over just-in-time ground logistics, with operators securing hotel capacity months ahead of departure windows. Supply geography concentrates in Germany, Spain, and Costa Rica for destination management and community-based partnership contracting. Ground handler networks in Mediterranean markets create single-source vulnerability for mid-size operators. Distribution runs through travel management companies for institutional accounts and direct booking channels for social groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern margin capture as dynamic pricing algorithms and unified payment orchestration create interoperability standards that reshape competitive boundaries between integrated carriers and specialist operators.
For Market Incumbents: Fortify end-to-end network control through captive airline-hotel inventory integration, particularly along high-frequency European charter routes. Invest in ISO 14001 certification acquisition to defend institutional RFP eligibility against CSRD-mandated procurement shifts. Prioritize dynamic pricing algorithm deployment to compress yield advantages held by integrated competitors with superior data infrastructure.
For New Entrants and Emerging Players: Differentiate on community-based tourism partnerships with indigenous cooperatives in Costa Rica and Peru, capturing margin layers previously extracted by intermediary destination management companies. Target educational institution counter-seasonal booking patterns during traditional leisure low seasons. Deploy digital-native payment orchestration platforms as primary go-to-market wedge against legacy operators with manual collection processes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-size specialists possessing regional destination expertise but lacking sustainability certification infrastructure. Long-term viability hinges on operators' ability to convert certification compliance from cost burden into institutional contract pricing power. Monitor carbon accounting standardization progress as inflection indicator for supplier qualification barrier height.
| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Pricing Algorithm Deployment | Machine learning rate adjustment compresses integrated carrier yield advantages across European charter routes. |
| ISO 14001 Certification Acquisition | Environmental management certification unlocks institutional RFP participation under CSRD procurement mandates. |
| Community-Based Partnership Expansion | Direct indigenous cooperative contracts in Costa Rica and Peru eliminate intermediary margin extraction layers. |
| Unified Payment Platform Integration | Automated contribution consolidation reduces booking abandonment among corporate retreat planners and educational organizers. |
| Counter-Seasonal Capacity Allocation | Academic calendar-driven demand capture fills rate gaps during traditional leisure low seasons. |
Methodological Framework
The analysis maps adventure tour operators, corporate retreat specialists, educational trip providers, and family gathering coordinators, each validated through tour operator revenue managers, corporate procurement officers, educational institution trip coordinators, and destination management company executives. Primary interview insights combined with secondary validation from EU Green Deal regulatory filings, CSRD implementation guidance, FAA Part 135 compliance databases, and ISO certification registries. Bottom-up passenger volume estimates triangulated against top-down market value reconstruction.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type configuration, customer procurement pattern, distribution channel economics, and end-user purpose hierarchy. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated jet fuel price scenario modeling and carbon accounting standardization timelines.
The analysis sits within stated boundaries; outcomes outside sustained CSRD enforcement intensity or stable aviation fuel cost regimes would require recalibration. Forecasts reflect documented assumptions regarding institutional buyer formalization rates and sustainability disclosure adoption velocity. Revision becomes warranted when carbon intensity verification requirement thresholds cross procurement mandate activation levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Europe Driving Vacation Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Educational Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
China Online Travel Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
India Sustainable Tourism Market
Travel and Tourism
France Culinary Tourism Market