
 China Online Travel Market | 2026-2036
China Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
China Online Travel Market Insights
China's dual carbon goals is realigning how online travel platforms source and market transportation inventory, pressuring operators to surface lower-emission routing options to environmentally conscious bookers. Trip.com Group Ltd leverages its integrated supply chain across flights, hotels, and rail to sustain margin capture from bundled itinerary sales. Meituan-Dianping anchors its travel vertical within a super-app architecture that cross-sells dining and local experience bookings. Tongcheng-Elong Holdings Ltd competes through sharpened penetration in lower-tier city hotel networks where direct digital access remains fragmented.
China online travel denotes the digital intermediation of transportation, accommodation, and experience reservations through web-based platforms and mobile applications, relying on real-time inventory APIs, dynamic pricing algorithms, and encrypted mobile payment gateways to complete transactions. The primary commercial purpose is to disintermediate traditional brick-and-mortar travel agencies while aggregating fragmented supplier inventory into searchable, comparable, and instantly bookable consumer interfaces. Flight booking and hotel reservation together constitute the mature revenue core where supplier commission structures are well-negotiated and inventory depth determines platform utility. Vacation packages represent the fastest-growing structural segment as domestic travelers seek bundled convenience and platforms extract higher take rates from packaged margin stacking. Mobile payments dominate the payment method dimension, with Alipay and WeChat Pay integration functioning as a technical moat that foreign competitors struggle to replicate.
SAMR enforces platform antitrust and consumer protection rules that constrain predatory pricing and mandate transparent fee disclosure, directly shaping how online travel agencies structure service charges and loyalty programs. NMPA oversight of cross-border health protocols and MEE carbon reporting requirements for corporate travel procurement are tightening product standards for business-oriented booking tools. Stakeholders must monitor how evolving data localization rules under MIIT affect cloud infrastructure costs and cross-border passenger data flows.
Market Dynamics
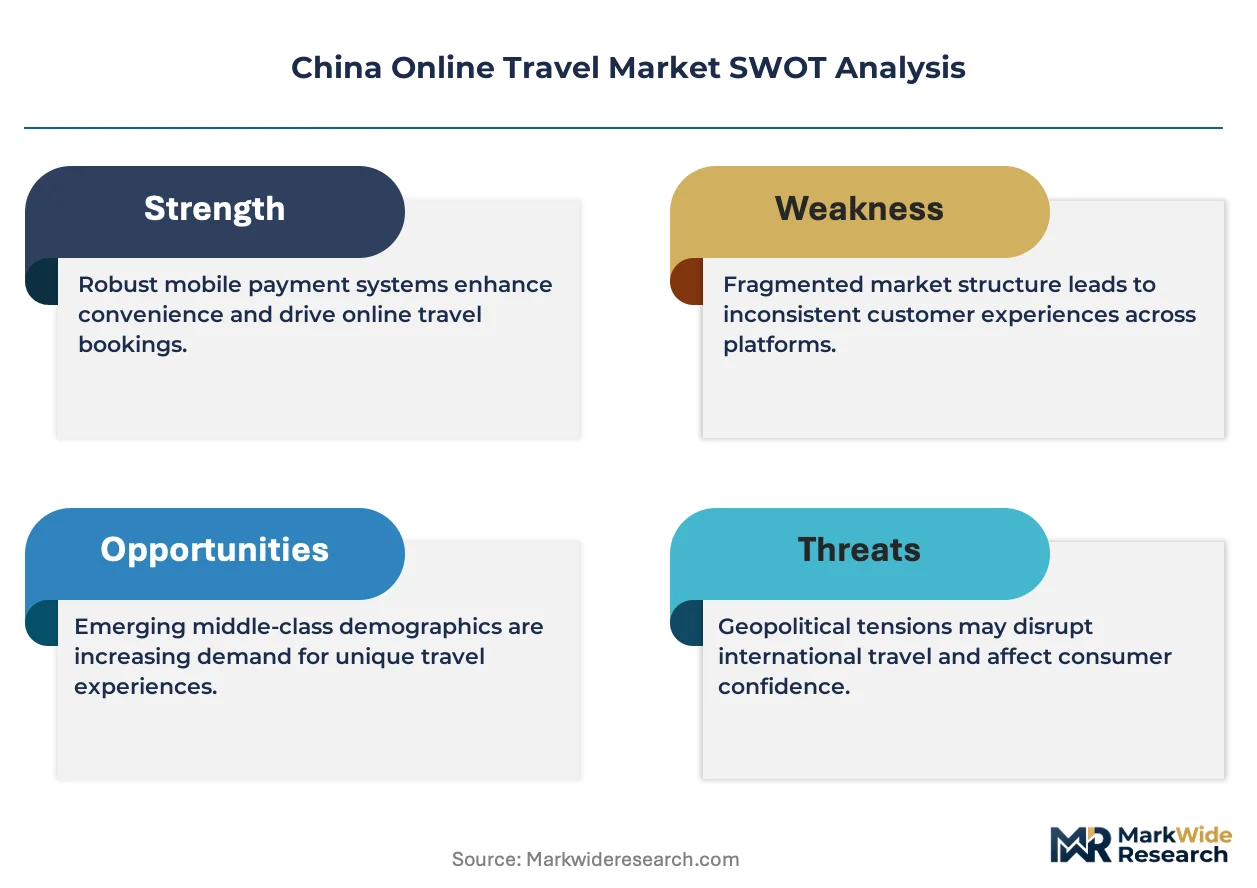
MIIT's digital platform standardization mandate is compressing operational margins for online travel aggregators while forcing rapid infrastructure upgrades to meet tightened data governance requirements.
Growth Catalysts
- Dual Carbon Goals:MEE carbon reporting requirements for corporate travel procurement are creating premium positioning opportunities for platforms that surface lower-emission routing options.
- Mobile Payment Infrastructure:Alipay and WeChat Pay penetration in tier-one cities enables frictionless booking completion that traditional travel agencies cannot replicate.
- Domestic Leisure Expansion:Middle-class families in Shanghai, Beijing, and Shenzhen are consolidating travel spend through integrated super-app ecosystems.
Market Restraints
- SAMR Antitrust Enforcement:Platform pricing transparency mandates constrain loyalty program structures and bundled discounting flexibility.
- Data Localization Costs:MIIT cloud infrastructure rules increase server expenditure for cross-border passenger data management.
- Supplier Commission Compression:Flight inventory APIs face margin pressure from direct airline app penetration in saturated tier-one corridors.
Strategic Opportunities
- Lower-Tier City Hotel Networks:Tongcheng-Elong Holdings demonstrates that fragmented digital access in tier-three and tier-four cities rewards specialized penetration.
- Rail-Flight Bundling:Integrated high-speed rail inventory with domestic aviation creates itinerary stickiness unavailable to single-vertical competitors.
- NMPA Cross-Border Protocol Alignment:Health documentation standardization for inbound tourism prepares platforms for post-normalization international recovery.
Industry Challenges
- Dynamic Pricing Algorithm Talent:Scarcity of engineers capable of real-time inventory optimization across multimodal transport limits platform differentiation.
- Legacy PMS Integration:Hotel property management system fragmentation in lower-tier cities delays API standardization and real-time availability accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Online Travel Market |
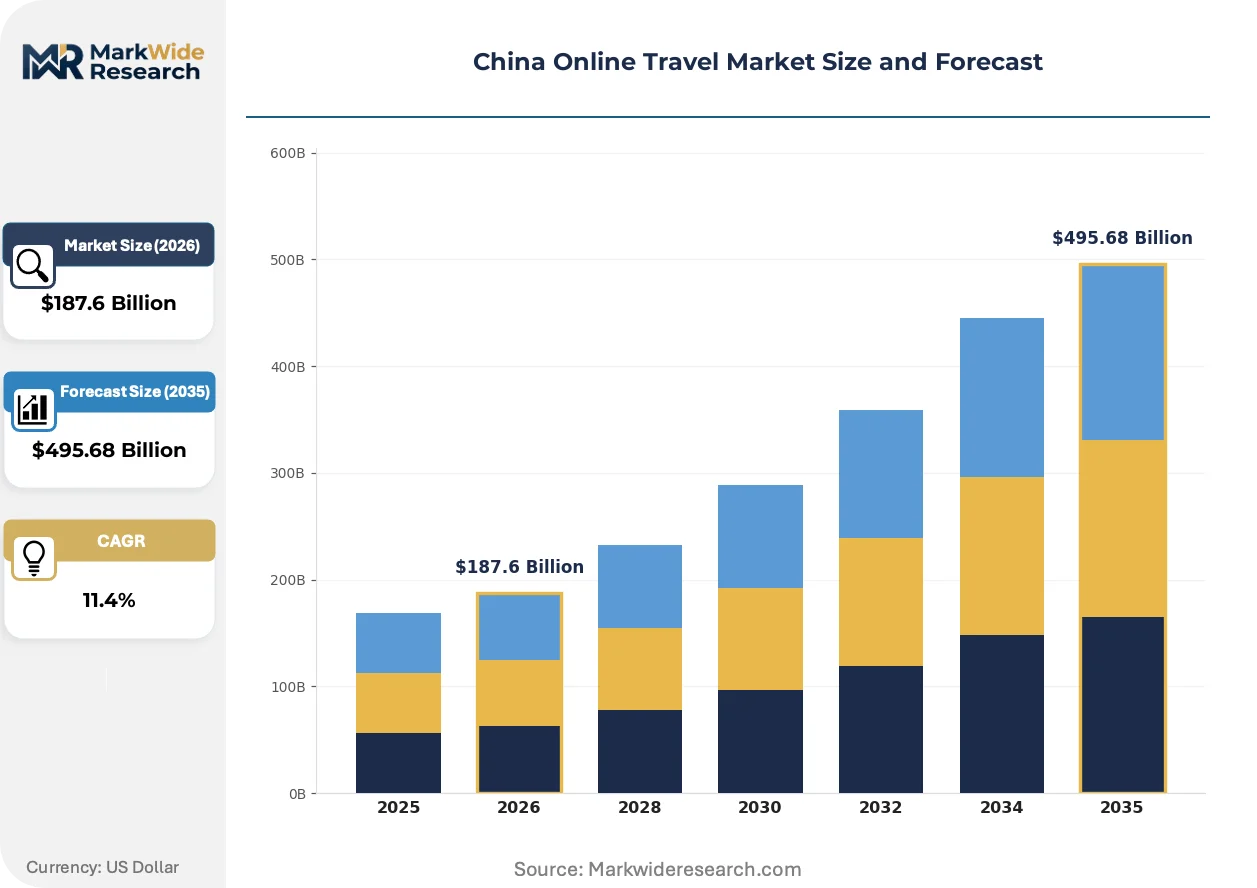
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Booking, Hotel Reservation, Vacation Packages, Car Rentals Customer Type: Business Travelers, Tourists, Families, Solo Travelers Payment Method: Credit Cards, Mobile Payments, Bank Transfers, E-Wallets Distribution Channel: Online Travel Agencies, Direct Bookings, Travel Agents, Aggregators |
| Companies Covered | Trip.com Group Ltd, Meituan-Dianping, Qunar.com, Tongcheng-Elong Holdings Ltd, Fliggy (Alibaba), Jin Jiang International Holdings Co., Ltd., Huazhu Group Ltd., GreenTree Hospitality Group Ltd., BTG Homeinns Hotels Group Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Online Travel Market Trends and Innovations
Artificial intelligence recommendation engines are compressing search-to-booking cycles while regulatory pressure on data handling is reshaping platform architecture investments.
Generative AI itinerary builders is electrifying how domestic travelers discover multi-city routes, with younger demographic segments adopting conversational booking interfaces at three times the rate of traditional search-based tools, compressing the competitive moat of established keyword-ranking platforms.
MIIT's push for algorithmic transparency in pricing is forcing disclosure of dynamic markup methodologies, with flight and hotel bundling segments facing the steepest compliance costs as platforms reengineer backend systems to document real-time commission stacking logic for auditor review.
Experience-first trip planning is displacing transportation-led booking sequences, with Shanghai and Shenzhen travelers initiating searches around dining reservations and local activities before confirming accommodation, forcing platforms to reweight inventory display algorithms toward experiential anchor points rather than flight availability.
China Online Travel Market Segmentation
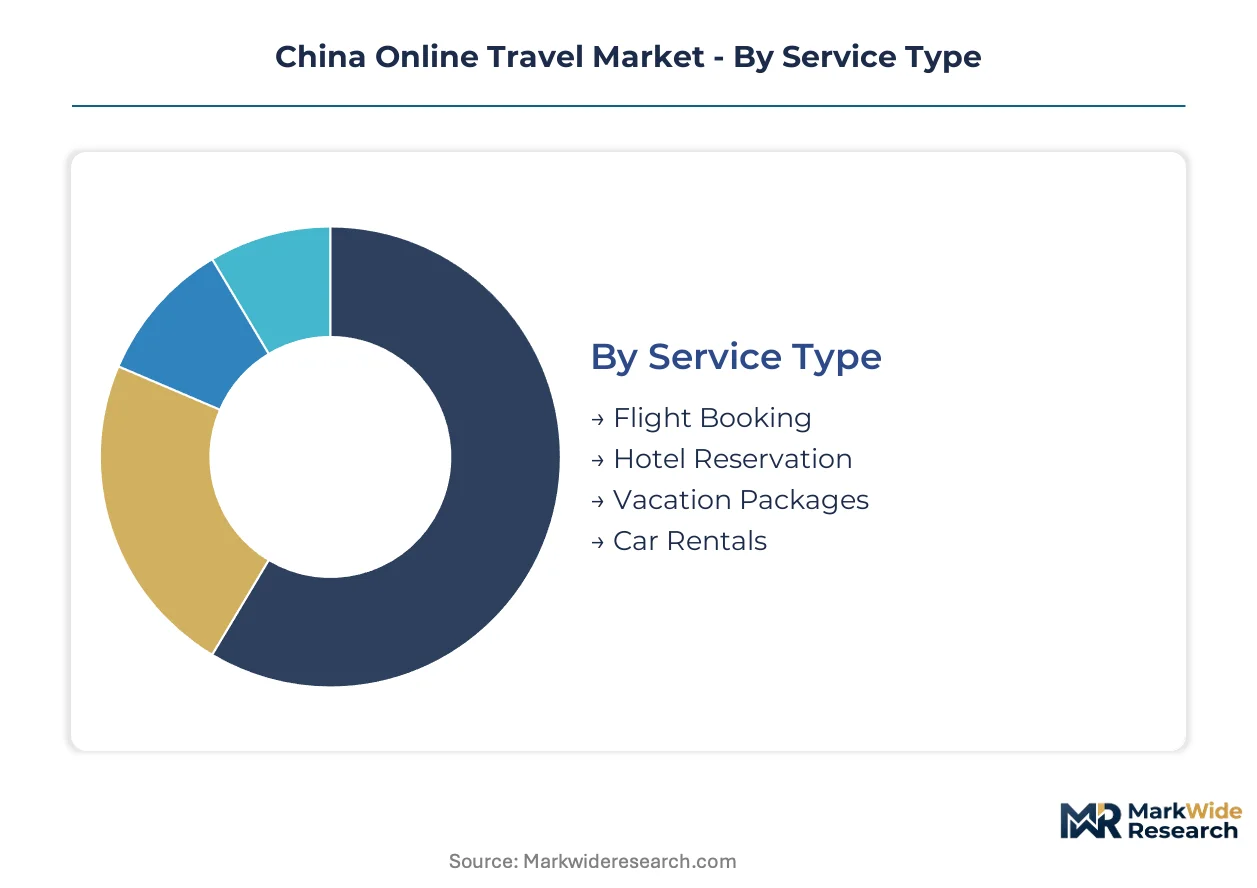
Segmentation in China's online travel market reveals how regulatory compliance burdens and payment infrastructure requirements vary sharply across service types and customer profiles. Platforms must architect separate operational workflows for each segment to satisfy MIIT data governance mandates and SAMR pricing transparency rules.
Service Type:
Flight Booking carries NMPA cross-border health protocol alignment requirements for international routes, while Vacation Packages face heightened SAMR scrutiny on bundled fee disclosure.
- Flight Booking:Real-time inventory APIs connect airline central reservation systems to platform search interfaces. Demand concentrates in Shanghai and Beijing corridor routes where business travelers prioritize schedule flexibility over price sensitivity, though direct airline app penetration compresses aggregator commissions in these saturated markets.
- Vacation Packages:Bundled itinerary sales stack margins across transportation, accommodation, and experience components into single transaction flows. Middle-class families in Shenzhen and Guangzhou drive adoption as they seek convenience over component-by-component booking, with platforms extracting higher take rates from packaged margin stacking.
- Hotel Reservation:Property management system fragmentation in lower-tier cities creates API standardization delays.
- Car Rentals:Fleet connectivity integration remains underdeveloped outside tier-one urban clusters.
Leading the category by volume: Flight Booking. Growing fastest: Vacation Packages.
Customer Type:
Business Travelers generate the highest per-transaction values but face MEE carbon reporting requirements that constrain routing flexibility, while Families exhibit the strongest super-app ecosystem loyalty.
- Business Travelers:Corporate procurement policies mandate centralized booking platforms with expense management integration and emissions documentation. Procurement departments in state-owned enterprises and multinational affiliates drive platform selection, with dual carbon goals forcing visibility into transportation carbon intensity.
- Families:Multi-generational trip planning demands simultaneous accommodation for varying mobility needs and dining preferences. Shanghai and Beijing households consolidate spend through Meituan-Dianping super-app architectures that cross-sell local experiences, creating stickiness unavailable to single-vertical competitors.
- Tourists:Experience-first search behavior displaces transportation-led booking sequences in coastal provinces.
- Solo Travelers:Price-sensitive segment with highest mobile payment adoption rates among younger demographics.
Volume leadership: Business Travelers. Steepest expansion trajectory: Families.
Payment Method:
Credit Cards face declining relevance as mobile infrastructure matures, while E-Wallets compete for unbanked traveler segments in lower-tier cities.
- Mobile Payments:Alipay and WeChat Pay integration functions as a technical moat that foreign competitors cannot replicate. Tier-one cities achieve near-complete penetration, with biometric authentication and escrow services reducing transaction abandonment rates below traditional card-based alternatives.
- E-Wallets:Platform-specific stored value instruments like Trip.com Wallet enable loyalty point monetization and refund acceleration. Younger travelers in Shenzhen and Hangzhou adopt these instruments for budget segmentation and parental oversight features on family account structures.
- Credit Cards:International card network acceptance remains concentrated in premium hotel inventory.
- Bank Transfers:Enterprise travel procurement maintains this channel for audit trail requirements.
Dominant by transaction volume: Mobile Payments. Expanding most quickly: E-Wallets.
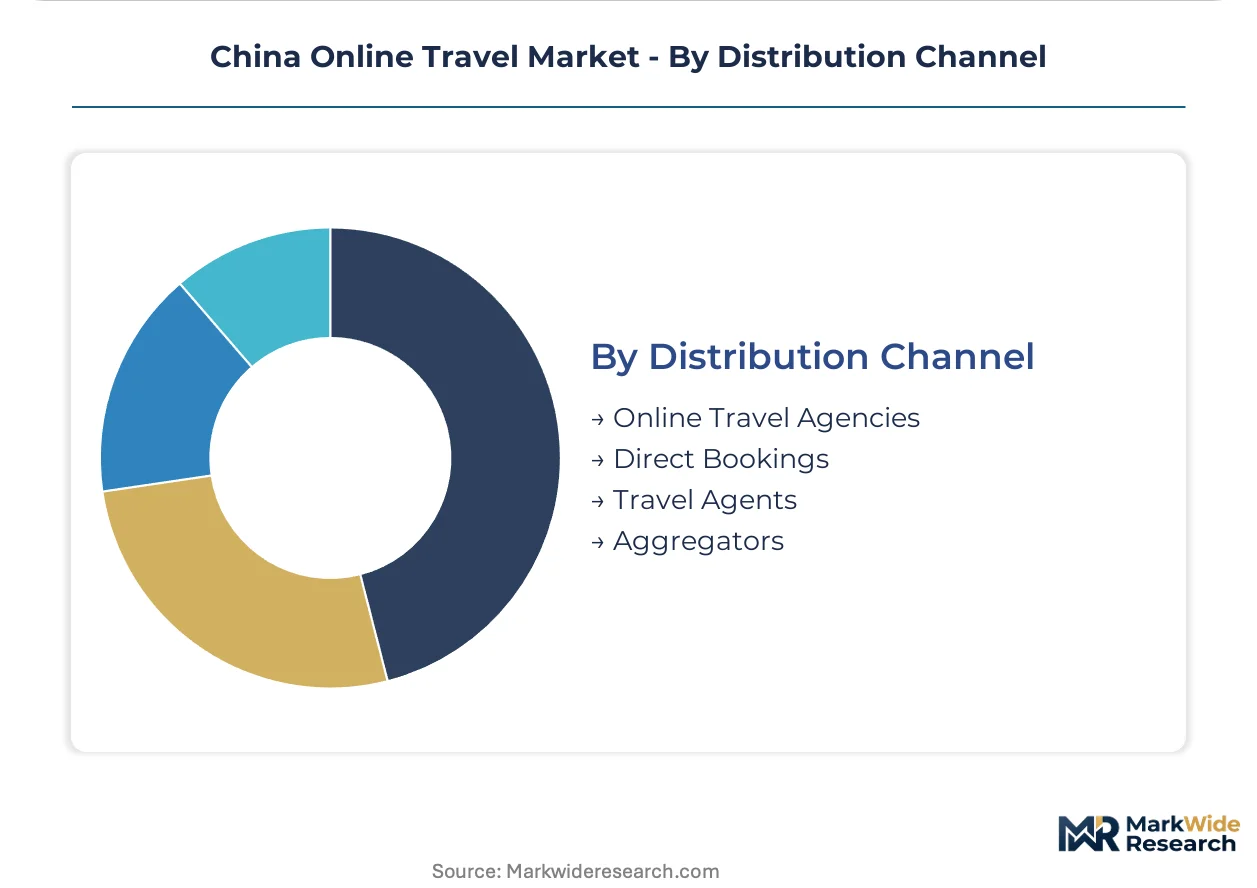
Distribution Channel:
Online Travel Agencies absorb the heaviest MIIT compliance costs for algorithmic transparency, while Direct Bookings bypass aggregator fees but sacrifice comparison functionality.
- Online Travel Agencies:Full-service platforms integrate flights, hotels, rail, and experiences into unified search and booking workflows. Trip.com Group and Tongcheng-Elong Holdings compete on inventory depth and supplier commission structures, with SAMR antitrust enforcement constraining loyalty program architectures.
- Direct Bookings:Airline and hotel proprietary applications capture repeat travelers through member-exclusive pricing and simplified modification policies. China Eastern and Hainan Airlines invest in app functionality to reclaim margin from aggregator intermediation in tier-one corridors.
- Aggregators:Metasearch models face pressure from platform commission compression and direct supplier retaliation.
- Travel Agents:Traditional brick-and-mortar retains relevance for complex multi-city corporate itineraries and visa documentation services.
Transaction volume leader: Online Travel Agencies. Gaining share fastest: Direct Bookings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors China's online travel demand through its dual-hub airport infrastructure and super-app payment density. The Yangtze River Delta, Pearl River Delta, and Beijing-Tianjin-Hebei corridor concentrate platform transaction volume. Provincial regulators enforce MIIT data localization mandates with varying stringency across municipal boundaries.
Yangtze River Delta
Shanghai and Hangzhou households drive vacation package adoption through Meituan-Dianping ecosystem consolidation. SAMR pricing transparency audits focus heavily on this corridor given transaction concentration. Suzhou and Ningbo hotel networks suffer property management system fragmentation that delays real-time inventory API standardization.
Pearl River Delta
Shenzhen and Guangzhou travelers exhibit experience-first search behavior, initiating bookings around dining and local activities. MEE carbon reporting requirements for corporate procurement reshape business travel platform selection in this manufacturing hub. Dongguan and Foshan hotel supply remains digitally fragmented, rewarding specialized lower-tier penetration strategies.
Beijing-Tianjin-Hebei
State-owned enterprise procurement departments in Beijing mandate centralized booking platforms with emissions documentation. MIIT algorithmic transparency enforcement originates from this administrative center, forcing dynamic pricing disclosure. Tianjin's cruise port infrastructure and Shijiazhuang's high-speed rail connectivity create multimodal itinerary bundling opportunities.
Sichuan-Chongqing
Chengdu and Chongqing leisure travelers show strongest adoption of generative AI itinerary builders among interior provinces. Dual carbon goals pressure rail-flight bundling integration given basin geography constraints. Deyang and Mianyang hotel networks lag in direct digital access, maintaining traditional travel agency intermediation.
Shandong Peninsula
Qingdao and Jinan families consolidate travel spend through Alipay-integrated super-app architectures. NMPA cross-border health protocol alignment concentrates preparation effort here given international aviation gateway status. Yantai and Weihai coastal tourism inventory faces API standardization delays from legacy property management systems.
China Online Travel Market Competitive Landscape
The competitive structure tilts toward super-app ecosystems and integrated supply chain operators. Platform concentration remains pronounced in tier-one cities where mobile payment penetration creates technical moats. Two archetypes dominate: vertically integrated travel-hospitality conglomerates and super-app cross-sellers leveraging dining-local experience adjacencies. Competitive moves center on rail-flight bundling integration and lower-tier city hotel network penetration.
Among integrated supply chain operators, Trip.com Group Ltd exemplifies the full-service platform archetype spanning flights, hotels, rail, and experiences. Meituan-Dianping occupies the super-app cross-seller position, anchoring travel within dining and local service ecosystems. Tongcheng-Elong Holdings Ltd represents specialized lower-tier penetration, sitting within the focused geographic coverage archetype. These three entities collectively illustrate how divergent platform architectures compete for domestic leisure and business traveler segments under tightening SAMR antitrust and MIIT data governance frameworks.
| Leading Market Players |
|---|
| Trip.com Group Ltd |
| Meituan-Dianping |
| Qunar.com |
| Tongcheng-Elong Holdings Ltd |
| Fliggy (Alibaba) |
| Jin Jiang International Holdings Co., Ltd. |
| Huazhu Group Ltd. |
| GreenTree Hospitality Group Ltd. |
| BTG Homeinns Hotels Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jet fuel price indices cascade through airline revenue management systems into online travel platform commission structures, compressing aggregator margins while forcing dynamic markup recalibration across bundled itinerary tiers.
Pricing Analysis
Yield-per-seat-mile optimization anchors airline inventory pricing, with platforms stacking commissions atop base fares to generate tiered service fees. Price differentiation stems from real-time inventory scarcity algorithms and loyalty tier status, with business travelers exhibiting lowest sensitivity due to corporate procurement policies while solo travelers drive price elasticity. Cost compression in saturated tier-one flight corridors intensifies as direct airline app penetration bypasses aggregator intermediation.
Supply Chain Analysis
Global Distribution System connectivity rests on Amadeus, Sabre, and TravelSky API infrastructure concentrated in Spain, USA, and China. Property management system integration draws from Oracle Hospitality, Shiji, and local Chinese vendors, while payment gateway processing hinges on Alipay and WeChat Pay domestic server networks. Single-source vulnerability concentrates in GDS contract renewals. Distribution runs through cloud-hosted platform architectures with MIIT-mandated data localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's online travel sector is consolidating around super-app ecosystems and integrated supply chain operators, with SAMR antitrust enforcement and MIIT data governance costs forcing marginal players toward exit or acquisition.
For Market Incumbents: Anticipate direct airline app retaliation in tier-one corridors by deepening rail-flight bundling integration that single-vertical competitors cannot replicate. Fortify lower-tier city hotel network APIs before Tongcheng-Elong Holdings extends its fragmentation-exploitation model. MIIT algorithmic transparency mandates threaten dynamic pricing flexibility—invest in documentation-ready backend systems now. For New Entrants and Emerging Players: Enter via experience-first trip planning interfaces targeting Shanghai and Shenzhen travelers who initiate searches around dining reservations before confirming accommodation. White-space concentrates in tier-three and tier-four city hotel property management system integration, where legacy fragmentation delays real-time inventory accuracy. Pursue generative AI itinerary builder positioning to capture younger demographic adoption at triple the rate of keyword-search platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized lower-tier penetration platforms with established hotel network APIs in Sichuan-Chongqing and Shandong Peninsula corridors, where direct digital access remains fragmented. Long-term viability centers on super-app ecosystem adjacencies or rail-transport integration capabilities that create multimodal itinerary stickiness. Watch NMPA cross-border health protocol normalization as inbound tourism recovery inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Flight Bundling Integration | Creates itinerary stickiness unavailable to single-vertical competitors in Beijing-Tianjin-Hebei corridor. |
| Generative AI Itinerary Builder Launch | Captures younger demographic adoption at triple rate of traditional search-based booking tools. |
| Lower-Tier City Hotel Network Expansion | Exploits property management system fragmentation that delays real-time API standardization. |
| MIIT Compliance Architecture Upgrade | Documents dynamic markup methodologies for auditor review under algorithmic transparency mandates. |
| Super-App Ecosystem Cross-Sell Partnership | Consolidates travel spend within dining and local experience adjacencies as Meituan-Dianping demonstrates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among online travel platform product managers, airline revenue management executives, hotel chain distribution directors, and MIIT compliance officers. Bottom-up modeling triangulated against top-down sector expenditure analysis using SAMR enforcement records, NMPA protocol documentation, and MIIT cloud infrastructure guidelines.
Segment-level granularity modeled service type, customer archetype, payment method, and distribution channel dimensions across the projection horizon. CAGRs derived from historical transaction volume trajectories and penetration rate assumptions, with vacation package growth calibrated against middle-class household expenditure surveys and rail inventory integration timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA cross-border protocol acceleration or MIIT data localization cost spikes. Assumptions reflect current regulatory enforcement posture and mobile payment infrastructure maturity. A small set of triggers—SAMR antitrust escalation, generative AI adoption inflection, and international aviation normalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Educational Tourism Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Agritourism Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
South Korea Sports Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
New Zealand Sustainable Tourism Market
Travel and Tourism
Yacht Charter Service Market
Travel and Tourism
Wedding Tourism Market