
 Airline a-La-Carte Services Market | 2026-2036
Airline a-La-Carte Services Market Size, Share, and Industry Trends Forecast 2026-2036
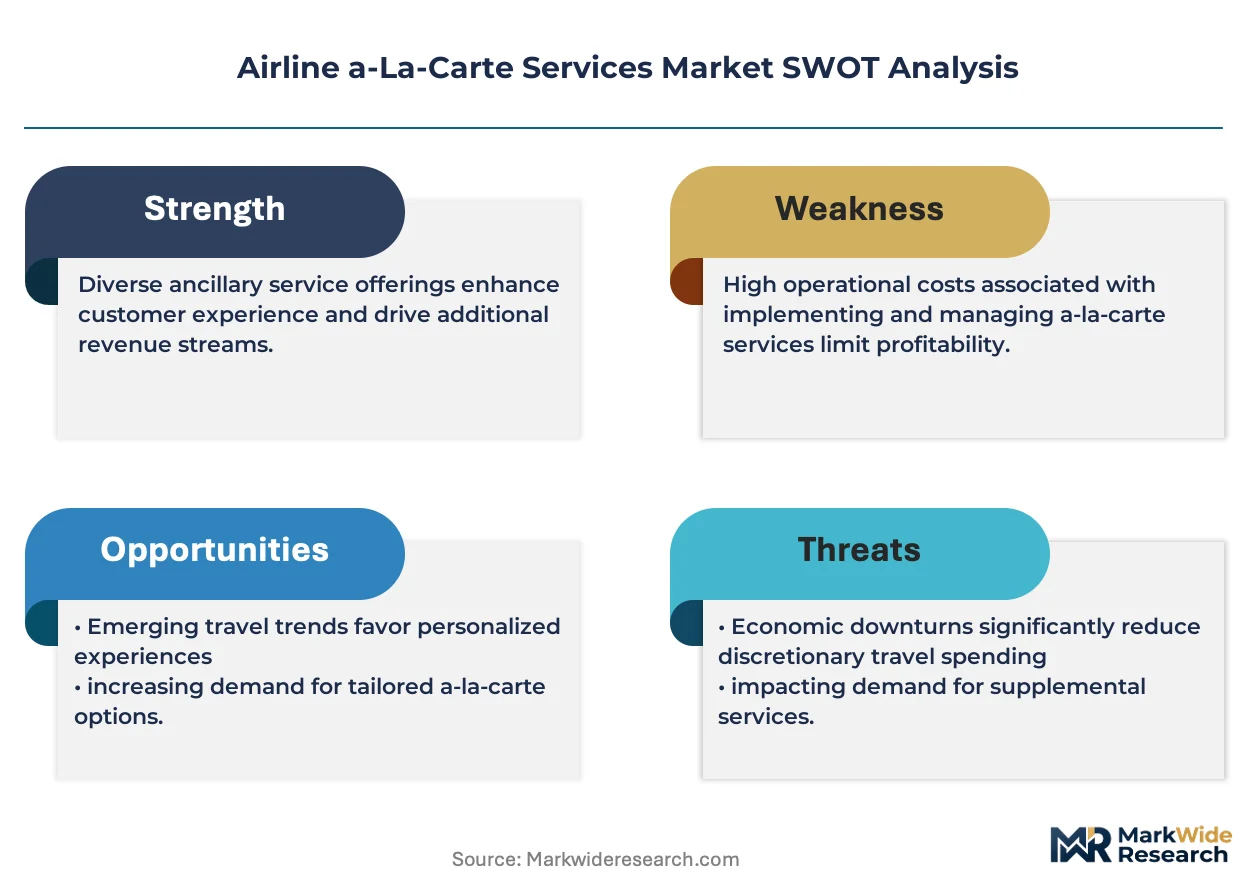
Airline a-La-Carte Services Market Analysis
The capability gap between full-service network carriers and ultra-low-cost operators is collapsing. Ryanair Holdings leverages its proprietary digital platform to control ancillary merchandising across every customer touchpoint. American Airlines Group anchors its revenue management systems around dynamic seat pricing algorithms that sustain premium yields on transatlantic routes. Delta Air Lines differentiates through branded fare bundles that integrate Wi-Fi and baggage allowances into tiered product architecture.
Airline a-la-carte services constitute individually priced travel amenities detached from base airfare, encompassing seat selection algorithms that process real-time cabin density data, priority boarding queues segmented by fare family, bandwidth-differentiated inflight connectivity, and weight-dimension baggage modules governed by IATA Resolution 302. These services functionally enable yield optimization across price-sensitive demand curves while transferring operational cost volatility to passengers. Seat selection and inflight Wi-Fi represent the deepest margin pools within service type segmentation, whereas subscription plans within pricing models are displacing fixed fees among frequent flyer cohorts. Mobile apps dominate delivery mode adoption due to push-notification merchandising and one-tap purchase friction reduction.
The US Department of Transportation enforces 24-hour refund transparency on ancillary purchases, while the EU's Passenger Rights Regulation mandates clear fee disclosure before booking completion. IATA's New Distribution Capability standard reshapes how carriers retail a-la-carte content through third-party channels. Stakeholders must monitor regulatory divergence between DOT refund mandates and EU disclosure rules as these frameworks determine platform architecture investments and partnership liability structures.
Market Dynamics
The unbundling of legacy fare structures into granular, algorithmically-priced components is reconfiguring airline revenue architecture. IATA's New Distribution Capability standard now governs how carriers merchandise seat selection, baggage modules, and connectivity through third-party channels, compressing the capability gap between network carriers and low-cost operators.
Growth Catalysts
- EU Passenger Rights Regulation:Mandates transparent fee disclosure before booking completion, accelerating consumer acceptance of itemized pricing across European Union member states.
- Mobile-first merchandising:Push-notification architectures and one-tap purchase friction reduction through proprietary carrier apps drive conversion rates on ancillary attachments.
- Southeast Asian LCC expansion:IndiGo and Air India deploy unbundled fare families across India's domestic network, normalizing à-la-carte expectations among price-sensitive travelers.
Market Restraints
- DOT refund mandates:US Department of Transportation enforcement of 24-hour refund transparency on ancillary purchases increases operational complexity and revenue recognition volatility.
- Legacy PSS integration:Passenger service system architectures from Sabre and Amadeus impose technical constraints on real-time ancillary pricing and inventory synchronization.
- Bandwidth infrastructure:Inflight connectivity depends on satellite capacity concentration with Viasat and Inmarsat, creating input cost volatility for Wi-Fi service margins.
Strategic Opportunities
- Subscription pricing models:Annual Wi-Fi passes and baggage bundles displace per-flight fees among frequent flyer cohorts, capturing lifetime value through recurring revenue structures.
- Biometric boarding integration:Facial recognition at gate checkpoints enables premium priority queue monetization and operational throughput gains at hub airports.
- Carbon offset attachment:EU Green Deal alignment creates regulatory tailwind for voluntary emissions compensation modules at point of sale.
Industry Challenges
- Revenue accounting systems:Legacy ERP platforms require reconfiguration to handle real-time recognition of fragmented ancillary transactions across multiple touchpoints.
- Interline settlement complexity:IATA Resolution 302 baggage rules create proration disputes between operating and marketing carriers on code-share itineraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline a-La-Carte Services Market |
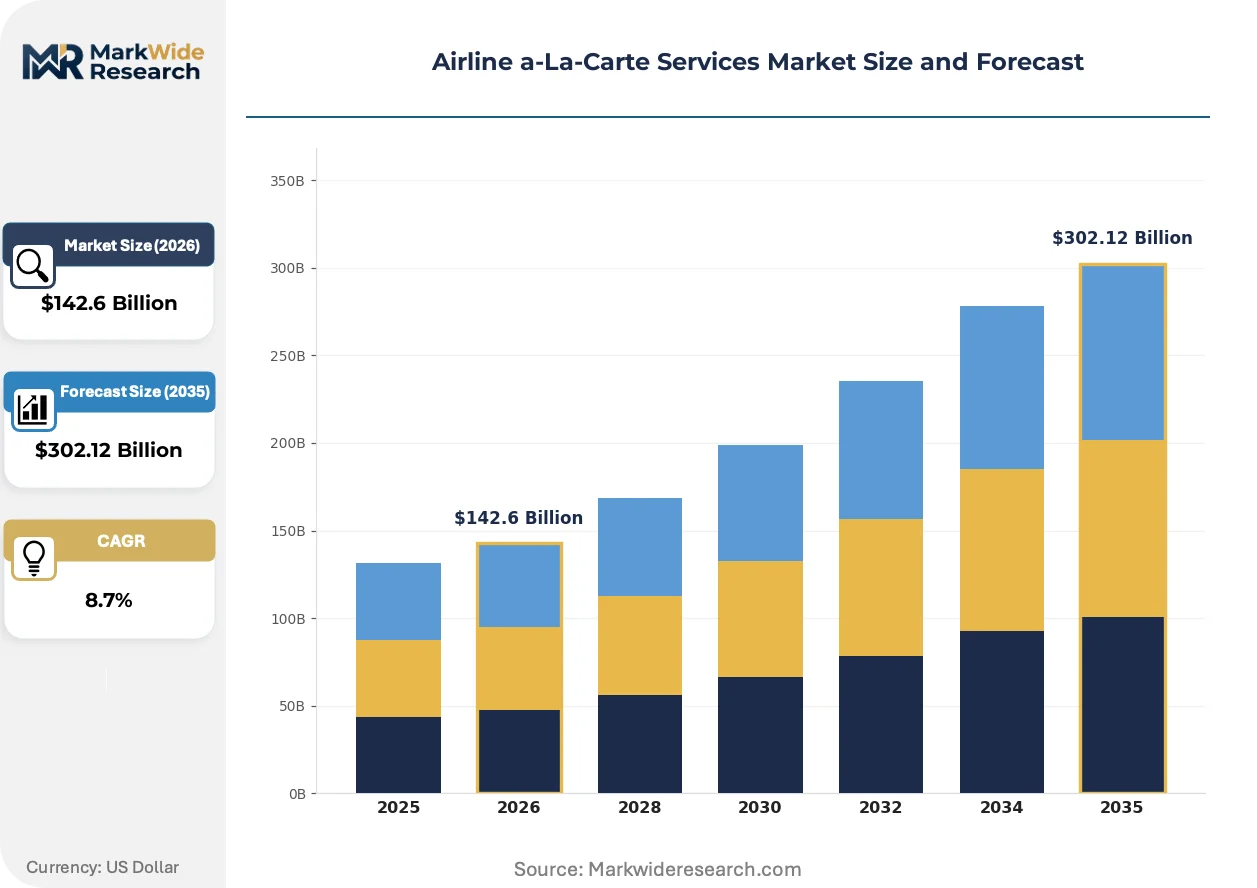
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Seat Selection, Priority Boarding, Extra Baggage, Inflight Wi-Fi Customer Type: Business Travelers, Leisure Travelers, Frequent Flyers, Group Booking Pricing Model: Fixed Fees, Tiered Pricing, Subscription Plans, Pay-Per-Use Delivery Mode: Online Booking, Mobile Apps, Travel Agents, Kiosks |
| Companies Covered | Ryanair Holdings, American Airlines Group, Delta Air Lines, United Airlines Holdings, Air France KLM, Southwest Airlines, EasyJet, Deutsche Lufthansa, Singapore Airlines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline a-La-Carte Services Market Emerging Trajectories
Artificial intelligence is decomposing traditional revenue management into dynamic micro-pricing engines that adjust seat and service values in real-time. Three interconnected developments are restructuring how airlines merchandise travel amenities.
Machine learning algorithms are decomposing static fare buckets into continuous pricing curves that respond to cabin density, booking velocity, and competitive position. Low-cost carriers deploy these engines most aggressively, while full-service airlines retrofit legacy revenue management systems. The structural consequence is margin compression on base fares offset by premium yields on attached services.
The EU's updated Passenger Rights Regulation mandates pre-booking disclosure of all optional fees, reshaping platform architecture investments. Airlines must reengineer reservation flows to display itemized costs before payment capture. This friction most affects indirect distribution channels where GDS intermediaries control the customer interface.
Subscription purchasing is displacing transactional fee models among high-frequency travelers. Annual Wi-Fi plans and baggage memberships reduce per-flight decision fatigue while locking in carrier loyalty. This pattern concentrates in North American and European domestic markets where business traveler density supports recurring revenue economics.
Airline a-La-Carte Services Market Segmentation
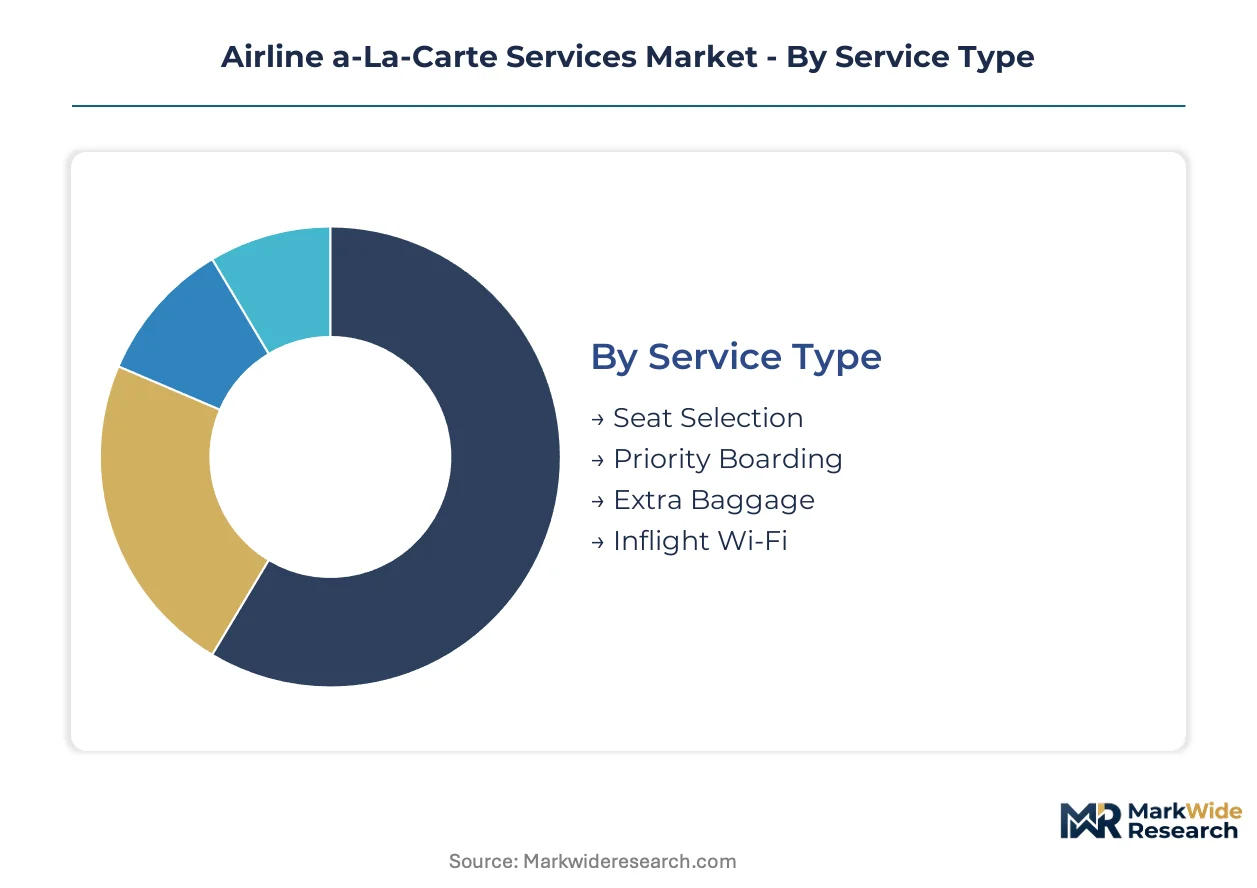
A-la-carte service segmentation reveals how airlines extract differential willingness-to-pay across passenger profiles and purchase contexts. Understanding substitution patterns between service categories enables targeted merchandising architecture that protects margin pools from erosion.
Service Type:
Substitution pressure runs strongest against commoditized amenities where passenger indifference is highest, while algorithmically differentiated services defend pricing power.
- Seat Selection:Dynamic pricing engines process real-time cabin density data to adjust fees based on remaining inventory and booking velocity. Demand concentrates in India's domestic network where IndiGo and Air India deploy unbundled fare families, though DOT refund mandates on 24-hour cancellations introduce revenue recognition volatility.
- Inflight Wi-Fi:Bandwidth-differentiated connectivity tiers generate the deepest ancillary margins through satellite-dependent infrastructure. European carriers face EU Passenger Rights Regulation disclosure requirements that reshape platform architecture investments before payment capture.
- Priority Boarding:Queue segmentation by fare family monetizes operational throughput at hub airports.
- Extra Baggage:Weight-dimension modules governed by IATA Resolution 302 create interline settlement complexity on code-share itineraries.
Seat selection anchors the volume base while inflight Wi-Fi gains share at the steepest rate.
Customer Type:
Cost tier stratification separates price-sensitive leisure segments from premium-capture business cohorts with divergent elasticity profiles.
- Frequent Flyers:Subscription purchasing displaces transactional fees through annual Wi-Fi passes and baggage bundles that reduce per-flight decision fatigue. North American and European domestic markets concentrate demand where business traveler density supports recurring revenue economics.
- Business Travelers:Corporate policy compliance requirements and receipt granularity needs drive attachment of itemized services. Mobile-first merchandising through push-notification architectures targets this segment with one-tap purchase friction reduction.
- Leisure Travelers:Price sensitivity dominates purchase behavior with high elasticity on optional fees.
- Group Booking:Consolidated purchasing power creates volume discount pressure on per-passenger ancillary yields.
Frequent flyers anchor the volume base while business travelers expand most quickly as corporate travel normalizes.
Pricing Model:
Volume concentration favors predictable recurring structures over variable per-use fees in high-frequency corridors.
- Subscription Plans:Annual passes lock in carrier loyalty and capture lifetime value through recurring revenue structures. EU Green Deal alignment creates regulatory tailwind for carbon offset attachments within bundled memberships.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy segments responds to cabin density and competitive position. Machine learning engines enable continuous pricing curves that replace static fare buckets.
- Fixed Fees:Simple per-service pricing persists in indirect distribution channels where GDS intermediaries control customer interface.
- Pay-Per-Use:Transactional models retain relevance for infrequent travelers with low annual flight volume.
Subscription plans anchor the volume base while tiered pricing climbs the fastest as algorithmic engines proliferate.
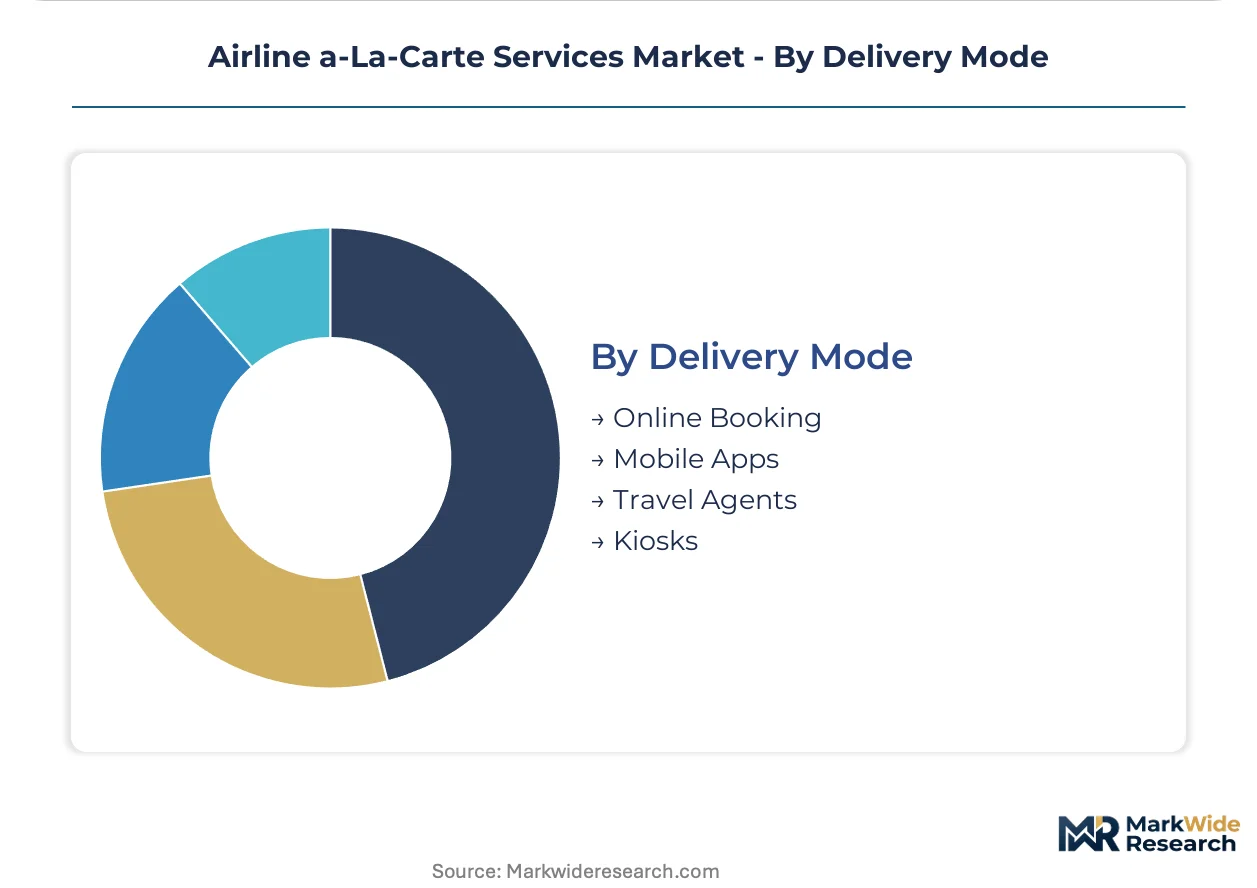
Delivery Mode:
Customer type concentration determines channel priority, with mobile architectures capturing the highest-attachment passenger segments.
- Mobile Apps:Proprietary carrier platforms control merchandising across every touchpoint with push-notification conversion optimization. Ryanair Holdings leverages this channel most aggressively for ancillary attachment.
- Online Booking:Direct web channels enable pre-booking fee disclosure compliance under EU Passenger Rights Regulation mandates.
- Travel Agents:Indirect distribution faces friction from GDS legacy constraints on real-time ancillary pricing synchronization.
- Kiosks:Airport self-service terminals capture last-minute purchase intent with reduced decision time.
Mobile apps anchor the volume base while online booking shows the steepest expansion trajectory as platform investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for ancillary services varies sharply across geographies. Southeast Asian travelers accept unbundled fares most readily, while European passengers demand fee transparency before purchase completion. North American carriers face the strictest refund mandates.
United States
Domestic carriers generate substantial ancillary yield from seat selection algorithms and dynamic Wi-Fi pricing. The DOT enforces 24-hour refund transparency on all optional purchases, increasing operational complexity. Dallas-Fort Worth and Atlanta hub concentrations anchor American Airlines Group and Delta Air Lines merchandising infrastructure.
Germany
Deutsche Lufthansa deploys branded fare bundles integrating connectivity and baggage across European trunk routes. The EU Passenger Rights Regulation mandates pre-booking disclosure of all optional fees. Frankfurt and Munich airport clusters support premium priority boarding monetization through biometric gate integration.
India
IndiGo and Air India expand unbundled fare families across domestic networks with 8.70% annual market growth through 2035. The Directorate General of Civil Aviation monitors fee disclosure compliance under consumer protection frameworks. Mumbai and Delhi-NCR aviation corridors concentrate demand for weight-dimension baggage modules.
United Kingdom
EasyJet leverages proprietary mobile platforms for push-notification ancillary conversion on short-haul European routes. The UK Civil Aviation Authority aligns with EU-derived disclosure standards post-Brexit. London Gatwick and Luton bases anchor low-cost carrier density for subscription pricing model trials.
Singapore
Singapore Airlines differentiates through tiered connectivity bundles on long-haul Asia-Pacific routes. The Civil Aviation Authority of Singapore enforces IATA Resolution 302 baggage settlement standards. Changi Airport's hub infrastructure enables priority queue segmentation and operational throughput gains.
Airline a-La-Carte Services Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the airline a-la-carte services market. Ultra-low-cost operators deploy proprietary digital platforms for ancillary merchandising control, while full-service network carriers retrofit legacy revenue management systems with dynamic pricing engines. Two strategic archetypes dominate: platform-native LCCs with zero-legacy infrastructure, and hybrid carriers with tiered product architecture. Competitive moves concentrate on mobile-first merchandising investments and biometric boarding integration at hub airports.
Within the ultra-low-cost tier, Ryanair Holdings exemplifies platform-native merchandising architecture. Among US-based network carriers, American Airlines Group and Delta Air Lines occupy positions representing divergent strategic approaches—dynamic seat pricing algorithms versus branded fare bundle integration. These three carriers anchor the competitive landscape through contrasting technology deployment and revenue management philosophies.
| Leading Market Players |
|---|
| Ryanair Holdings |
| American Airlines Group |
| Delta Air Lines |
| United Airlines Holdings |
| Air France KLM |
| Southwest Airlines |
| EasyJet |
| Deutsche Lufthansa |
| Singapore Airlines |
| Others |
Supply Flow & Price Mechanics
IATA's New Distribution Capability standard gates both supplier qualification for third-party channel access and carrier ability to command price premiums on attached services. Airlines lacking NDC certification face margin compression on base fares while certified operators extract algorithmic yields from real-time merchandising.
Pricing Analysis
Subscription revenue tiers now drive lifetime value more than transactional per-flight fees. Three-tier pricing structure across premium, standard, and economy connectivity bundles anchors yield management, with price differentiation resting on bandwidth allocation and loyalty program integration. Pricing pressure stems from DOT refund mandates on 24-hour cancellations, which compress margin recognition timing. Leisure travelers exhibit highest price sensitivity on optional fees, while corporate road warriors locked into annual Wi-Fi passes show lowest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate satellite capacity procurement, with carriers avoiding long-term bandwidth commitments amid orbital constellation deployment cycles. Supply concentrates in the United States, United Kingdom, and Singapore where Viasat and Inmarsat ground station infrastructure anchors connectivity service delivery. Raw material dependencies span geostationary satellite transponders, low-earth-orbit terminal hardware, and terrestrial data center interconnection. Single-source vulnerability runs through concentrated satellite operator consolidation. Distribution runs through proprietary carrier mobile apps and GDS intermediaries with legacy synchronization constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as IATA NDC interoperability reshapes how carriers merchandise through indirect channels. This ecosystem shift rewards operators controlling end-to-end customer data flows.
For Market Incumbents: Consolidate proprietary digital platform architecture to defend ancillary attachment rates against ultra-low-cost carrier encroachment. Lock in exclusive satellite capacity agreements to secure Wi-Fi margin pools. Prioritize biometric boarding infrastructure investment at hub airports to monetize operational throughput gains. For New Entrants and Emerging Players: Lead with white-space targeting of interline settlement complexity on code-share itineraries where legacy carriers face revenue leakage. India's domestic aviation corridor offers most penetrable geography given IndiGo and Air India expansion dynamics. Deploy API-first distribution partnerships with online travel agencies lacking NDC-native infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from full-service network carriers spinning non-core ancillary technology stacks. Long-term viability favors operators capturing recurring subscription revenue over transactional fee dependence. Monitor biometric boarding deployment velocity at Changi, Frankfurt, and Dallas-Fort Worth as inflection signal for premium queue monetization scalability.| Strategic Initiative | Industry Significance |
|---|---|
| NDC Platform Integration | Enables real-time ancillary merchandising through third-party channels per IATA standards. |
| Biometric Boarding Deployment | Captures priority queue premiums at hub airports with facial recognition gate infrastructure. |
| Subscription Pricing Migration | Locks frequent flyer lifetime value through annual Wi-Fi passes and baggage memberships. |
| Satellite Capacity Agreement | Secures bandwidth supply with Viasat or Inmarsat to defend inflight connectivity margins. |
| Mobile App Merchandising Optimization | Reduces purchase friction through push-notification architectures and one-tap conversion flows. |
Methodological Framework
Initial hypotheses were tested against primary input from airline revenue management executives, ancillary product directors, GDS platform engineers, and satellite connectivity procurement leads and refined through secondary validation across IATA operational reports, DOT regulatory filings, EU Passenger Rights Regulation documentation, and carrier annual disclosures. Bottom-up transaction volume estimates triangulated with top-down market sizing from aviation authority statistics.
Variance-decomposition framing isolates growth contributions across service type, customer segment, pricing model, and delivery mode dimensions throughout the forecast period. CAGRs derived from logistic adoption curves for subscription pricing and linear penetration assumptions for biometric infrastructure deployment. Industry-specific inputs include satellite capacity expansion schedules and NDC certification adoption curves by carrier archetype.
Underlying assumptions cover regulatory enforcement consistency on refund transparency, with deviation risk concentrated in DOT mandate expansion or EU disclosure rule harmonization shifts. Revision becomes warranted when biometric boarding deployment at major hubs crosses operational viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
Europe Business Travel Market
Business Travel Services
Latin America Business Travel Market
Business Travel Services
Business Travel Lodging Market
Business Travel Services
United States Business Travel Market
Business Travel Services
Brazil Business Travel Lodging Market
Business Travel Services
Europes Golden Generation Travel Market
Business Travel Services
Bleisure Travel Market
Business Travel Services
Business Travel Market