
 Chile OOH and DOOH Market | 2026-2036
Chile OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Chile OOH and DOOH Market Insights
Buyer concentration among Santiago-based retail and automotive advertisers is repositioning inventory negotiation power toward national agencies with cross-format capabilities. Clear Channel Chile leverages its transit concession network across Metro Santiago and major bus corridors. JCDecaux Chile sustains dominance in street furniture formats through exclusive municipal partnerships. Viva Outdoor competes via specialized billboard placements along the Pan-American Highway and northern mining corridor access routes.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display media deployed in public spaces for commercial messaging, encompassing static vinyl billboards, LED digital screens, and programmatically traded network inventory with real-time audience measurement capabilities. The medium serves brand awareness, local activation, and performance marketing objectives for advertisers seeking geographic precision beyond digital channel saturation. Digital displays represent the fastest-growing medium type as programmatic infrastructure enables impression-based trading and dynamic creative optimization. Static billboards remain the largest revenue pool due to lower operational complexity and established regulatory pathways. Transit ads capture concentrated demand from automotive and telecommunications end users seeking captive commuter audiences.
Chile's municipal advertising codes and the Undersecretariat of Telecommunications framework govern physical installation permits and digital screen emissions standards, while the National Consumer Service oversees truth-in-advertising enforcement across public displays. These regulations shape deployment density limits, screen brightness thresholds, and content approval timelines that directly affect network expansion economics. Stakeholders must monitor evolving municipal digitization policies and programmatic data privacy interpretations as Santiago and Valparaíso advance smart city infrastructure plans.
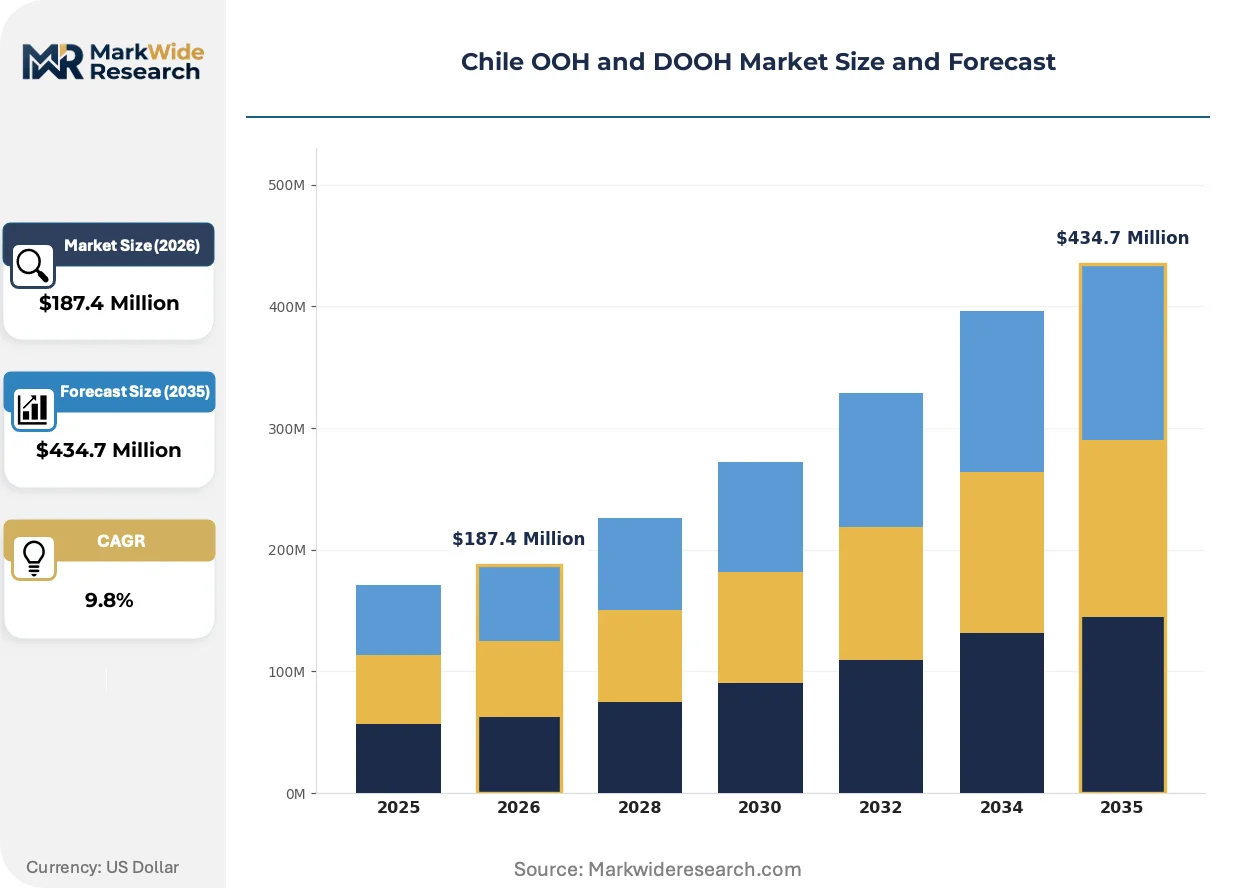
Market Dynamics
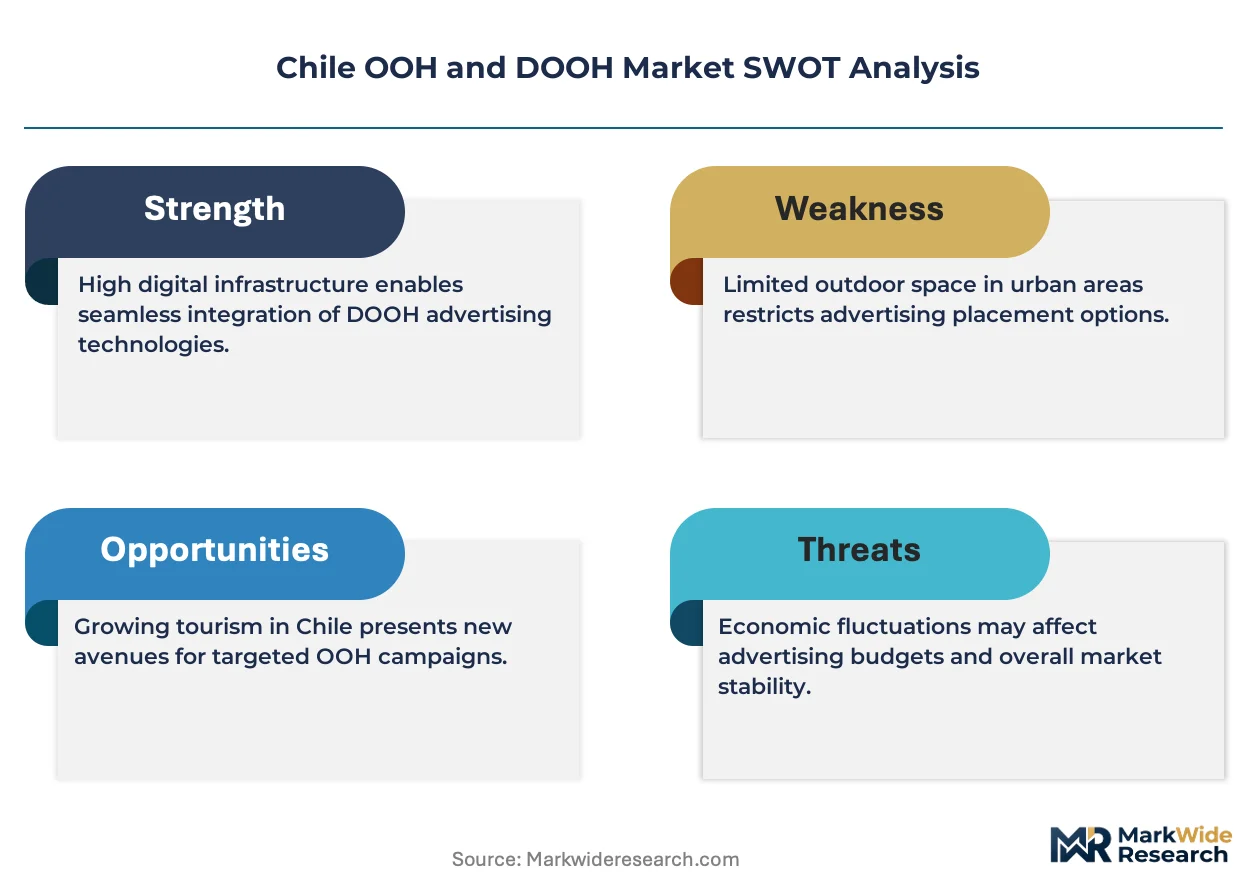
Programmatic trading infrastructure is compressing the buying cycle for digital inventory, shifting negotiation power from media owners toward data-enabled agencies and direct retail advertisers in Santiago's transit corridors.
Growth Catalysts
- Updated municipal advertising codes:Chile's revised municipality frameworks streamline digital screen deployment permissions, reducing approval timelines for network expansion in metropolitan zones.
- Transit infrastructure modernization:Metro Santiago's corridor upgrades create captive audience environments where automotive and telecommunications advertisers concentrate spend.
- Programmatic impression-based trading:Real-time audience measurement capabilities enable dynamic creative optimization, pulling budget from static formats toward addressable digital inventory.
Market Restraints
- LED hardware import concentration:Display panel sourcing depends on Asian manufacturing hubs, exposing operators to shipping cost volatility and currency fluctuation risk.
- Municipal exclusivity fragmentation:Street furniture concessions lock into single-operator contracts per municipality, blocking competitive entry in Valparaíso and Concepción premium zones.
- Digital emissions compliance:Undersecretariat of Telecommunications brightness thresholds and energy standards raise operational complexity for high-lumen roadside installations.
Strategic Opportunities
- Northern mining corridor access routes:Billboard networks along the Pan-American Highway serve extraction industry suppliers and logistics operators with limited media alternatives.
- Smart city infrastructure convergence:Santiago's integrated sensor and display pilot programs create data-rich environments where DOOH integrates with municipal information systems.
- Automotive test-drive activation zones:Premium commercial districts in Las Condes and Vitacura offer experiential formats combining static presence with digital engagement triggers.
Industry Challenges
- Programmatic technical talent scarcity:The shortage of data science and ad-tech engineering skills in Chilean media agencies constrains dynamic campaign execution and real-time optimization.
- Legacy static contract renegotiation:Long-term billboard lease structures resist conversion to flexible digital terms, complicating portfolio transformation for established operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile OOH and DOOH Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Billboards, Transit Ads, Street Furniture, Digital Displays End User: Retailers, Automotive, Food & Beverage, Telecommunications Deployment Type: Static, Digital, Programmatic, Hybrid Campaign Duration: Short-term, Seasonal, Long-term, Event-based |
| Companies Covered | Clear Channel Chile, JCDecaux Chile, Viva Outdoor, Vistar Media, Hivestack, OOH Group, Taggify, Lamar Media Corp, Dentsu Creative Chile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile OOH and DOOH Market Trends and Innovations
Data-enabled audience targeting and dynamic content adaptation are compressing the traditional planning cycle, forcing infrastructure investment toward impression-verified inventory and away from location-based assumptions.
Programmatic DOOH platforms are electrifying campaign deployment by enabling real-time bidding on Santiago transit screen impressions. Retail and automotive advertisers now activate creative variations based on traffic density and weather triggers. This capability is compressing the gap between digital and physical media planning cycles.
Chile's Undersecretariat of Telecommunications emissions framework is tightening digital screen brightness and energy consumption thresholds. Operators face retrofit costs or replacement timelines for non-compliant LED installations. Transit network concessions in Santiago's Metro system are responding with hardware upgrade clauses in renewal negotiations.
Buyer concentration among Santiago-based retail conglomerates is consolidating negotiation leverage with national media agencies. Direct advertiser relationships are displacing traditional insertion-order workflows in premium commercial district inventory. This pattern concentrates most visibly in automotive launch campaigns targeting Las Condes and Providencia corridors.
Chile OOH and DOOH Market Segmentation
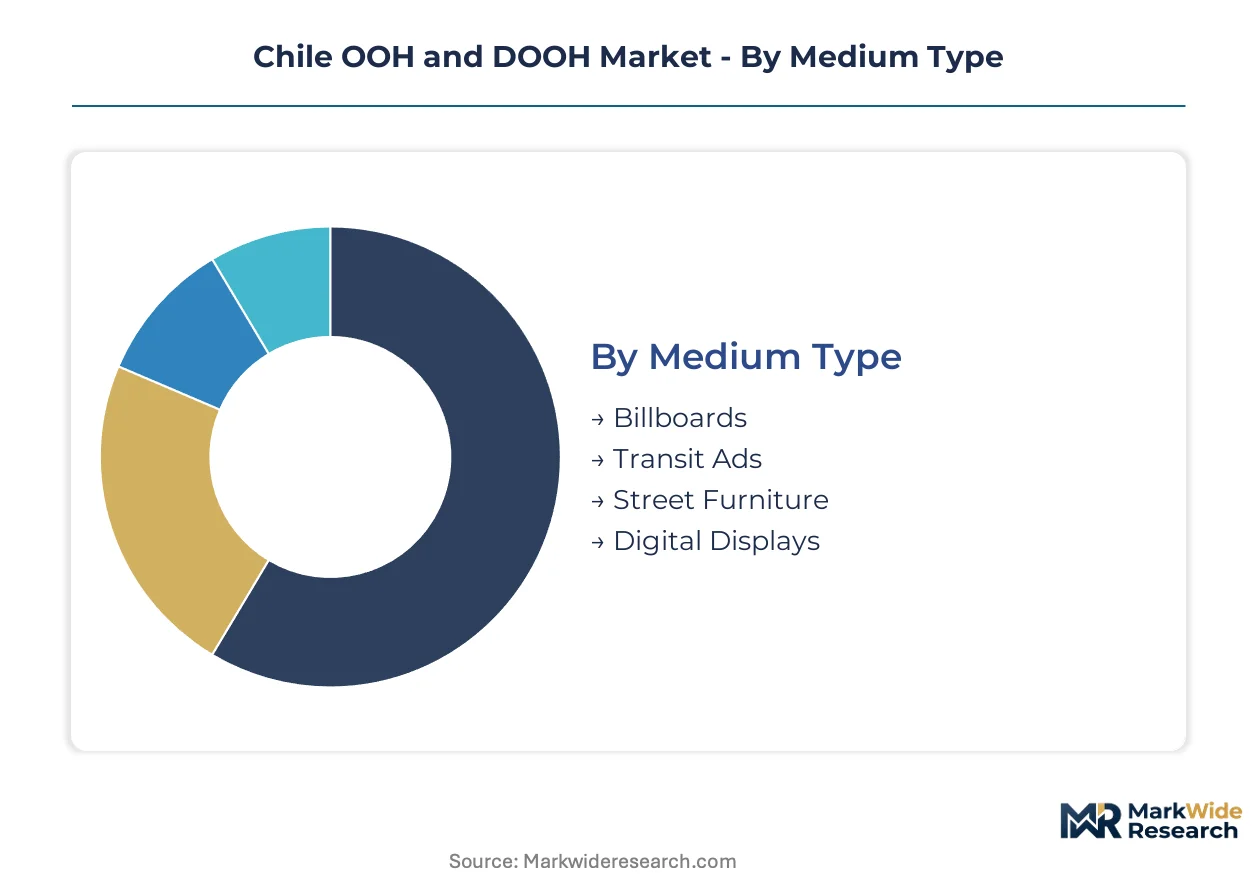
Chile's OOH and DOOH segmentation reflects divergent regulatory burdens across physical formats and trading mechanisms. Municipal codes and telecommunications emissions standards create tiered compliance costs that reshape operator portfolio economics and advertiser channel selection.
Medium Type:
Billboards and digital displays carry distinct certification pathways through Chile's Undersecretariat of Telecommunications brightness standards and municipal installation permits, while transit and street furniture formats navigate concession-based exclusivity agreements.
- Billboards:Large-format vinyl and printed structures positioned along highways and urban corridors. Retailers and automotive brands concentrate spend across Santiago's Pan-American Highway access routes and Las Condes commercial districts, where long-term lease structures favor established operators with municipal relationships.
- Digital Displays:LED and LCD screens enabling dynamic content rotation and programmatic trading. Santiago's Metro corridors and Vitacura premium zones drive demand from telecommunications advertisers seeking real-time audience measurement, though hardware import dependencies and emissions compliance raise operational barriers.
- Transit Ads:Interior and exterior placements across Metro Santiago, bus networks, and commuter rail. Captive commuter environments attract automotive and telecommunications spend, with concession renewals increasingly mandating hardware upgrade clauses.
- Street Furniture:Bus shelters, kiosks, and urban information panels deployed through exclusive municipal partnerships. Valparaíso and Concepción premium zones remain locked under single-operator contracts, blocking competitive entry despite advertiser demand concentration.
Billboards sit at the top of the volume ranking, with digital displays climbing the fastest.
End User:
Buyer concentration patterns vary sharply across retail conglomerates, automotive manufacturers, and telecommunications operators, each deploying distinct campaign architectures and negotiating leverage.
- Retailers:Santiago-based department stores and supermarket chains deploy programmatic DOOH for promotional activation across metropolitan transit hubs. Dynamic creative optimization enables real-time inventory messaging tied to store proximity.
- Automotive:Manufacturers and dealership networks concentrate spend in Las Condes and Providencia corridors for launch campaigns, combining static billboards with experiential test-drive activation zones. Long-term lease commitments in premium districts lock out challenger brands.
- Food & Beverage:Quick-service restaurants and beverage brands target commuter corridors and event-based placements around Santiago's entertainment districts. Seasonal demand spikes align with summer consumption patterns and festival calendars.
- Telecommunications:Mobile operators and internet service providers prioritize digital displays in Metro Santiago for plan promotion and network coverage messaging. Real-time bidding capabilities enable competitive response to rival campaign activations.
Retailers dominate current inventory commitment levels, while telecommunications advertisers are gaining share fastest through programmatic infrastructure adoption.
Deployment Type:
Technical architecture and trading mechanisms segment the market across legacy static installations and data-enabled dynamic systems, with hybrid formats emerging as a transitional category.
- Static:Fixed vinyl and printed materials with predetermined display periods. Lower operational complexity and established regulatory pathways sustain volume leadership, though contract renegotiation friction complicates portfolio transformation for incumbent operators.
- Digital:Network-connected screens with scheduled content rotation. Santiago's smart city pilot programs create integration opportunities with municipal information systems, though LED hardware import concentration exposes operators to currency and shipping volatility.
- Programmatic:Real-time impression-based trading with audience measurement and dynamic creative optimization. Data science talent scarcity in Chilean media agencies constrains execution capabilities despite advertiser demand compression of planning cycles.
- Hybrid:Combined static-digital installations enabling physical presence with digital engagement triggers. Premium commercial districts in Vitacura test experiential formats bridging awareness and performance marketing objectives.
Static deployment retains the largest revenue base, with programmatic trading expanding most quickly.
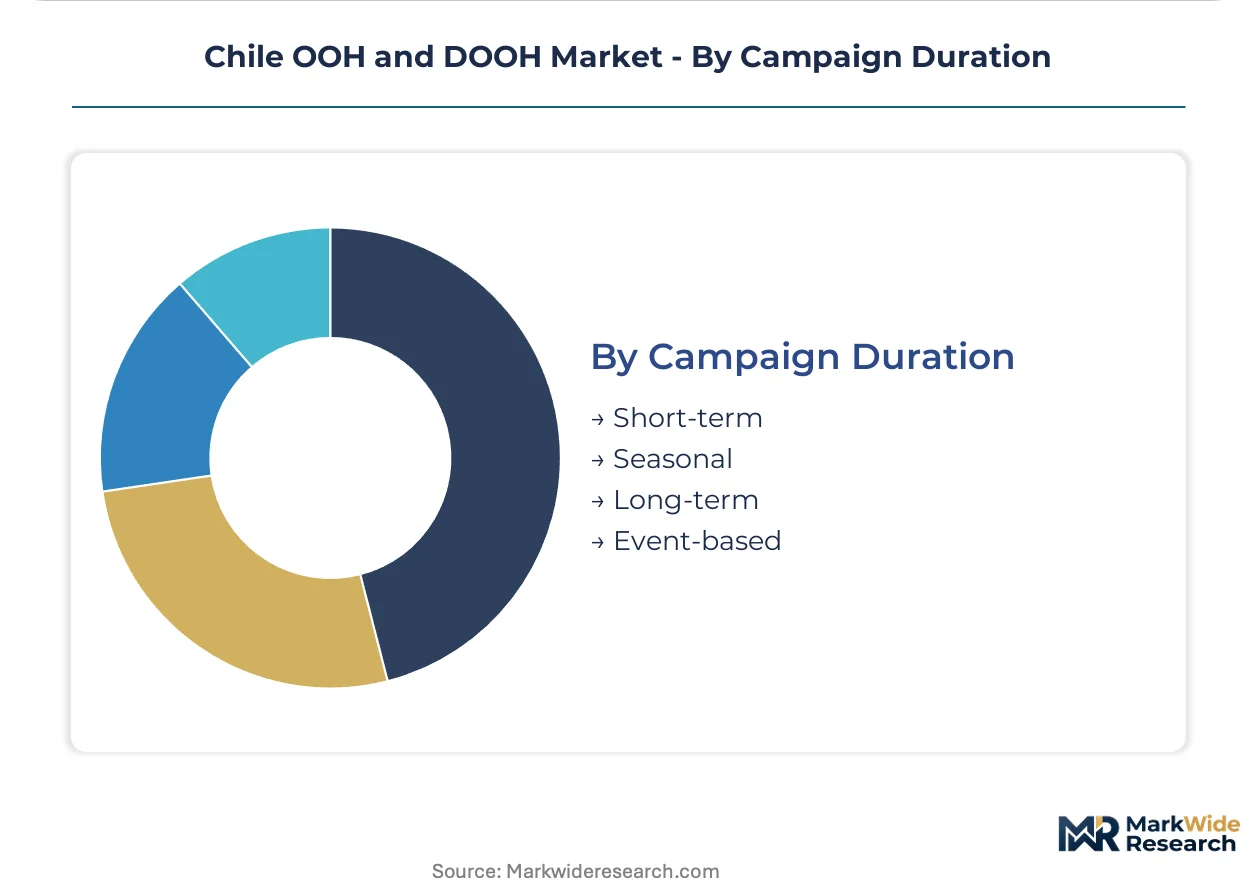
Campaign Duration:
Planning cycle compression and inventory flexibility requirements segment advertiser commitment structures across tactical activation and sustained presence strategies.
- Short-term:Burst campaigns spanning days to weeks for product launches and promotional windows. Programmatic infrastructure enables rapid deployment without traditional insertion-order workflows.
- Seasonal:Quarterly alignments with retail calendars, agricultural cycles, and summer tourism peaks. Mining corridor suppliers activate during extraction industry high-activity periods.
- Long-term:Annual or multi-year commitments securing premium inventory positions. Automotive and retail conglomerates leverage negotiation scale for rate advantages in Santiago's most trafficked corridors.
- Event-based:Activations tied to sports fixtures, concerts, and municipal festivals. Limited inventory availability and premium pricing characterize Santiago's major entertainment venues.
Long-term contracts anchor operator revenue stability, with short-term activation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's advertising workforce concentrates in Santiago's metropolitan agencies, with specialized talent pools in programmatic trading and digital creative production anchoring national deployment decisions.
Santiago Metropolitan Region
Transit corridor upgrades across Metro Santiago and the Pan-American Highway access routes concentrate advertiser spend from automotive and telecommunications brands. The Undersecretariat of Telecommunications enforces digital screen brightness thresholds and energy consumption standards that shape hardware procurement timelines. Las Condes and Providencia commercial districts host premium inventory where retail conglomerates negotiate long-term lease commitments.
Valparaíso Region
Port logistics and tourism flows create demand for billboard networks serving mining suppliers and international shipping operators. Municipal advertising codes in Valparaíso and Viña del Mar maintain exclusive street furniture concessions that block competitive entry despite concentrated advertiser interest. The region's coastal highway corridors remain underdeveloped relative to Santiago for digital display deployment.
Biobío Region
Concepción's industrial base sustains static billboard demand from manufacturing and agricultural equipment marketers. Local municipality frameworks govern installation permits with varying digitization readiness across constituent communes. The regional capital's commercial districts lag Santiago in programmatic infrastructure adoption.
Antofagasta Region
Mining corridor access routes along the Pan-American Highway generate specialized billboard demand from extraction industry suppliers and logistics operators. Limited media alternatives in northern Chile create pricing premiums for inventory positioned near Calama and Antofagasta city entries. Municipal permitting remains less codified for digital screens compared to Santiago's established frameworks.
Chile OOH and DOOH Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Chile's OOH and DOOH infrastructure. The market structure consolidates around three dominant operators holding transit concessions and municipal exclusivity agreements, while programmatic technology providers fragment the trading layer. Two strategic archetypes prevail: legacy infrastructure owners with concession-based moats, and ad-tech platforms enabling impression-based inventory access. Competitive moves center on hardware upgrade clauses in concession renewals and programmatic partnership formations with retail advertisers.
Among infrastructure-owning incumbents, Clear Channel Chile and JCDecaux Chile exemplify the concession-dependent archetype, leveraging exclusive municipal partnerships and transit network control. Viva Outdoor occupies a specialized position along highway corridors where mining and logistics demand concentrates. These three entities anchor the physical inventory layer while programmatic platforms including Vistar Media and Hivestack represent the data-enabled trading tier that is compressing traditional planning cycles.
| Leading Market Players |
|---|
| Clear Channel Chile |
| JCDecaux Chile |
| Viva Outdoor |
| Vistar Media |
| Hivestack |
| OOH Group |
| Taggify |
| Lamar Media Corp |
| Dentsu Creative Chile |
| Others |
Pricing and Supply Chain Analysis
Chile's Undersecretariat of Telecommunications emissions standards for LED brightness and energy consumption gate qualified hardware supply and premium-tier pricing access. Operators meeting these thresholds command rate premiums in Santiago's Metro corridors and Las Condes commercial districts, while non-compliant inventory faces retrofit costs or displacement to secondary markets.
Pricing Analysis
Bundled service packages combining hardware installation, content management, and programmatic trading access separate from unbundled screen-only leases. Three-tier pricing structure across premium, standard, and economy levels reflects location traffic density, screen resolution specifications, and data-enabled audience measurement capabilities. Price differentiation hinges on concession exclusivity in transit corridors versus competitive highway corridors. Cost compression in standard-tier highway inventory is intensifying because mining corridor demand concentrates among limited suppliers. Telecommunications advertisers show least price sensitivity for impression-verified Metro placements, while regional retail chains negotiate aggressively on peripheral digital screens.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs to Valparaíso and San Antonio ports shapes total landed cost for LED display panels. Hardware sourcing concentrates in China, South Korea, and Taiwan for high-lumen outdoor-rated screens. Component dependencies span driver ICs from Taiwanese semiconductor foundries, aluminum framing from Chinese extrusion plants, and power management systems from South Korean suppliers. Single-source vulnerability in specialized outdoor brightness calibration creates procurement risk for operators scaling Santiago networks. Distribution runs through bonded warehouse arrangements in Santiago's Pudahuel logistics cluster before final-mile installation deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's OOH and DOOH market represents a late-cycle quality story as advertiser demand shifts toward impression-verified programmatic inventory with real-time audience measurement capabilities. This specification premium favors operators with data infrastructure and concession security.
For Market Incumbents: To counter programmatic talent scarcity constraining campaign execution, Clear Channel Chile and JCDecaux Chile should anchor defensive positioning through hardware upgrade clauses in Metro Santiago concession renewals and captive data science partnerships with Santiago-based retail conglomerates. Securing exclusive municipal digitization pilots in Valparaíso and Concepción extends concession moats against highway-focused competitors. For New Entrants and Emerging Players: Programmatic trading platforms without physical inventory represent the most penetrable wedge for technology-first market entry. White-space targets include northern mining corridor billboard networks along the Pan-American Highway where Viva Outdoor's specialized positioning leaves digital display gaps, and Concepción's industrial districts where programmatic infrastructure lags Santiago. A direct advertiser relationship model bypassing traditional agency insertion-order workflows accelerates initial traction. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid static-digital operators with legacy lease portfolios requiring conversion capital. Long-term viability across the projection horizon depends on concession renewal timelines and municipal digitization policy alignment. Acquisition target archetypes include regional billboard networks in Antofagasta and Biobío with undeveloped digital potential. The signal to watch is Undersecretariat of Telecommunications emissions standard enforcement tightening, which would accelerate replacement demand and consolidate pricing power among compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal with Hardware Upgrade Clauses | Metro Santiago operators secure digital transition pathways against municipal emissions compliance deadlines. |
| Programmatic Platform Partnership Formation | Retail advertisers gain impression-based trading access compressing planning cycles versus static insertion orders. |
| Northern Mining Corridor Network Expansion | Pan-American Highway access routes capture extraction industry supplier spend with limited media alternatives. |
| Smart City Infrastructure Integration Pilot | Santiago's sensor-display convergence creates data-rich environments linking DOOH to municipal information systems. |
| Specialized Digital Emissions Compliance Service | Technical consultancy offerings address operator retrofit needs under Undersecretariat of Telecommunications brightness thresholds. |
Research Methodology
Multiple input streams — primary interviews with media agency trading directors, OOH operator network managers, and municipal permitting officials; secondary validation through Undersecretariat of Telecommunications regulatory filings, Metro Santiago concession documents, and Chilean customs import data for LED display components — were reconciled through bottom-up inventory counting and top-down advertiser spend estimation. Stakeholder consultations spanned Santiago-based retail conglomerate marketing executives, automotive brand media planners, and programmatic technology platform engineers. Secondary sources included municipal advertising code revisions, transit authority infrastructure upgrade announcements, and trade flow records for display hardware.
Historical deployment data cross-referenced against panel-based industry expert input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include medium type, end-user industry, deployment architecture, and regional corridor tier. CAGRs were derived from installed base growth trajectories, advertiser budget reallocation patterns from static to digital formats, and concession renewal timelines. Industry-specific forecast inputs incorporated municipal digitization policy momentum in Santiago and Valparaíso, plus LED hardware cost curves from Asian manufacturing capacity expansion.
The model holds under stable regulatory enforcement and continued transit infrastructure investment; deviation in municipal exclusivity fragmentation or emissions standard acceleration would shift deployment economics and operator consolidation patterns. Forecasts reflect assumptions about programmatic adoption velocity and hardware import cost stability. Stakeholders should weight assumptions against their own operating context and concession renewal schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Global Print Advertising Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
North America Public Relation Services Market