
 Digital Out of Home (OOH) Advertising Market | 2026-2036
Digital Out of Home (OOH) Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Out of Home (OOH) Advertising Market Outlook
Retail advertisers are unwinding traditional media commitments as transit authorities and municipal buyers expand programmatic digital placements. JCDecaux leverages its street furniture dominance across European capitals to control premium inventory. Lamar Advertising Company anchors rural and interstate billboard conversions with aggressive LED retrofit programs. Clear Channel Outdoor Holdings Inc. competes through airport and transit authority partnerships that lock in multi-year digital concessions.
Digital Out of Home (OOH) Advertising comprises networked electronic display systems—typically LED modules with pixel pitches ranging from 3mm to 16mm, LCD panels, or projection mapping rigs—programmed remotely via content management platforms to deliver time-targeted messaging in public spaces. These installations serve commercial purposes by capturing audience attention during dwell-time intervals in high-footfall environments, with programmatic buying now enabling real-time auction-based ad serving. Digital Billboards command the largest revenue pool due to highway and urban premium positioning, while Transit Displays represent the fastest-expanding segment as rail and bus networks replace static panels with connected screens. Kiosks concentrate margin in retail and wayfinding applications where interactive touch layers extend dwell metrics.
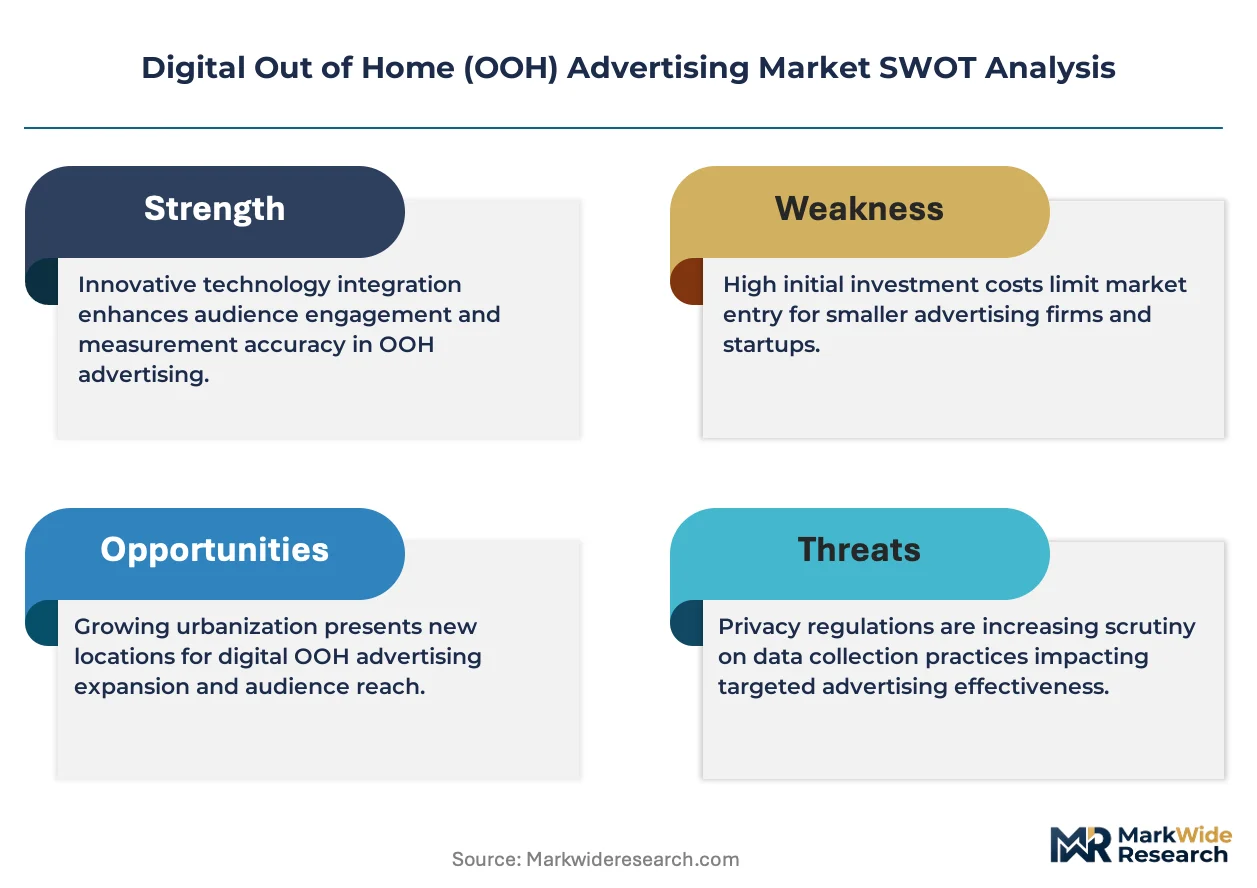
The FCC governs electronic display brightness and electromagnetic emissions in the United States, while GDPR and the EU AI Act constrain facial recognition and audience analytics deployment across European networks. These frameworks shape demand by forcing vendors toward privacy-preserving computer vision and aggregated mobility data rather than individual tracking. Stakeholders must monitor how municipal zoning boards and data protection authorities coordinate permitting timelines with technology refresh cycles.
Market Dynamics
Programmatic buying platforms are compressing sales cycles and collapsing the premium that static inventory once commanded, forcing asset owners to restructure yield management around real-time auction mechanics.
Growth Catalysts
- GDPR Privacy Frameworks:European data governance rules are accelerating investment in aggregated mobility analytics and privacy-preserving computer vision, creating compliant audience measurement tools that transit authorities now mandate.
- LED Retrofit Programs:Highway authorities across multiple jurisdictions are replacing static billboards with networked digital displays, unlocking dynamic scheduling and multi-advertiser rotation.
- Retail Corridor Density:Urban shopping districts in the United States are driving screen installation rates as property managers seek ancillary revenue from digital facade leasing.
Market Restraints
- Input Cost Volatility:Semiconductor shortages and gallium nitride price swings are inflating LED module costs and extending procurement timelines for network operators.
- Supply Concentration Risk:Display driver IC fabrication concentrates in East Asian foundries, exposing buyers to geopolitical disruption and concentrated supplier leverage.
- FCC Brightness Limits:Federal electromagnetic emission caps constrain peak luminosity specifications, limiting competitive differentiation on visibility metrics.
Strategic Opportunities
- India Transit Modernization:Metro rail expansions in Mumbai, Delhi, and Bangalore are creating greenfield digital concession opportunities with 15-20 year lease structures.
- 5G-Edge Convergence:Low-latency connectivity and distributed compute are enabling interactive kiosk experiences and real-time creative optimization previously impossible on cellular backhaul.
- EU Green Deal Procurement:Carbon disclosure mandates for public infrastructure are favoring energy-efficient LED retrofits and renewable-powered screen networks in municipal tenders.
Industry Challenges
- Technical Talent Scarcity:Programmatic ad operations and data science skill shortages are constraining network monetization and yield optimization capabilities.
- Legacy CMS Integration:Proprietary content management systems from static-era vendors are fragmenting network interoperability and inflating migration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Out of Home (OOH) Advertising Market |
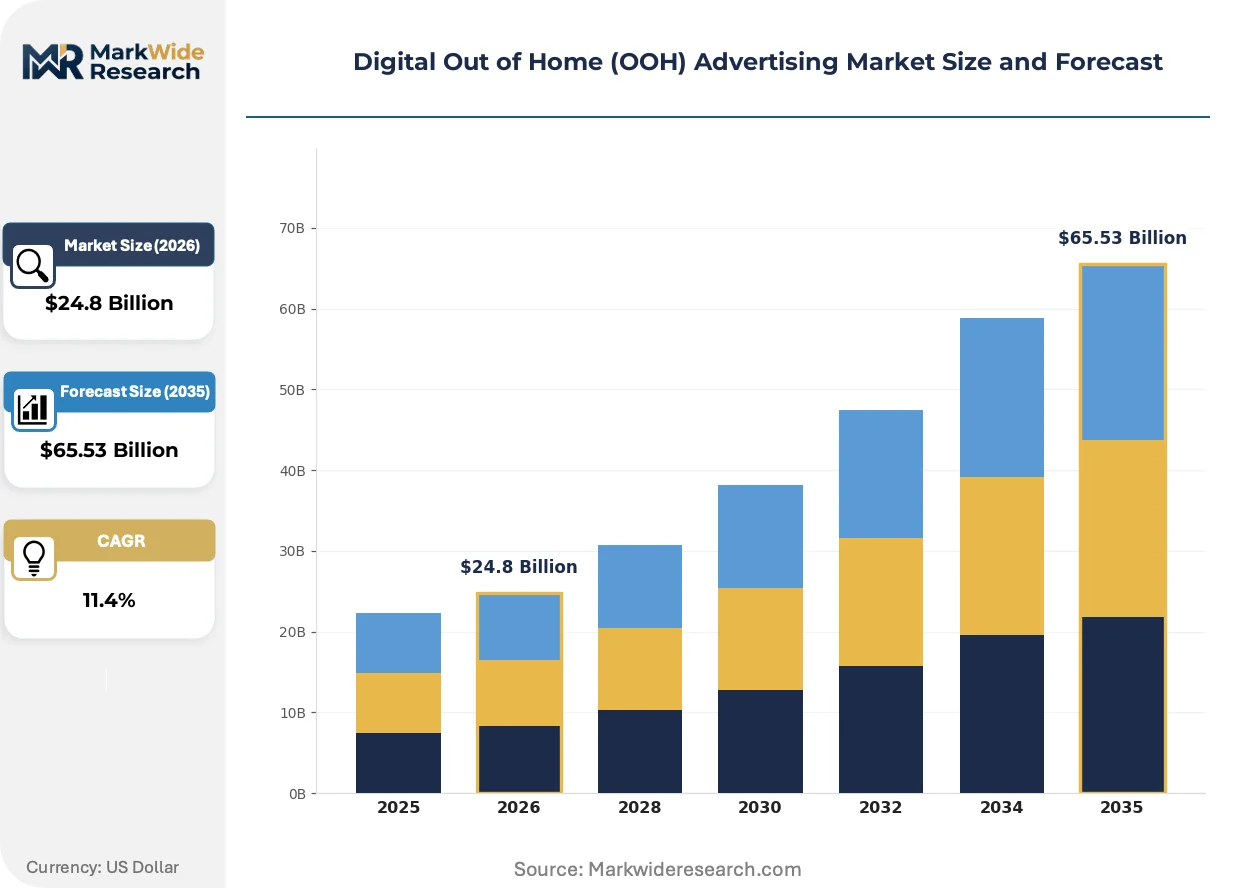
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format Type: Digital Billboards, Kiosks, Screens, Transit Displays Application: Retail Advertising, Event Promotion, Transportation, Sports Marketing Technology: LED, LCD, Projection, Digital Signage Target Audience: General Public, Commuters, Tourists, Event Attendees |
| Companies Covered | Clear Channel Outdoor Holdings Inc., JCDecaux, Outfront Media Inc., Lamar Advertising Company, Stroer, oOh!media Limited, APG|SGA, Global Media, Broadsign International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Out of Home (OOH) Advertising Market Strategic Shifts
Real-time data feeds and automated creative adaptation are dissolving the boundary between digital out-of-home and mobile advertising, creating synchronized cross-screen campaigns that respond to environmental triggers.
Computer vision systems with on-device processing are supplanting camera-based facial recognition for audience analytics. Transit authorities in Germany and France are deploying these edge-computing sensors to measure dwell time and demographic composition without transmitting biometric data. The structural consequence is that GDPR-compliant verification is now opening inventory to privacy-sensitive advertisers previously blocked from programmatic OOH.
REACH chemical restrictions on heavy metals in electronics are forcing display manufacturers to reformulate solder and phosphor compositions. Industrial consequence includes extended certification timelines and redesign costs for European-bound LED modules. Outdoor network operators in the Netherlands and Sweden are responding by consolidating procurement around pre-certified component suppliers with established compliance documentation.
Buyer contracting is compressing from annual upfront commitments to impression-guaranteed programmatic deals with weekly cancellation windows. Media agencies are displacing traditional direct sales teams as the primary inventory access point, particularly for digital billboard networks in the United States. This behavioral shift is most visible in Chicago and Los Angeles, where transit authority concessions now require API-enabled demand-side platform connectivity as a bid qualification.
Digital Out of Home (OOH) Advertising Market Segmentation
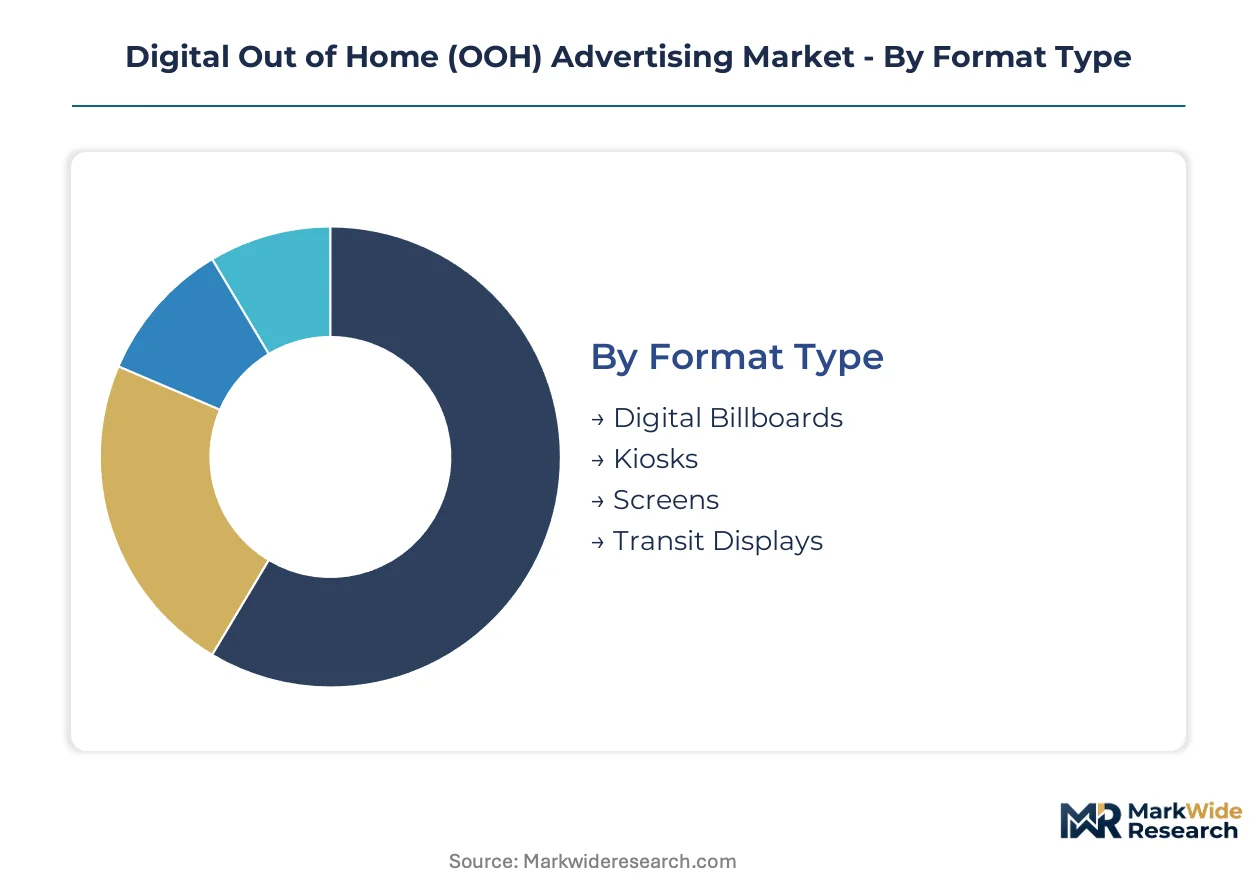
Format fragmentation determines competitive intensity across the Digital Out of Home (OOH) Advertising Market, with legacy static infrastructure facing substitution pressure from networked digital alternatives. Understanding segment boundaries clarifies where procurement budgets are migrating and which technology stacks command premium positioning.
Format Type:
Digital Billboards face the most acute substitution threat from programmatic trading platforms that collapse the yield premium static inventory once commanded.
- Digital Billboards:Large-format LED arrays with pixel pitches from 6mm to 16mm dominate highway and urban premium positioning. Highway authorities in the United States and Germany are unwinding static contracts in favor of multi-advertiser rotation systems that unlock dynamic scheduling.
- Transit Displays:Networked screens deployed across rail platforms, bus shelters, and vehicle interiors represent the steepest expansion curve. Metro rail expansions in Mumbai, Delhi, and Bangalore are creating greenfield concession opportunities with 15-20 year lease structures.
- Kiosks:Interactive touch-enabled installations concentrate in retail corridors and wayfinding applications where dwell-time metrics extend advertiser value.
- Screens:General-purpose digital panels in shopping malls, airports, and entertainment venues serve ambient advertising with lower production values than purpose-built billboards.
Digital Billboards retain volume leadership; Transit Displays hold the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency retail commitments from episodic event spending that fluctuates with macroeconomic cycles.
- Retail Advertising:Sustained brand presence in shopping districts drives recurring revenue pools. Urban retail corridors in Chicago and Los Angeles are accelerating screen density as property managers seek ancillary revenue from digital facade leasing.
- Transportation:Transit authority concessions lock in multi-year digital placements with API-enabled demand-side platform connectivity now mandatory for bid qualification. FCC brightness limits constrain peak luminosity specifications for roadside visibility.
- Event Promotion:Temporary installations for concerts, festivals, and sporting events command premium day-rates with compressed sales cycles.
- Sports Marketing:Stadium and arena deployments integrate with broadcast feeds to synchronize in-venue messaging with televised coverage.
Retail Advertising captures the largest revenue commitment; Transportation delivers the most predictable contract tenor.
Technology:
Supply concentration in East Asian foundries exposes procurement timelines to geopolitical disruption and concentrated supplier leverage.
- LED:Gallium nitride-based modules with driver IC fabrication concentrated in Taiwan and South Korea dominate outdoor applications. REACH chemical restrictions on heavy metals are forcing European-bound manufacturers to reformulate solder and phosphor compositions.
- LCD:Indoor-focused panels with lower brightness ceilings serve controlled-environment retail and corporate installations where ambient light management is feasible.
- Projection:Mapping rigs enable temporary architectural transformations for experiential campaigns with limited permanence requirements.
- Digital Signage:Software-agnostic display hardware integrates with proprietary and open content management platforms.
LED commands outdoor infrastructure investment; LCD maintains cost advantages in climate-controlled deployments.
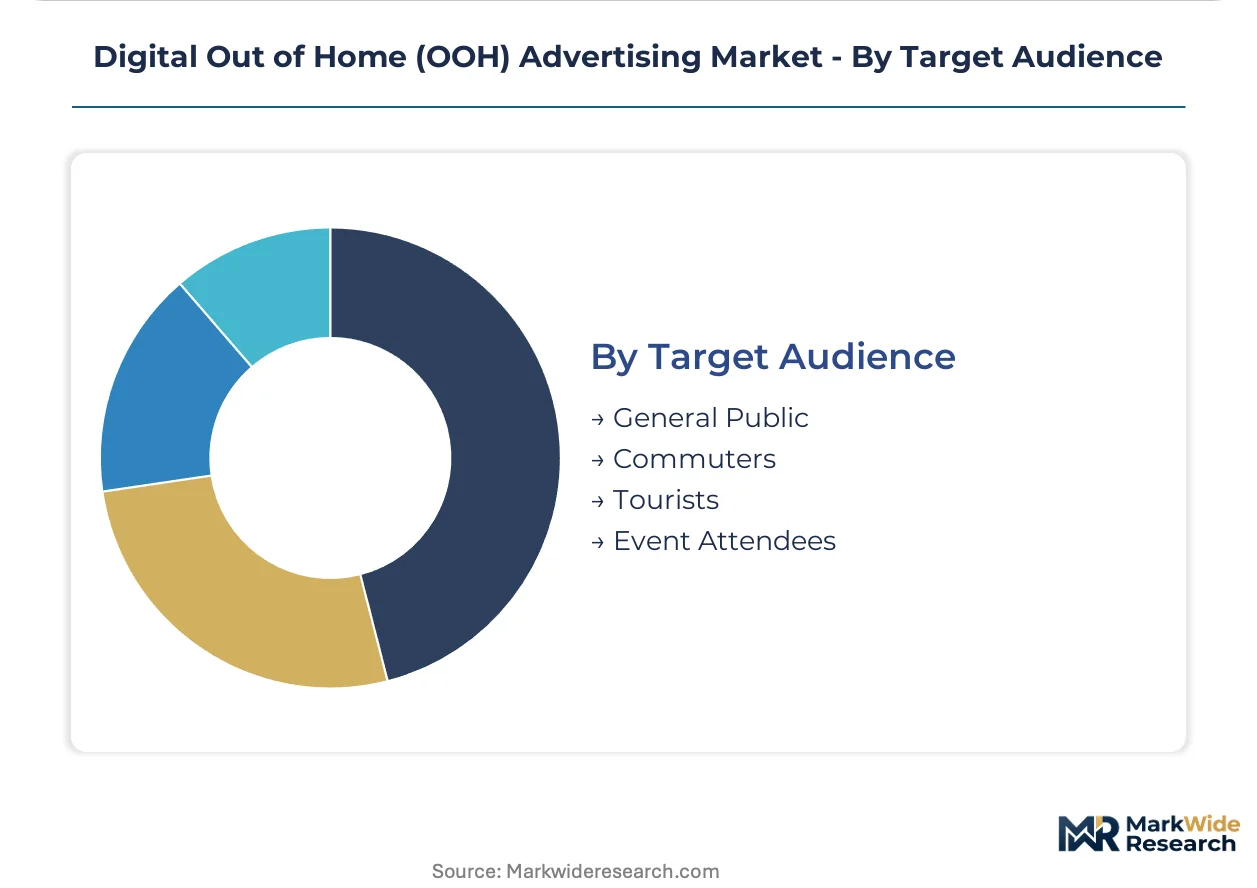
Target Audience:
Audience mobility patterns determine measurement methodology, with GDPR and EU AI Act constraints favoring aggregated mobility analytics over individual tracking.
- Commuters:Predictable daily route patterns enable daypart targeting with verified dwell-time metrics. Transit authorities in Germany and France are deploying edge-computing sensors to measure demographic composition without transmitting biometric data.
- General Public:Broad-reach campaigns in high-footfall environments prioritize impression volume over precision targeting.
- Tourists:Seasonal concentration in gateway cities creates inventory scarcity during peak travel windows.
- Event Attendees:Cohort-specific messaging responds to real-time crowd density and sentiment triggers.
Commuters enable the most granular attribution; General Public delivers the widest reach efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display driver IC fabrication concentrates in Taiwan and South Korea, exposing network operators to geopolitical disruption and concentrated supplier leverage. LED module assembly clusters in Shenzhen and Dongguan feed deployment pipelines across North America and Europe. Municipal zoning boards in transit-dense cities coordinate permitting timelines with technology refresh cycles.
United States
Urban transit hubs in Chicago and Los Angeles drive screen density as property managers seek ancillary revenue from digital facade leasing. FCC brightness limits and electromagnetic emission caps constrain peak luminosity specifications for roadside visibility. Lamar Advertising Company anchors rural and interstate billboard conversions with aggressive LED retrofit programs across Texas and the Southeast.
Germany
REACH chemical restrictions on heavy metals force display manufacturers to reformulate solder and phosphor compositions for European-bound LED modules. Transit authorities in Berlin and Munich deploy edge-computing sensors to measure dwell time without transmitting biometric data under GDPR constraints. Stroer leverages street furniture dominance across Hamburg and Frankfurt to control premium inventory.
France
CNIL oversight and the EU AI Act constrain facial recognition deployment across Paris and Lyon transit networks. JCDecaux maintains street furniture concessions in European capitals with multi-year digital placements. The Île-de-France region accelerates metro rail screen installation as rail networks replace static panels with connected displays.
India
Metro rail expansions in Mumbai, Delhi, and Bangalore create greenfield digital concession opportunities with 15-20 year lease structures. TRAI spectrum allocation for 5G-edge convergence enables interactive kiosk experiences previously impossible on cellular backhaul. Maharashtra and Karnataka state authorities unwind legacy static contracts in favor of programmatic digital placements.
United Kingdom
GDPR-compliant verification opens inventory to privacy-sensitive advertisers previously blocked from programmatic OOH in London and Manchester. Outfront Media Inc. competes through transit authority partnerships that lock in multi-year digital concessions. The Greater London Authority mandates API-enabled demand-side platform connectivity as a bid qualification for new concessions.
Digital Out of Home (OOH) Advertising Market Competitive Environment
Concentration sits with diversified outdoor media conglomerates controlling street furniture and transit authority concessions across multiple jurisdictions. Tiered competition separates global scale operators from regional specialists and technology enablers. Two dominant competitive moves reshape positioning: M&A activity consolidating concession portfolios and strategic partnerships locking 5G-edge infrastructure into transit modernization programs.
Among diversified outdoor media conglomerates, Clear Channel Outdoor Holdings Inc., JCDecaux, and Lamar Advertising Company exemplify scale-driven concession control. Clear Channel Outdoor Holdings Inc. occupies a position anchored in airport and transit authority partnerships. JCDecaux represents the street furniture archetype across European capitals. Lamar Advertising Company sits within the rural-interstate conversion tier with LED retrofit specialization. Technology enablers like Broadsign International LLC occupy a distinct layer providing content management platforms without direct inventory ownership.
| Leading Market Players |
|---|
| Clear Channel Outdoor Holdings Inc. |
| JCDecaux |
| Outfront Media Inc. |
| Lamar Advertising Company |
| Stroer |
| oOh!media Limited |
| APG|SGA |
| Global Media |
| Broadsign International LLC |
| Others |
Value Chain & Pricing Dynamics
REACH chemical restrictions on heavy metals in electronics simultaneously gate supplier qualification for European-bound LED modules and enforce price stratification between certified and non-certified component tiers, compressing margins for manufacturers lacking pre-established compliance documentation while rewarding consolidated procurement around pre-certified suppliers.
Pricing Analysis
FCC brightness limits and electromagnetic emission caps dictate the pricing tier structure across roadside digital billboard deployments in the United States. Pricing stratifies across premium, standard, and economy tiers based on peak luminosity specifications and certification grade, with highway authorities in Texas and the Southeast exhibiting highest price sensitivity due to aggressive LED retrofit program budgets. Cost compression in the standard tier is intensifying because semiconductor shortages and gallium nitride price swings are inflating LED module procurement timelines.
Supply Chain Analysis
Strategic stockpiling of display driver ICs dominates inventory strategy as network operators buffer against fabrication concentration risks. Supply draws from Taiwan, South Korea, and Shenzhen-Dongguan assembly clusters for LED modules, with gallium nitride substrates and phosphor compositions representing critical input dependencies. Single-source vulnerability in East Asian foundries exposes buyers to geopolitical disruption, while distribution runs through direct OEM relationships with transit authorities and municipal procurement boards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Programmatic buying penetration in transit and retail corridors remains below saturation thresholds, with 5G-edge convergence enabling interactive kiosk experiences that expand addressable inventory beyond static replacement cycles.
For Market Incumbents: Consolidate concession portfolios through targeted acquisitions of regional transit authority contracts in Mumbai, Delhi, and Bangalore where metro rail expansions create greenfield digital opportunities. Lock in multi-year API-enabled demand-side platform connectivity as a bid qualification standard to defend against technology enablers lacking direct inventory ownership. Prioritize backward integration into display driver IC sourcing to mitigate Taiwan and South Korea concentration risk.
For New Entrants and Emerging Players: Differentiate on privacy-preserving computer vision capabilities that satisfy GDPR and EU AI Act constraints without transmitting biometric data. Target Germany and France transit authority deployments where edge-computing sensors are displacing camera-based facial recognition. Pursue white-space opportunities in India's 15-20 year lease structures through partnerships with Maharashtra and Karnataka state authorities unwinding legacy static contracts.
For Investors and Strategic Acquirers: The EU Green Deal's carbon disclosure mandates for public infrastructure reshape the acquisition landscape toward energy-efficient LED retrofit specialists with established compliance documentation. Long-term viability centers on concession holders with embedded 5G-edge infrastructure in transit modernization programs. The signal to monitor is municipal tender requirements for API-enabled demand-side platform connectivity as a mandatory bid qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Program Expansion | Highway authorities in Texas unlock dynamic scheduling through multi-advertiser rotation systems. |
| Privacy-Preserving Computer Vision Deployment | Transit authorities in Berlin and Munich measure dwell time without GDPR biometric data transmission. |
| 5G-Edge Infrastructure Partnership | TRAI spectrum allocation enables interactive kiosk experiences previously impossible on cellular backhaul. |
| Concession Portfolio Consolidation | Street furniture dominance across Hamburg and Frankfurt controls premium inventory positioning. |
| API-Enabled Demand-Side Platform Integration | Chicago and Los Angeles transit authorities mandate connectivity as bid qualification for new concessions. |
Study Parameters
A spread of perspectives from network operations directors, transit authority procurement managers, programmatic platform engineers, and municipal zoning officials converged on the working assumptions driving this analysis. Primary interviews with LED module manufacturers, content management platform providers, and media agency trading desks combined with secondary validation from FCC filings, ECHA REACH registration databases, SEC 10-K disclosures from listed outdoor media conglomerates, and TRAI spectrum allocation records. Bottom-up triangulation of concession lease values and top-down validation against aggregated mobility analytics expenditure produced convergent estimates.
Segmentation dimensions modeled include format type, application vertical, technology stack, and target audience mobility patterns across the projection horizon. CAGRs were derived from regression analysis of historical concession award values and projected screen density trajectories. Industry-specific forecast inputs incorporate LED retrofit program commitments from highway authorities and 5G-edge deployment timelines from telecom infrastructure disclosures.
Material uncertainties — semiconductor shortage duration, gallium nitride price volatility, and municipal permitting timeline coordination — sit outside the modeled envelope. Forecasts reflect assumptions about continued programmatic buying adoption and privacy-preserving measurement technology maturation. Revision becomes warranted when display driver IC fabrication concentration crosses geopolitical disruption thresholds or when FCC brightness limit enforcement intensifies beyond historical patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Japan OOH and DOOH Market