
 GCC Defense Market | 2026-2036
GCC Defense Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Defense Market Foresight
Government ministries as direct procurers is bifurcating from traditional foreign prime contracting toward domestic joint ventures and offset arrangements. Saudi Arabian Military Industries anchors indigenous production through licensed manufacturing and technology transfer agreements with European and American partners. EDGE Group PJSC competes across the full technology stack by consolidating advanced electronics, munitions, and platforms under one Emirati umbrella. Lockheed Martin Corporation navigates this shift through co-production frameworks and local workforce development commitments rather than pure export models.
GCC defense encompasses the design, development, production, and sustainment of military platforms and systems operating across land, air, sea, space, and cyber domains, with specifications typically requiring interoperability with NATO-standard communications architectures and thermal operating ranges exceeding 55 degrees Celsius. Combat aircraft and missile systems absorb the largest capital allocations due to unit costs and long sustainment tail requirements. Autonomous systems and artificial intelligence represent the fastest-expanding technology segments as Gulf militaries prioritize reduced personnel risk and persistent surveillance coverage. Drones within the product type category concentrate margin pools in sensor packages and encrypted datalinks rather than airframe fabrication.
Saudi Arabia's General Authority for Military Industries and the UAE's Tawazun Council shape demand through localization quotas, offset ratios, and sovereign content requirements that foreign suppliers must satisfy for contract eligibility. The UAE's EDGE Group operates under procurement preferences that steer technology transfer toward domestic entities. Stakeholders must monitor how GAMI's evolving supplier certification standards and Tawazun's investment mandates redistribute competitive advantage between established foreign primes and emerging local champions.
Market Dynamics
Sovereign wealth-backed localization mandates are redirecting procurement flows from foreign primes toward domestic joint ventures, forcing suppliers to restructure around GAMI certification standards and Tawazun investment requirements.
Growth Catalysts
- Saudi Vision 2030 localization mandates:GAMI's industrial city programs require foreign primes to establish domestic production facilities, transferring manufacturing know-how to Saudi entities.
- Autonomous systems proliferation:Gulf militaries prioritize unmanned platforms for persistent surveillance in extreme thermal conditions, accelerating sensor and encrypted datalink procurement.
- UAE EDGE Group consolidation:Twenty-five entities merged into a vertically integrated conglomerate capable of competing across electronics, munitions, and platform categories.
Market Restraints
- Technology transfer barriers:US ITAR regulations and European export controls restrict access to critical subsystems, forcing GCC manufacturers toward less advanced alternatives.
- Specialized workforce scarcity:Domestic engineering talent pools remain insufficient for precision manufacturing, aerospace systems integration, and cyber-physical security roles.
- Long platform development cycles:Combat aircraft and missile systems require decade-long investment horizons that strain sovereign balance sheets amid fiscal diversification pressures.
Strategic Opportunities
- Kuwait and Qatar defense modernization:Smaller GCC states lag Saudi Arabia and UAE in indigenous capacity, creating first-mover advantages for suppliers establishing local partnerships.
- Cyber-physical convergence:Integration of artificial intelligence with electronic warfare systems opens new product categories at the intersection of software and hardware.
- Offset arrangement restructuring:Tawazun Council's evolving investment mandates allow foreign primes to satisfy obligations through equity stakes in domestic technology ventures rather than traditional counter-trade.
Industry Challenges
- GAMI supplier certification complexity:Evolving standards for industrial security clearances and quality accreditation create timeline uncertainty for contract eligibility.
- Legacy system integration friction:NATO-standard communications architectures must interface with existing GCC military infrastructure, requiring costly interoperability engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Defense Market |
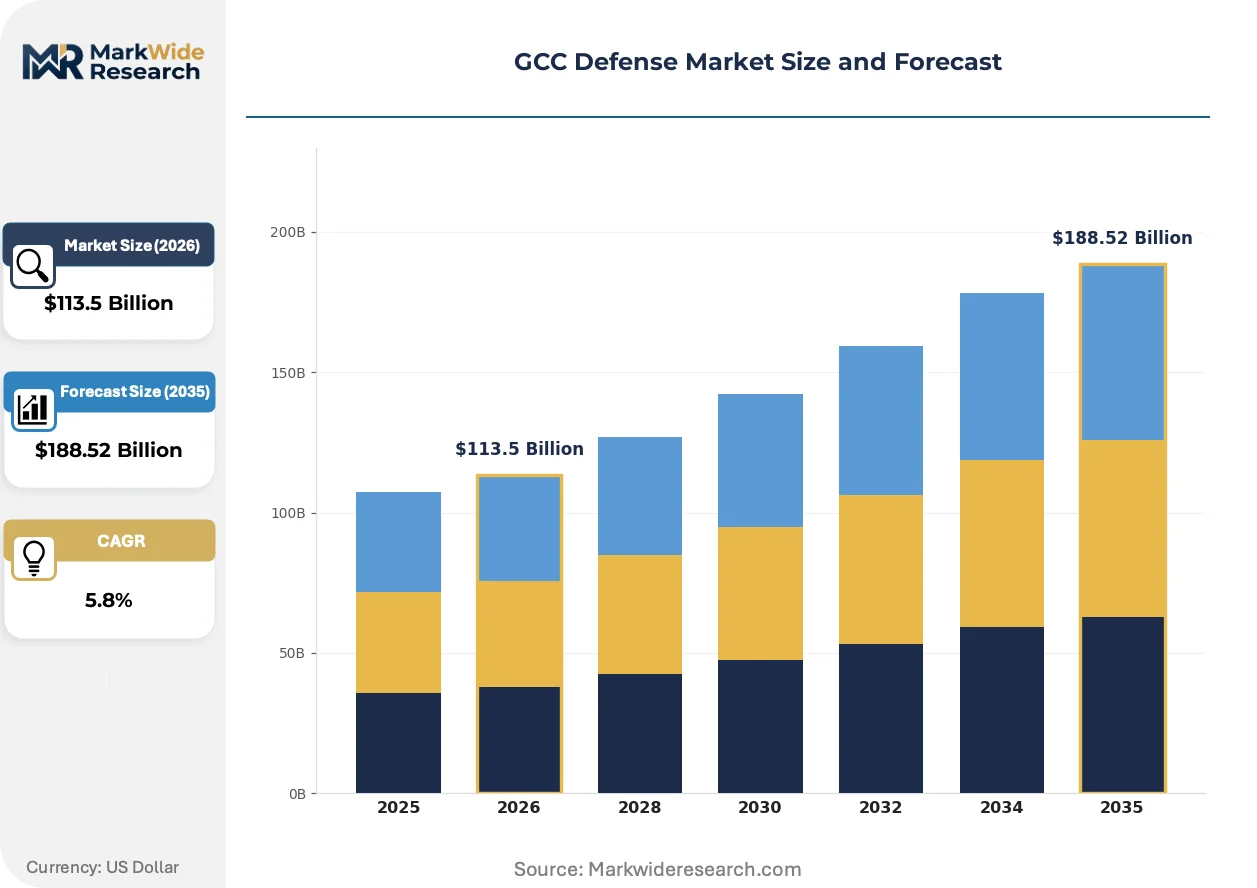
| Market Size in 2026 | $113.5 Billion |
| Market Size in 2035 | $188.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Armored Vehicles, Missile Systems, Radar Systems, Small Arms, Combat Aircraft, Drones Technology: Artificial Intelligence, Cybersecurity, Autonomous Systems, Satellite Communications, Electronic Warfare, Directed Energy Application: Border Security, Maritime Surveillance, Counterterrorism, Peacekeeping Operations, Strategic Deterrence, Emergency Response End User: Military Branches, Defense Contractors, Security Forces, Training Academies, Government Ministries, Intelligence Agencies |
| Companies Covered | Saudi Arabian Military Industries, Northrop Grumman Corporation, Lockheed Martin Corporation, BAE Systems PLC, Raytheon Company, The Boeing Company, EDGE Group PJSC, Leonardo SpA, Airbus SE, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Defense Market Shifts & Advancements
Defense procurement across the GCC is pivoting from platform acquisition toward capability-as-a-service models, with artificial intelligence and sovereign manufacturing requirements compressing traditional contracting timelines.
Autonomous swarm architectures are displacing single-platform procurement strategies. These distributed systems enable persistent area denial and surveillance coverage without risking personnel. Saudi and Emirati forces are field-testing coordinated drone formations for border security applications. The shift is displacing conventional manned aircraft orders in favor of modular, rapidly upgradeable unmanned fleets.
Saudi GAMI's evolving offset framework now mandates technology transfer thresholds for all contracts exceeding specified values. Foreign suppliers must establish joint ventures with Saudi entities and meet workforce localization quotas. Combat aircraft and missile system categories face the steepest compliance requirements, driving primes toward licensed manufacturing arrangements rather than direct export.
Defense ministries are unbundling sustainment contracts from initial platform purchases, creating separate competitive tenders for lifecycle support. This procurement model change fragments supplier relationships and opens aftermarket revenue to specialized maintenance providers. Abu Dhabi's Tawazun-backed supplier ecosystems show the clearest adoption of this approach, with platform OEMs now competing against third-party sustainment specialists for long-term service agreements.
GCC Defense Market Segmentation
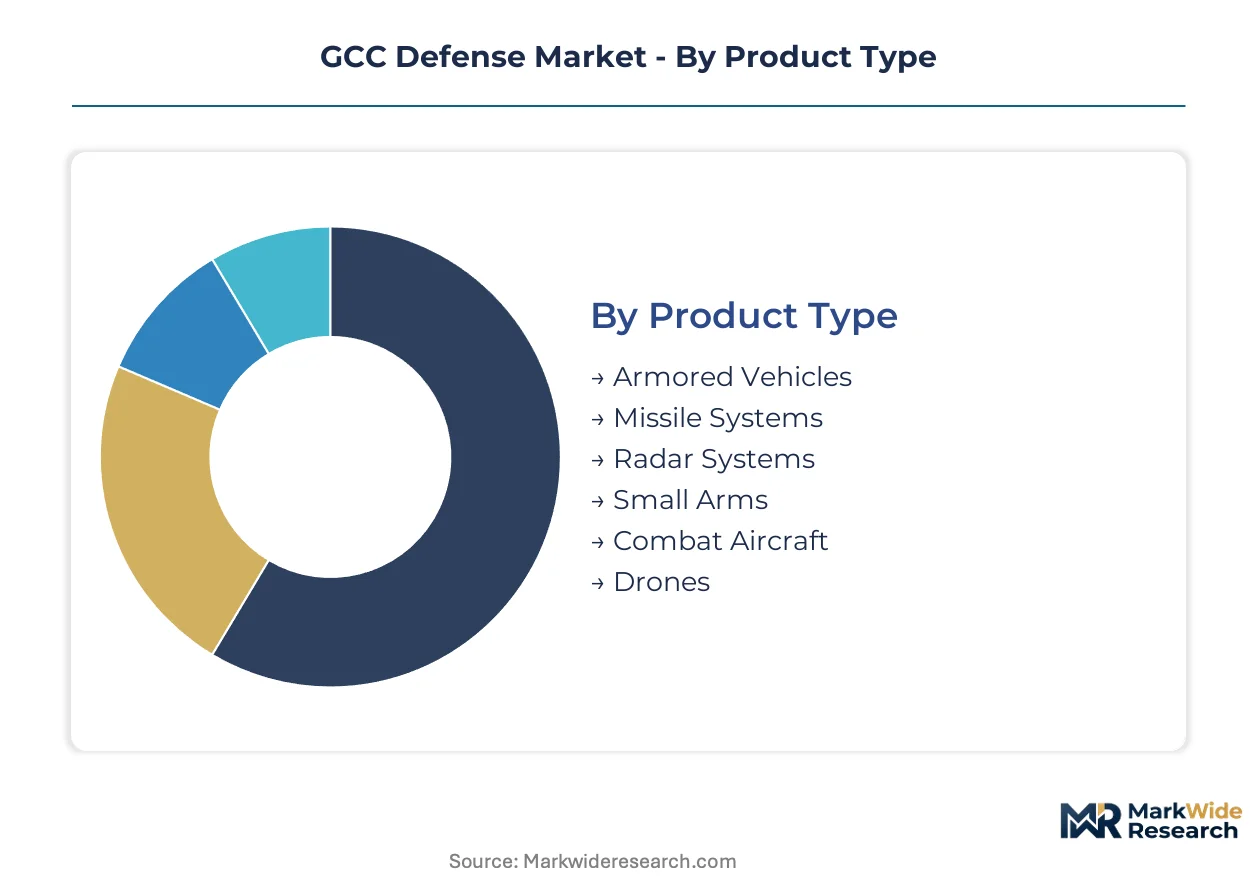
Segmentation reveals how GCC procurement priorities are diverging from legacy platform acquisition toward software-defined capabilities and sovereign manufacturing requirements. Each dimension exposes distinct competitive pressures reshaping supplier positioning across Saudi Arabia and the UAE.
Product Type:
Combat aircraft and armored vehicles face acute substitution pressure from autonomous alternatives as Gulf militaries prioritize reduced personnel exposure and persistent coverage.
- Combat Aircraft:Manned fighter platforms absorb the largest capital allocations per unit due to sophisticated avionics suites and long sustainment requirements. Saudi Arabia's GAMI-led industrial cities concentrate demand through licensed manufacturing partnerships with European and American primes seeking localization compliance.
- Drones:Unmanned platforms incorporate modular sensor packages and encrypted datalinks designed for extreme thermal operating conditions exceeding 55 degrees Celsius. UAE forces field-test coordinated swarm formations for border security, displacing conventional manned aircraft orders in favor of rapidly upgradeable unmanned fleets.
- Missile Systems:Precision strike and air defense categories require decade-long investment horizons and technology transfer agreements.
- Radar Systems:Ground-based and airborne early warning platforms interface with NATO-standard communications architectures.
- Armored Vehicles:Main battle tanks and infantry fighting vehicles face procurement slowdowns as autonomous systems gain preference.
- Small Arms:Domestic production through EDGE Group and GAMI joint ventures reduces import dependency for standard infantry weapons.
Combat aircraft anchors the volume base while drones gain share at the steepest rate.
Technology:
Cost tier differentiation separates mature electronic warfare systems from emerging directed energy investments requiring sovereign R&D backing.
- Autonomous Systems:Distributed architectures enable persistent area denial without risking personnel. Saudi and Emirati forces prioritize coordinated drone formations and unmanned ground vehicles for surveillance applications in extreme desert conditions.
- Artificial Intelligence:Machine learning integration with sensor fusion and decision-support systems accelerates procurement across command-and-control networks. Tawazun-backed supplier ecosystems in Abu Dhabi concentrate investment in AI-enabled electronic warfare and predictive maintenance platforms.
- Cybersecurity:Network defense and secure communications protect critical infrastructure from state-sponsored threats.
- Electronic Warfare:Mature jamming and signals intelligence platforms face pricing pressure from software-defined alternatives.
- Satellite Communications:Secure datalinks and positioning systems require interoperability with existing GCC military infrastructure.
- Directed Energy:Laser and high-power microwave systems remain developmental, constrained by technology transfer barriers from US ITAR regulations.
Autonomous systems capture the steepest investment trajectory while artificial intelligence climbs fastest in procurement priority rankings.
Application:
Volume concentration in border security reflects persistent territorial threats, while counterterrorism applications face budget reallocation toward strategic deterrence capabilities.
- Border Security:UAV patrol corridors and sensor networks span Saudi Arabia's northern frontier and UAE's disputed maritime boundaries. GAMI certification standards mandate domestic content thresholds for surveillance infrastructure contracts.
- Strategic Deterrence:Long-range strike platforms and missile defense systems absorb capital as regional rivalries intensify. The UAE's Tawazun Council steers technology transfer toward domestic entities through equity stakes in advanced munitions ventures.
- Maritime Surveillance:Coastal defense and anti-access systems protect critical shipping lanes and offshore energy infrastructure.
- Counterterrorism:Special operations equipment and rapid-response capabilities face procurement consolidation.
- Peacekeeping Operations:Force projection logistics and interoperable communications receive secondary priority.
- Emergency Response:Disaster relief and civil defense applications remain underdeveloped in GCC procurement frameworks.
Border security commands the largest procurement volume while strategic deterrence expands most quickly in budget allocation.
End User:
Customer type segmentation exposes bifurcation between traditional military branches and emerging sovereign manufacturers capturing previously outsourced production.
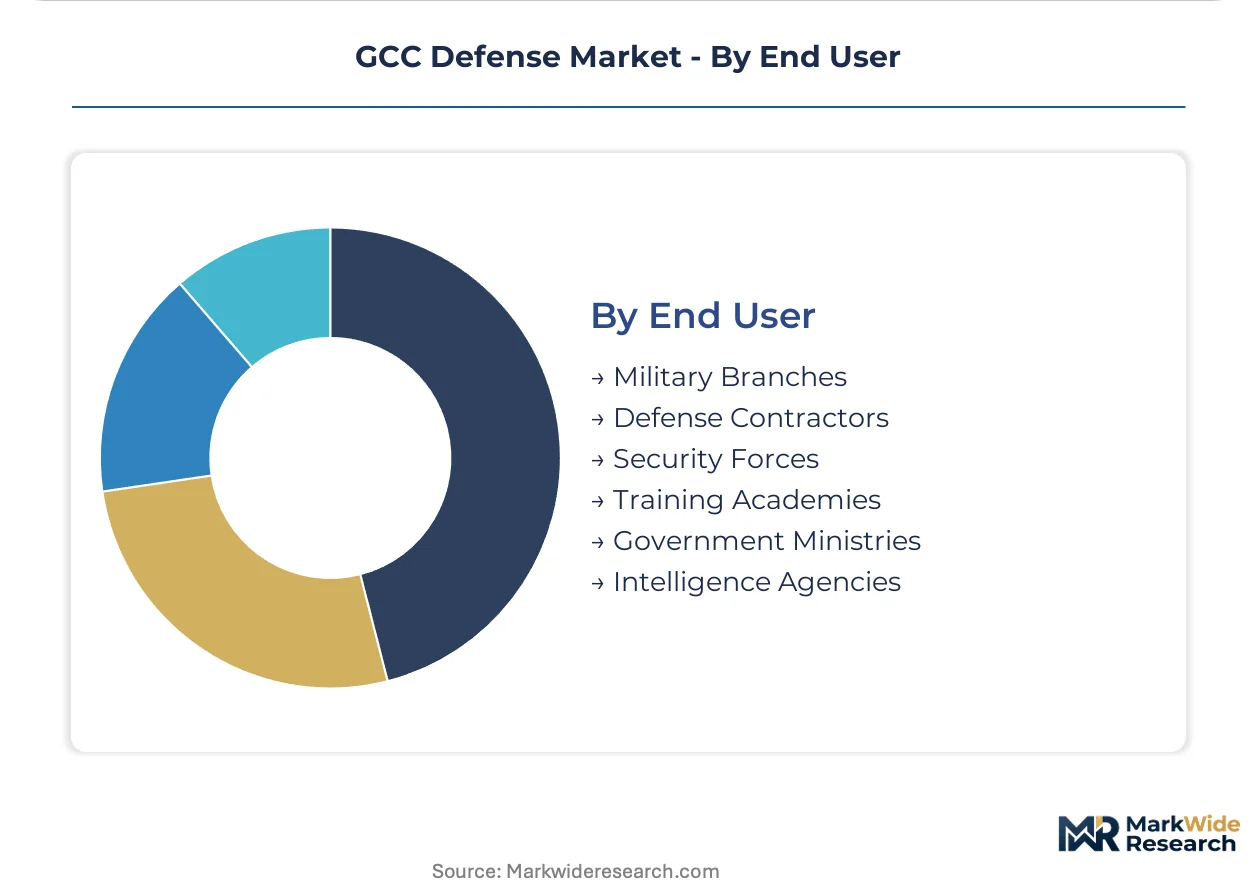
- Military Branches:Army, air force, and naval services remain the dominant procurement channel for major platforms. Saudi Vision 2030 localization mandates require foreign primes to establish domestic production facilities and meet workforce quotas.
- Defense Contractors:EDGE Group PJSC and Saudi Arabian Military Industries now function as both suppliers and procurers, consolidating twenty-five entities into vertically integrated conglomerates capable of competing across electronics, munitions, and platform categories.
- Security Forces:Interior ministry units and paramilitary organizations drive demand for surveillance and crowd-control systems.
- Intelligence Agencies:Signals intelligence and cyber operations require specialized procurement channels outside standard defense ministry frameworks.
- Government Ministries:Direct procurer roles are expanding as GAMI and Tawazun assume contracting authority from traditional foreign prime relationships.
- Training Academies:Simulation and instructional systems represent a fragmented, lower-value procurement segment.
Military branches retain the dominant procurement volume while defense contractors gain share fastest through sovereign manufacturing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Industrial Port in Jubail anchors Saudi Arabia's defense manufacturing corridor, connecting GAMI-led industrial cities to global supply chains. This maritime infrastructure underwrites the kingdom's capacity to import precision components while exporting locally assembled platforms.
Saudi Arabia
GAMI certification standards and Vision 2030 localization mandates drive procurement restructuring across Riyadh and the Eastern Province. The General Authority for Military Industries enforces domestic content thresholds for contracts exceeding specified values. Industrial cities near Jubail and Taif concentrate licensed manufacturing partnerships with European and American primes transferring airframe assembly know-how.
United Arab Emirates
Tawazun Council investment requirements and EDGE Group consolidation reshape procurement flows toward Abu Dhabi and Dubai. The council's evolving offset framework permits equity stakes in domestic technology ventures rather than traditional counter-trade. Tawazun-backed supplier ecosystems in Abu Dhabi concentrate artificial intelligence investment for electronic warfare and predictive maintenance platforms.
Qatar
Amiri Guard modernization and air defense expansion absorb capital as Doha diversifies beyond energy infrastructure. The country's national defense procurement framework emphasizes interoperability with NATO-standard communications architectures. Industrial zones near Hamad Port host emerging maintenance and sustainment capabilities for imported combat aircraft.
Kuwait
Border security infrastructure and maritime surveillance upgrades lag regional peers in indigenous capacity development. The Ministry of Defense directs procurement toward persistent UAV patrol corridors and coastal defense systems. Subiya and Bubiyan Island developments concentrate sensor network deployment for northern frontier monitoring.
Oman
Strategic deterrence requirements and maritime chokepoint protection drive Muscat's procurement priorities along the Strait of Hormuz. The Royal Navy of Oman prioritizes anti-access systems for coastal defense and offshore energy infrastructure protection. Duqm Special Economic Zone hosts emerging maintenance capabilities for naval platforms and submarine systems.
GCC Defense Market Competitive Landscape
Concentration sits with sovereign wealth-backed domestic manufacturers capturing procurement share previously held by foreign primes. The vendor base bifurcates between vertically integrated local champions and foreign primes restructuring around co-production frameworks. Three archetypes dominate: state-owned conglomerates with full technology stack coverage, American and European primes navigating localization mandates through joint ventures, and specialized component suppliers satisfying GAMI certification standards. Competitive moves center on licensed manufacturing arrangements and local workforce development commitments rather than pure export models.
Among state-owned conglomerates, Saudi Arabian Military Industries and EDGE Group PJSC exemplify the vertically integrated archetype consolidating electronics, munitions, and platform capabilities under sovereign umbrellas. Lockheed Martin Corporation occupies a position within the foreign prime tier adapting to localization requirements through technology transfer agreements. BAE Systems PLC sits within the European prime segment restructuring around GAMI industrial city partnerships and domestic production facility commitments.
| Leading Market Players |
|---|
| Saudi Arabian Military Industries |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| BAE Systems PLC |
| Raytheon Company |
| The Boeing Company |
| EDGE Group PJSC |
| Leonardo SpA |
| Airbus SE |
| Others |
Supply & Pricing Matrix
Licensed manufacturing partnerships replacing direct platform exports simultaneously reshape supply geography toward Saudi industrial cities and compress pricing economics through domestic assembly cost structures. GAMI certification requirements and Tawazun equity mandates force foreign primes to absorb technology transfer costs upfront, altering margin distribution across the value chain.
Pricing Analysis
Volume-discount tiering structures separate national-level platform acquisitions from component-level supply contracts, with combat aircraft and missile systems commanding premium pricing due to decade-long sustainment obligations. Price differentiation hinges on GAMI localization compliance grades and sovereign content thresholds, with non-compliant suppliers facing bid disqualification. Cost compression in sensor packages and encrypted datalinks is intensifying as EDGE Group and SAMI expand captive production capabilities. National ministries exhibit lowest price sensitivity for strategic deterrence platforms, while security forces show highest sensitivity for standardized surveillance equipment.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical component flows from European and American precision manufacturers to GCC assembly facilities. Supply concentration rests on Germany, France, and the United States for avionics subsystems, precision munitions, and thermal-resistant electronics. Raw material dependencies span rare earth elements for sensor arrays, high-grade aluminum alloys for airframes, and specialized semiconductors for encrypted datalinks. Single-source vulnerability from US ITAR regulatory restrictions threatens subsystem availability for autonomous platforms. Distribution runs through King Fahd Industrial Port and Jebel Ali for inbound components, with outbound finished platforms moving via military airlift and naval transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through GAMI and Tawazun consolidation of procurement authority, fragmenting traditional foreign prime contracting relationships into joint venture and offset arrangements.
For Market Incumbents: Shield core platform revenues by accelerating licensed manufacturing partnerships in Saudi industrial cities before GAMI certification standards harden. Deepen backward integration into sensor package production to offset margin pressure from domestic assembly mandates. Prioritize workforce localization commitments over pure technology export models to maintain contract eligibility.
For New Entrants and Emerging Players: Differentiate on sovereign-compliant sustainment services, unbundling lifecycle support from initial platform sales where Tawazun-backed ecosystems show adoption. Target Kuwait and Qatar border security modernization as most penetrable geographies lacking indigenous capacity. Pursue equity joint ventures with EDGE Group or SAMI as primary go-to-market channel rather than direct ministry engagement.
For Investors and Strategic Acquirers: GAMI's evolving supplier certification standards reshape the acquisition landscape toward entities with existing industrial security clearances and quality accreditation. Five-to-ten year viability favors specialized component manufacturers with proven NATO interoperability rather than platform assemblers facing localization displacement. Priority acquisition targets include sensor fusion specialists and encrypted datalink developers with active Tawazun investment relationships. Monitor GAMI industrial city occupancy rates as inflection indicator for contract flow redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Manufacturing Partnership | Enables foreign primes to satisfy GAMI localization mandates through technology transfer agreements. |
| Autonomous Systems Development | Captures procurement priority as Saudi and Emirati forces field-test coordinated drone formations. |
| Sovereign Equity Joint Venture | Allows Tawazun Council offset obligations through stakes in domestic technology ventures. |
| Sustainment Capability Buildout | Positions third-party providers for unbundled lifecycle contracts separate from platform sales. |
| GAMI Certification Investment | Secures contract eligibility as industrial security clearance standards evolve. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of defense ministry procurement disclosures, GAMI industrial city development reports, and Tawazun Council investment mandates. Primary interviews engaged platform engineering directors at sovereign manufacturers, procurement officers at GCC defense ministries, offset compliance managers at European primes, and supply chain leads for precision component distributors. Secondary validation drew from customs trade databases, SAMI and EDGE Group corporate filings, NATO standardization agreements, and US ITAR regulatory updates. Bottom-up project pipeline assessment triangulates against top-down defense budget allocation analysis.
Segmentation dimensions modeled span product type, technology category, application mission, and end-user archetype across the projection horizon. Product-type segmentation separates combat aircraft, drones, missile systems, radar platforms, armored vehicles, and small arms. Technology segmentation captures autonomous systems, artificial intelligence, cybersecurity, electronic warfare, satellite communications, and directed energy. Application segmentation addresses border security, strategic deterrence, maritime surveillance, counterterrorism, peacekeeping, and emergency response. End-user segmentation distinguishes military branches, defense contractors, security forces, intelligence agencies, government ministries, and training academies. CAGRs derive from contract award velocity analysis and localization mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued GAMI certification standardization and Tawazun investment mandate enforcement; material deviation in sovereign wealth allocation or regulatory relaxation would warrant model refresh. Practitioners should keep alternative scenarios live as US ITAR regulatory posture and European export control frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Military Laser Systems Market