
 Global Microscopy Software Market | 2026-2036
Global Microscopy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microscopy Software Market Foresight
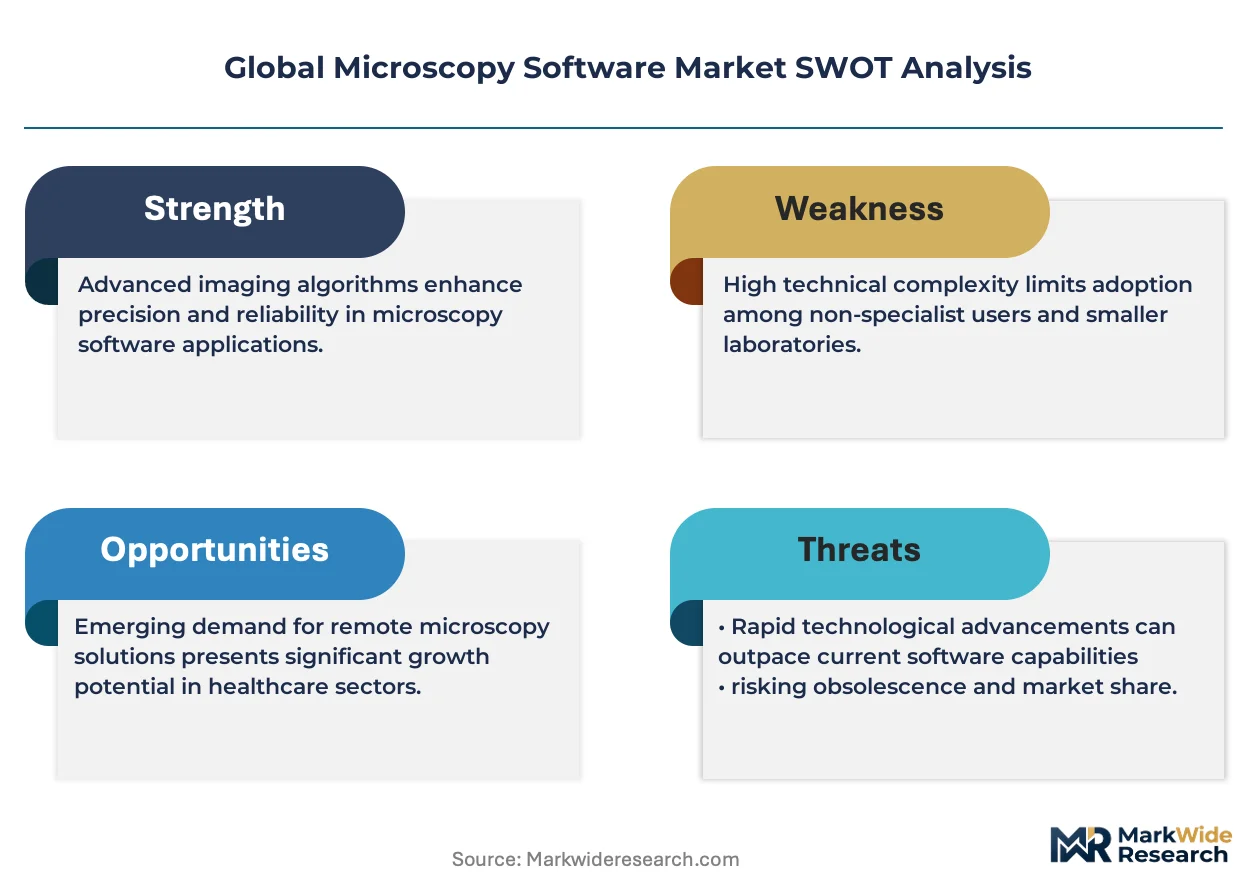
Subscription-based licensing for advanced image processing modules is expanding the addressable base beyond capital-intensive instrument buyers. Carl Zeiss AG leverages its embedded software position across electron and light microscopy systems to sustain recurring revenue streams. Nikon Corporation anchors its competitive stance through deep integration with live cell imaging workflows. Oxford Instruments plc differentiates by specializing in quantitative analysis packages for material science applications.
Microscopy software encompasses computational platforms that capture, process, analyze, and visualize data from optical, electron, and scanning probe instruments, typically handling file formats exceeding gigabytes per acquisition and supporting spectral deconvolution algorithms. Its primary commercial purpose is transforming raw detector output into actionable dimensional, compositional, or morphological intelligence for R&D and quality assurance decisions. Image analysis software commands the largest installed base among product type segments, while automation software represents the fastest expansion trajectory as laboratories seek unattended high-content screening protocols. Electron microscopy solutions retain premium pricing power within technology segments due to the computational intensity of aberration-corrected imaging reconstruction.
FDA software validation requirements under 21 CFR Part 11 constrain market entry for unproven algorithm vendors in clinical diagnostics applications, while the EU AI Act imposes additional conformity obligations on automated image classification tools deployed in European pharmaceutical quality control labs. ISO 13485 and IEC 62304 standards further shape product development roadmaps for vendors targeting regulated medical device environments. Stakeholders must monitor evolving harmonization between FDA predicate device pathways and EU MDR software classification rules to anticipate compliance-driven consolidation among mid-tier platform providers.
Market Dynamics
Algorithm-driven image analysis platforms are restructuring competitive boundaries in microscopy software, as laboratories shift from perpetual licenses toward consumption-based pricing models that bundle computational capacity with hardware access. This transition compresses vendor margins while expanding addressable demand beyond capital-intensive instrument purchasers.
Growth Catalysts
- EU AI Act conformity pathways:Mandatory algorithmic transparency requirements for pharmaceutical quality control labs are accelerating procurement of validated software stacks with pre-certified documentation packages.
- Live cell imaging workflows:Biopharma R&D teams demand real-time segmentation tools capable of tracking cellular dynamics across multi-day experiments without human intervention.
- German OEM cluster density:Concentration of electron and light microscopy manufacturers around Oberkochen and Wetzlar creates captive demand for embedded software development partnerships.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for deep learning-based deconvolution depend on NVIDIA datacenter hardware subject to export control restrictions and supply allocation limits.
- FDA 21 CFR Part 11 validation burden:Clinical diagnostics applications require extensive documentation of algorithm version control, audit trails, and electronic signature protocols that extend sales cycles.
- Open-source ImageJ ecosystem:Free extensible platforms with plugin architectures constrain pricing power for basic image processing functionality in academic and government research segments.
Strategic Opportunities
- India CDSCO medical device software classification:Emerging regulatory clarity for algorithm-based diagnostic aids creates first-mover advantage for vendors establishing local validation partnerships.
- Correlative microscopy convergence:Integration of light, electron, and ion beam data streams into unified analytical environments opens premium pricing for multi-modal reconstruction engines.
- Cloud-native SaaS delivery:Browser-based analysis platforms eliminate on-premise IT infrastructure requirements and expand access to small biotech and contract research organizations.
Industry Challenges
- Computational microscopy skill scarcity:Laboratory personnel lack cross-training in both optical physics and Python-based algorithm development, forcing vendors to embed professional services with every deployment.
- Legacy file format fragmentation:Proprietary vendor-specific data structures from electron microscopes, confocal systems, and scanning probe instruments complicate unified analysis pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microscopy Software Market |
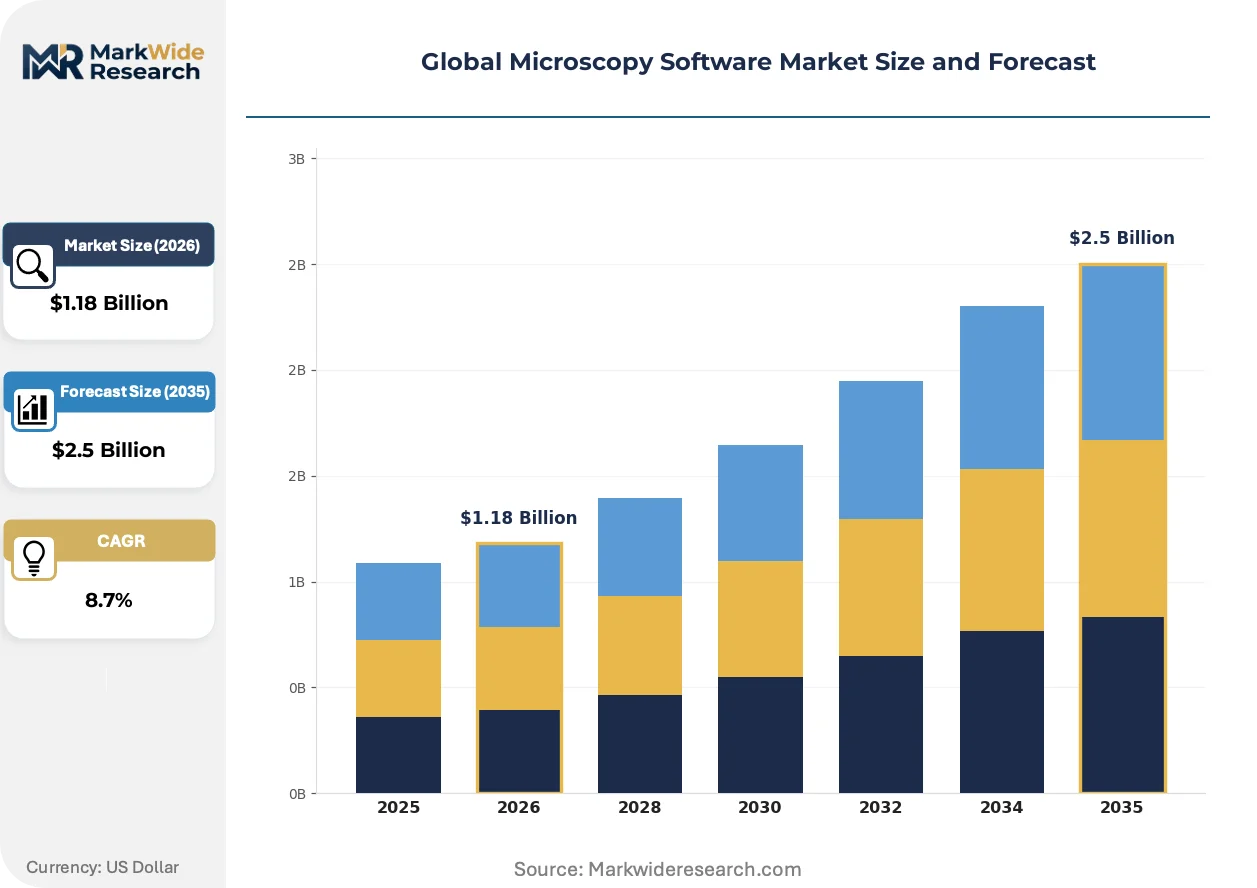
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Image Analysis Software, 3D Reconstruction Tools, Data Visualization, Automation Software, Quantification Solutions Technology: Confocal Microscopy Software, Electron Microscopy Solutions, Fluorescence Imaging, Live Cell Imaging, Super-Resolution Processing Application: Life Sciences Research, Material Science Analysis, Pharmaceutical Development, Semiconductor Inspection, Forensic Investigation End User: Academic Institutions, Biotechnology Firms, Quality Control Labs, Research Institutes, Clinical Diagnostics Centers |
| Companies Covered | Carl Zeiss AG, Leica Microsystems, Nikon Corporation, Thermo Fisher Scientific Inc., Olympus Corporation, Basler AG, Oxford Instruments plc, JEOL Ltd., Gatan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microscopy Software Market Shifts & Advancements
Foundation model architectures trained on microscopy-specific image corpora are compressing development timelines for specialized analysis tasks. These pre-trained networks reduce customer-specific training data requirements while raising performance baselines across segmentation, classification, and anomaly detection workflows.
Deep learning-based aberration correction is absorbing the computational burden previously handled by hardware-based electron optical elements. Materials science laboratories at national research facilities are adopting these algorithmic approaches to extend instrument resolution without physical column modifications. The technology is absorbing capital expenditure that would otherwise flow to microscope hardware upgrades, redirecting budget toward software and compute infrastructure.
EMA's incoming guidance on artificial intelligence in medicinal product lifecycle management is forcing software vendors to restructure quality management systems. Documentation of training data provenance, model validation protocols, and post-deployment monitoring must now satisfy pharmaceutical inspectorate scrutiny. Electron microscopy suites used for biologics characterization face the steepest compliance ramps, with vendors embedding regulatory affairs specialists into implementation teams.
Consumption-based licensing tied to image analysis throughput is displacing traditional seat-based pricing in high-content screening environments. Pharmaceutical contract research organizations in the United States are negotiating enterprise agreements that meter computational operations rather than count named users. This metering model aligns vendor revenue with customer value realization, compressing upfront procurement friction while extending contractual visibility over multi-year horizons.
Global Microscopy Software Market Segmentation
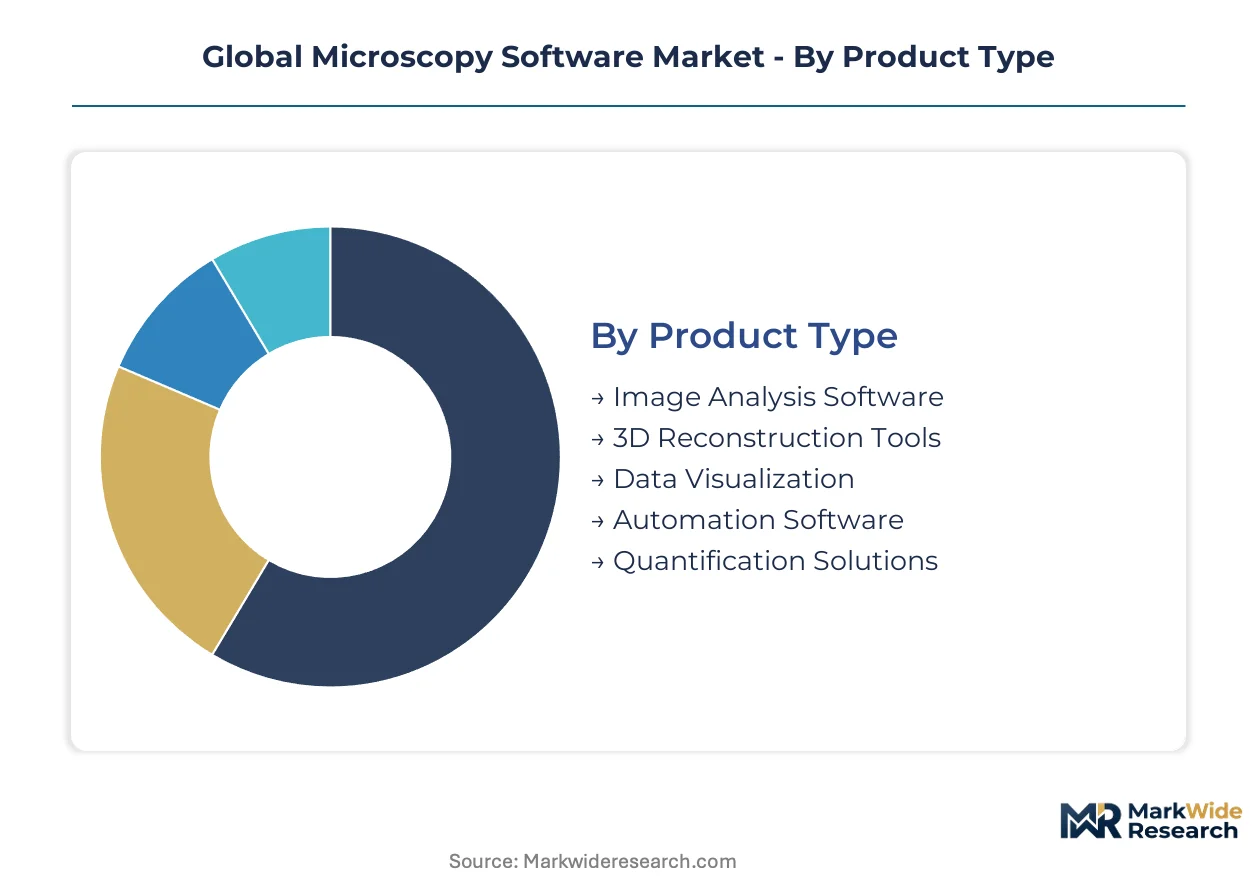
Segmentation in microscopy software reflects divergent computational intensity requirements across research workflows. Procurement decisions pivot on integration depth with existing instrument fleets and regulatory validation status rather than standalone feature comparisons.
Product Type:
Laboratories allocate software budgets based on whether the purchase extends instrument capability or automates existing manual workflows.
- Image Analysis Software:Handles segmentation, particle counting, and morphometric measurements on gigabyte-scale image stacks. Academic institutions in Germany deploy these tools for high-content screening pipelines constrained by EU AI Act documentation requirements.
- Automation Software:Orchestrates unattended acquisition protocols and real-time feedback loops for multi-day live cell experiments. Pharmaceutical development teams in the United States prioritize these modules to satisfy FDA 21 CFR Part 11 validation protocols for electronic records.
- 3D Reconstruction Tools:Computational engines for volumetric rendering from serial section or tomographic data.
- Data Visualization:Browser-based dashboards and collaborative annotation environments for distributed research teams.
- Quantification Solutions:Specialized packages for spectral unmixing and intensity calibration in material science applications.
Volume sits with Image Analysis Software; growth tilts toward Automation Software.
Technology:
Technology selection tracks the underlying hardware investment cycle, with software pricing indexed to instrument capital cost tiers.
- Electron Microscopy Solutions:Aberration-corrected reconstruction algorithms and drift-compensation routines for sub-angstrom resolution data. National research facilities in Japan absorb premium licensing costs to extend existing column performance without physical upgrades.
- Super-Resolution Processing:Deconvolution and localization microscopy algorithms that extract sub-diffraction information from fluorescence datasets. Life sciences research institutes in Switzerland deploy these tools for biologics characterization under EMA scrutiny.
- Confocal Microscopy Software:Z-stack acquisition and pinhole optimization for optical sectioning applications.
- Fluorescence Imaging:Spectral unmixing and bleaching correction for multiplexed labeling experiments.
- Live Cell Imaging:Environmental control integration and time-lapse analysis for cellular dynamics studies.
Revenue concentrates in Electron Microscopy Solutions; Super-Resolution Processing gains share fastest.
Application:
Application segmentation mirrors end-user funding stability and regulatory exposure, with pharmaceutical and semiconductor buyers commanding longest sales cycles.
- Pharmaceutical Development:GMP-compliant image analysis for biologics characterization and quality control documentation. Quality control labs in Ireland and Germany face the steepest compliance ramps under incoming EMA guidance on artificial intelligence in medicinal product lifecycle management.
- Semiconductor Inspection:Defect classification and metrology algorithms for node shrink validation. Foundries in South Korea and Taiwan meter computational operations through consumption-based enterprise agreements rather than seat licensing.
- Life Sciences Research:Basic and translational research workflows with variable validation requirements.
- Material Science Analysis:Crystallography, spectroscopy, and mechanical property correlation for industrial R&D.
- Forensic Investigation:Trace evidence documentation and comparative analysis for law enforcement agencies.
Spending weight rests with Pharmaceutical Development; Semiconductor Inspection climbs the fastest.
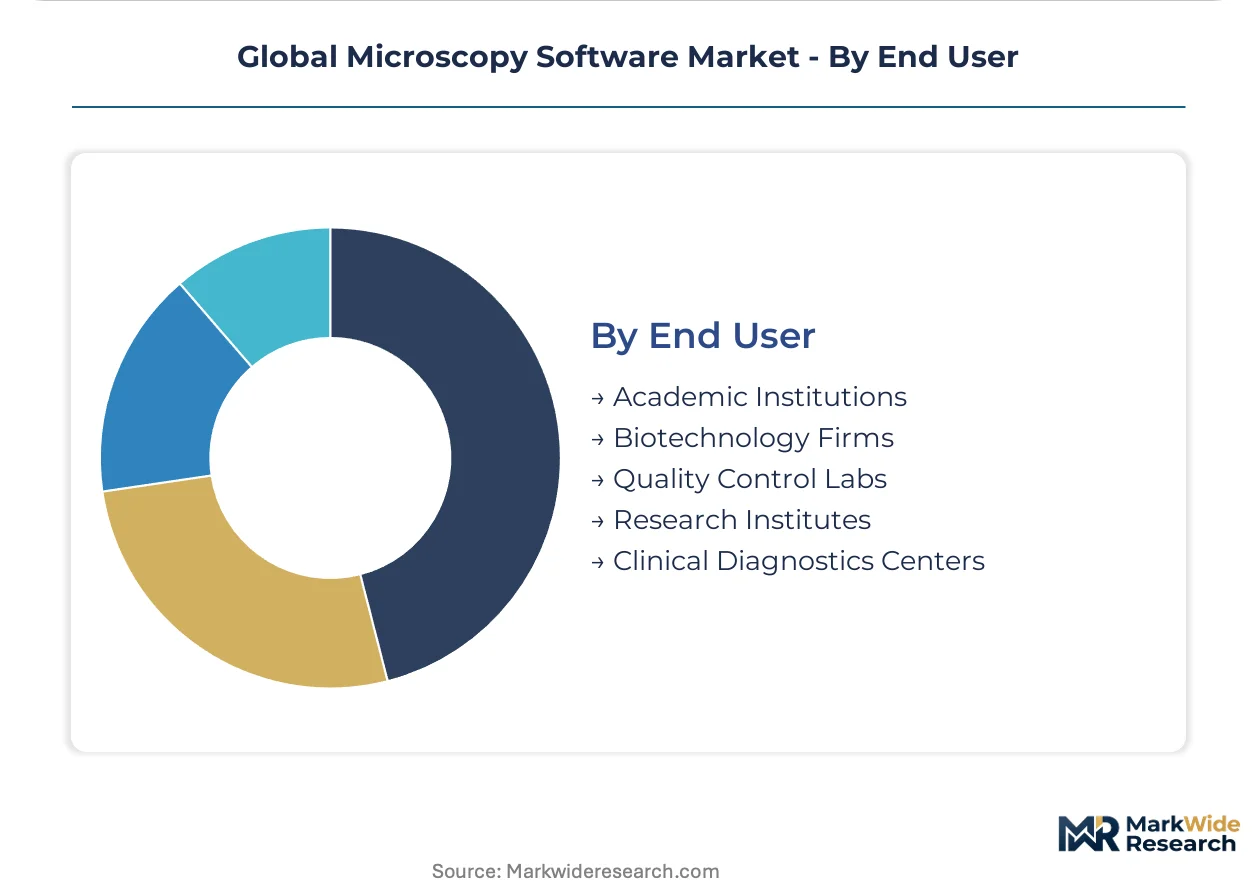
End User:
End user type determines pricing elasticity and support intensity, with commercial laboratories accepting higher per-seat costs for validated documentation packages.
- Biotechnology Firms:Rapidly scaling R&D operations with hybrid cloud deployment preferences. Contract research organizations in India negotiate local validation partnerships ahead of CDSCO medical device software classification clarity.
- Quality Control Labs:Regulated environments requiring audit trails, electronic signatures, and version-controlled algorithm releases. These buyers in the United States and European Union absorb the highest professional services attachment rates.
- Academic Institutions:Price-sensitive adopters with heavy reliance on open-source ImageJ ecosystems for basic processing.
- Research Institutes:National facility operators with captive IT infrastructure and high-performance computing access.
- Clinical Diagnostics Centers:Emerging adopters constrained by FDA predicate device pathway complexity and reimbursement uncertainty.
Revenue tilts toward Biotechnology Firms; Quality Control Labs drive premium pricing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oberkochen and Wetzlar anchor the densest concentration of electron and light microscopy manufacturing, creating captive demand for embedded software development partnerships that radiate across pharmaceutical and materials science laboratories.
Germany
Pharmaceutical quality control labs in Baden-Württemberg and Hesse drive procurement of EU AI Act-validated software stacks with pre-certified documentation packages. EMA guidance on artificial intelligence in medicinal product lifecycle management forces vendors to embed regulatory affairs specialists into implementation teams. The Oberkochen-Wetzlar corridor sustains OEM-integrated software ecosystems through Carl Zeiss AG and Leica Microsystems.
United States
Biopharma R&D teams in Greater Boston and San Diego demand real-time segmentation tools for multi-day live cell experiments without human intervention. FDA 21 CFR Part 11 validation requirements constrain market entry for unproven algorithm vendors in clinical diagnostics applications. Pharmaceutical contract research organizations negotiate enterprise agreements metering computational operations rather than counting named users.
Japan
National research facilities in Tsukuba and Kobe absorb premium licensing costs for aberration-corrected reconstruction algorithms extending existing electron microscope column performance. METI funding priorities emphasize computational microscopy infrastructure over physical hardware upgrades. Materials science laboratories at RIKEN and KEK adopt deep learning-based aberration correction to redirect capital expenditure toward software and compute.
India
Contract research organizations in Hyderabad and Bangalore negotiate local validation partnerships ahead of CDSCO medical device software classification clarity for algorithm-based diagnostic aids. The country's national pharmaceutical regulator is finalizing regulatory frameworks for AI-enabled microscopy tools. Biotechnology firms in Karnataka and Telangana prefer hybrid cloud deployment models eliminating on-premise IT infrastructure requirements.
Switzerland
Life sciences research institutes in Basel and Zurich deploy super-resolution processing tools for biologics characterization under Swissmedic and EMA scrutiny. Spectral unmixing and localization microscopy algorithms extract sub-diffraction information from fluorescence datasets for pharmaceutical development. The Basel pharmaceutical cluster generates concentrated demand for GMP-compliant image analysis documentation.
Global Microscopy Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the microscopy software landscape, as perpetual license vendors face margin compression from consumption-based pricing models. The market structure tilts toward consolidation around embedded software positions within instrument manufacturers, with mid-tier platform providers vulnerable to compliance-driven acquisition. Three archetypes dominate: OEM-integrated incumbents with captive hardware channels, cloud-native challengers with SaaS delivery models, and specialized quantitative analysis boutiques. Dominant competitive moves include strategic partnerships bundling computational capacity with hardware access and portfolio diversification into correlative microscopy convergence.
Among Germany-based OEM-integrated providers, Carl Zeiss AG and Leica Microsystems exemplify the archetype of embedded software positions across electron and light microscopy systems. Nikon Corporation represents the Asia-Pacific hardware-software integration model, while Oxford Instruments plc occupies a specialist position in quantitative analysis packages for material science applications. These three companies anchor the competitive structure through their respective geographic and technological strongholds.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Leica Microsystems |
| Nikon Corporation |
| Thermo Fisher Scientific Inc. |
| Olympus Corporation |
| Basler AG |
| Oxford Instruments plc |
| JEOL Ltd. |
| Gatan, Inc. |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate qualified supply for pharmaceutical quality control labs, restricting premium-tier pricing access to vendors with pre-certified documentation packages and validated software stacks. Compliance investment thresholds stratify the vendor base, concentrating pricing power among embedded software providers with captive hardware channels.
Pricing Analysis
Consumption-based pricing anchored to image analysis throughput dominates high-content screening environments, displacing perpetual seat licenses. Price differentiation rests on FDA 21 CFR Part 11 validation status and EU AI Act conformity tier, with certified automation software commanding substantial premiums over basic image processing modules. Cost compression in academic and government research segments intensifies as open-source ImageJ ecosystems constrain pricing power for baseline functionality. Biotechnology firms exhibit highest price sensitivity due to hybrid cloud deployment preferences, while quality control labs absorb elevated per-seat costs for audit-trail documentation.
Supply Chain Analysis
Freight cost volatility for NVIDIA datacenter GPU hardware complicates margin planning for deep learning-based deconvolution vendors. Software development concentrates in Germany, the United States, and Japan, drawing from specialized talent pools in optical physics and Python-based algorithm engineering. Supply chain risk centers on single-source vulnerability for aberration-corrected reconstruction compute hardware subject to export control restrictions. Distribution runs through OEM-embedded channels for instrument manufacturers and direct SaaS provisioning for cloud-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model architectures are displacing customer-specific training pipelines, compressing development timelines and restructuring competitive boundaries across image analysis workflows.
For Market Incumbents: Deepen regulatory affairs integration within implementation teams to defend against compliance-driven consolidation. Embed quality management systems satisfying EMA guidance on artificial intelligence in medicinal product lifecycle management. Extend backward integration into GPU compute infrastructure to mitigate NVIDIA supply allocation exposure. For New Entrants and Emerging Players: CDSCO medical device software classification in India opens a window for local validation partnerships ahead of framework finalization. Target contract research organizations in Hyderabad and Bangalore with hybrid cloud deployment models eliminating on-premise IT requirements. Lead with browser-based SaaS delivery to bypass OEM channel capture. For Investors and Strategic Acquirers: CDSCO regulatory clarity publication is the leading indicator that algorithm-based diagnostic aid software will command premium valuations. Position for mid-tier platform provider acquisition opportunities as FDA-EU MDR harmonization pressures compliance infrastructure investment. Monitor GPU export control policy adjustments as supply constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | EMA and FDA validation protocols secure pharmaceutical quality control procurement channels. |
| Cloud-Native SaaS Migration | Browser-based platforms eliminate IT infrastructure barriers for small biotech laboratories. |
| Correlative Microscopy Integration | Unified light, electron, and ion beam environments command premium reconstruction engine pricing. |
| Foundation Model Development | Pre-trained microscopy-specific networks reduce customer training data requirements substantially. |
| GPU Infrastructure Partnership | Computational capacity bundling aligns vendor revenue with customer throughput realization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this microscopy software market assessment. Primary interviews with platform engineers, laboratory directors, regulatory affairs specialists, and biomedical procurement officers combined with FDA 510(k) databases, EMA submission repositories, and hyperscaler capex disclosures. Bottom-up instrument installation base modeling and top-down pharmaceutical R&D spend analysis provided triangulation across the analysis window.
Data-stream reconciliation across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern dimensions shaped the analytical framework. CAGRs derived from instrument replacement cycles and software attach rate trajectories incorporated live cell imaging workflow expansion and electron microscopy aberration correction algorithm penetration as industry-specific inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for foundation model architectures would alter the outlook if laboratory personnel training gaps persist. Forecasts reflect documented assumptions regarding EU AI Act implementation timing and GPU supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Enterprise Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Marketing Automation Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Self-Storage Software Market
Software & Services
Performance Management Software Market
Software & Services
Live Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global Florist Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Asia-Pacific Digital Signage Software Market