
 Foot Insole Market | 2026-2036
Foot Insole Market Size, Share, and Industry Trends Forecast 2026-2036
Foot Insole Market Analysis
Modular insole systems that separate arch supports from base cushioning layers is recalibrating how consumers assemble foot comfort solutions. Bauerfeind AG leverages its medical-grade manufacturing heritage to anchor premium positioning in European pharmacy channels. Superfeet Worldwide, Inc. competes through specialized trail-running and hiking configurations that dominate outdoor specialty retail. Dr. Scholl's extends its mass-market brand strength through supermarket and drugstore distribution networks across North America.
Foot insoles are engineered inserts placed inside footwear to modify biomechanical function, redistribute plantar pressure, or enhance comfort, typically fabricated from ethylene-vinyl acetate foam, thermoplastic polyurethane gel, or carbon-fiber composite shells with specified durometer ratings between 30 and 70 Shore A. Their primary commercial purpose spans medical correction of gait abnormalities, athletic performance optimization, and occupational fatigue reduction. Orthotic insoles command the deepest margin pools due to prescription validation requirements and custom fabrication workflows, while gel insoles sustain volume leadership in over-the-counter comfort segments. Sports application demand accelerates fastest among marathon and ultrarunning participants seeking impact attenuation above 50% ground reaction force reduction.
US FDA classifies prescription orthotic insoles as Class I medical devices exempt from premarket notification, yet state-level scope-of-practice laws governing podiatrist dispensing create fragmented market access conditions. Europe's MDR and CE marking requirements for custom-fabricated devices impose biocompatibility testing obligations on manufacturers serving clinical channels. Stakeholders must monitor evolving reimbursement thresholds at CMS and Germany's G-BA, as coverage compression would redirect prescription volumes toward direct-pay retail models without professional fitting oversight.
Market Dynamics
Material substitution toward thermoplastic polyurethane foams is compressing production costs while elevating pressure redistribution performance, forcing legacy ethylene-vinyl acetate manufacturers to reformulate compound recipes or surrender shelf space to medical-grade competitors.
Growth Catalysts
- CMS Medicare Coverage Expansion:Tightened reimbursement criteria for diabetic foot care is channeling prescription volumes toward clinically validated orthotic devices, validating professional fitting workflows.
- Marathon Runner Demographics:Ultrarunning participation growth is generating demand for impact attenuation exceeding 50% ground reaction force reduction in sports-specific configurations.
- Thermoplastic Polyurethane Gel Formulation:Durometer-tunable foams between 30 and 70 Shore A are enabling mass-customization of pressure-mapping insoles without full custom fabrication overhead.
Market Restraints
- Ethylene-Vinyl Acetate Feedstock Volatility:Petrochemical input cost swings compress margin pools for volume manufacturers dependent on commodity foam grades.
- German Statutory Insurance Concentration:Reimbursement dependency on Germany's G-BA decisions creates geographic revenue concentration risk for European orthotic specialists.
- Carbon-Fiber Composite Shell Cost Barrier:High-performance rigid orthotic fabrication remains capital-intensive, limiting custom device accessibility in direct-pay retail channels.
Strategic Opportunities
- Occupational Fatigue Reduction Mandates:Workplace safety regulations in manufacturing and logistics sectors are creating employer-funded procurement channels for anti-fatigue insole programs.
- Modular Component Systems:Separable arch support and base cushioning layers enable consumer-assembled configurations, opening pharmacy and outdoor specialty retail placement.
- Biocompatibility Certification Pathways:Europe's MDR and CE marking workflows for custom-fabricated devices create competitive moats for manufacturers investing in clinical channel compliance.
Industry Challenges
- Podiatrist Scope-of-Practice Fragmentation:US state-level dispensing laws create inconsistent market access conditions, complicating multi-state distribution strategies for prescription orthotic brands.
- Biomechanical Fitting Skill Scarcity:Professional gait analysis and pressure mapping expertise remains concentrated among certified pedorthists, constraining scalable direct-to-consumer conversion.
- Legacy Retail Inventory Complexity:Size and arch-type proliferation strains supermarket and drugstore shelf productivity, pressuring mass-market brands to rationalize SKU counts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot Insole Market |
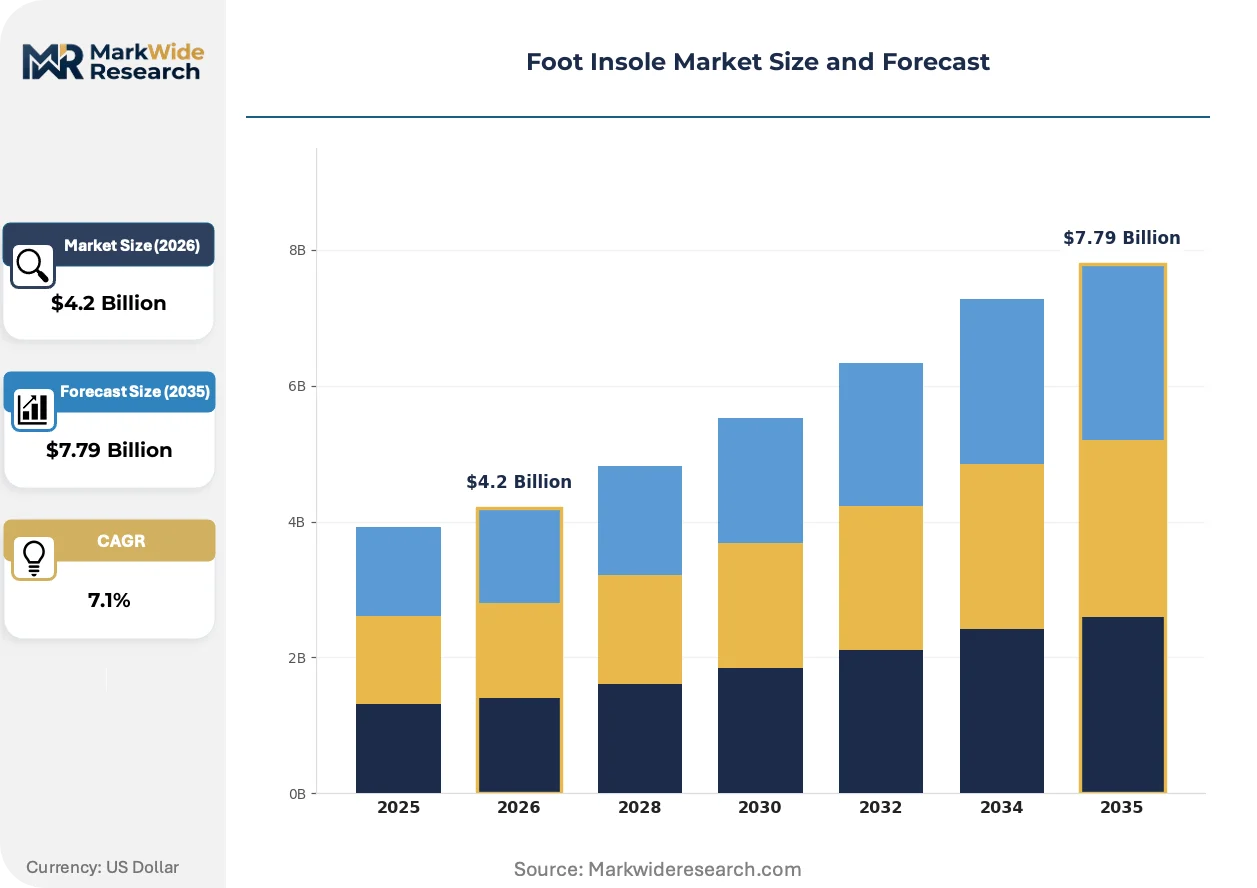
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.79 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Insoles, Gel Insoles, Foam Insoles, Cushioned Insoles Application: Sports, Medical, Comfort, Everyday Wear End User: Athletes, Diabetics, General Consumers, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Superfeet Worldwide, Inc., Dr. Scholl's, Aetrex Worldwide, Bauerfeind AG, PowerStep, Vionic, Foot Science International, Spenco, Hanger Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot Insole Market Emerging Trajectories
Digital manufacturing workflows and sensor-embedded diagnostics are converging to transform how foot insoles are fitted, fabricated, and monitored throughout their service life. This technological layering is compressing the traditional separation between medical device and consumer wellness categories.
Pressure-mapping sensor arrays embedded within insole structures are integrating real-time gait analytics into athletic training and diabetic foot monitoring protocols. Professional sports teams and remote patient management programs are adopting these configurations fastest. The technology is integrating clinical-grade biomechanical feedback into previously passive comfort products, blurring regulatory classification boundaries.
Europe's MDR biocompatibility testing obligations for custom-fabricated devices are elevating documentation burdens on manufacturers serving clinical channels. Smaller fabricators face consolidation pressure as compliance costs concentrate market share among scaled medical-grade producers. German pharmacy and orthotic specialist networks are responding by deepening supplier exclusivity arrangements with MDR-certified manufacturers.
Marathon and ultrarunning participants are compressing replacement cycles for high-performance insoles, treating these components as consumable training equipment rather than durable footwear accessories. Specialty running retailers are capturing this behavioral shift through subscription-based replacement programs and gait-reassessment services. This pattern concentrates in Germany and US coastal metropolitan markets where organized running club density supports premium channel development.
Foot Insole Market Segmentation
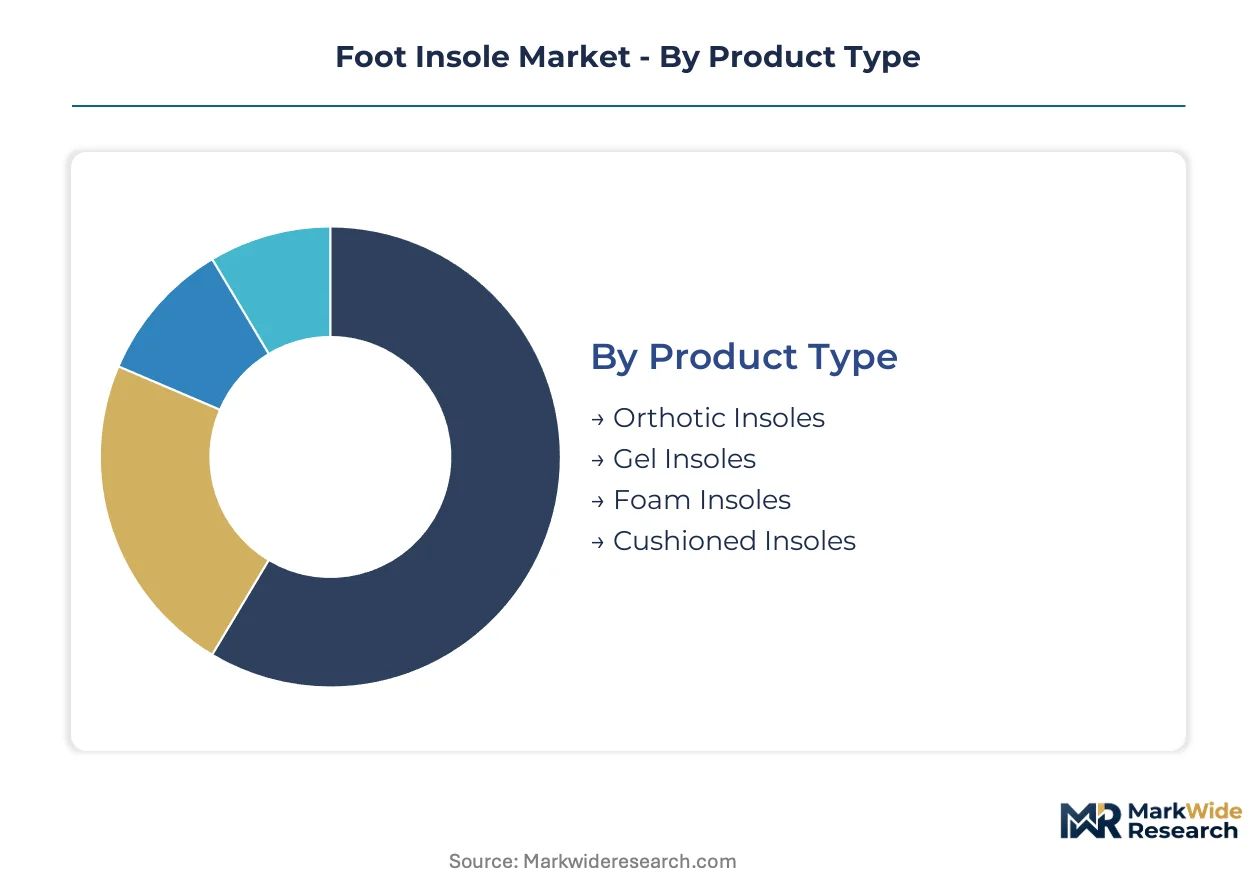
Foot insole segmentation reveals divergent margin architectures across product categories, with prescription-validated devices commanding premium pricing while commodity comfort products compete on shelf velocity. Understanding these segment boundaries enables manufacturers to align R&D investment with reimbursement pathways and retail channel economics.
Product Type:
Orthotic insoles function as embedded biomechanical correction systems requiring professional fitting workflows, while gel and foam variants operate as standalone comfort accessories with minimal integration overhead.
- Orthotic Insoles:Carbon-fiber composite shells and thermoplastic structures fabricated to specified durometer ratings between 30 and 70 Shore A address gait abnormalities and plantar pressure redistribution. Demand concentrates among diabetic patients in Germany where statutory health insurance reimbursement remains comprehensive, though CMS coverage tightening in the US is validating professional dispensing channels.
- Gel Insoles:Thermoplastic polyurethane gel formulations provide viscoelastic cushioning without prescription requirements. Volume leadership persists in North American supermarket and drugstore networks where Dr. Scholl's brand recognition sustains impulse purchase conversion.
- Foam Insoles:Ethylene-vinyl acetate compounds offer cost-efficient pressure relief for occupational fatigue reduction programs. Petrochemical feedstock volatility compresses margin pools for manufacturers dependent on commodity foam grades.
- Cushioned Insoles:Multi-layer constructions combining memory foam with moisture-wicking top sheets target everyday wear applications. Mass-market positioning limits pricing power despite broad demographic accessibility.
Gel insoles lead volumes today; orthotic insoles are gaining share fastest.
Application:
Application segmentation tracks how end-use intensity shapes replacement cycles, with athletic training regimens compressing product lifespans versus medical applications prioritizing durability.
- Sports:Marathon and ultrarunning participants demand impact attenuation exceeding 50% ground reaction force reduction, treating insoles as consumable training equipment with accelerated replacement schedules. Specialty running retailers in Germany and US coastal metropolitan markets capture this behavioral shift through subscription-based replacement programs.
- Medical:Diabetic foot care protocols and gait correction therapies require prescription validation and custom fabrication workflows. Europe's MDR biocompatibility testing obligations elevate documentation burdens, concentrating market share among scaled medical-grade producers.
- Comfort:General wellness positioning targets consumers seeking discretionary footwear enhancement without clinical indication. Price sensitivity constrains margin expansion in direct-pay retail channels.
- Everyday Wear:Occupational fatigue reduction mandates in manufacturing and logistics sectors are creating employer-funded procurement channels distinct from consumer-driven purchasing.
Medical applications anchor premium pricing; sports applications are expanding most quickly.
End User:
End user segmentation distinguishes between professionally supervised fitting workflows and self-directed consumer selection, with significant implications for distribution channel strategy.
- Athletes:Organized running club density in Germany and US coastal markets supports premium channel development for performance-optimized configurations. Gait-reassessment services deepen customer retention.
- Diabetics:Medicare coverage criteria under CMS rules are channeling prescription volumes toward clinically validated orthotic devices, reinforcing professional fitting requirements.
- General Consumers:Mass-market accessibility through supermarket and drugstore networks prioritizes brand recognition and price accessibility over biomechanical customization.
- Healthcare Professionals:Podiatrists and certified pedorthists serve as gatekeepers for prescription orthotic dispensing, though US state-level scope-of-practice fragmentation complicates multi-state distribution strategies.
General consumers dominate unit volumes; athletes are climbing the fastest.
Distribution Channel:
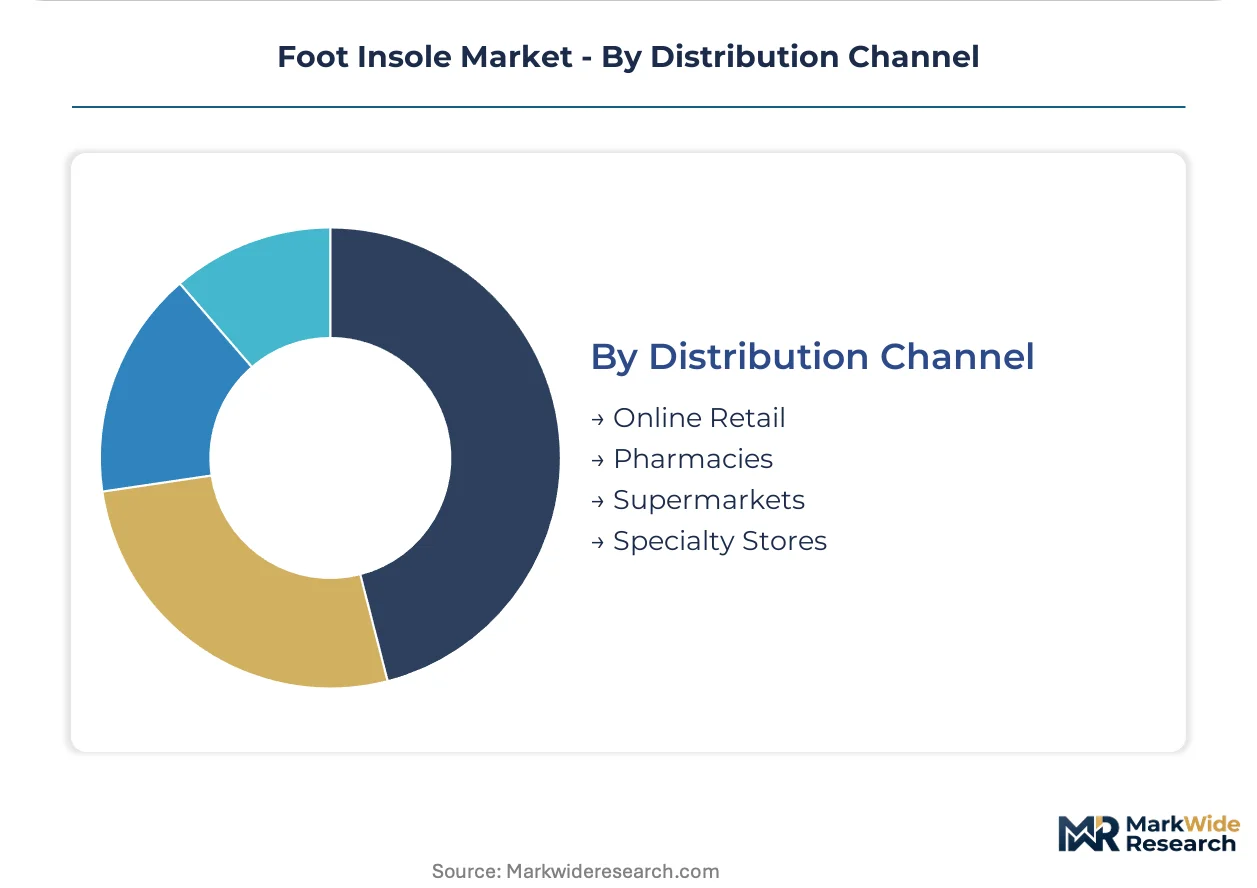
Channel segmentation reflects the tension between professional fitting oversight and retail convenience, with reimbursement pathways heavily influencing channel selection for medical-grade products.
- Online Retail:Direct-to-consumer platforms enable mass-customization of pressure-mapping insoles without full custom fabrication overhead, though biomechanical fitting skill scarcity constrains scalable conversion.
- Pharmacies:European pharmacy networks deepen supplier exclusivity arrangements with MDR-certified manufacturers, leveraging medical-grade manufacturing heritage for premium positioning.
- Supermarkets:Size and arch-type proliferation strains shelf productivity, pressuring mass-market brands to rationalize SKU counts while maintaining brand visibility.
- Specialty Stores:Outdoor specialty retail captures trail-running and hiking configurations through modular component systems that separate arch supports from base cushioning layers.
Supermarkets and pharmacies lead volume distribution; specialty stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthotic engineering traditions established the technical foundations for modern foot insole fabrication, with precision manufacturing clusters in Bavaria and North Rhine-Westphalia setting standards for medical-grade thermoplastic processing that competitors worldwide still reference.
United States
Marathon runner density in coastal metropolitan markets drives replacement cycle compression for high-performance configurations. CMS Medicare coverage tightening under diabetic foot care protocols validates professional dispensing channels. Boston and San Francisco running club ecosystems support specialty retailer subscription programs for gait-reassessment services.
Germany
Statutory health insurance reimbursement through G-BA decisions sustains prescription orthotic volumes among diabetic patient populations. Europe's MDR biocompatibility testing obligations elevate compliance burdens that concentrate market share among scaled producers. Bavarian manufacturing clusters around Munich and Nuremberg anchor medical-grade thermoplastic polyurethane foam production for pharmacy channel distribution.
Japan
Aging demographics expand gait correction therapy demand among elderly populations seeking biomechanical stability solutions. METI industrial standards for medical device manufacturing impose quality system requirements on domestic fabricators. Osaka-Kobe industrial corridor hosts precision molding specialists serving podiatrist dispensing networks.
United Kingdom
NHS procurement frameworks for diabetic foot care create institutional demand channels for prescription-validated devices. MHRA medical device regulations align with MDR transition timelines for custom-fabricated orthotics. London and Manchester orthopedic specialist networks concentrate professional fitting expertise.
China
Manufacturing and logistics sector expansion generates employer-funded occupational fatigue reduction program demand. NMPA medical device classification for custom orthotics remains under development, creating regulatory uncertainty for clinical channel entry. Yangtze River Delta manufacturing clusters around Shanghai supply commodity foam grades for export markets.
Foot Insole Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reimbursement pathway access, with prescription-validated orthotic specialists commanding deeper margin pools than supermarket-distributed comfort brands. The vendor base stratifies into three tiers: medical-grade manufacturers with MDR certification, outdoor specialty brands with modular component systems, and mass-market labels with drugstore distribution. Scale-driven consolidation pressures smaller fabricators facing Europe's biocompatibility documentation burdens. Geographic expansion and portfolio diversification represent the dominant competitive vectors as players seek to reduce reimbursement dependency concentration.
Among German medical device specialists, Bauerfeind AG exemplifies the premium-tier archetype anchored in European pharmacy channel exclusivity arrangements. Superfeet Worldwide, Inc. and Dr. Scholl's occupy contrasting positions across the specialization spectrum—one representing outdoor performance configuration expertise, the other exemplifying mass-market brand recognition through supermarket and drugstore networks. These three entities collectively illustrate how fabrication heritage, channel strategy, and price positioning segment competitive terrain without requiring identical capability investments.
| Leading Market Players |
|---|
| Superfeet Worldwide, Inc. |
| Dr. Scholl's |
| Aetrex Worldwide |
| Bauerfeind AG |
| PowerStep |
| Vionic |
| Foot Science International |
| Spenco |
| Hanger Inc. |
| Others |
Supply Flow & Price Mechanics
Europe's MDR biocompatibility testing obligations gate qualified supply for clinical-grade insoles while simultaneously justifying premium-tier pricing access for manufacturers bearing compliance documentation burdens. German pharmacy channel exclusivity arrangements reward MDR-certified producers with pricing power that commodity foam manufacturers cannot replicate.
Pricing Analysis
Three-tier pricing structure across prescription-validated orthotics, performance sports configurations, and mass-market comfort products anchors revenue architecture. Price differentiation hinges on certification grade — MDR/CE marking versus over-the-counter positioning — and customization depth requiring professional fitting workflows. Cost compression in commodity foam tiers intensifies because petrochemical feedstock volatility erodes manufacturer margins. General consumers exhibit highest price sensitivity; diabetic patients with statutory insurance coverage demonstrate lowest sensitivity due to reimbursement insulation.
Supply Chain Analysis
Workforce availability constraints in Bavarian and North Rhine-Westphalian manufacturing clusters tether high-performance thermoplastic polyurethane foam production to established German industrial corridors. Raw material sourcing draws from Saudi petrochemical complexes for ethylene-vinyl acetate feedstock, Belgian chemical processors for polyurethane precursors, and Japanese carbon-fiber specialists for rigid orthotic shells. Single-source vulnerability concentrates in German precision molding equipment suppliers. Distribution runs through pharmacy networks for medical-grade products and supermarket chains for mass-market comfort lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion runway through thermoplastic polyurethane substitution that compresses production costs while elevating performance premiums. Material innovation cascades through reimbursement-validated and direct-pay channels alike.
For Market Incumbents: Cement MDR certification moats by deepening biocompatibility documentation investments that smaller fabricators cannot replicate. Fortify pharmacy channel exclusivity in Germany against emerging modular component competitors. Vertical integration into thermoplastic polyurethane gel formulation secures supply continuity when petrochemical volatility disrupts commodity foam grades. For New Entrants and Emerging Players: Launch via direct-to-consumer pressure-mapping platforms that bypass professional fitting scarcity constraints in underserved North American markets. Exploit subscription-based replacement programs for marathon runners as the most penetrable sports segment. Partner with specialty running retailers for gait-reassessment service bundling. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale MDR-certified fabricators because compliance cost concentration forces smaller European competitors toward distressed exit. Five-to-ten-year viability favors scaled producers with pharmacy network anchoring. Watch CMS reimbursement threshold adjustments as the critical signal for prescription volume redirection toward retail models.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Biocompatibility documentation creates defensible pharmacy channel access against commodity competitors. |
| Modular Component System Launch | Separable arch supports unlock outdoor specialty retail placement beyond clinical dispensing constraints. |
| Subscription Replacement Programs | Marathon runner consumable behavior compresses replacement cycles into recurring revenue streams. |
| Thermoplastic Polyurethane Backward Integration | In-house gel formulation insulates margin pools from petrochemical feedstock volatility. |
| Pressure-Mapping Platform Development | Sensor-embedded diagnostics blur medical device and wellness categories for regulatory arbitrage. |
Methodological Framework
Multiple input streams — podiatrist dispensing records, pharmacy procurement databases, and specialty retailer inventory systems — were reconciled against CMS Medicare claims data and German G-BA reimbursement filings. Primary interviews with certified pedorthists, biomedical engineers, and GPO contracts managers informed clinical workflow validation. Secondary sources included FDA Class I medical device registrations, MDR technical documentation filings, and customs records tracking thermoplastic polyurethane resin imports. Bottom-up segment sizing and top-down macroeconomic triangulation converged on volume and value estimates.
Historical shipment data cross-referenced against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, application intensity, end-user archetype, and distribution channel economics. CAGRs derived from logistic diffusion curves fitted to adoption patterns in diabetic foot care protocols and ultrarunning participation trends. Forecast inputs incorporated CMS coverage threshold sensitivity and German statutory insurance reimbursement stability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MDR enforcement escalation or CMS reimbursement compression scenarios. Projections reflect documented assumptions regarding material substitution velocity and professional fitting workflow scalability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Biohacking Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Maternity and Personal Care Market
Personal Health
Sleep Mask Market
Personal Health
Menstrual Cup Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Feminine Hygiene Market
Personal Health
OTC Health Products Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Global on Site Preventive Care Market
Personal Health
PTBCHA Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Earwax Removal Products Market
Personal Health
Disposable Underwear Market