
 Japan Tourism Market | 2026-2036
Japan Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Tourism Market Outlook
Artificial intelligence-driven itinerary personalization is rewriting how travel packages are assembled and sold in Japan. JTB Corp. leverages decades of domestic network density to sustain package tour dominance across prefectural rail corridors. Inside Japan Tours specializes in culturally immersive small-group routing that differentiates its offering from mass-market alternatives. Odynovo anchors its position through direct-to-consumer digital booking platforms that bypass traditional agency layers.
Japan tourism encompasses the structured movement of domestic and international visitors across Japanese territory for leisure, commerce, wellness, or education purposes, typically involving multi-day stays requiring accommodation, ground transport, and curated access to cultural, natural, or commercial attractions. The sector operates through tightly coordinated hospitality and transport infrastructure where rail connectivity and seasonal capacity management function as core operational parameters. Leisure travel occupies the dominant share of visitor volume, while medical tourism represents the fastest-expanding segment as regional hospitals secure international accreditation. Ryokan accommodations command premium pricing through cultural authenticity positioning, whereas vacation rentals face tightening regulation in historic districts.
METI tourism promotion frameworks and PMDA medical facility accreditation standards jointly shape market access conditions for inbound operators. Japan's national tourism organization coordinates with prefectural governments to enforce accommodation quality benchmarks and sustainability reporting under evolving visitor management protocols. Stakeholders must monitor how visa policy adjustments and regional dispersal incentives redistribute visitor flows beyond the capital corridor.
Market Dynamics
Visa relaxation policies and digital nomad visa frameworks are fundamentally altering entry conditions for inbound visitors, redistributing demand patterns across Japan's prefectural tourism infrastructure.
Growth Catalysts
- Digital nomad visa introduction:METI's new visa category attracts extended-stay professionals who combine remote work with regional exploration, generating longer booking cycles and off-peak demand.
- Southeast Asia outbound expansion:Rising middle-class leisure travelers from Indonesia, Vietnam, and Thailand are driving volume growth in cultural and shopping-oriented itineraries.
- Regional revitalization zone incentives:Prefectural governments offer accommodation subsidies and transport integration to disperse visitors beyond Tokyo-Osaka-Kyoto corridors.
Market Restraints
- Labor-intensive ryokan operations:Traditional Japanese inns require specialized hospitality training that faces generational supply constraints, limiting capacity expansion.
- Historic district rental restrictions:Kyoto and Kanazawa municipalities impose strict short-term rental caps to preserve neighborhood character, constraining alternative accommodation supply.
- Rail corridor capacity ceilings:Shinkansen peak scheduling during cherry blossom and autumn foliage seasons creates transport bottlenecks that suppress incremental visitor volume.
Strategic Opportunities
- Medical tourism accreditation:PMDA-certified regional hospitals can capture wellness-oriented visitors seeking preventive care packages combined with cultural immersion.
- Hokkaido and Tohoku winter positioning:Underdeveloped ski and onsen infrastructure in northern prefectures offers white-space expansion for premium outdoor hospitality.
- AI-native itinerary platforms:Machine learning personalization tools enable direct-to-traveler package assembly that bypasses traditional agency commission structures.
Industry Challenges
- Multilingual guide certification timelines:National interpreter standards require extensive training periods that lag behind inbound visitor language diversity.
- Legacy reservation system integration:Ryokan proprietors operate on paper-based or outdated digital platforms that resist connectivity with modern booking aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Tourism Market |
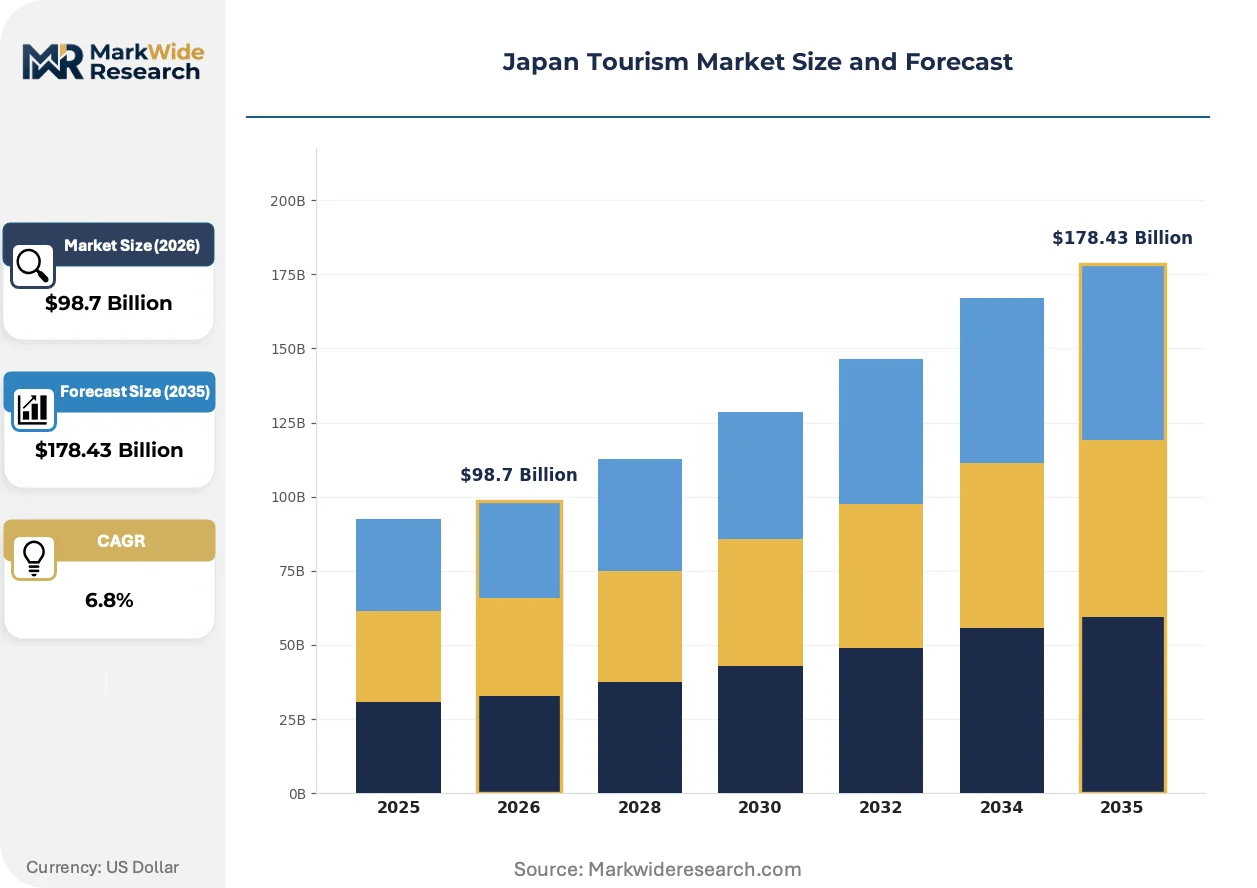
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Visitor Type: Leisure, Business, Medical, Educational Accommodation Type: Hotels, Ryokans, Hostels, Vacation Rentals Travel Mode: Air, Rail, Cruise, Bus Attraction Type: Cultural Sites, Natural Parks, Entertainment, Shopping |
| Companies Covered | UME Travel Co. Ltd, Inside Japan Tours, JTB Corp., Odynovo, Japan Deluxe Tours, Intrepid Travel, Reiwa Travel, One Life Adventures, Asia Highlights, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Tourism Market Strategic Shifts
Technology deployment and regulatory adaptation are compressing traditional intermediation layers while reshaping how visitors discover and purchase Japanese travel experiences.
Artificial intelligence itinerary assembly is collapsing the traditional travel agency value chain. Machine learning platforms analyze traveler preference signals to generate personalized day-by-day routing that previously required human consultant intervention. Independent travelers and small-group bookers are adopting these tools fastest, forcing legacy operators to reposition toward experience curation rather than logistics coordination.
METI tourism promotion frameworks now mandate sustainability reporting from accommodation providers receiving public marketing support. Properties must document energy efficiency, waste reduction, and community benefit metrics to maintain eligibility for national tourism organization co-promotion. This compliance burden falls heaviest on mid-scale ryokan operators with limited administrative capacity, creating segmentation pressure between certified and non-certified properties.
Direct booking behavior is fragmenting traditional distribution relationships. Experience-seeking travelers increasingly research through social platforms then transact on property or activity-provider websites, bypassing Online Travel Agency commission layers. This channel shift concentrates margin recovery with operators who invest in payment infrastructure and multilingual customer service, particularly visible in Tokyo and Osaka boutique hospitality segments.
Japan Tourism Market Segmentation
Japan's tourism market segments reflect tightly coordinated infrastructure dependencies where rail connectivity, seasonal capacity, and cultural authenticity create distinct operational boundaries for operators. Understanding these divisions reveals where margin concentrates and where regulatory constraints reshape competitive positioning.
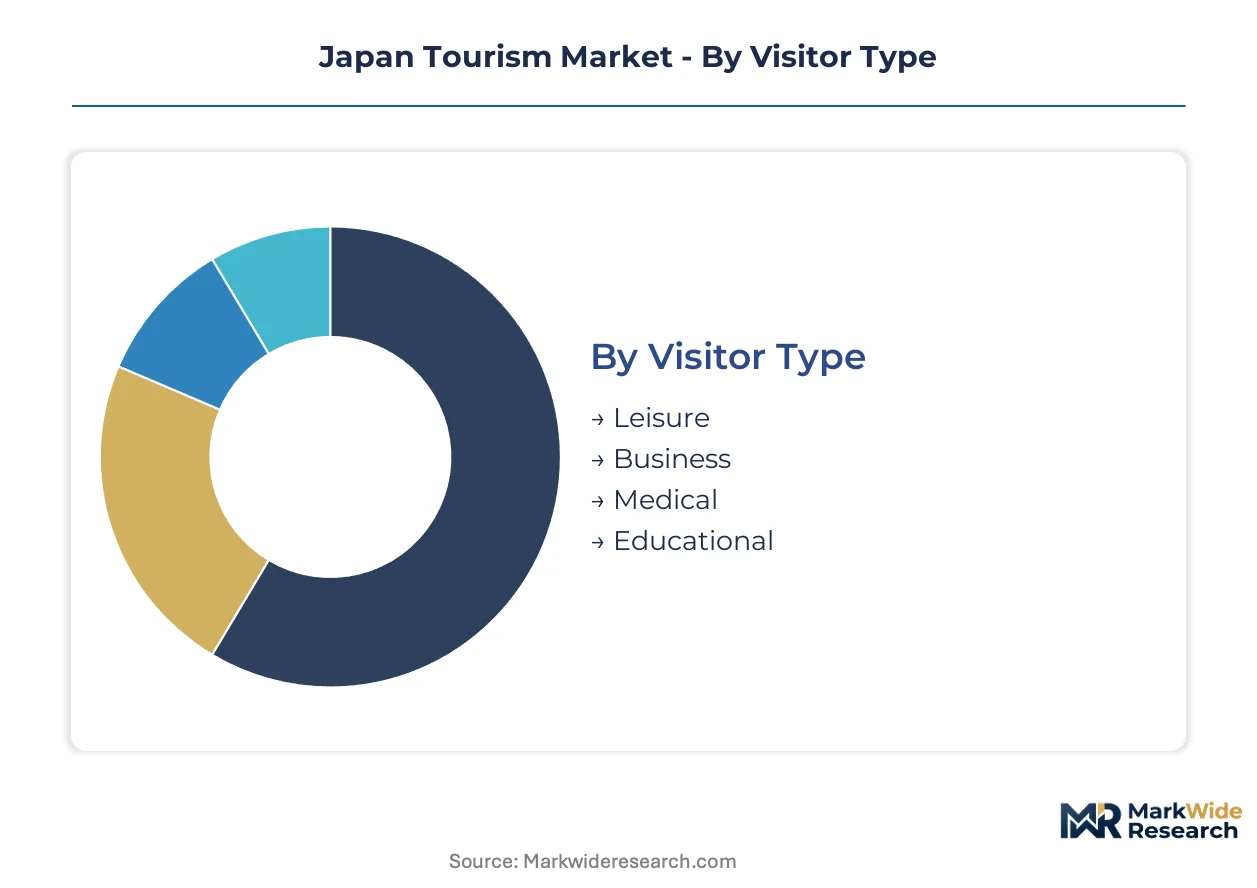
Visitor Type:
Mature leisure travel dominates current volume while emerging segments reshape booking cycles and geographic dispersal patterns.
- Leisure:Multi-day itineraries centered on cultural immersion, seasonal events, and regional cuisine drive the bulk of accommodation nights. Tokyo-Osaka-Kyoto corridor infrastructure captures the majority of this traffic, though METI regional revitalization incentives are redirecting flows toward secondary prefectures.
- Business:Corporate travel concentrates in Tokyo and Osaka financial districts with short-stay, high-frequency patterns. Convention center bookings and incentive travel packages generate concentrated demand spikes that align with fiscal calendar cycles rather than seasonal tourism patterns.
- Medical:PMDA-accredited facilities in regional cities attract wellness-oriented visitors seeking preventive care combined with cultural immersion. This segment generates extended stays and higher per-visitor expenditure than standard leisure travel.
- Educational:Language programs and cultural exchange initiatives drive long-duration bookings concentrated in university cities. Student housing networks and semester-aligned arrival patterns create predictable demand cycles distinct from commercial hospitality.
Leisure handles the majority of throughput; medical is the fastest mover on share.
Accommodation Type:
Cost tier stratification separates premium cultural authenticity from standardized efficiency and budget accessibility.
- Hotels:International chains and domestic operators deliver standardized service levels with multilingual staff and integrated booking platforms. Business districts in Tokyo and Osaka concentrate inventory, while regional cities expand supply to capture dispersal incentives.
- Ryokans:Traditional Japanese inns command premium pricing through tatami flooring, kaiseki dining, and onsen access. Labor-intensive operations face generational staffing constraints that limit capacity expansion despite sustained demand from experience-seeking international visitors.
- Hostels:Capsule and shared-room formats target budget-conscious independent travelers and backpacker segments. Urban centers and transport hubs concentrate supply, with social common areas designed to facilitate peer-to-peer itinerary sharing.
- Vacation Rentals:Private apartments and guesthouses face tightening municipal restrictions in Kyoto and Kanazawa historic districts. Regulatory caps preserve neighborhood character while constraining alternative supply during peak seasonal demand.
Hotels manage the highest absolute room nights; ryokans capture the steepest pricing premium per available room.
Travel Mode:
Volume concentration in air and rail reflects infrastructure investment patterns that constrain modal flexibility.
- Air:International gateway function concentrates in Narita, Haneda, Kansai, and Chubu airports with long-haul connectivity driving inbound visitor composition. Domestic air routes serve peripheral islands and Hokkaido winter destinations where rail coverage remains incomplete.
- Rail:Shinkansen network density defines domestic tourism geography with Tokyo-Osaka corridor operating at capacity ceilings during cherry blossom and autumn foliage seasons. JR Pass products and regional rail passes structure multi-city itinerary economics for international visitors.
- Cruise:Port calls at Yokohama, Kobe, and Nagasaki generate concentrated shore excursion demand with limited overnight stays. Regional port infrastructure investments aim to extend visitor dispersal beyond gateway cities.
- Bus:Highway express and tour coach services capture price-sensitive domestic travelers and regional package tours. Night bus routes between major cities compete with rail on cost while sacrificing speed and comfort.
Rail carries the dominant share of intercity movement; air is expanding most quickly as Southeast Asian visitor volumes accelerate.
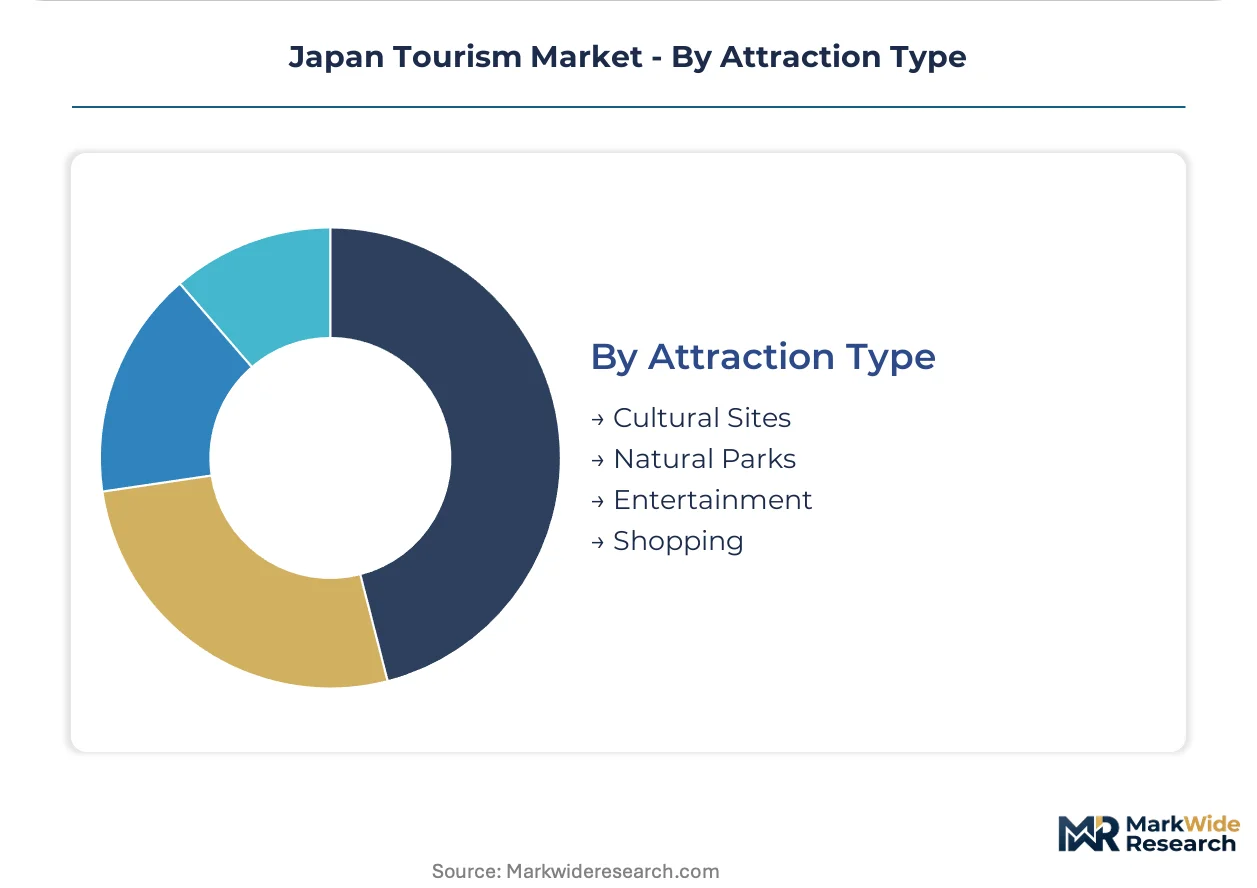
Attraction Type:
Geographic clustering determines visitor flow management challenges and revenue capture efficiency for operators.
- Cultural Sites:Temples, shrines, castles, and historic districts generate concentrated foot traffic requiring timed entry systems and capacity management. Kyoto's UNESCO World Heritage concentration exemplifies overtourism pressures that municipal regulations attempt to disperse.
- Natural Parks:National park designation covers mountainous regions, coastal areas, and volcanic landscapes where seasonal access varies dramatically. Hokkaido and Tohoku winter positioning targets underdeveloped ski and onsen infrastructure for premium outdoor hospitality expansion.
- Entertainment:Theme parks, digital art museums, and immersive experiences concentrate in Tokyo and Osaka metropolitan areas with high repeat-visit potential from domestic markets. Foreign visitor ticketing platforms require integration with multilingual reservation systems.
- Shopping:Duty-free retail, department store tourism, and specialty commercial districts attract Southeast Asian visitors with specific merchandise preferences. Ginza, Shibuya, and Osaka's Shinsaibashi form primary concentration nodes with dedicated tourist service infrastructure.
Cultural sites absorb the highest visitor hours; natural parks are gaining share fastest as regional revitalization incentives redirect flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travelers from Southeast Asia represent the fastest-growing buyer archetype, while digital nomad visa holders extend booking cycles across Japan's prefectural infrastructure. Domestic metropolitan corridors absorb concentrated demand as regional revitalization incentives redirect flows toward secondary destinations.
Kanto/Tokyo
International gateway functions and business travel concentrate demand in Tokyo's 23 wards and surrounding prefectures. METI tourism promotion frameworks coordinate with the Japan National Tourism Organization to enforce accommodation quality benchmarks across this corridor. Haneda and Narita airports anchor air connectivity while Shinkansen terminals structure multi-city itinerary economics for inbound visitors.
Kansai/Osaka
Cultural heritage tourism and convention center bookings drive distinct demand cycles in Osaka, Kyoto, and Nara prefectures. Municipal regulations in Kyoto impose strict short-term rental caps to preserve historic district character. The Keihanshin industrial zone integrates hospitality infrastructure with manufacturing supply chains, creating hybrid business-leisure visitor profiles.
Chubu/Nagoya
Automotive industry supply networks generate concentrated business travel with fiscal calendar-aligned demand spikes. Centrair International Airport serves as an alternative gateway reducing Tokyo corridor congestion. Regional hospitals in Nagoya and Gifu prefectures pursue PMDA accreditation to capture medical tourism flows seeking preventive care packages.
Hokkaido
Winter sports and onsen infrastructure attract premium outdoor hospitality investment across Niseko, Furano, and Sapporo sub-regions. Underdeveloped ski resort capacity offers white-space expansion as regional revitalization zone incentives subsidize accommodation development. Domestic air routes compensate for incomplete rail coverage during heavy snow periods.
Kyushu
Cruise port calls at Nagasaki and Fukuoka generate concentrated shore excursion demand with limited overnight stays. Volcanic landscapes and coastal hot springs differentiate natural park offerings from Honshu corridor alternatives. Prefectural governments integrate ferry networks with rail passes to extend visitor dispersal across the island.
Japan Tourism Market Competitive Environment
Channel-controlling players compete with product-specialist players across package assembly, direct booking platforms, and culturally immersive routing. The market structure fragments across legacy tour operators with domestic network density, digital-native platforms bypassing agency layers, and niche specialists targeting experience-seeking segments. Three archetypes dominate: rail-corridor package assemblers, direct-to-consumer booking engines, and small-group cultural immersion curators. Competitive moves concentrate on AI-native itinerary personalization and strategic partnerships with prefectural tourism boards.
Within the legacy operator tier, JTB Corp. anchors package tour dominance through decades of rail corridor integration. Among digitally native platforms, Odynovo exemplifies direct-to-consumer positioning that collapses traditional agency commission structures. Specialists in culturally immersive routing include Inside Japan Tours, which occupies a position distinct from mass-market alternatives through small-group format differentiation.
| Leading Market Players |
|---|
| UME Travel Co. Ltd |
| Inside Japan Tours |
| JTB Corp. |
| Odynovo |
| Japan Deluxe Tours |
| Intrepid Travel |
| Reiwa Travel |
| One Life Adventures |
| Asia Highlights |
| Others |
Value Chain & Pricing Dynamics
Japan's inbound aviation seat inventory concentrates in Tokyo and Osaka gateway airports, directly determining where hospitality operators capture rate premiums and where price competition intensifies among secondary prefectural suppliers.
Pricing Analysis
Cost-plus contracts with fuel surcharge indexation dominate international air charter agreements serving Japanese inbound routes. Ryokan properties command premium-mid-economy pricing differentiation based on METI sustainability certification status and tatami room scarcity. Pricing pressure stems from Southeast Asian carrier capacity additions on Bangkok-Tokyo and Jakarta-Osaka corridors. Independent travelers booking direct-to-property channels exhibit highest price sensitivity, while medical tourism packages show lowest elasticity due to bundled care premiums.
Supply Chain Analysis
Upstream aviation feedstock dependence on Singapore and South Korea jet fuel refining capacity exposes Japanese carriers to regional energy price volatility. Hospitality linen and amenity sourcing draws from China and Vietnam manufacturing bases. Single-source vulnerability concentrates in Hokkaido winter resort food supply chains during snow-blocked ground transport periods. Distribution runs through JR Group rail networks and domestic air feeder routes to final accommodation nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's tourism platform economics are inflecting around AI-native itinerary assembly ecosystems that collapse traditional agency commission layers and restructure interoperability between rail, accommodation, and experience booking systems.
For Market Incumbents: Build data network moats through exclusive prefectural tourism board partnerships that lock in AI training data access. JTB Corp. and legacy rail-integrated operators must consolidate fragmented ryokan reservation systems before digital-native platforms achieve critical mass. Threat substitution comes from Odynovo-style direct booking engines that bypass traditional agency layers. Certification investment in METI sustainability frameworks provides channel control leverage with government co-promotion eligibility.
For New Entrants and Emerging Players: Build out white-space positioning in Tohoku and Hokkaido winter hospitality infrastructure where regional revitalization subsidies reduce capital intensity. Medical tourism package assembly represents the most penetrable segment given PMDA accreditation timelines that deter incumbent fast-follower responses. Go-to-market execution should anchor on prefectural government co-development agreements that secure marketing support and land access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hotel platform operators that acquired distressed ryokan inventory during previous demand contractions. Long-term viability framing centers on whether AI-native booking penetration reaches threshold levels that obsolete traditional package tour economics. Acquisition target archetypes include regional rail-integrated hospitality operators with untapped digital channel potential. Signal to watch is JR Group API openness policy shifts that determine third-party platform interoperability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Itinerary Platform Launch | Machine learning personalization collapses traditional JTB Corp. agency commission structures. |
| PMDA Medical Tourism Certification | Regional hospital accreditation unlocks preventive care package bundling with cultural immersion. |
| Prefectural Tourism Board Partnership | METI co-promotion eligibility secures marketing subsidies and dispersal incentive access. |
| Ryokan Reservation System Integration | Legacy platform connectivity addresses paper-based operator resistance to modern booking aggregators. |
| Hokkaido Winter Infrastructure Expansion | Niseko and Furano ski capacity buildout captures premium outdoor hospitality white space. |
Study Parameters
Operator-level perspectives from ryokan proprietors, JR Group network planners, prefectural tourism board officials, and PMDA accreditation specialists anchored the qualitative base. Primary interview insights combined with secondary validation from Japan National Tourism Organization visitor statistics, METI regional revitalization policy documents, and JR Group annual securities filings. Bottom-up accommodation capacity modeling and top-down inbound arrival projections were triangulated against rail pass sales data and international aviation seat capacity disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions covering visitor type, accommodation category, travel mode, and attraction clustering. CAGRs were derived from trend extrapolation adjusted for policy intervention effects. Forecast inputs incorporated digital nomad visa uptake trajectories, Southeast Asian middle-class expansion rates, and Shinkansen peak capacity constraints during seasonal demand spikes.
Sensitivities concentrate around visa policy reversals, aviation fuel cost volatility, and AI platform adoption speed among independent travelers. Forecasts reflect assumptions on regional dispersal incentive continuity and rail infrastructure expansion timelines. Quarterly review of METI policy announcements, PMDA accreditation awards, and JR Group partnership disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
New Zealand Sports Tourism Market
Travel and Tourism
Domestic Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Customised Holidays Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Hong Kong Tourism Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
Dark Tourism Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
North America Driving Vacation Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Travel and Tourism Market
Travel and Tourism
Japan Travel Retail Market