
 Middle East and Africa Business Process Outsourcing (BPO) Market | 2026-2036
Middle East and Africa Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Business Process Outsourcing (BPO) Market Foresight
The premium-commodity split in Middle East and Africa BPO is shifting toward outcome-based contracts versus transactional seat pricing. Accenture plc leverages its consulting heritage to anchor complex finance-and-accounting transformations for Gulf banks. Raya CX competes on Arabic-native customer-support depth across Egyptian and Saudi operations. Teleperformance SE extends its footprint through hybrid delivery models blending onshore Egyptian talent with offshore Moroccan capacity.
Business Process Outsourcing denotes the contractual delegation of specific operational functions—customer interaction management, information-technology service desks, payroll processing, or accounts-payable workflows—to third-party specialists, typically governed by service-level agreements specifying response-time thresholds, first-call resolution rates, and data-security protocols. Its commercial purpose centers on converting fixed labor costs into variable expenditure while accessing process expertise unavailable in-house. Customer Support commands the largest revenue pool among service types, though IT Services generates superior margins through cloud-migration and cybersecurity adjuncts. The BFSI vertical dominates contract value given compliance-intensive documentation requirements, while Healthcare outsourcing accelerates fastest as Gulf states privatize hospital administration. Hybrid engagement models now lead new contract structures, supplanting pure offshore arrangements that once defined regional BPO procurement.
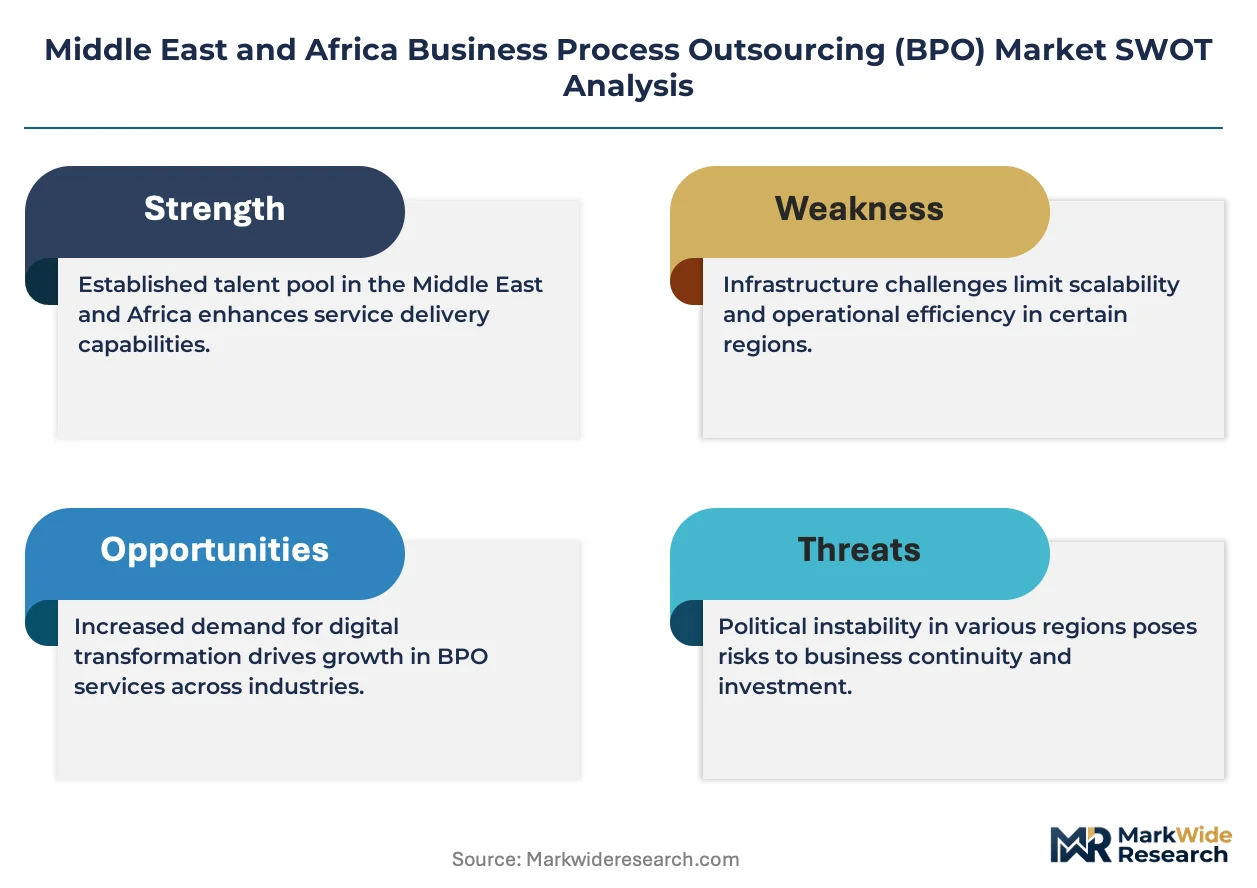
South Africa's Information Regulator enforces POPIA compliance for cross-border data flows, compelling providers to certify local hosting infrastructure or forfeit public-sector contracts. Egypt's General Authority for Investment and Free Zones coordinates tax incentives within technology parks, directly shaping where delivery centers locate. Saudi Arabia's National Data Management Office imposes data-sovereignty requirements on financial-services outsourcing. Stakeholders must weigh localization mandates against talent-pool depth when selecting between Egyptian Arabic fluency and South African English-accent neutrality for voice-channel operations.
Market Dynamics
Data-sovereignty mandates from Gulf regulators are forcing BPO providers to reconfigure delivery architectures, shifting from centralized offshore hubs toward distributed national infrastructures that fragment economies of scale.
Growth Catalysts
- POPIA enforcement:South Africa's Information Regulator mandates local data hosting, compelling infrastructure investment that upgrades overall service reliability for financial-services clients.
- Arabic-language depth:Egypt's technology parks cultivate native Arabic talent pools, attracting European and Middle Eastern customer-support contracts that require dialect-specific cultural fluency.
- Hybrid engagement models:Blended onshore-offshore delivery structures reduce per-interaction costs while maintaining compliance with Saudi National Data Management Office localization requirements.
Market Restraints
- Power infrastructure volatility:Unreliable grid supply in Nigerian and Kenyan delivery clusters forces diesel-generator dependency, inflating operational expenditure unpredictably.
- Currency mismatch exposure:Egyptian pound and Nigerian naira depreciation against dollar-denominated client contracts compresses margin realization for providers with unhedged positions.
- Technical talent scarcity:Cloud-architecture and cybersecurity specialists concentrate in Johannesburg and Cairo, leaving secondary cities dependent on expensive relocation packages.
Strategic Opportunities
- Moroccan French-Arabic bridge:Casablanca-Rabat corridor offers untapped capacity for Francophone African and European Union customer operations with favorable timezone alignment.
- Healthcare privatization:Gulf state hospital administration outsourcing creates first-mover advantage for providers building HIPAA-equivalent compliance frameworks.
- AI-augmented quality assurance:Real-time speech analytics integration with human agent workflows enables outcome-based pricing that captures value from resolution-rate improvements.
Industry Challenges
- Agent attrition management:Cairo and Johannesburg contact centers experience annual turnover exceeding 35%, draining recruitment budgets and degrading client relationship continuity.
- Legacy system integration:Gulf banking clients operate on 1990s-era core banking platforms that resist API-based connectivity, extending implementation timelines and inflating customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Business Process Outsourcing (BPO) Market |
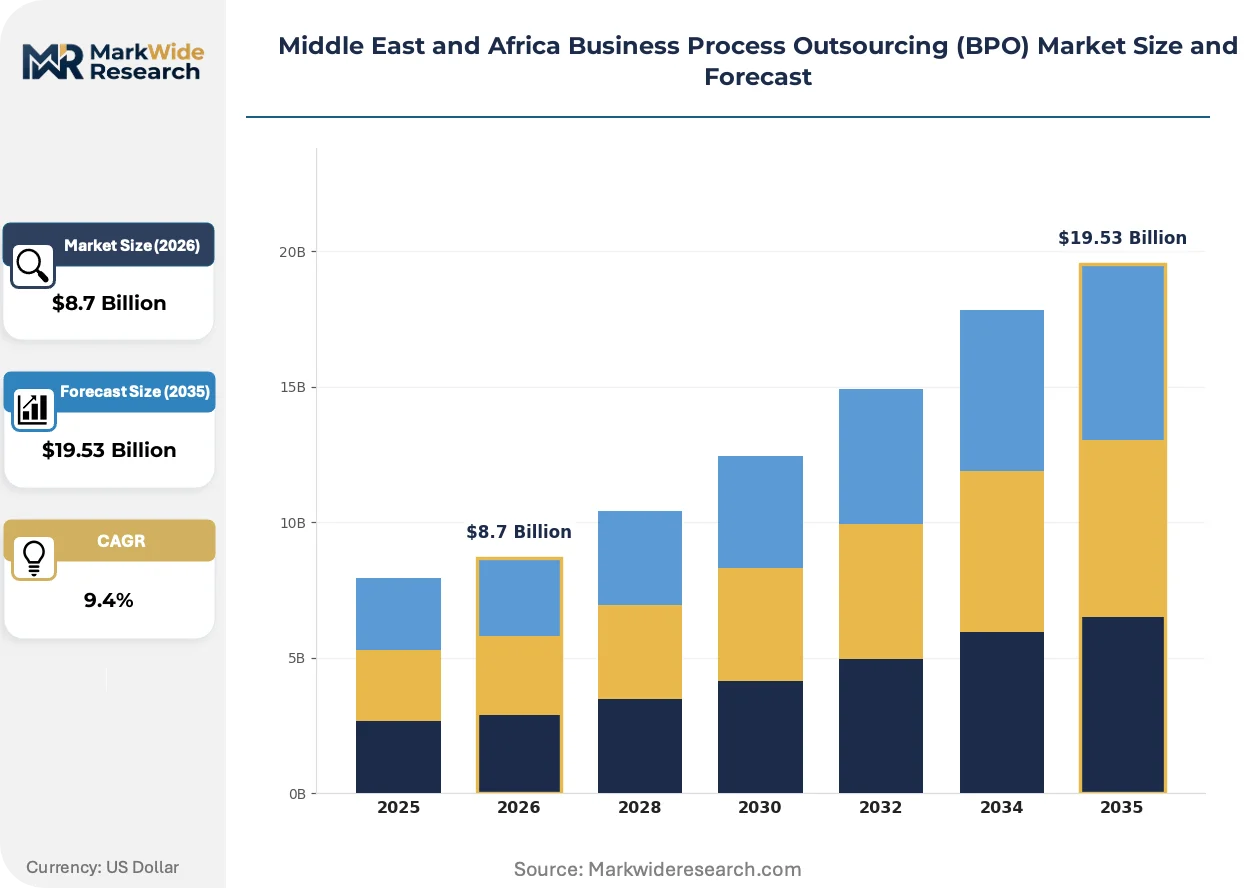
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customer Support, IT Services, Human Resources, Finance & Accounting Industry Vertical: Telecommunications, Healthcare, Retail, BFSI Engagement Model: Onshore, Offshore, Nearshore, Hybrid Delivery Mode: Cloud-Based, On-Premise, Outsourced, In-House |
| Companies Covered | Cognizant Technology Solutions Corporation, Infosys Limited, Accenture plc, Raya CX, Wipro Limited, Teleperformance SE, Capgemini SE, Genpact Ltd., Concentrix Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Business Process Outsourcing (BPO) Market Shifts & Advancements
Intelligent automation is rewriting workforce composition across Middle East and Africa delivery centers, compressing the ratio of human agents to automated touchpoints while elevating remaining staff toward exception-handling and advisory functions.
Conversational AI platforms with natural-language processing capabilities are converging with robotic process automation backends to handle tier-one customer queries across Arabic dialects. Saudi and UAE banks are deploying these systems at pilot scale with 18-month full-rollout targets. This convergence is compressing headcount expansion plans for new contract ramps, forcing providers to retrain existing agents toward complex dispute resolution.
Saudi Arabia's National Data Management Office and UAE's data protection regulations are imposing data-sovereignty requirements that prohibit cross-border processing of citizen financial records. Industrial consequence mandates in-country server deployment and staff localization for BFSI contracts. Providers are responding by establishing certified facilities in Riyadh and Abu Dhabi despite 40-60% cost premiums over Egyptian alternatives.
Buyers are unbundling after-sales support from core outsourcing agreements, creating separate procurement streams for technical helpdesk versus customer care. This disintermediation allows Gulf banks to award cybersecurity-intensive contracts to specialized IT services firms while retaining voice operations with traditional BPO players. The pattern is most visible in UAE and Qatar, where procurement teams now run parallel RFP processes for distinct service layers.
Middle East and Africa Business Process Outsourcing (BPO) Market Segmentation
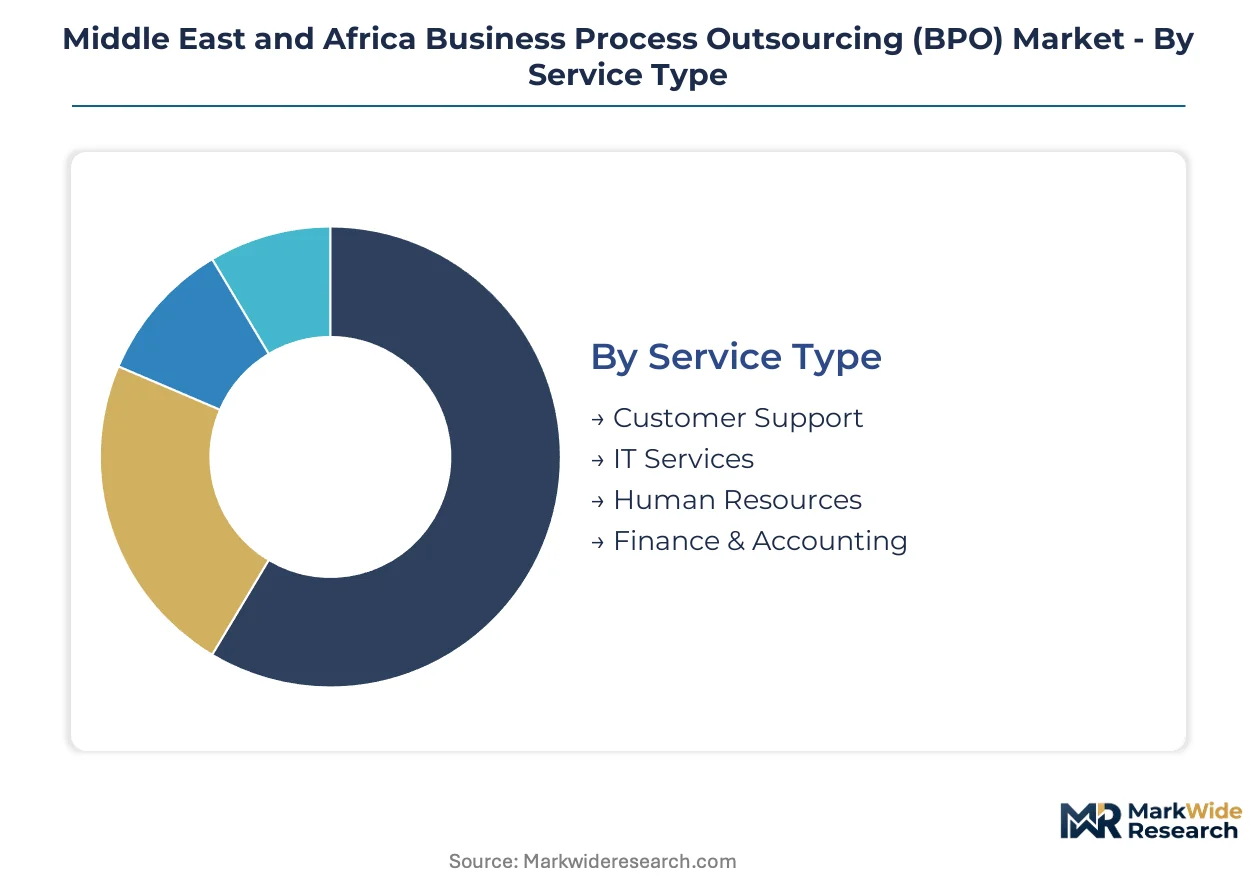
Segmentation in Middle East and Africa BPO reveals how regulatory fragmentation and localization mandates reshape procurement patterns across service lines. Buyers select engagement architectures based on data-sovereignty exposure, talent-pool depth, and cost-positioning trade-offs.
Service Type:
Certification burdens vary sharply: HIPAA-equivalent frameworks govern healthcare customer interactions, while PCI-DSS compliance dominates finance-and-accounting workflows. IT Services carry ISO 27001 and cloud-specific attestations that extend sales cycles but lock in multi-year contracts.
- Customer Support:Voice, chat, and email interaction management across Arabic dialects and European languages. Egyptian technology parks anchor capacity for Gulf and European clients requiring native Arabic fluency. POPIA enforcement in South Africa compels local hosting infrastructure for financial-services voice operations.
- IT Services:Cloud migration, cybersecurity operations, and service desk management. Saudi National Data Management Office mandates in-country server deployment for citizen financial records, inflating infrastructure costs. Margin structures exceed voice-channel economics through outcome-based pricing tied to uptime guarantees.
- Human Resources:Payroll processing, benefits administration, and talent acquisition support. South African providers leverage POPIA-compliant infrastructure to capture public-sector contracts requiring local data residency.
- Finance & Accounting:Accounts payable, receivable management, and regulatory reporting. Gulf banking clients demand staff localization for compliance-intensive documentation, fragmenting delivery across Riyadh, Abu Dhabi, and Cairo clusters.
Leading the category by volume: Customer Support. Growing fastest: IT Services.
Industry Vertical:
Vertical-specific compliance regimes segment procurement behavior. BFSI contracts carry data-sovereignty riders absent in retail engagements, while healthcare privatization creates first-mover advantages for HIPAA-equivalent certified providers.
- BFSI:Banking, financial services, and insurance outsourcing with intensive documentation requirements. Saudi and UAE regulators prohibit cross-border processing of citizen financial records, mandating national infrastructure. Contract values concentrate here due to compliance complexity and multi-year tenures.
- Healthcare:Hospital administration, claims processing, and patient interaction management. Gulf state privatization programs accelerate outsourcing adoption for non-clinical functions. Providers building healthcare-specific compliance frameworks capture expanding contract flow.
- Telecommunications:Subscriber acquisition, retention, and technical support. Moroccan capacity serves Francophone African markets with favorable timezone alignment to European operations.
- Retail:E-commerce customer care, order management, and returns processing. Seasonal demand spikes drive preference for hybrid engagement models with elastic capacity.
Volume leadership sits with BFSI. Healthcare climbs fastest on privatization tailwinds.
Engagement Model:
Cost-positioning and compliance exposure determine model selection. Pure offshore economics erode against data-localization mandates, elevating hybrid architectures that blend Egyptian cost advantages with Saudi onshore presence.
- Hybrid:Blended delivery combining onshore compliance presence with offshore cost optimization. Teleperformance deploys Egyptian talent alongside Moroccan capacity to satisfy European and Gulf clients simultaneously. This architecture now dominates new contract structures.
- Onshore:Fully localized delivery within client jurisdiction. Saudi National Data Management Office and UAE data protection regulations compel this model for BFSI citizen data. Riyadh and Abu Dhabi facilities command 40-60% cost premiums over Egyptian alternatives.
- Offshore:Centralized delivery from lower-cost jurisdictions with cross-border data flows. Regulatory compression restricts this model to non-sensitive retail and telecommunications workflows.
- Nearshore:Delivery from adjacent geographies with timezone and cultural alignment. Casablanca-Rabat corridor serves European Union and Francophone African markets.
Hybrid engagement captures the largest contract flow. Onshore is expanding most quickly on regulatory compulsion.
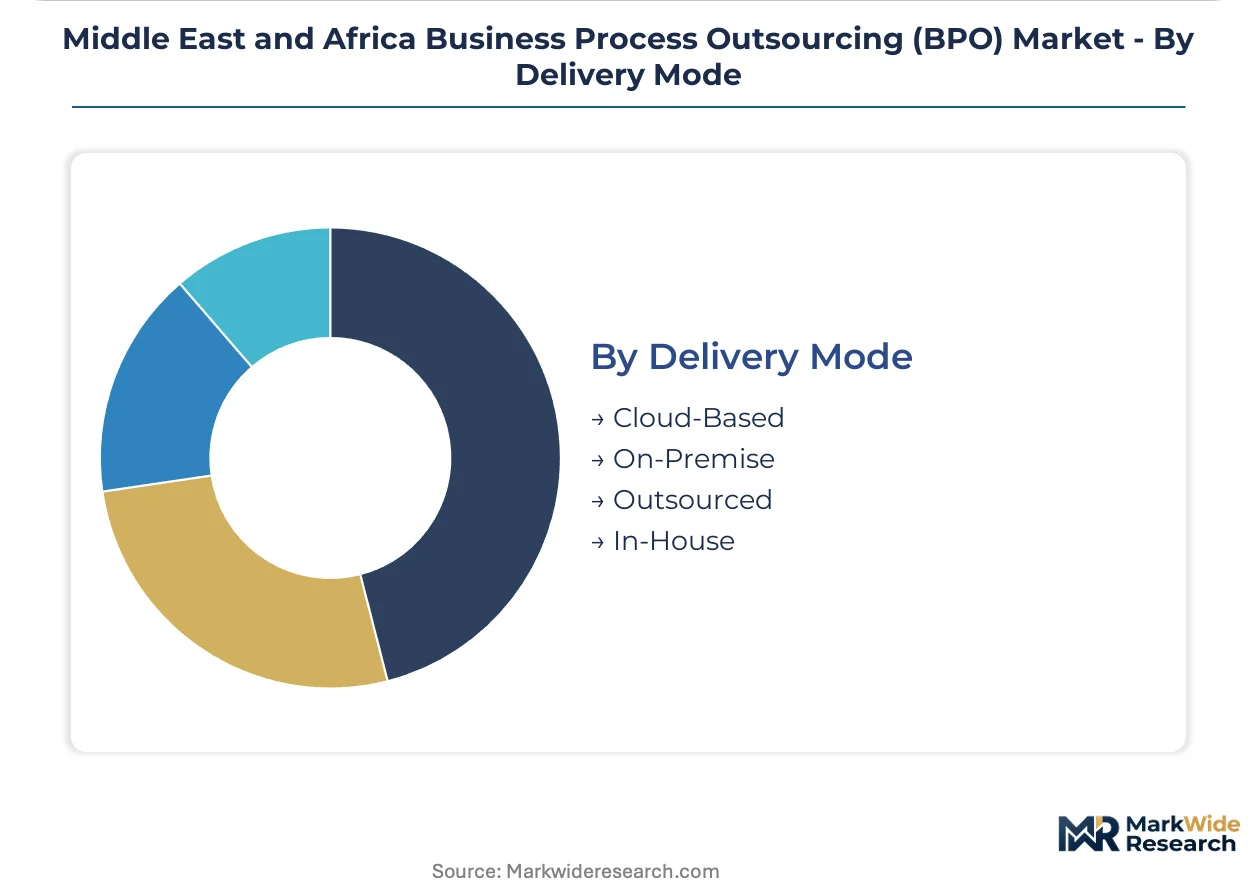
Delivery Mode:
Infrastructure ownership and control levels segment buyer preferences. Cloud-based delivery accelerates for IT Services, while on-premise retention persists in BFSI for core banking platform integration.
- Cloud-Based:Third-party hosted infrastructure with elastic scaling. Saudi and UAE cloud adoption targets elevate demand for certified hyperscaler partnerships. Cybersecurity adjuncts generate margin premiums over baseline compute provisioning.
- On-Premise:Client-owned infrastructure with provider staff embedding. Gulf banking clients retain this model for 1990s-era core platforms resisting API connectivity. Implementation timelines extend due to legacy system customization requirements.
- Outsourced:Full function delegation to third-party infrastructure and staff. The dominant commercial construct across Customer Support and Finance & Accounting segments.
- In-House:Captive operations with limited third-party involvement. Retained primarily for strategic functions and compliance-sensitive executive workflows.
Outsourced delivery leads by contract volume. Cloud-Based gains share fastest on IT Services expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cairo's technology parks anchor Middle East and Africa BPO capacity, drawing European and Gulf customer-support contracts through Arabic-native talent pools and government-coordinated tax incentives.
Egypt
Egypt's General Authority for Investment and Free Zones coordinates tax incentives within technology parks, directly shaping delivery center location decisions. Cairo and Alexandria clusters attract Gulf banking clients seeking Arabic dialect fluency for voice-channel operations. Government technology parks cultivate native Arabic talent pools that European and Middle Eastern clients prize for cultural alignment.
Saudi Arabia
Saudi Arabia's National Data Management Office imposes data-sovereignty requirements on financial-services outsourcing, compelling in-country server deployment. Riyadh facilities command substantial cost premiums over Egyptian alternatives but capture BFSI contracts prohibited from cross-border processing. Staff localization mandates fragment delivery architectures away from centralized offshore hubs.
United Arab Emirates
UAE data protection regulations prohibit cross-border processing of citizen financial records, driving certified facility establishment in Abu Dhabi and Dubai. Procurement teams run parallel RFP processes for technical helpdesk versus customer care, unbundling after-sales support from core agreements. Cloud adoption targets elevate demand for certified hyperscaler partnerships.
South Africa
South Africa's Information Regulator enforces POPIA compliance for cross-border data flows, compelling local hosting infrastructure certification. Johannesburg and Cape Town delivery centers leverage English-accent neutrality for voice-channel operations serving British and Australian clients. Public-sector contracts require local data residency, upgrading service reliability for financial-services clients.
Morocco
Morocco's Casablanca-Rabat corridor offers untapped capacity for Francophone African and European Union customer operations with favorable timezone alignment. Teleperformance deploys Moroccan capacity alongside Egyptian talent to satisfy European and Gulf clients simultaneously. French-Arabic bilingual depth creates bridge positioning for multiregional contract capture.
Middle East and Africa Business Process Outsourcing (BPO) Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform orchestrators across Middle East and Africa BPO procurement. The vendor base spans three tiers: global consultancies anchoring complex finance-and-accounting transformations, regional specialists competing on Arabic-native customer-support depth, and scale-driven contact center operators deploying hybrid delivery models. Dominant competitive moves include hybrid engagement architecture deployment and outcome-based contract structuring displacing transactional seat pricing.
Within the global consultancy tier, Accenture plc exemplifies consulting-heritage positioning for Gulf bank transformations. Among regional Arabic-depth specialists, Raya CX occupies a position across Egyptian and Saudi operations. At the scale-driven hybrid delivery vector, Teleperformance SE represents blended onshore-offshore architecture deployment.
| Leading Market Players |
|---|
| Cognizant Technology Solutions Corporation |
| Infosys Limited |
| Accenture plc |
| Raya CX |
| Wipro Limited |
| Teleperformance SE |
| Capgemini SE |
| Genpact Ltd. |
| Concentrix Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed technology park operators and private-equity-rolled-up contact center platforms anchor supply-side concentration, translating facility ownership patterns into pricing discipline that fragments across compliance tiers rather than pure cost competition. Egyptian government incentives compress baseline seat rates while Saudi localization mandates inflate premium-tier delivery premiums, creating divergent pricing architectures within the same contract portfolio.
Pricing Analysis
Outcome-based pricing tied to first-call resolution rates and uptime guarantees anchors contract structures for IT Services and complex finance-and-accounting workflows. Price differentiation separates POPIA-certified South African infrastructure from Egyptian technology park capacity, with certification level and geographic delivery cost as primary tiering mechanisms. Pricing pressure stems from Egyptian pound depreciation against dollar-denominated contracts, compressing unhedged provider margins. Retail and e-commerce buyers exhibit highest price sensitivity, while BFSI clients prioritize compliance assurance over per-seat economics.
Supply Chain Analysis
Regional distribution centers in Cairo, Johannesburg, and Casablanca form hub-and-spoke patterns for talent deployment and client proximity. Supply concentration centers on Egypt, South Africa, and Morocco as primary delivery clusters. Raw material dependencies include cloud compute capacity from hyperscaler partnerships, commercial real estate in government technology parks, and Arabic-native labor pools with dialect-specific training. Single-source vulnerability runs through concentrated hyperscaler relationships for certified cloud infrastructure. Distribution feeds from centralized recruitment pipelines in Cairo and Alexandria toward dispersed client sites across the Gulf and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as data-sovereignty mandates force subscale providers to surrender public-sector contracts to certified competitors with localized infrastructure investment capacity.
For Market Incumbents: Deploy hybrid engagement architecture as the primary defensive lever. Establish certified facilities in Riyadh and Abu Dhabi to capture BFSI contracts prohibited from cross-border processing, while maintaining Egyptian cost bases for non-sensitive workflows. Accenture and Teleperformance demonstrate this bifurcation strategy. Counter agent attrition exceeding 35% in Cairo and Johannesburg through structured career-pathing toward exception-handling roles displaced by conversational AI deployment. For New Entrants and Emerging Players: Healthcare privatization in Gulf states offers the most penetrable vertical for specialist entrants building HIPAA-equivalent compliance frameworks from inception. Target hospital administration outsourcing in Saudi Arabia and UAE where incumbent presence remains thin. Moroccan French-Arabic bilingual capacity provides geographic differentiation for European Union customer operations underserved by Egyptian-centric supply. Partner with established hyperscalers for cloud certification rather than building proprietary infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional Arabic-depth specialists with existing Saudi facility certifications in Riyadh. Long-term viability hinges on five-to-ten year positioning around AI-augmented quality assurance capabilities that enable outcome-based contract capture. Watch for POPIA enforcement intensity in South Africa as signal for public-sector contract flow redirection toward compliant infrastructure owners.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Engagement Architecture Deployment | Blends Egyptian cost optimization with Saudi compliance presence to capture BFSI contracts under National Data Management Office mandates. |
| Healthcare Compliance Framework Buildout | HIPAA-equivalent certification positions providers for Gulf hospital administration privatization programs accelerating outsourcing adoption. |
| Conversational AI Platform Integration | Real-time speech analytics with Arabic dialect NLP compresses headcount expansion while elevating remaining agents toward complex resolution. |
| POPIA-Certified Infrastructure Investment | Local hosting certification in Johannesburg and Cape Town unlocks South African public-sector contracts requiring data residency. |
| Moroccan Capacity Expansion | Casablanca-Rabat corridor French-Arabic depth captures Francophone African and European Union customer operations with timezone alignment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across BPO operations directors, Gulf banking procurement leads, Egyptian technology park administrators, and South African Information Regulator compliance officers. Secondary sources included POPIA enforcement notices, Saudi National Data Management Office circulars, Egyptian General Authority for Investment incentive disclosures, and hyperscaler partnership certifications. Bottom-up contract value aggregation and top-down macroeconomic scaling provided triangulation.
Segmentation-level granularity modeled service type, industry vertical, engagement model, and delivery mode dimensions across the analysis window. CAGRs derived from trend extrapolation of contract flow data and regulatory implementation timelines. Forecast inputs incorporated technology park capacity expansion schedules, Gulf healthcare privatization program pacing, and conversational AI pilot-to-production conversion rates.
Caveats apply where currency volatility in Egyptian pound and Nigerian naira, or accelerated AI adoption compressing agent headcount demand, could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market