
 Middleoffice BPO Services Market | 2026-2036
Middleoffice BPO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middleoffice BPO Services Market Insights
Hedge fund administration is expanding as a buyer vertical, displacing traditional asset manager dominance in middle-office outsourcing. EXL Service leverages domain-specific analytics platforms to anchor its position in risk management workflows. Wipro sustains delivery scale across multiple geographies, while Genpact specializes in regulatory technology integration for compliance-heavy clients. Accenture competes through consulting-led transformation engagements that extend beyond pure process outsourcing.
Middleoffice BPO services encompass post-trade processing, portfolio accounting, reconciliation, corporate actions management, and regulatory reporting executed by third-party providers on behalf of financial institutions. These functions require sub-second data validation, ISO 15022/20022 messaging compatibility, and exception-based workflow architectures designed to reduce manual intervention in high-volume transaction environments. Trade support and settlement processing segments dominate current revenue pools given their maturity and non-discretionary nature, while risk management and compliance monitoring represent faster-expanding categories as Basel III, SEC liquidity rule, and EU SFDR obligations deepen. Cloud-based and hybrid delivery models are capturing disproportionate growth as legacy onshore installations face cost pressure and talent scarcity.
The SEC, FCA, and ECB collectively shape demand through mandatory trade reporting, liquidity stress testing, and operational resilience directives that force buy-side firms to upgrade middle-office infrastructure or outsource to compliant specialists. GDPR and emerging US state privacy laws add data residency complexity that influences delivery model selection across jurisdictions. Stakeholders must monitor evolving AI governance frameworks and their intersection with fiduciary duty standards when automating investment decision support functions.
Market Dynamics
Cloud-native delivery architectures are compressing cost structures for post-trade processing while forcing incumbent providers to re-platform legacy infrastructure. Asset managers now demand ISO 20022 messaging compatibility and sub-second reconciliation as table stakes, reshaping competitive requirements across the value chain.
Growth Catalysts
- SEC liquidity rule mandates:US-registered investment advisers must demonstrate daily liquidity stress testing capabilities. Firms lacking internal infrastructure accelerate outsourcing to compliant specialists.
- Hedge fund administration surge:Alternative asset managers now represent the fastest-expanding buyer vertical. Their complex multi-asset strategies require specialized corporate actions processing and tax lot accounting expertise.
- AI-enabled exception management:Machine learning models trained on historical settlement failures now predict and preempt breaks before they cascade. Providers deploying these tools capture disproportionate wallet share from manual-heavy competitors.
Market Restraints
- Talent scarcity in specialized domains:Professionals possessing both SWIFT messaging expertise and derivatives product knowledge command premium compensation. This input cost inflation compresses margins for labor-intensive reconciliation services.
- Data residency fragmentation:GDPR requirements and emerging US state privacy laws fragment cloud deployment architectures. Providers must maintain redundant infrastructure across jurisdictions, elevating capital intensity.
- Legacy system entrenchment:Tier-1 asset managers operate decades-old portfolio accounting platforms with deep customizations. Migration friction sustains suboptimal in-house operations and delays outsourcing decisions.
Strategic Opportunities
- Poland nearshore expansion:Warsaw and Krakow talent pools offer European timezone coverage at cost structures below London or Dublin. Providers establishing delivery centers here capture EU asset manager demand seeking regulatory proximity.
- SFDR regulatory reporting services:EU sustainable finance disclosure requirements mandate granular ESG data aggregation across holdings. Specialist providers can build defensible positions in this compliance-heavy workflow.
- Blockchain-DLT settlement convergence:Distributed ledger infrastructure for securities settlement is maturing from pilot to production. Early integration with these networks positions providers for T+0 settlement workflows.
Industry Challenges
- ISO 20022 migration complexity:The SWIFT message format transition requires simultaneous updates to parsing engines, validation rules, and counterparty mapping tables. Execution errors during cutover windows create operational risk exposure.
- AI governance framework ambiguity:Fiduciary duty standards for algorithmic decision support remain unsettled across jurisdictions. Providers automating investment-related workflows face liability uncertainty until regulatory clarity emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middleoffice BPO Services Market |
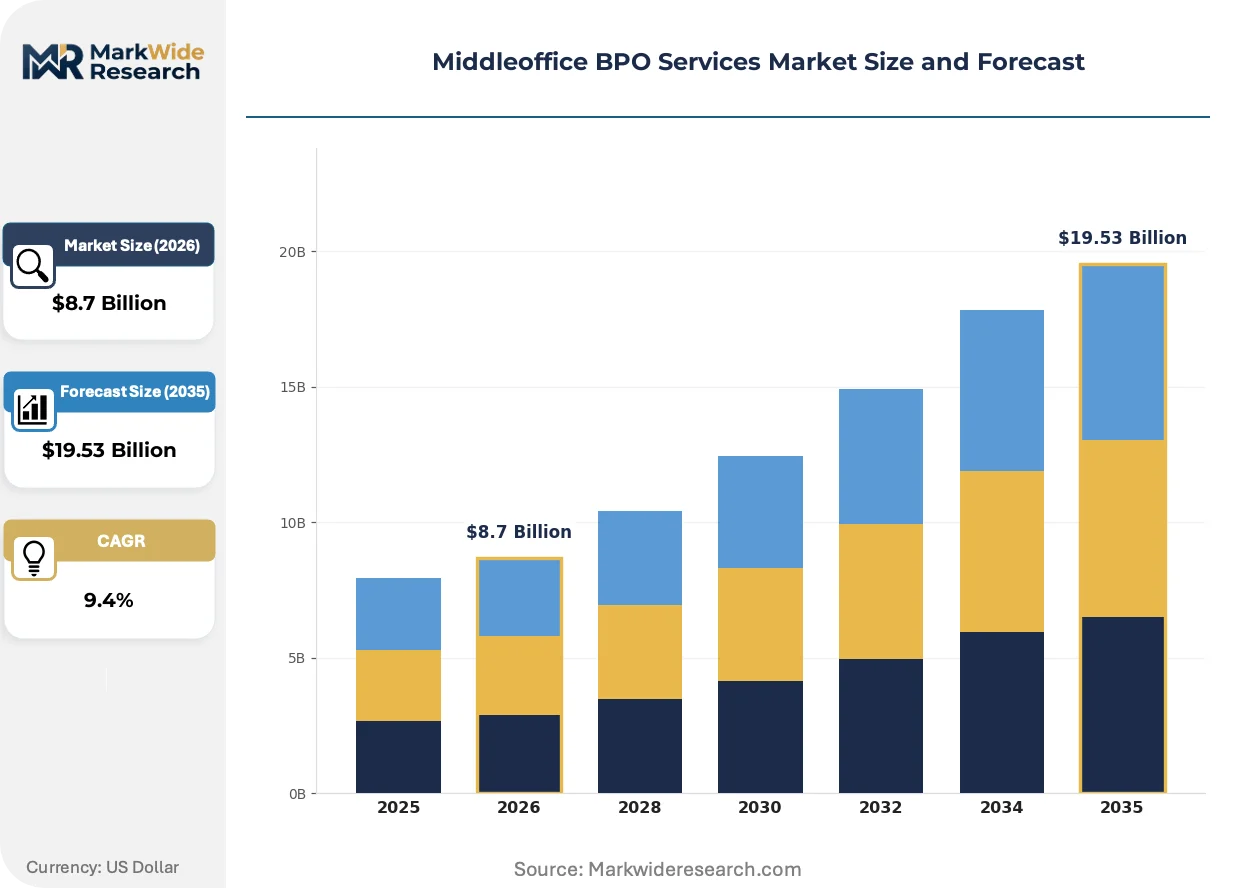
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Trade Support, Risk Management, Compliance Monitoring, Data Management, Settlement Processing, Reporting Services Client Type: Asset Managers, Investment Funds, Hedge Funds, Custodian Banks, Broker-Dealers, Wealth Managers Delivery Model: Onshore, Nearshore, Offshore, Hybrid, Cloud-Based, Managed Services Engagement Type: Project-Based, Dedicated Team, Transactional, Outcome-Based, Time & Material, Retainer |
| Companies Covered | EXL Service, Wipro, Accenture, Concentrix, Teleperformance, Genpact, Cognizant, Infosys BPM, WNS Global Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middleoffice BPO Services Market Trends and Innovations
Automation architectures are shifting from rule-based engines to probabilistic models that learn from exception patterns. This transformation is compressing headcount requirements in mature processing segments while elevating the strategic importance of data science capabilities.
Distributed ledger infrastructure is decentralizing settlement workflows away from centralized clearing utilities. Asset managers in Singapore and Switzerland are piloting atomic settlement for digital securities. This architecture eliminates counterparty exposure windows and collapses reconciliation requirements into single-source-of-truth ledgers.
The EU AI Act establishes risk-based compliance obligations for automated systems supporting investment decisions. Providers deploying machine learning in portfolio accounting or risk aggregation must implement explainability mechanisms and human oversight protocols. European asset managers now evaluate vendor AI governance maturity as a procurement criterion alongside technical capabilities.
Subscription-based commercial models are displacing traditional FTE-based pricing in middle-office outsourcing. Asset managers in the United Kingdom and United States prefer outcome-linked contracts tied to error rates, settlement timeliness, and regulatory audit outcomes. This shift transfers operational risk to providers and rewards automation investments over labor arbitrage.
Middleoffice BPO Services Market Segmentation
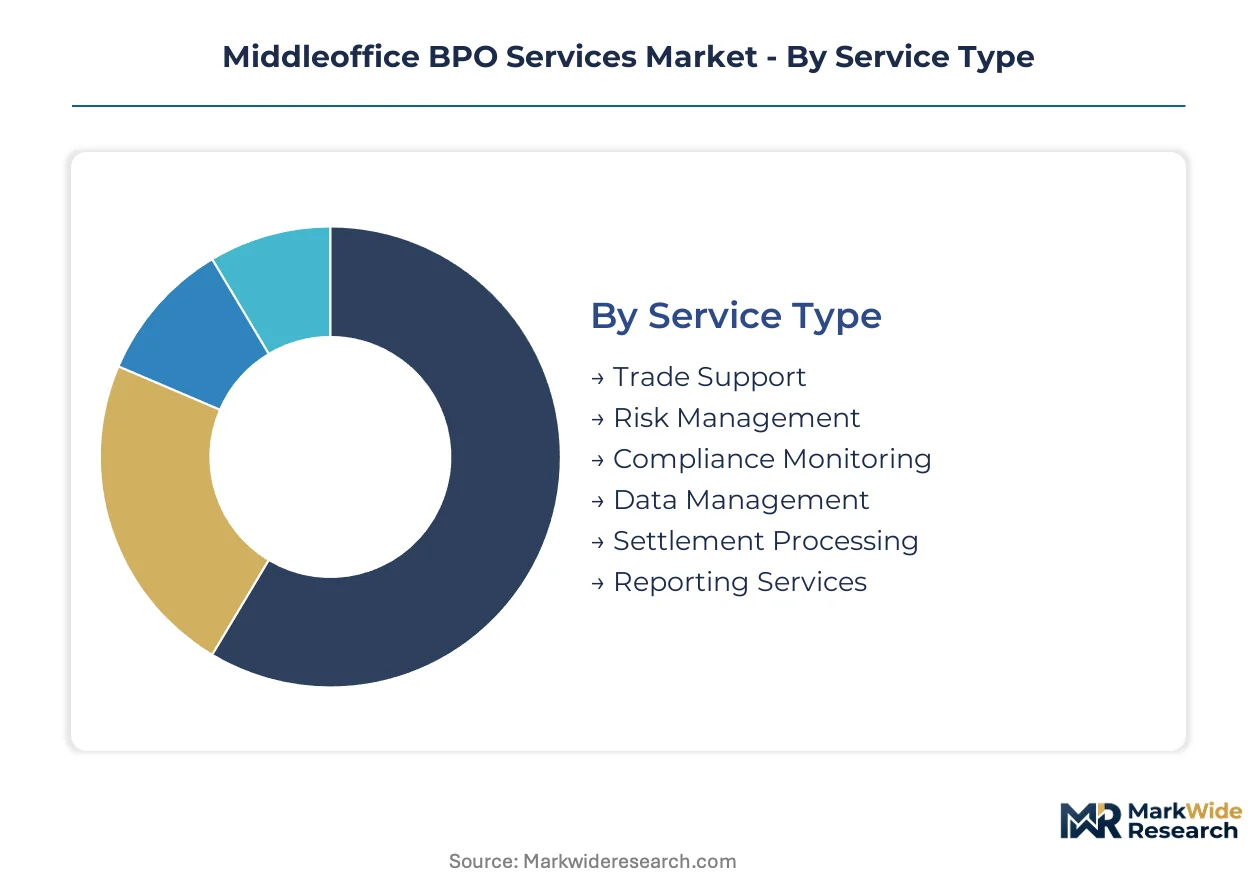
Middle-office BPO segmentation reveals divergent capital requirements across service architectures. Cloud-native delivery models demand substantial platform investment, while legacy onshore configurations carry maintenance-heavy cost structures. Client sophistication and regulatory proximity further fragment procurement patterns across buyer verticals.
Service Type:
Capital intensity peaks in settlement processing infrastructure, where sub-second reconciliation engines and ISO 20022 messaging stacks require dedicated platform investment. Trade support and compliance monitoring follow with substantial technology commitments.
- Trade Support:Encompasses order validation, execution confirmation, and pre-settlement matching workflows. Asset managers in the United States and United Kingdom concentrate demand here as trading velocity accelerates across multi-asset strategies. SEC liquidity rule compliance drives upgrades to real-time position monitoring capabilities.
- Settlement Processing:Requires SWIFT messaging gateways, nostro reconciliation engines, and exception management architectures. Custodian banks in Singapore and Switzerland deploy these services most intensively as T+1 compression deadlines approach. Blockchain-DLT pilot integration is elevating capital requirements for next-generation providers.
- Risk Management:Portfolio analytics, exposure aggregation, and stress testing automation for buy-side firms.
- Compliance Monitoring:Regulatory reporting, audit trail maintenance, and control framework validation.
- Data Management:Reference data cleansing, corporate actions processing, and security master maintenance.
- Reporting Services:Investor statements, regulatory filings, and performance attribution documentation.
Most installed capacity flows through Trade Support. Expansion is steepest in Risk Management.
Client Type:
Cost tier stratification separates institutional asset managers with integrated multi-function needs from specialized hedge funds purchasing discrete workflows. Hedge fund administration is climbing the fastest as alternative asset complexity deepens.
- Asset Managers:Long-only and balanced mandate institutions requiring comprehensive post-trade coverage. Firms in Germany and France outsource entire middle-office functions to achieve SEC and FCA compliance without captive infrastructure. Multi-asset strategies demand sophisticated corporate actions processing and tax lot accounting.
- Hedge Funds:Alternative managers with complex derivatives exposure and prime brokerage relationships. Cayman Islands and Delaware-domiciled funds drive specialized demand for portfolio reconciliation across fragmented custody arrangements. Fee compression is accelerating outsourcing of non-differentiating operations.
- Investment Funds:Mutual funds and UCITS vehicles with standardized processing requirements.
- Custodian Banks:Global custodians sub-contracting operational functions to specialist providers.
- Broker-Dealers:Execution venues requiring post-trade affirmation and confirmation services.
- Wealth Managers:Private banks and family offices with bespoke reporting and aggregation needs.
Asset Managers retain the largest committed spend base. Hedge Funds are expanding most quickly.
Delivery Model:
Volume concentration favors offshore configurations in India and the Philippines, while margin protection drives nearshore expansion into Poland and Mexico. Hybrid architectures are gaining share fastest as data residency requirements fragment deployment strategies.
- Offshore:India and Philippines delivery centers with established financial services talent pools. Mumbai and Bangalore operations process high-volume reconciliation and data management for North American and European asset managers. Time zone arbitrage enables overnight processing cycles.
- Cloud-Based:Native SaaS platforms with API-first integration and elastic compute scaling. Providers in Ireland and the Netherlands deploy these architectures for GDPR-compliant European asset manager coverage. Subscription economics displace FTE-based pricing.
- Onshore:Domestic delivery maintaining regulatory proximity and data sovereignty.
- Nearshore:Poland and Mexico centers offering timezone alignment with cost advantages.
- Hybrid:Blended onshore-offshore models with workflow-specific location optimization.
- Managed Services:Outcome-based contracts with operational risk transfer to providers.
Offshore maintains the deepest installed base. Cloud-Based is climbing the fastest.
Engagement Type:
Customer maturity separates transactional spot purchasing from strategic outcome-based partnerships. Project-based engagements dominate initial vendor relationships, while retainer structures anchor long-term commitments.
- Outcome-Based:Contracts tied to error rates, settlement timeliness, and audit performance metrics. United Kingdom and United States asset managers prefer these structures for risk transfer and automation incentive alignment. Providers bear operational risk and invest in machine learning exception management.
- Dedicated Team:Captive personnel assigned to specific client operations with embedded domain expertise. Large asset managers in Switzerland and Luxembourg deploy these arrangements for complex multi-jurisdictional fund structures. Staff retention and knowledge continuity justify premium pricing.
- Project-Based:Discrete implementation or transformation engagements with defined deliverables.
- Transactional:Per-unit pricing for volume-variable processing without commitment.
- Time & Material:Hourly or daily rates for advisory and implementation services.
- Retainer:Fixed periodic fees for ongoing operational support and maintenance.
Dedicated Team arrangements hold the most committed capacity. Outcome-Based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Bangalore delivery clusters anchor global middle-office BPO capacity, processing overnight reconciliation cycles for North American and European asset managers. Talent concentration in SWIFT messaging and derivatives accounting sustains India's dominance despite wage inflation. Regulatory divergence across jurisdictions is fragmenting deployment architectures and elevating nearshore alternatives.
United States
SEC liquidity rule mandates and T+1 settlement compression drive outsourcing demand among mid-tier asset managers. The regulator requires daily stress testing documentation that many firms lack infrastructure to produce internally. New York and Boston financial centers host captive operations, though Chicago and Dallas are emerging as domestic delivery alternatives.
United Kingdom
FCA operational resilience directives and SFDR disclosure requirements push buy-side firms toward compliant specialist providers. The regulator's March 2025 deadline for critical third-party oversight intensifies vendor due diligence. London retains decision-making concentration while Belfast and Edinburgh delivery centers capture regulatory reporting workflows.
India
SWIFT-certified talent pools in Mumbai and Bangalore process high-volume reconciliation for global custodians. SEBI's framework for investment manager outsourcing provides regulatory cover for domestic expansion. Hyderabad and Pune are capturing specialized risk management workflows as domain expertise deepens beyond generic processing.
Poland
Warsaw and Krakow talent markets offer European timezone coverage at cost structures below London or Dublin. EU AI Act compliance requirements favor nearshore delivery for explainability-critical workflows. The country's financial services education pipeline is expanding to meet derivatives accounting demand from Frankfurt and Luxembourg clients.
Singapore
Monetary Authority of Singapore guidelines on technology risk management shape vendor selection for Asia-Pacific fund administrators. The regulator's emphasis on operational resilience elevates provider audit requirements. The city-state's blockchain-DLT pilot programs are attracting settlement processing specialists seeking T+0 infrastructure exposure.
Middleoffice BPO Services Market Competitive Landscape
Consulting-led transformation engagements dominate the current landscape as pure-play processors face margin compression from automation. The vendor base separates into three tiers: global IT consultancies with financial services verticals, specialist BPO providers with domain-specific platforms, and captive units of major asset managers. Strategic archetypes include automation-first challengers, regulatory compliance specialists, and scale-driven commodity processors. M&A activity and cloud platform re-architecture represent the primary competitive vectors as legacy infrastructure becomes a liability.
Among the specialist tier, EXL Service, Genpact, and WNS Global Services occupy distinct positioning. EXL Service exemplifies the analytics-anchored archetype with domain-specific risk management platforms. Genpact represents regulatory technology integration specialists serving compliance-heavy client profiles. WNS Global Services sits within the scale-driven segment with multi-geography delivery footprints. These three entities illustrate how differentiation now hinges on automation depth and regulatory proximity rather than labor arbitrage alone.
| Leading Market Players |
|---|
| EXL Service |
| Wipro |
| Accenture |
| Concentrix |
| Teleperformance |
| Genpact |
| Cognizant |
| Infosys BPM |
| WNS Global Services |
| Others |
Pricing and Supply Chain Analysis
Captive delivery center networks in India and the Philippines anchor supply positioning and pricing power for incumbent providers, while cloud-native challengers compress margins through subscription economics. This integration choice forces traditional BPO operators to re-platform legacy infrastructure or cede wallet share to automated alternatives.
Pricing Analysis
Specialized talent costs in SWIFT messaging and derivatives accounting pass through to client contracts, elevating input-driven pricing for reconciliation services. Three-tier pricing structure across premium analytics platforms, standard processing workflows, and economy data management tiers separates buyers by complexity requirements. Cost compression in commodity reconciliation segments intensifies as machine learning exception management displaces manual labor. Hedge funds exhibit highest price sensitivity due to fee compression pressures, while sovereign wealth funds prioritize regulatory compliance over unit economics.
Supply Chain Analysis
SWIFT-certified talent supply rests on Mumbai and Bangalore training pipelines, with Krakow and Mexico City emerging as secondary sourcing nodes. Specialized inputs include ISO 20022 messaging engines, cloud compute infrastructure, and regulatory technology software licenses. Single-source vulnerability concentrates in India's derivatives accounting expertise pool, where wage inflation outpaces productivity gains. Distribution runs through direct enterprise sales teams for large asset managers, with channel partners penetrating mid-market hedge fund administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middleoffice BPO Services Market represents a late-cycle quality story as asset managers shift procurement criteria toward AI governance maturity and regulatory compliance depth over labor arbitrage alone.
For Market Incumbents: Anchor defensive positioning through captive upskilling programs in EU AI Act explainability protocols, insulating against pure-play automation challengers. Prioritize backward integration into cloud-native platform development to escape margin compression in legacy FTE-based contracts. The regulatory technology integration specialists pose substitution threats to generic processors lacking compliance depth.
For New Entrants and Emerging Players: Begin with SFDR regulatory reporting services for EU asset managers, where incumbent coverage gaps and compliance complexity create penetrable white space. Target Poland nearshore delivery for Frankfurt and Luxembourg clients seeking timezone alignment without London cost structures. Lead with outcome-based commercial models that transfer operational risk and align incentives with automation investments.
For Investors and Strategic Acquirers: Roll-up economics work for regulatory technology specialists because SEC liquidity rule mandates and EU SFDR obligations deepen compliance outsourcing demand across fragmented buyer bases. Five-to-ten year viability hinges on cloud platform architecture and AI governance maturity rather than scale alone. Watch for T+0 settlement pilot conversions to DLT infrastructure as inflection signals for next-generation provider positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Re-architecture | Elastic compute scaling enables ISO 20022 messaging compatibility without legacy infrastructure drag. |
| Regulatory Technology Acquisition | SEC liquidity rule compliance capabilities differentiate providers for US-registered investment advisers. |
| Nearshore Delivery Expansion | Poland and Mexico centers capture EU and North American demand seeking timezone proximity. |
| AI Governance Certification | EU AI Act explainability protocols become procurement criteria for European asset manager RFPs. |
| Blockchain-DLT Integration | Atomic settlement pilots in Singapore position providers for T+0 infrastructure convergence. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with asset manager operations executives, hedge fund administration heads, BPO delivery center directors, regulatory compliance officers, and cloud platform architects informed demand-side and supply-side perspectives. Secondary sources include SEC regulatory filings, FCA operational resilience directives, SEBI outsourcing frameworks, and EU SFDR implementation guidelines. Bottom-up service line modeling and top-down market sizing triangulated volume and value estimates.
Granularity-level modeling addressed service type, client vertical, delivery model, and engagement structure dimensions across the projection horizon. Deployment architecture segmentation separated cloud-native, hybrid, and legacy configurations. CAGRs derived from historical trajectory analysis and technology adoption curve positioning. Forecast inputs incorporated SEC liquidity rule implementation timelines, T+1 settlement compression deadlines, and EU AI Act compliance phase-in patterns.
Several conditions sit outside the modeled scope, including geopolitical disruptions to India-Philippines delivery corridors and unanticipated regulatory reversals on AI governance standards. Forecasts reflect assumptions about automation adoption rates and cloud migration velocity that warrant reassessment if machine learning exception management deployment stalls. A small set of named triggers warrants ongoing watch: DLT settlement infrastructure commercialization, US state privacy law fragmentation, and talent pool wage spirals in specialized domains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market