
 US Managed Print Services Market | 2026-2036
US Managed Print Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Managed Print Services Market Analytics
Domestic copier and printer hardware distribution is consolidating around fewer national service networks with sufficient technician density to honor same-day response SLAs. Xerox Corporation leverages its direct sales organization and legacy installed base to sustain long-term annuity contracts across federal and healthcare accounts. HP Inc. anchors its position through integrated supplies logistics and predictive monitoring software bundled with hardware leases. Lexmark International Inc. specializes in secure print architectures for regulated industries, competing on compliance depth rather than unit volume.
Managed Print Services encompass the outsourcing of document output management, combining hardware provision, toner and parts replenishment, remote monitoring, and help-desk support under per-page or fixed-fee contractual structures. The technical stack typically includes embedded Java-based firmware agents reporting page counts, jam rates, and supply levels via SNMP or proprietary cloud gateways to centralized service desks. Print Management services command the largest revenue share due to their direct linkage to consumables replenishment and break-fix labor, while Workflow Automation represents the fastest-expanding margin pool as customers seek to digitize paper-based approval chains and reduce physical page volumes. Large Corporations dominate absolute contract value, though Medium Enterprises generate higher growth velocity as managed print penetrates organizations previously served by ad-hoc dealer arrangements.
FCC guidelines on network-connected device security, FTC enforcement against deceptive service contract terms, and HIPAA requirements for document traceability in healthcare collectively shape provider obligations and customer procurement criteria. The EPA's e-waste directives and Energy Star specifications further influence hardware refresh cycles and end-of-life handling protocols embedded in service agreements. Stakeholders must weigh cloud-based fleet analytics against on-premises data residency requirements as state-level privacy laws proliferate beyond California's CCPA framework.
Market Dynamics
Healthcare systems across the United States are consolidating vendor relationships under single-source fleet optimization contracts, compressing the addressable supplier base while elevating technical service requirements around encrypted print infrastructure and same-day response guarantees.
Growth Catalysts
- HIPAA traceability mandates:Healthcare providers require document audit trails for every printed page, forcing infrastructure upgrades that favor outsourced managed print architectures with embedded compliance tooling.
- Multi-site enterprise consolidation:Corporate headquarters clusters in California and Texas are unifying fragmented dealer relationships under national service networks with technician density sufficient for four-hour response SLAs.
- Predictive monitoring platforms:Cloud-based firmware agents reporting jam rates and supply levels via SNMP are reducing unplanned downtime, converting break-fix relationships into annuity revenue streams.
Market Restraints
- Technician labor scarcity:Field service engineer density constraints in the Mountain West and rural Southeast limit same-day coverage expansion, capping contract win rates in underpenetrated territories.
- Hardware refresh capital intensity:Energy Star specifications and EPA e-waste directives are shortening depreciation cycles, pressuring providers to absorb residual value risk in lease structures.
- Cloud data residency fragmentation:State-level privacy laws proliferating beyond California's CCPA framework are complicating centralized fleet analytics architectures, forcing redundant infrastructure deployment.
Strategic Opportunities
- Workflow automation integration:Digitization of paper-based approval chains represents the fastest-expanding margin pool as customers seek to reduce physical page volumes while maintaining compliance documentation.
- Medium enterprise penetration:Organizations previously served by ad-hoc dealer arrangements generate higher growth velocity than saturated large corporate accounts, offering greenfield contract origination.
- FTC enforcement alignment:The Commission's emphasis on data security in outsourced business services pushes providers toward encrypted print infrastructure, differentiating compliant national networks from regional competitors.
Industry Challenges
- Legacy system integration complexity:Embedded Java-based firmware agents must interoperate with decades-old on-premises document management systems, extending implementation timelines and eroding first-year margins.
- Certification timeline compression:Federal and healthcare accounts require Common Criteria or FIPS 140-2 validation for secure print architectures, creating six-to-twelve month sales cycle delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Managed Print Services Market |
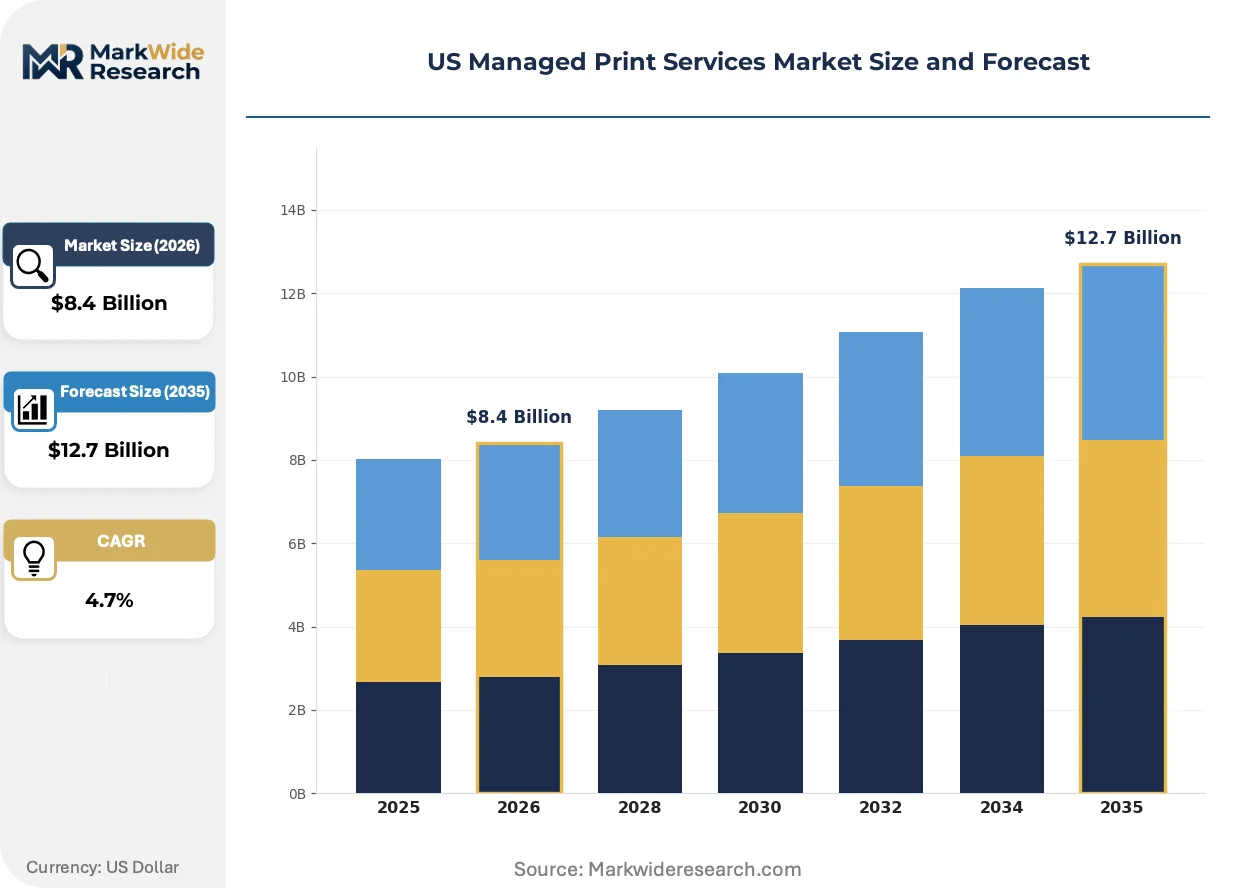
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Document Services, Print Management, Device Management, Workflow Automation Industry Vertical: Healthcare, Education, Retail, Government Customer Size: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Deployment Model: On-Premises, Cloud-Based, Hybrid, Outsourced |
| Companies Covered | Canon Inc., Konica Minolta Inc., Xerox Corporation, Kyocera Document Solutions Inc., Lexmark International Inc., Ricoh Company Ltd., Brother Industries Ltd., Marco Technologies, HP Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Managed Print Services Market Evolving Landscape
Edge computing architectures are redistributing processing load away from centralized cloud gateways, while regulatory pressure on network-connected device security is hardening firmware requirements. Buyer procurement patterns are simultaneously compressing contract durations and unbundling hardware from service components.
Cloud-native print management platforms are decentralizing fleet oversight by embedding analytics directly at the device level. Healthcare systems and federal agencies are adopting these architectures fastest, driven by HIPAA and FISMA data sovereignty requirements. This shift is compressing the addressable market for centralized managed print service desks while elevating demand for distributed technical support networks with local presence.
The FTC's emphasis on deceptive service contract terms is reshaping provider disclosure obligations around automatic renewal clauses and usage-based billing calculations. Hardware lessors must now itemize residual value assumptions and early termination penalties with greater specificity. Healthcare and financial services procurement departments are leveraging these requirements to renegotiate legacy agreements.
Enterprise buyers are fragmenting vendor relationships by unbundling hardware acquisition, supplies logistics, and break-fix labor into separate contractual vehicles. Large corporations in Texas and California are piloting this approach, sourcing devices direct from manufacturers while contracting field service regionally. This pattern is compressing margins for integrated providers while creating openings for specialized supplies distributors and independent service technicians.
US Managed Print Services Market Segmentation
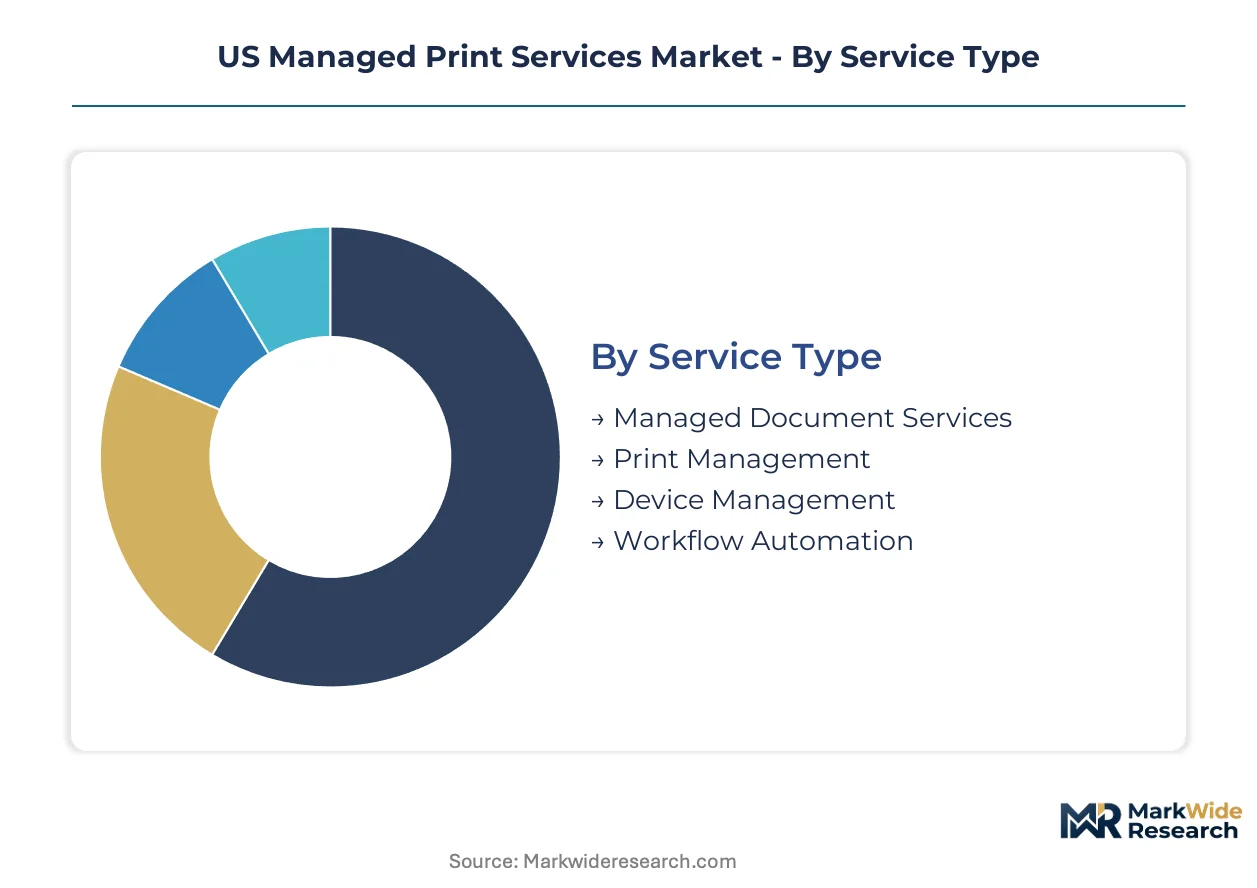
Segmentation in managed print services reflects divergent technical requirements across regulated industries, customer scale, and infrastructure maturity. Service packaging, compliance depth, and deployment architecture vary substantially across these dimensions, shaping provider specialization and contract economics.
Service Type:
Service packaging differentiates by the degree of process integration versus hardware-centric delivery, with cloud-native architectures displacing traditional break-fix models.
- Managed Document Services:End-to-end document lifecycle management combining capture, storage, retrieval, and archival with print infrastructure. Healthcare systems in Texas and California deploy these for HIPAA-compliant patient record workflows, absorbing higher per-page costs in exchange for audit trail automation.
- Print Management:Core fleet oversight encompassing toner logistics, remote monitoring via SNMP-enabled firmware agents, and break-fix labor dispatch. Federal accounts sustain long-term annuity relationships through this segment, prioritizing technician density over feature expansion.
- Device Management:Hardware lifecycle administration including refresh scheduling, residual value optimization, and EPA e-waste directive compliance. Energy Star specification upgrades shorten depreciation cycles, pressuring lease structure design.
- Workflow Automation:Digitization of paper-based approval chains and routing logic. Medium enterprises in underpenetrated Mountain West territories adopt fastest, leapfrogging legacy dealer relationships.
Print Management leads on scale; Workflow Automation leads on momentum.
Industry Vertical:
Regulatory intensity and document volume density determine vertical attractiveness and technical service requirements.
- Healthcare:HIPAA traceability mandates demand encrypted print infrastructure with page-level audit capabilities. Hospital systems consolidate vendor relationships under single-source fleet optimization contracts, elevating same-day response SLAs to contractual necessities.
- Government:FISMA data sovereignty requirements and FTC enforcement on deceptive contract terms shape procurement patterns. Federal accounts require Common Criteria validation, extending sales cycles six to twelve months.
- Education:K-12 and university systems balance decentralized departmental purchasing against central IT standardization. Budget constraints favor hardware lease structures with bundled supplies over per-page billing.
- Retail:Multi-site operators prioritize four-hour response guarantees across distributed store footprints. Seasonal volume spikes complicate predictive supply replenishment algorithms.
Healthcare commands premium pricing; Retail offers volume expansion potential.
Customer Size:
Procurement sophistication and contract fragmentation vary inversely with organizational scale, reshaping provider go-to-market economics.
- Large Corporations:Enterprise headquarters clusters in California and Texas unifying fragmented dealer relationships under national service networks. These accounts pilot unbundled procurement, sourcing hardware direct from manufacturers while contracting field service regionally.
- Medium Enterprises:Organizations previously served by ad-hoc dealer arrangements generate higher contract origination velocity. Cloud-based fleet analytics penetration remains nascent, creating greenfield opportunity for predictive monitoring platforms.
- Small Businesses:Price-sensitive buyers relying on regional dealer networks with limited technician density. Same-day coverage gaps in rural Southeast and Mountain West cap addressable share.
- Non-Profits:Grant-funded capital cycles and donor transparency requirements influence refresh timing. Hardware residual value risk absorption matters more than feature depth.
Large Corporations anchor absolute revenue; Medium Enterprises drive expansion velocity.
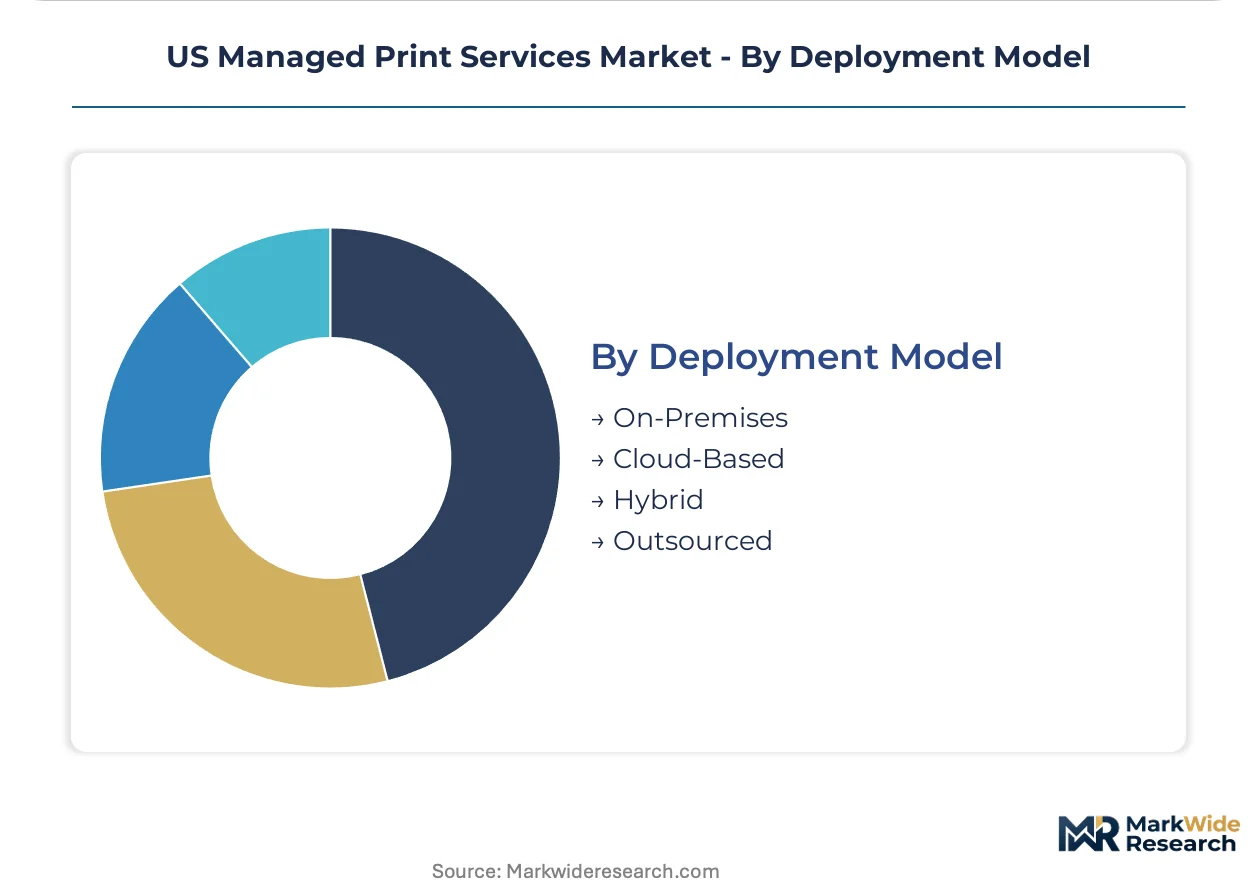
Deployment Model:
Infrastructure location decisions reflect data residency constraints, latency requirements, and IT staffing levels across customer profiles.
- Cloud-Based:Centralized fleet analytics with firmware agents reporting via proprietary gateways to hosted service desks. State-level privacy laws proliferating beyond California's CCPA framework force redundant infrastructure deployment, complicating architecture economics.
- Hybrid:Edge computing redistribution of processing load with local analytics and cloud backup. Healthcare and federal agencies adopt fastest for HIPAA and FISMA compliance.
- On-Premises:Legacy document management system integration requiring embedded Java-based firmware agents. Implementation timelines extend, eroding first-year margins for complex deployments.
- Outsourced:Complete operational transfer to managed service providers with dedicated technician staffing. FTC emphasis on data security in outsourced business services pushes providers toward encrypted print infrastructure differentiation.
Cloud-Based dominates new contract flow; Hybrid gains share in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between states with stringent data residency laws and those with lighter regulatory burdens are reshaping where managed print providers concentrate technician networks and cloud infrastructure investments.
California
Enterprise headquarters clusters in Silicon Valley and Los Angeles drive multi-site fleet optimization contracts demanding encrypted print infrastructure. The California Consumer Privacy Act (CCPA) forces redundant cloud gateway deployment for fleet analytics, elevating compliance costs for centralized service providers. Healthcare systems in the San Francisco Bay Area consolidate vendor relationships under single-source contracts with four-hour response SLAs.
Texas
Energy sector headquarters in Houston and technology corridors in Austin generate demand for secure document workflows with FISMA-aligned architectures. State procurement guidelines emphasize competitive bidding for managed services, compressing contract durations while unbundling hardware from service components. Federal contractor density in the Dallas-Fort Worth metroplex sustains long-term annuity relationships with Common Criteria-validated providers.
New York Metro
Financial services concentration in Manhattan drives premium pricing for HIPAA and SOX-compliant print infrastructure with page-level audit capabilities. New York State's SHIELD Act supplements federal data security requirements, forcing firmware-level encryption upgrades across legacy installed bases. Healthcare networks in the tri-state area prioritize same-day technician response for patient record workflows.
Southeast
Manufacturing and logistics hubs in Georgia and Florida generate volume demand for break-fix labor and supplies logistics. Technician labor scarcity across rural markets caps same-day coverage expansion, limiting contract win rates outside Atlanta and Miami metropolitan zones. State-level privacy legislation remains lighter than California or New York, attracting cloud infrastructure investment from cost-sensitive national providers.
Mountain West
Medium enterprises in Colorado and Arizona previously served by ad-hoc dealer arrangements represent greenfield opportunity for predictive monitoring platforms. Sparse population density constrains field service engineer deployment, forcing hybrid service models with remote diagnostics and periodic technician visits. Energy sector operations in Wyoming and New Mexico require ruggedized print infrastructure for remote site deployment.
US Managed Print Services Market Competitive Landscape
Japanese and American producers anchor the premium tier; European and Korean specialists hold mid-market positions through regional service density. The vendor base organizes around three strategic archetypes: integrated hardware-service providers with legacy installed bases, cloud-native platform specialists, and independent service organizations with geographic focus. Consolidation pressures favor national networks with sufficient technician density to honor same-day SLAs, while unbundling trends create openings for specialized supplies distributors. Dominant competitive moves include M&A to expand regional coverage and strategic partnerships to embed workflow automation capabilities.
Within the integrated hardware-service tier, Xerox Corporation and Canon Inc. exemplify providers leveraging direct sales organizations and legacy installed bases to sustain long-term annuity contracts. HP Inc. occupies a position combining supplies logistics with predictive monitoring software bundled across hardware lease structures. Lexmark International Inc. represents the compliance-focused specialization vector, competing on secure print architecture depth for federal and healthcare accounts rather than unit volume scale.
| Leading Market Players |
|---|
| Canon Inc. |
| Konica Minolta Inc. |
| Xerox Corporation |
| Kyocera Document Solutions Inc. |
| Lexmark International Inc. |
| Ricoh Company Ltd. |
| Brother Industries Ltd. |
| Marco Technologies |
| HP Inc. |
| Others |
Value Network & Pricing Analysis
Captive technician networks anchor both supply position and pricing power across the US managed print services landscape, with national service providers leveraging field engineer density to command premium per-page rates in HIPAA-regulated healthcare corridors.
Pricing Analysis
Distributor margin compression in the hardware procurement layer is forcing national providers toward direct manufacturer relationships. Three-tier pricing structure across enterprise, mid-market, and small business levels reflects technician response-time guarantees rather than device specifications alone. Cost compression in the mid-market tier is intensifying because cloud-native platform entrants are unbundling predictive monitoring from hardware leases. Small businesses exhibit highest price sensitivity, while federal accounts prioritize FIPS 140-2 certification depth over unit economics.
Supply Chain Analysis
Freight cost volatility across Pacific routes is elevating landed costs for Japanese and Korean hardware manufacturers serving US coastal markets. Component supply concentrates in Japan, South Korea, and Taiwan for precision imaging engines and secure firmware chipsets. Semiconductor dependency for embedded Java-based firmware agents creates single-source vulnerability when foundry capacity tightens. Distribution runs through national service networks with regional parts depots, bypassing traditional distributor layers for toner and consumables logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with HIPAA traceability mandates and FTC data security enforcement continuously refreshing infrastructure replacement cycles across healthcare and federal verticals.
For Market Incumbents: To counter unbundling pressure from enterprise buyers in Texas and California, national providers should deepen captive control over field service technician networks while embedding workflow automation capabilities through strategic partnerships. Certification investment in Common Criteria validation for federal accounts extends contract duration and protects annuity streams against regional competitors.
For New Entrants and Emerging Players: Enter via cloud-native predictive monitoring platforms targeting medium enterprises in the Mountain West and rural Southeast, where ad-hoc dealer relationships dominate and same-day coverage gaps persist. A direct sales model emphasizing per-page billing transparency aligns with FTC disclosure requirements while differentiating against legacy contract structures.
For Investors and Strategic Acquirers: Roll-up economics work for independent service organizations with concentrated technician presence in underpenetrated territories because fragmented regional dealer networks lack capital for HIPAA-compliant infrastructure upgrades. Target acquisition archetypes include Mountain West specialists with established healthcare relationships. The signal to watch is FTC enforcement action accelerating customer churn from non-compliant regional providers toward national networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Workflow Automation Integration | Captures fastest-expanding margin pool as healthcare systems digitize paper-based approval chains. |
| Technician Network Expansion | Enables four-hour SLA guarantees in Mountain West territories previously served by ad-hoc dealers. |
| Common Criteria Certification | Unlocks federal contract eligibility despite six-to-twelve month sales cycle delays. |
| Cloud-Native Platform Launch | Addresses state-level privacy law fragmentation beyond California's CCPA framework. |
| Strategic Partnership with Supplies Distributor | Supports unbundled procurement pilots by large corporations in Texas and California. |
Research Methodology
Multiple input streams — interviews with managed print service operations directors, conversations with healthcare IT procurement managers, and discussions with federal contract officers — were reconciled against secondary validation from SEC 10-K filings, GSA contract databases, and hospital procurement records. Bottom-up triangulation across technician dispatch logs and fleet analytics deployments was cross-checked with top-down market sizing from hardware shipment data and service contract registrations.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeled across service type, industry vertical, customer size, and deployment architecture dimensions. CAGRs were derived from fitted growth curves incorporating HIPAA compliance upgrade cycles, Energy Star refresh mandates, and cloud migration adoption patterns specific to regulated industries.
Inputs from federal contracting databases and hospital system RFP records were available through the study window; gaps in private dealer transaction data introduce uncertainty bands around small business and non-profit segment estimates. Forecasts reflect assumptions regarding FTC enforcement continuity and state privacy law proliferation. A model refresh is warranted upon material change in federal data security procurement requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market