
 Morocco Hospitality Market | 2026-2036
Morocco Hospitality Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Hospitality Market Insights
Corporate meeting and incentive travel demand from French, Spanish, and German buyer groups is consolidating around premium properties in Marrakech and Casablanca. Accor leverages its multi-brand portfolio to capture both luxury and midscale segments across Moroccan gateway cities. Marriott International sustains competitive positioning through its resort footprint along the Atlantic coast. Kenzi Hotels Group anchors its presence in urban business-travel hubs with convention-oriented properties.
Morocco hospitality encompasses lodging, food service, and event facilities that deliver guest accommodation, dining, and ancillary experiences across urban, coastal, and desert destinations. Properties typically integrate traditional riad architecture with modern amenities, operating across star-rated categories from budget riads to palace-grade resorts. Hotels and resorts command the dominant revenue share, while spas and wellness facilities within integrated resorts capture expanding margin pools as wellness tourism deepens. Business travelers and event organizers represent a concentrated high-yield segment, particularly in Casablanca's financial district and Marrakech's conference zone.
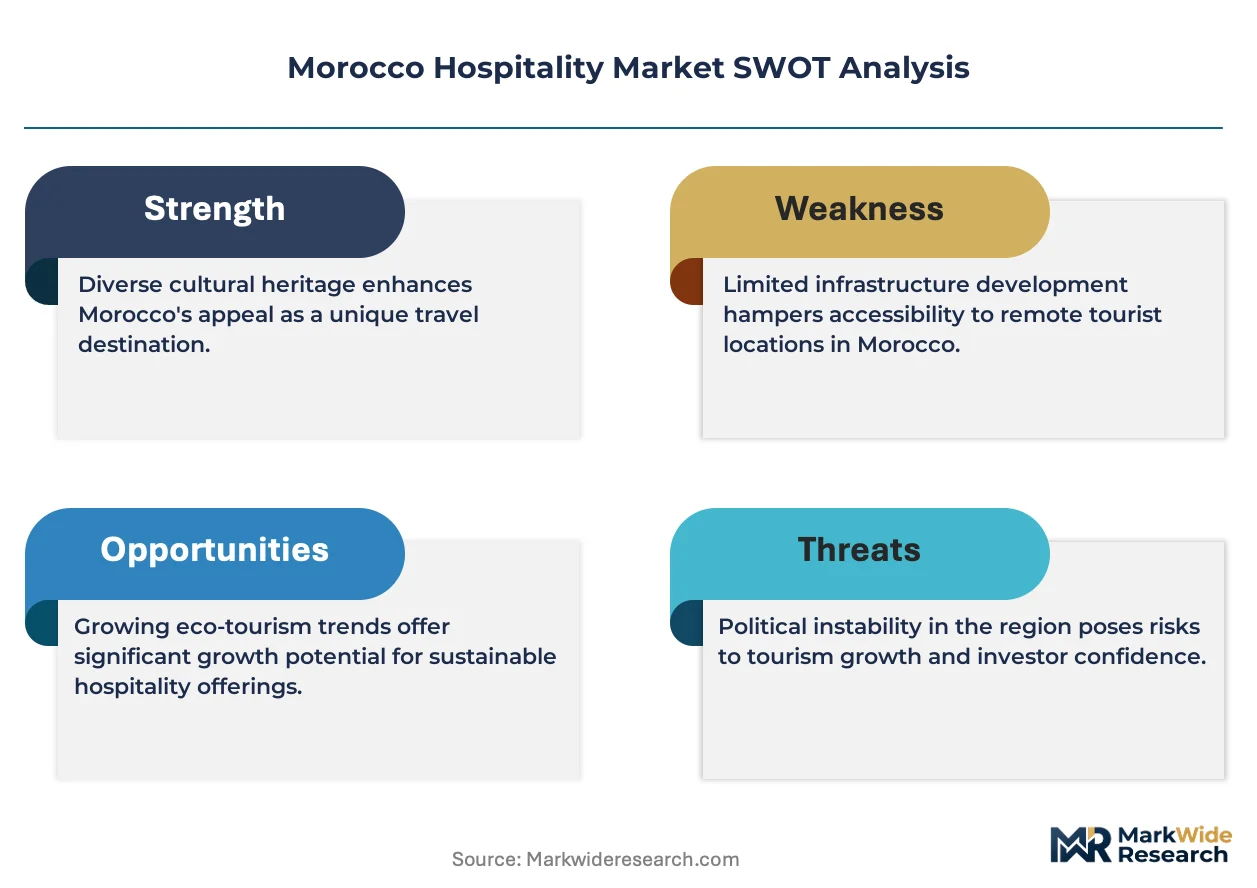
Morocco's Ministry of Tourism, Air Transport, Handicrafts, and Social Economy sets licensing and classification standards that shape property investment thresholds and service mandates. The country's national tourism strategy and airport expansion protocols direct infrastructure funding toward certified sustainable developments. Stakeholders must monitor evolving classification criteria and sustainability benchmarks that will determine access to state-supported financing and international distribution channels.
Market Dynamics
Investment gravity in Moroccan hospitality is concentrating around airport-linked corridors where the national tourism strategy channels financing toward certified sustainable developments. This spatial sorting is compressing development timelines for integrated resort projects while elevating entry barriers for independent operators.
Growth Catalysts
- Airport Infrastructure Expansion:Mohammed V International Airport's capacity upgrades and new terminal construction are shortening access times for European source markets. This infrastructure pull is redirecting leisure demand toward Casablanca's business district and Atlantic coastal zones.
- Eco-Certification Mandates:Morocco's Ministry of Tourism classification standards now embed sustainability benchmarks into licensing protocols. Properties achieving Green Key or EarthCheck certification gain preferential access to state-backed financing instruments.
- Riad Architecture Revival:Heritage restoration techniques combined with modern amenity integration are differentiating boutique properties in Marrakech's medina. This design vocabulary attracts premium leisure segments seeking authentic cultural immersion.
Market Restraints
- Construction Input Volatility:Imported steel and specialized glazing for desert-adapted building envelopes face price instability tied to European supply chain disruptions. This cost pressure compresses margin projections for resort developments in the Agadir corridor.
- Seasonal Demand Concentration:European holiday calendars concentrate occupancy into March-May and September-November windows. This temporal clustering forces revenue management complexity across Atlantic coast properties.
- Water Scarcity Constraints:Ouarzazate and desert-adjacent development zones face extraction limits under national drought response protocols. This technical ceiling restricts expansion of golf-course-anchored resort concepts.
Strategic Opportunities
- Wellness Tourism Integration:Traditional hammam rituals combined with clinical spa protocols are creating service differentiation for properties in the Marrakech Palmeraie zone. This convergence attracts extended-stay segments from German and Benelux markets.
- Secondary City Activation:Fez and Tangier remain underdeveloped relative to gateway corridors. These destinations offer first-mover positioning for convention-oriented properties serving domestic corporate demand.
- Digital Nomad Visa Framework:Morocco's remote work permit stream is channeling long-stay demand toward riad conversions with co-working infrastructure. This regulatory tailwind extends average length of stay in urban hospitality assets.
Industry Challenges
- Skilled Craftsmanship Shortage:Zellige tile installation and traditional plasterwork (tadelakt) require multi-year apprenticeship pipelines. This talent gap delays fit-out schedules for heritage-anchored properties.
- Legacy PMS Integration:Independent riad operators rely on fragmented booking systems that resist channel manager standardization. This technical debt limits rate parity enforcement across online travel agency distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Hospitality Market |
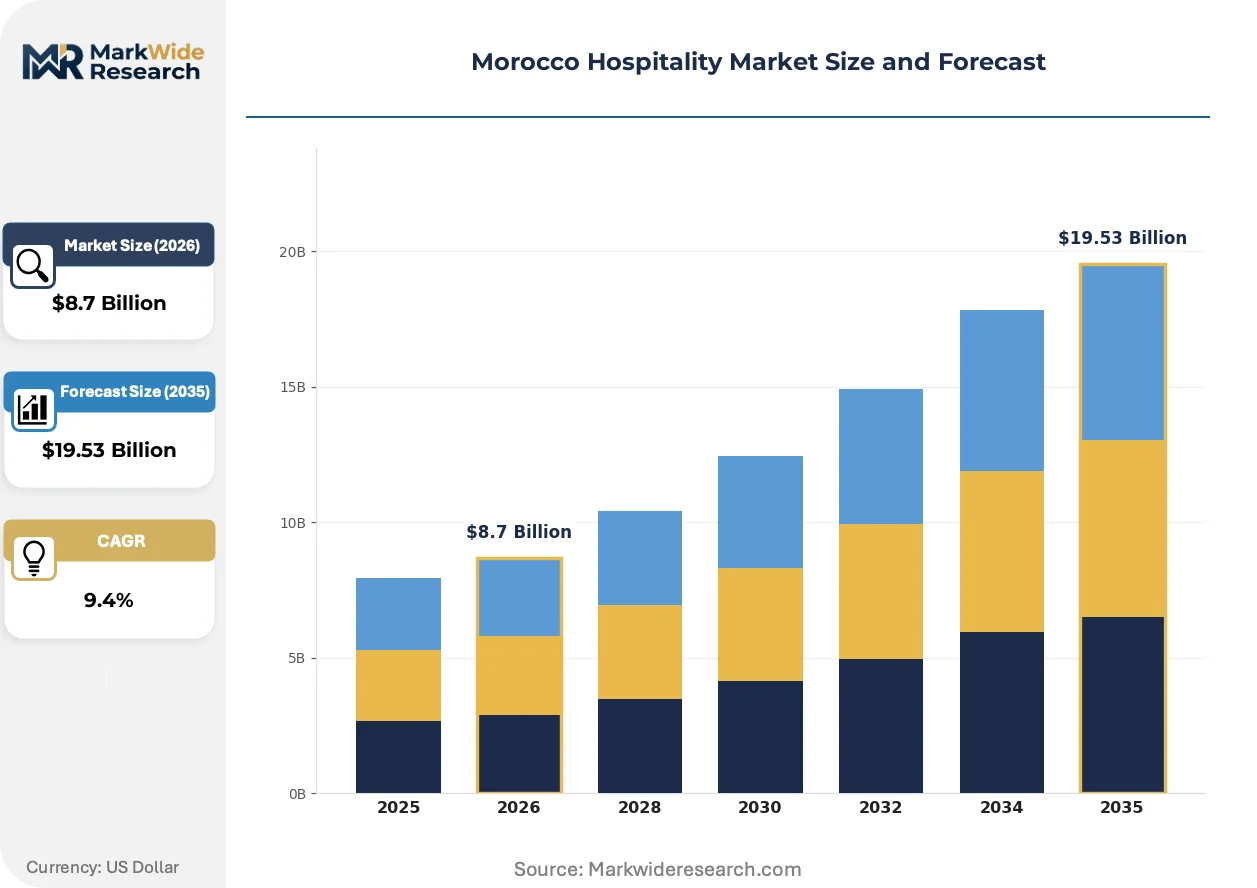
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotels, Restaurants, Cafés, Resorts Client Type: Business Travelers, Tourists, Locals, Event Organizers Room Type: Luxury Suites, Standard Rooms, Shared Dormitories, Villas Facility Type: Convention Centers, Meeting Rooms, Spas, Fitness Centers |
| Companies Covered | Accor, Marriott International, Hilton Worldwide, Radisson Hotel Group, Four Seasons Hotels & Resorts, Hyatt Hotels Corp., Iberostar Hotels & Resorts, Atlas Hospitality Morocco, Kenzi Hotels Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Hospitality Market Trends and Innovations
Operational technology deployment and guest-facing digital interfaces are compressing service delivery timelines while elevating personalization expectations across Moroccan hospitality assets. These shifts are restructuring capital allocation between physical amenities and data infrastructure.
Smart room management systems combining IoT sensors with predictive maintenance algorithms are rewriting operational cost structures for large-format resorts. Atlantic coast properties above 200 keys are deploying these platforms to reduce energy intensity in climate-controlled environments. This technology compression is enabling staff redeployment from routine maintenance toward guest experience curation.
Morocco's Ministry of Tourism revised classification criteria now mandate accessibility standards and fire safety protocols that exceed previous voluntary benchmarks. Properties seeking four-star and above designation must demonstrate compliance through third-party audit. Urban assets in Casablanca's financial district face compressed retrofit timelines to maintain competitive positioning.
Direct booking channels powered by property-level content marketing are displacing traditional online travel agency dependency for boutique riad operators. Marrakech-based independents are investing in video storytelling and influencer collaboration to capture guest relationships pre-arrival. This channel shift is most visible among properties under fifty keys targeting repeat visitation from French and Spanish source markets.
Morocco Hospitality Market Segmentation
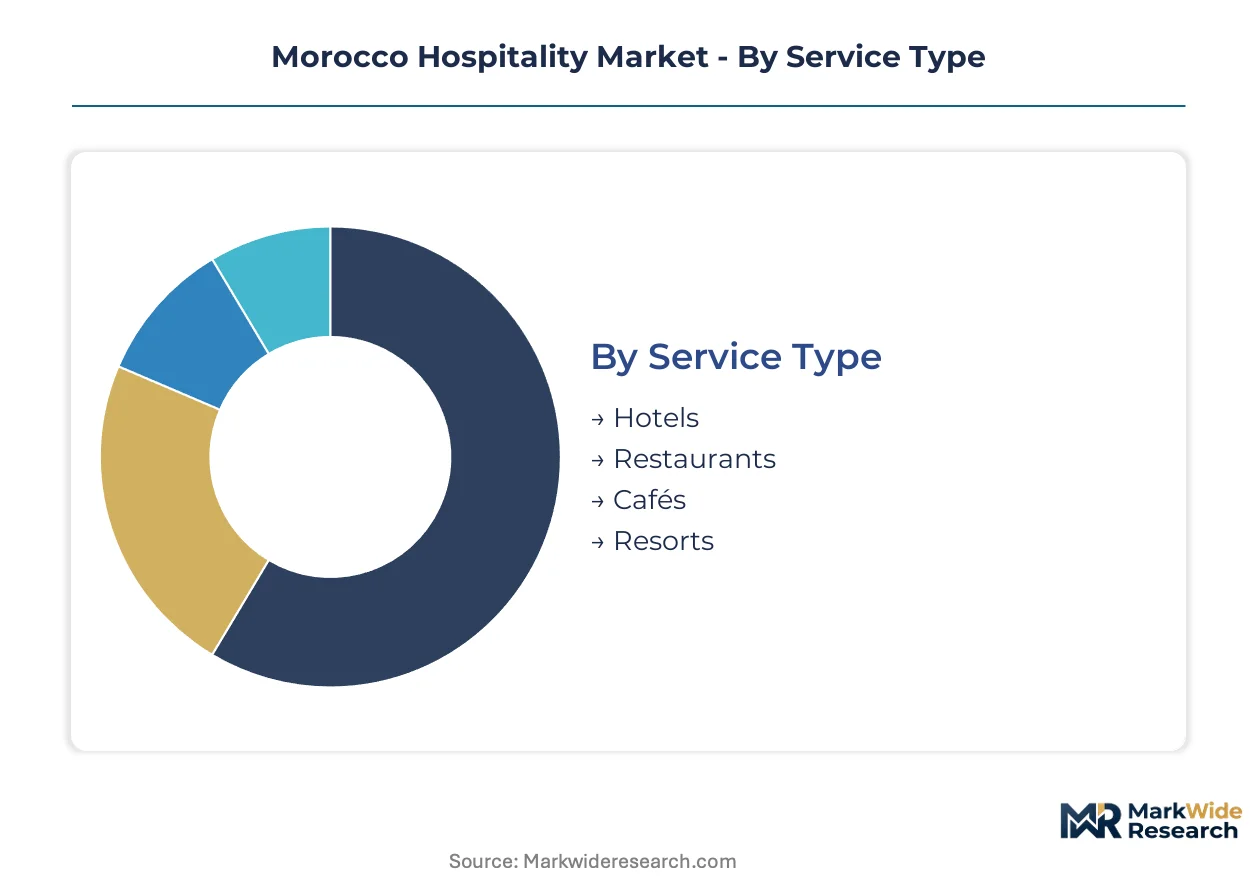
Segmentation in Moroccan hospitality reveals distinct operational models and investment profiles across service delivery modes. Each dimension shapes capital deployment, staffing ratios, and regulatory compliance pathways differently.
Service Type:
Standalone service formats operate as discrete revenue centers with dedicated management structures, while integrated resort complexes embed multiple service lines under unified P&L accountability.
- Hotels:Full-service properties with front-desk operations, housekeeping, and F&B integration command the dominant revenue position. Demand concentrates in Marrakech's medina-adjacent zones and Casablanca's financial district, driven by airport capacity expansion shortening European access times.
- Resorts:Large-format coastal properties combining accommodation with golf, spa, and marina infrastructure require extended development timelines. Atlantic coastline zones near Agadir face water extraction limits that constrain golf-course-anchored expansion concepts.
- Restaurants:Standalone dining venues in urban centers capture corporate entertainment spend from French and Spanish business travelers.
- Cafés:Smaller-format operations in Fez and Tangier medinas serve domestic leisure and remote worker segments.
Hotels lead volumes today; Resorts are expanding most quickly along certified sustainable development corridors.
Client Type:
Customer mix determines pricing power, seasonality exposure, and distribution channel strategy across Moroccan hospitality assets.
- Tourists:International leisure travelers from European source markets generate concentrated demand in March-May and September-November windows. This temporal clustering forces revenue management complexity across Atlantic coast properties.
- Business Travelers:Corporate meeting and incentive demand from French, Spanish, and German buyer groups consolidates around premium properties in Marrakech and Casablanca.
- Event Organizers:Convention-oriented demand anchors occupancy in Casablanca's financial district and Marrakech's conference zone.
- Locals:Domestic demand supports secondary city activation in Fez and Tangier where international visitation remains underdeveloped.
Tourists anchor current revenue; Business Travelers deliver the highest yield per occupied room.
Room Type:
Accommodation tiering aligns with Morocco's Ministry of Tourism classification standards that embed service mandates and amenity thresholds.
- Luxury Suites:Palace-grade accommodations in restored riad structures command premium positioning through heritage architecture integration. Marrakech Palmeraie properties combine these with hammam wellness protocols to attract extended-stay German segments.
- Standard Rooms:Mid-tier inventory dominates volume across urban business-travel hubs and coastal resort zones.
- Villas:Private-unit formats with dedicated service staff target family and extended-stay segments in resort environments.
- Shared Dormitories:Budget-oriented configurations in converted riads serve digital nomad visa holders seeking co-working infrastructure.
Standard Rooms drive occupancy scale; Luxury Suites capture expanding margin pools as wellness tourism deepens.
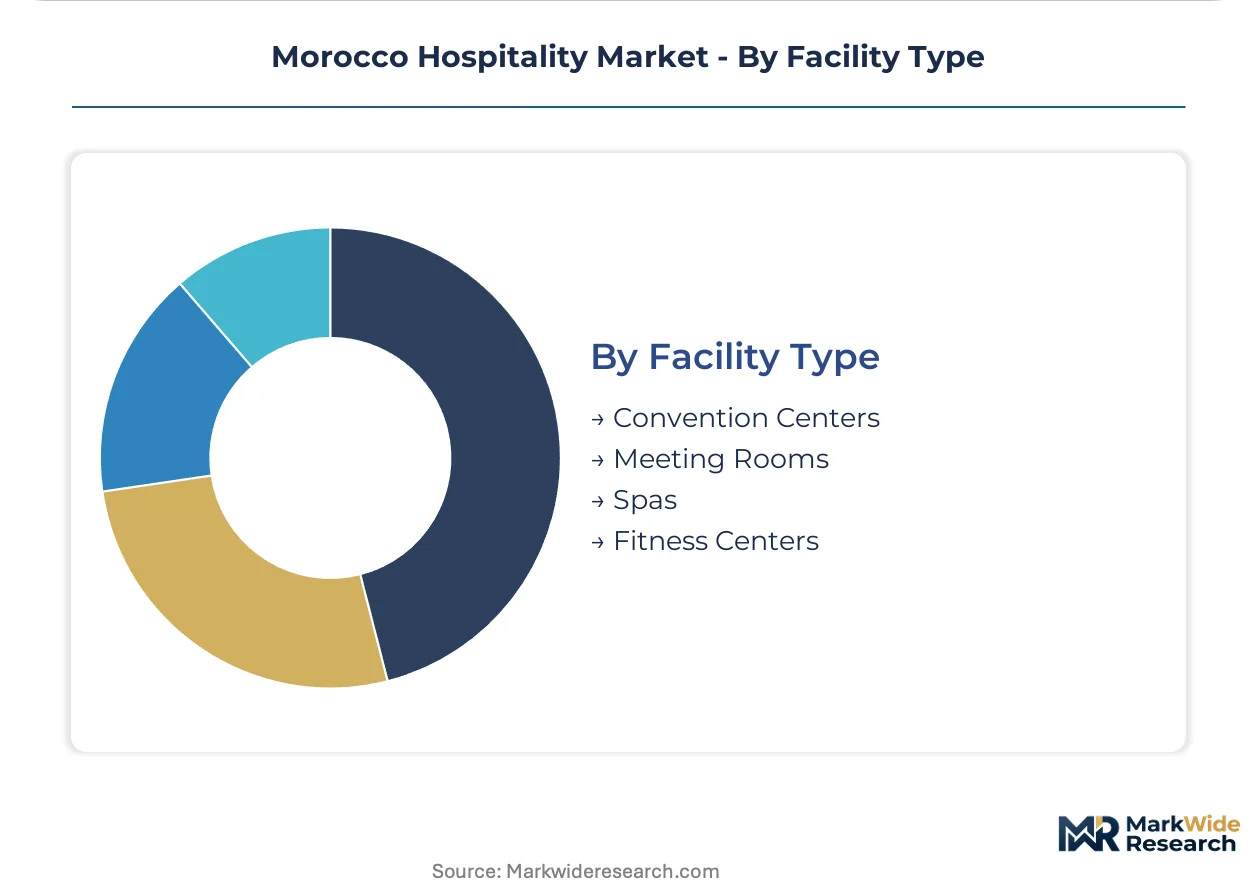
Facility Type:
Ancillary revenue centers vary in capital intensity and operational complexity, with some requiring specialized certification for access to state-backed financing.
- Spas:Wellness facilities within integrated resorts capture expanding margin pools through traditional hammam rituals combined with clinical protocols. Green Key or EarthCheck certification unlocks preferential state-backed financing instruments.
- Convention Centers:Large-format meeting infrastructure anchors corporate demand in Casablanca's financial district.
- Meeting Rooms:Smaller-scale corporate facilities support business-travel demand in urban hospitality assets.
- Fitness Centers:Standard amenity offerings increasingly mandated under revised classification criteria for four-star and above designation.
Spas deliver the steepest margin expansion; Convention Centers concentrate demand in gateway corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled artisans in traditional plasterwork and zellige tile installation anchor Morocco's hospitality construction pipeline, with apprenticeship bottlenecks compressing fit-out timelines for heritage-anchored properties across multiple development corridors.
Marrakech-Safi
International leisure travelers from French and German source markets drive concentrated demand in the Red City corridor. Morocco's Ministry of Tourism classification standards mandate accessibility upgrades and fire safety protocols that exceed prior voluntary benchmarks. The Palmeraie zone attracts extended-stay wellness segments through hammam-integrated luxury suites.
Casablanca-Settat
Corporate meeting and incentive buyers from Spanish and German business groups consolidate around premium properties near Mohammed V International Airport. State-backed financing instruments flow toward certified sustainable developments under the national tourism strategy. The financial district anchors convention-oriented demand with compressed retrofit timelines for four-star compliance.
Souss-Massa
Atlantic coastal resorts face seasonal demand clustering into March-May and September-November windows. Water extraction limits under national drought response protocols constrain golf-course-anchored expansion concepts near Agadir. The corridor attracts large-format integrated resort investments with extended development timelines.
Fez-Meknes
Domestic corporate demand supports secondary city activation where international visitation remains underdeveloped relative to gateway corridors. The national tourism strategy channels infrastructure funding toward underdeveloped destinations with first-mover positioning potential. The medina restoration pipeline creates boutique inventory targeting cultural immersion segments.
Tanger-Tetouan-Al Hoceima
Port infrastructure upgrades and Mediterranean access improvements redirect cruise and ferry-linked leisure demand. Morocco's Ministry of Tourism licensing protocols shape property investment thresholds for coastal developments. The region offers expansion terrain for midscale properties serving Spanish source markets with shorter access times.
Morocco Hospitality Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Morocco's hospitality landscape. Multi-brand portfolios dominate gateway city positioning while independent riad operators fragment the boutique segment. Three archetypes prevail: global brand licensors anchoring luxury and upscale tiers, regional specialists controlling midscale urban inventory, and heritage-focused independents capturing cultural immersion premiums. Competitive moves concentrate on portfolio diversification through brand tiering and strategic partnerships with state-backed development finance.
Within the global brand licensor tier, Accor and Marriott International exemplify multi-brand scale strategies, while Kenzi Hotels Group represents regional specialist positioning in convention-oriented urban hubs. These anchors demonstrate how brand architecture and geographic focus shape competitive positioning without requiring identical operational models.
| Leading Market Players |
|---|
| Accor |
| Marriott International |
| Hilton Worldwide |
| Radisson Hotel Group |
| Four Seasons Hotels & Resorts |
| Hyatt Hotels Corp. |
| Iberostar Hotels & Resorts |
| Atlas Hospitality Morocco |
| Kenzi Hotels Group |
| Others |
Pricing and Supply Chain Analysis
Green Key and EarthCheck certification gates access to both qualified construction supply and premium-tier pricing corridors in Moroccan hospitality. Properties lacking these credentials face compressed rate ceilings and exclusion from state-backed financing instruments that subsidize sustainable development.
Pricing Analysis
Bundled wellness-F&B packages dominate luxury resort pricing while unbundled room-only rates prevail in urban business segments. Three-tier pricing structure across premium, standard, and economy levels separates palace-grade riads from midscale airport properties and budget medina conversions. Pricing pressure stems from European source market sensitivity to exchange rate volatility, compressing margin projections for Atlantic coast operators. Corporate meeting buyers show lowest price sensitivity, while independent leisure travelers from Spain and France drive hardest bargain hunting.
Supply Chain Analysis
Morocco's domestic-content mandates for heritage restoration reshape sourcing toward local zellige ateliers and tadelakt plasterwork cooperatives. Imported steel and specialized glazing draw from Spain, Italy, and Turkey, while climate-control equipment feeds from French and German OEMs. Single-source vulnerability concentrates in artisan apprenticeship pipelines where multi-year training cycles create fit-out bottlenecks. Distribution runs through Casablanca-based logistics hubs serving Atlantic coastal corridors with consolidated material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's hospitality sector operates as a regulatory compounder where Ministry of Tourism classification upgrades mandate accessibility and fire safety investments that drive property-level capital deployment.
For Market Incumbents: Deploy multi-brand portfolio architecture to capture both luxury and midscale demand across Marrakech and Casablanca gateway corridors. Accor and Marriott International exemplify this lever through brand tiering that defends share against emerging regional specialists. Certification investment in Green Key or EarthCheck credentials protects access to state-backed financing instruments that emerging competitors cannot replicate. For New Entrants and Emerging Players: The price-point gap between premium riad conversions and economy hostel formats offers white-space targeting in Fez and Tangier secondary corridors. First-mover positioning in convention-oriented urban assets serving domestic corporate demand avoids direct confrontation with entrenched Atlantic coast resort competition. Co-working infrastructure integration captures digital nomad visa holders seeking extended-stay configurations. For Investors and Strategic Acquirers: Roll-up economics work for independent riad operators under fifty keys because fragmented booking systems and channel manager debt create distressed acquisition targets. Boutique heritage properties in Marrakech's medina offer platform consolidation potential with direct booking channel upside. Watch Ministry of Tourism enforcement timelines for four-star compliance retrofits as inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Riad Conversion | Restored properties in Marrakech's medina command rate premiums through authentic cultural immersion positioning. |
| Eco-Certification Investment | Green Key credentials unlock preferential state financing and distribution access under national tourism strategy protocols. |
| Wellness Service Integration | Hammam-anchored spa protocols in Palmeraie zone attract extended-stay German and Benelux market segments. |
| Secondary City Expansion | Fez and Tangier convention assets capture underdeveloped domestic corporate demand with lower competitive intensity. |
| Direct Booking Channel Build | Property-level content marketing reduces OTA dependency for independent operators targeting repeat French visitation. |
Research Methodology
Bottom-up property-level modeling reconciled against top-down airport capacity and tourism arrival tracking forms the analytical core. Primary interviews with hotel development executives, Ministry of Tourism licensing officers, heritage restoration contractors, and European tour operator procurement teams combined with secondary validation from customs trade data, national tourism strategy filings, and hospitality investment databases. Supply-side construction input tracking and demand-side occupancy rate analysis triangulate volume estimates.
Historical trendline analysis across property classification tiers, regional development corridors, and source market visitation patterns shaped projection logic. Segmentation dimensions modeled include service type, client archetype, room tier, and facility category across the analysis window. CAGRs derive from fitted trend extrapolation adjusted for infrastructure completion timelines and regulatory milestone phasing. Water extraction limits and artisan supply constraints feed as hard ceilings into resort development forecasts.
Caveats apply where drought response protocol tightening or European supply chain disruption could materially shift the outlook. Forecasts reflect assumptions about airport expansion completion and certification mandate enforcement pace. A small set of named triggers—classification standard revision timing, state financing instrument availability, and apprenticeship pipeline recovery—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
North America Luxury Hotel Market
Hotels and Resorts
Hotel Armchair Market
Hotels and Resorts
United Kingdom HRI Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Hotel Furniture and Furnishing Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Morocco Tourism and Hotel Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Morocco Tourism Market
Hotels and Resorts
Global Floating Hotels Market