
 North America Luxury Hotel Market | 2026-2036
North America Luxury Hotel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Hotel Market Analytics
Subscription-based loyalty and experience memberships is expanding as a distinct revenue layer beyond nightly rates. Marriott International leverages its Bonvoy ecosystem to capture recurring spend across dining, spa, and event verticals. Hyatt Hotels Corporation anchors its portfolio in destination wellness programming. Four Seasons Hotels & Resorts differentiates through residential club models that blend ownership with hotel services.
Luxury hotels in North America comprise high-service lodging assets with staffing ratios exceeding two employees per guest room, premium finishes, and curated food-and-beverage operations designed for affluent transient and group clientele. Properties typically operate at average daily rates above metropolitan market indexes by a factor of three or more. Full-Service properties command the largest share of invested capital and operating margin pools across the segment structure. Boutique inventory captures the fastest expansion in new supply, particularly in secondary urban markets. Extended-Stay luxury product remains underdeveloped relative to leisure and business transient formats.
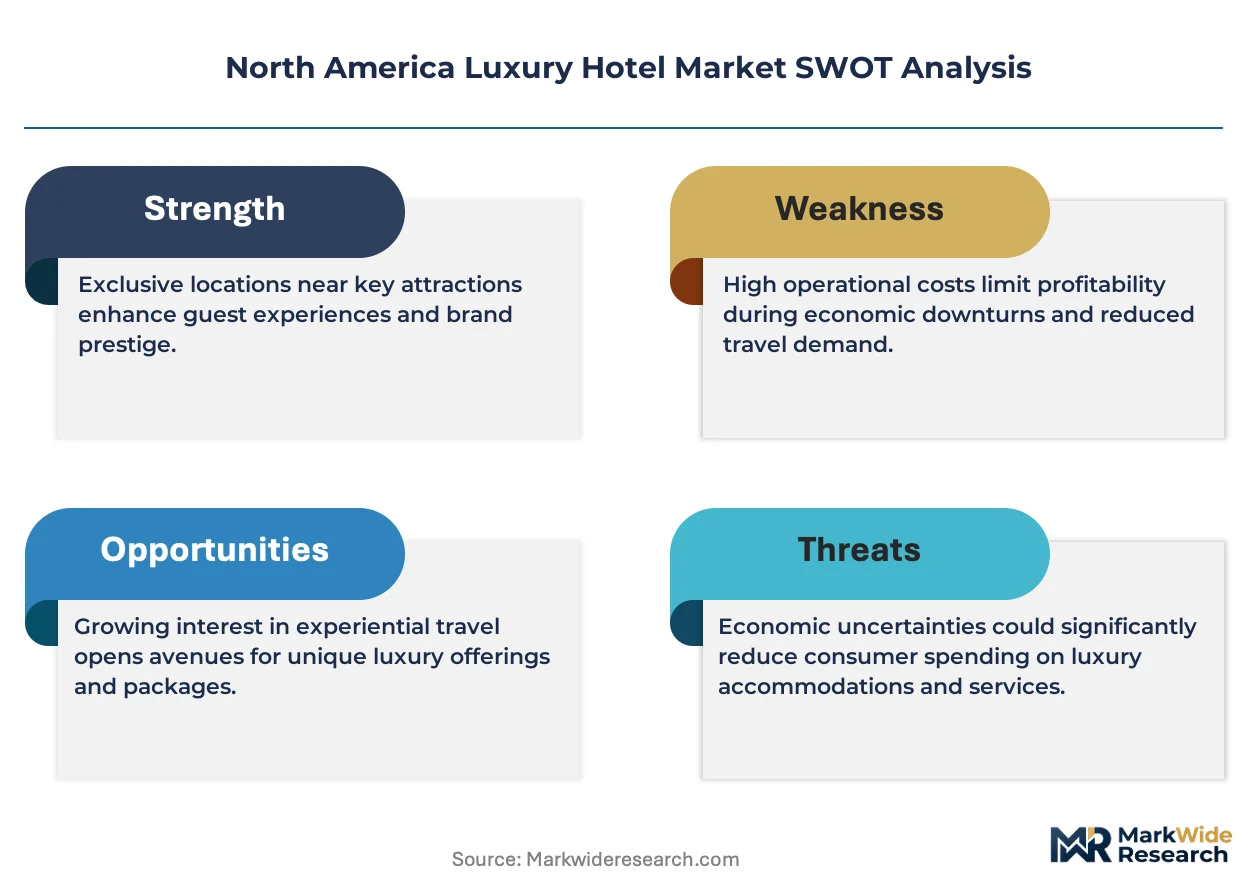
The U.S. Department of Labor's OSHA standards govern hospitality worker safety protocols, while the EPA regulates chemical handling in housekeeping and food service operations. Canadian provincial regulators enforce building energy codes that increasingly mandate electrification retrofits for existing assets. Stakeholders must monitor how municipal short-term rental ordinances in Los Angeles, Miami, and Toronto reshape competitive supply dynamics in urban core submarkets.
Market Dynamics
Leisure travelers now dominate booking flows across North America, forcing luxury properties to reconfigure revenue management systems around experience duration rather than traditional business-transient patterns. This demand rotation compresses shoulder-season pricing power and elevates service-staffing costs.
Growth Catalysts
- U.S. Inflation Reduction Act:Clean energy retrofits unlock federal tax credits that improve net operating income for properties pursuing electrification.
- Coastal California demand clusters:Affluent leisure concentration in Los Angeles and San Francisco metros sustains rate premiums above national indexes.
- Residential club models:Hybrid ownership structures generate recurring fee streams independent of transient occupancy volatility.
Market Restraints
- Labor cost escalation:Unionized housekeeping and culinary wages in New York and Toronto compress operating margins below asset-level debt service coverage thresholds.
- Short-term rental ordinance proliferation:Municipal caps on Airbnb supply in Miami and Los Angeles limit competitive pressure relief during demand troughs.
- Electrification capex burdens:Canadian provincial building codes mandate heat-pump conversions that strain renovation budgets for pre-2000 assets.
Strategic Opportunities
- Secondary urban boutique expansion:Austin, Nashville, and Denver present undersupplied luxury inventory relative to inbound high-net-worth migration.
- Extended-stay format development:Remote-work leisure patterns create unmet demand for multi-week residential-style product with full-service amenities.
- OSHA-aligned wellness programming:Properties integrating certified safety protocols into spa and fitness operations differentiate for liability-conscious group buyers.
Industry Challenges
- Executive chef talent scarcity:Culinary school pipeline contraction limits sourcing for Michelin-tracked food-and-beverage operations.
- Legacy property management system integration:Cloud-native guest experience platforms require costly middleware to connect with on-premise accounting and inventory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Hotel Market |
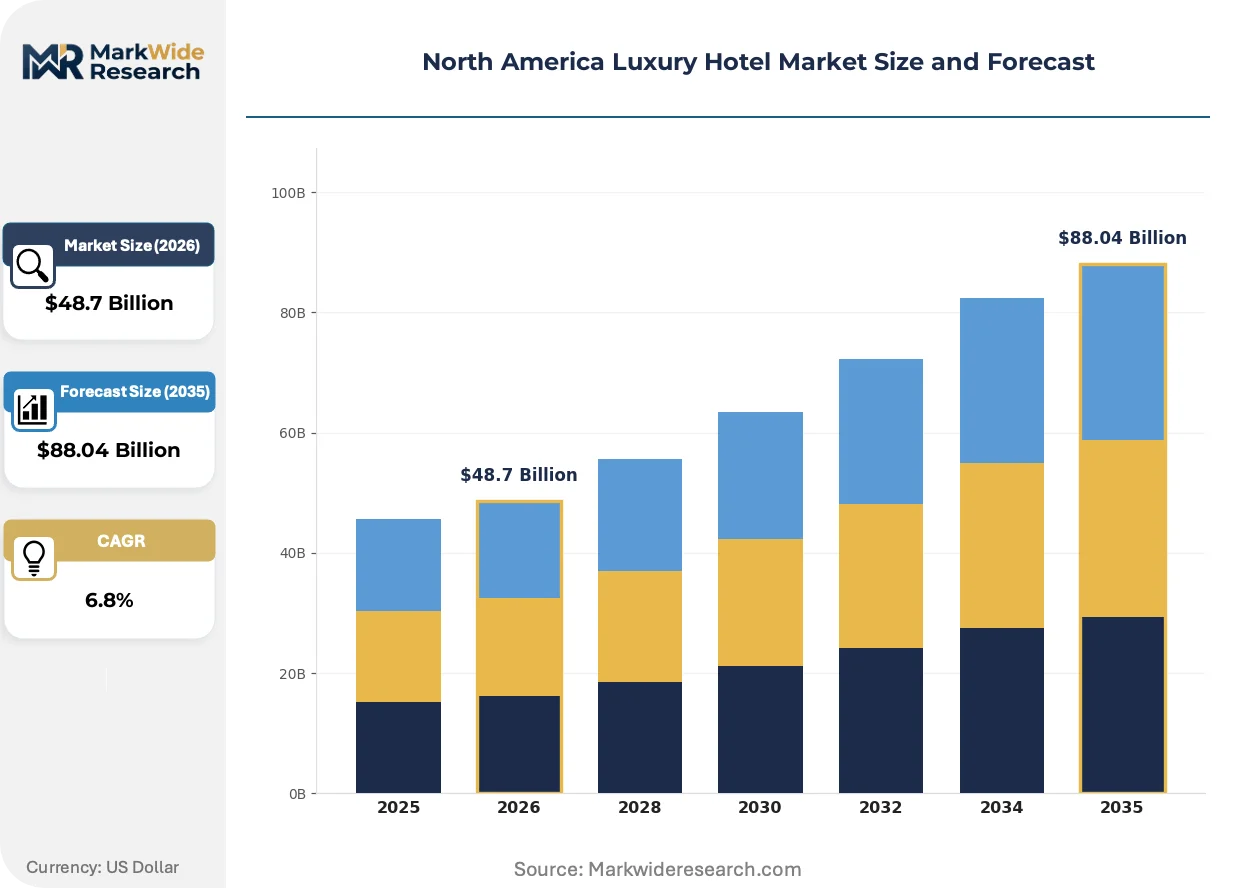
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service, Select-Service, Boutique, Extended-Stay Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Corporate Clients Price Tier: Luxury, Premium, Mid-Scale, Budget Distribution Channel: Online Travel Agencies, Direct Booking, Travel Agents, Global Distribution Systems |
| Companies Covered | Four Seasons Hotels & Resorts, IHG Hotels & Resorts, Marriott International, Fairmont Hotels & Resorts, Wyndham Hotels & Resorts, Hilton Worldwide, Accor SA, Mandarin Oriental Hotel Group, Hyatt Hotels Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Hotel Market Evolving Landscape
Technology deployment across North American luxury hotels now prioritizes labor substitution and personalization at scale. Properties balance automation investments against the service-density expectations that define the segment.
Guest-facing artificial intelligence is consolidating operational workflows across revenue management, concierge routing, and predictive maintenance scheduling. Mid-scale luxury portfolios in South Florida and coastal California deploy these tools fastest. The technology is consolidating front-desk and back-of-house staffing models into unified guest-experience pods.
Canadian provincial regulators enforce escalating electrification mandates through building energy codes that phase out natural gas heating. Properties in Toronto and Vancouver face 2030 compliance deadlines for heat-pump retrofits. Full-service assets with centralized plant infrastructure encounter the steepest capital reconfiguration costs.
Leisure buyers now book extended-duration stays through direct channels, bypassing traditional corporate travel management intermediaries. Destination wellness programming and residential club memberships capture this shift. South Florida markets exhibit the most pronounced channel migration, with direct booking shares expanding fastest among independent boutique operators.
North America Luxury Hotel Market Segmentation
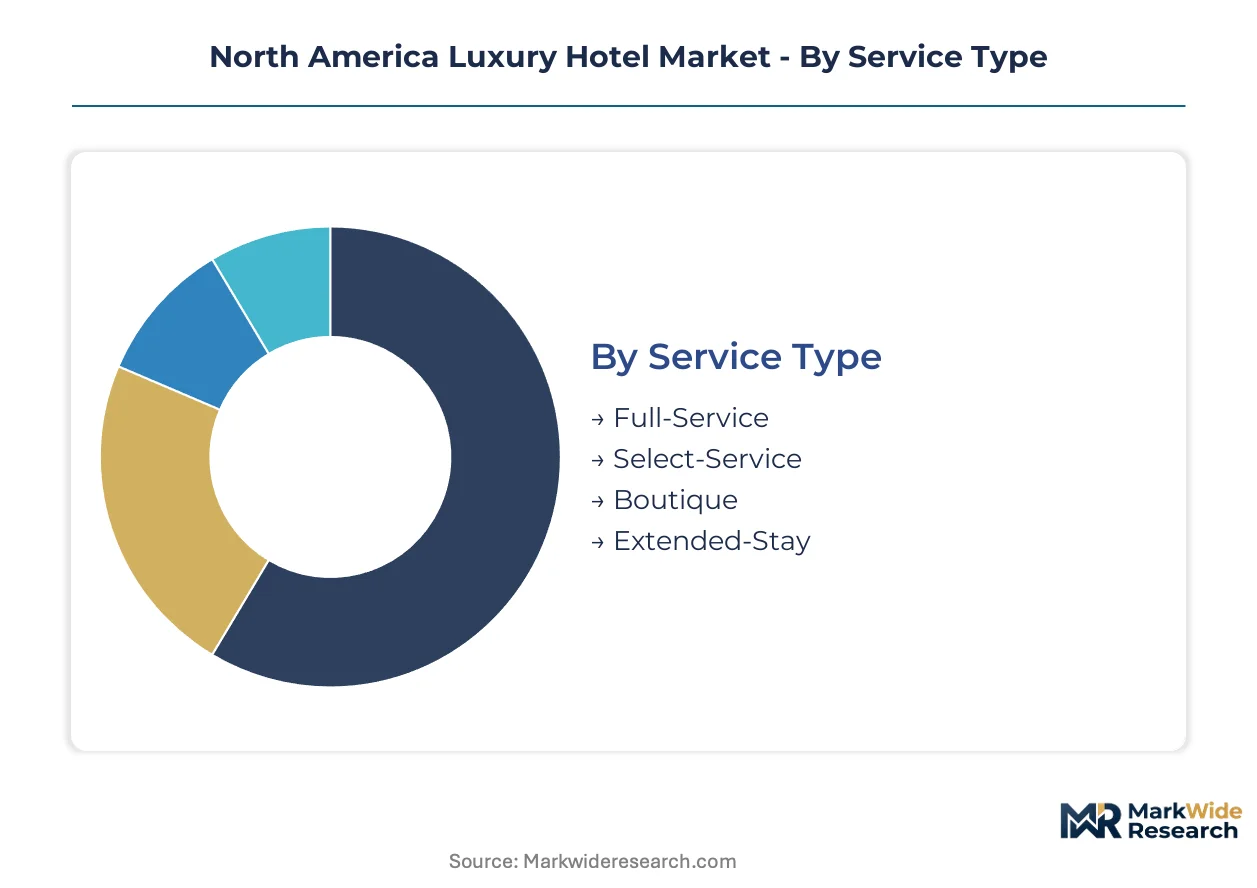
Luxury hotel operators configure asset portfolios around distinct service-density thresholds and guest-stay patterns. Segmentation discipline determines capital allocation between urban transient properties and resort-style developments. Revenue management systems calibrate pricing architecture differently across each category boundary.
Service Type:
Buyer selection hinges on the ratio of staffed amenities to guest room count and the intended duration of stay.
- Full-Service:Properties maintain comprehensive food-and-beverage operations, spa facilities, and dedicated concierge staffing above two employees per room. Coastal California and South Florida concentrate demand for this format where affluent leisure travelers sustain extended on-property spending.
- Boutique:Smaller-room-count assets emphasize design-forward interiors and localized programming over standardized brand protocols. Austin, Nashville, and Denver show the steepest supply expansion as secondary urban markets attract high-net-worth migration.
- Select-Service:Curated amenity sets reduce operating overhead while preserving premium positioning in airport and highway-adjacent submarkets.
- Extended-Stay:Multi-week residential-style product with full-service amenities remains underdeveloped relative to leisure and business transient formats.
Volume sits with Full-Service; growth tilts toward Boutique.
Customer Type:
Booking pattern density shapes staffing models and channel investment priorities across the forecast window.
- Leisure Travelers:Individual and family bookings now dominate reservation flows, forcing revenue systems to optimize around experience duration rather than traditional corporate patterns. Shoulder-season pricing power compresses as this segment concentrates demand in peak windows.
- Business Travelers:Transient corporate demand concentrates in metropolitan corridors with proximity to financial and technology employment centers. The New York metropolitan corridor sustains midweek occupancy premiums despite hybrid work normalization.
- Group Travelers:Wedding, celebration, and association meeting blocks require configurable event space and catering scale.
- Corporate Clients:Negotiated rate agreements with multinational employers generate base-load occupancy in gateway cities.
Revenue concentration rests with Leisure Travelers; margin expansion favors Group Travelers.
Price Tier:
Rate positioning relative to metropolitan market indexes determines asset-class financing terms and buyer expectations.
- Luxury:Average daily rates exceed market indexes by factors of three or more, supported by staffing ratios and finish specifications that justify premium positioning. Institutional capital allocates disproportionately to this tier for yield stability.
- Premium:Elevated service standards with selective amenity reduction capture price-sensitive affluent travelers in secondary markets.
- Mid-Scale:Limited-service configurations with design-forward public spaces compete on value perception in oversupplied urban submarkets.
- Budget:Minimal amenity sets with automated service delivery occupy peripheral locations with transportation access.
Capital deployment concentrates in Luxury; supply response is climbing the fastest in Premium.
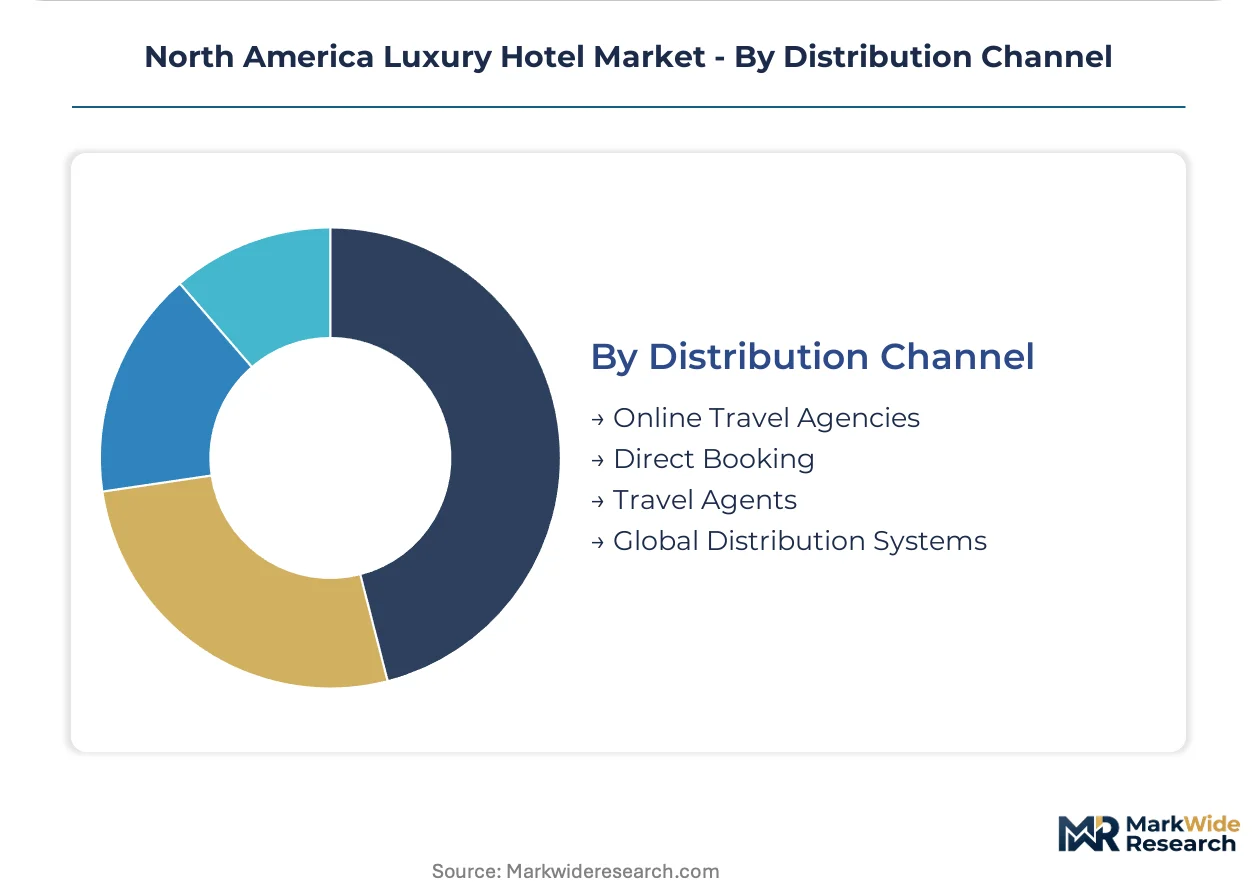
Distribution Channel:
Commission structures and guest data ownership rights drive channel-mix strategy for revenue optimization.
- Direct Booking:Proprietary websites and mobile applications capture guest data for loyalty program enrollment and ancillary spend targeting. South Florida independents show the most pronounced channel migration as leisure buyers bypass intermediaries.
- Online Travel Agencies:Aggregator platforms deliver volume with commission burdens that compress net revenue per available room.
- Travel Agents:High-touch intermediaries retain relevance for complex multi-destination itineraries and ultra-high-net-worth household placement.
- Global Distribution Systems:Sabre, Amadeus, and Travelport connections sustain corporate travel management company flows.
Share accumulates with Direct Booking; technology investment prioritizes Online Travel Agency rate parity tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the bulk of luxury hotel consumption across North America, while Canada and Mexico concentrate development activity in gateway urban centers. Capital deployment tracks affluent leisure migration patterns toward coastal and mountain destinations.
United States
Coastal California and South Florida absorb the highest concentration of new luxury supply as affluent leisure buyers prioritize destination wellness experiences. OSHA governs hospitality worker safety protocols nationwide, while the EPA regulates chemical handling in housekeeping operations. The New York metropolitan corridor sustains midweek occupancy premiums despite hybrid work normalization, with institutional capital favoring full-service assets for yield stability.
Canada
Toronto and Vancouver face accelerating demand for boutique inventory as high-net-worth migration flows into secondary urban markets. Provincial regulators enforce building energy codes mandating electrification retrofits for existing assets, with 2030 compliance deadlines for heat-pump conversions. Montreal's full-service properties encounter steeper capital reconfiguration costs due to centralized plant infrastructure dating from pre-2000 construction.
Mexico
Cancun and Los Cabos anchor leisure-driven development along the Caribbean and Pacific coasts, with residential club models generating recurring fee streams. Mexico's federal environmental regulator SEMARNAT oversees coastal construction permits and wastewater discharge standards for beachfront properties. Mexico City concentrates business transient demand in the Polanco and Santa Fe districts, where corporate rate negotiations sustain base-load occupancy.
North America Luxury Hotel Market Competitive Landscape
Top-tier vendors anchor the global brand tier, while independent boutique operators and regional specialists occupy the mid-market. The North America luxury hotel market exhibits consolidated structure at the upper echelon, with a handful of multinational hospitality groups controlling premium positioning and loyalty ecosystems. Three strategic archetypes dominate: asset-light brand licensors, vertically integrated owner-operators, and residential club hybridizers. Competitive moves center on portfolio diversification into wellness programming and strategic partnerships with residential real estate developers.
Within the asset-light licensor tier, Marriott International and Hilton Worldwide exemplify scale-driven brand architecture, while Four Seasons Hotels & Resorts occupies a position in the ultra-premium owner-operator segment. Hyatt Hotels Corporation represents the wellness-anchored diversification archetype. These three entities collectively illustrate how competitive positioning stratifies across loyalty ecosystem depth, service-density ratios, and residential hybridization capabilities.
| Leading Market Players |
|---|
| Four Seasons Hotels & Resorts |
| IHG Hotels & Resorts |
| Marriott International |
| Fairmont Hotels & Resorts |
| Wyndham Hotels & Resorts |
| Hilton Worldwide |
| Accor SA |
| Mandarin Oriental Hotel Group |
| Hyatt Hotels Corporation |
| Others |
Value Network & Pricing Analysis
Labor cost indices in the hospitality sector cascade through North American luxury hotel operations, compressing margins at full-service properties while amplifying rate premiums at boutique assets with leaner staffing models. This input-cost pressure stratifies pricing power across service-density tiers.
Pricing Analysis
Margin tightening in full-service tiers reflects unionized wage escalation in New York and Toronto. Three-tier pricing structure across luxury, premium, and mid-scale levels separates properties by staffing ratios and finish specifications. Price differentiation hinges on service-density ratios and destination wellness programming. Corporate buyers exhibit highest price sensitivity; leisure travelers booking extended stays through direct channels show lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for culinary talent and housekeeping labor force luxury operators to qualify multiple staffing agencies across Mexico, the Philippines, and Central American corridors. Food-and-beverage operations draw from California produce hubs, Pacific seafood corridors, and imported specialty ingredients. Single-source vulnerability concentrates in executive chef talent pipelines. Distribution runs through consolidated procurement platforms serving brand portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American luxury hotel supply remains constrained by construction cost escalation and municipal entitlement timelines, propping rate premiums for existing assets. This capacity bottleneck sustains pricing power for well-positioned operators.
For Market Incumbents: Anchor portfolio resilience through electrification retrofit timing aligned with IRA tax credit windows. Consolidate loyalty ecosystem depth against independent boutique encroachment. Prioritize backward integration into residential club fee streams to buffer transient occupancy volatility.
For New Entrants and Emerging Players: Direct-booking platform investment opens underserved secondary urban corridors. Target Austin, Nashville, and Denver where high-net-worth migration outpaces luxury inventory growth. Pursue extended-stay format development capturing remote-work leisure demand with residential-style amenities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor pre-2000 full-service assets in Canadian gateway cities facing 2030 electrification compliance deadlines. Long-term viability centers on properties with convertible event space and wellness programming infrastructure. Monitor municipal short-term rental ordinance enforcement as demand-trough inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Program | IRA tax credits improve net operating income for properties pursuing heat-pump conversions. |
| Residential Club Expansion | Hybrid ownership structures generate recurring fee streams independent of transient occupancy. |
| Direct Booking Platform Investment | South Florida independents capture guest data for loyalty enrollment and ancillary targeting. |
| Secondary Urban Boutique Development | Austin and Denver present undersupplied inventory relative to inbound high-net-worth migration. |
| Wellness Programming Certification | OSHA-aligned safety protocols differentiate properties for liability-conscious group buyers. |
Research Methodology
Independent corroboration across property-level operating statements, municipal entitlement databases, and labor union contract filings underwrites the qualitative findings. Primary interviews with hotel asset managers, revenue management directors, culinary operations leads, and hospitality procurement specialists combined with secondary validation from STR performance data, Smith Travel Research supply pipelines, and EPA regulatory filings. Bottom-up property-level modeling and top-down regional demand aggregation triangulate volume estimates.
Comparable-period anchoring to pre-pandemic demand baselines and post-recovery booking patterns structured the forecast window. Segmentation dimensions modeled include service type, customer type, price tier, and distribution channel across the projection horizon. CAGRs derived from booking-flow velocity indicators and capital deployment tracking. Forecast inputs incorporate leisure migration pattern data and electrification compliance cost curves.
Inputs from property operating statements and municipal regulatory filings were available through the study window; gaps in forward-looking construction cost indices introduce uncertainty bands. Forecasts reflect documented assumptions regarding labor cost trajectory and short-term rental ordinance proliferation. Deviation in IRA tax credit extension timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hotels and Resorts
Global Floating Hotels Market
Hotels and Resorts
Europe Luxury Hotel Market
Hotels and Resorts
United States Luxury Hotel Market
Hotels and Resorts
Spa Resorts Market
Hotels and Resorts
Cuba Tourism and Hotel Market
Hotels and Resorts
Hotels, Resorts, and Cruise Lines Market
Hotels and Resorts
Asia-Pacific Luxury Hotel Market
Hotels and Resorts
Mountain and Ski Resorts Market
Hotels and Resorts
Five Star Hotel Market
Hotels and Resorts
Global Beach Hotels Market
Hotels and Resorts
Germany HRI Market
Hotels and Resorts
India Luxury Hotel Market
Hotels and Resorts
Boutique Hotels Market
Hotels and Resorts
Philippines Tourism and Hotel Market
Hotels and Resorts
Spain HRI Market
Hotels and Resorts
Morocco Hospitality Market